
 Europe Laser Interferometer Market | 2026-2036
Europe Laser Interferometer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Laser Interferometer Market Insights
The gap between premium calibration-grade interferometers and commodity displacement sensors is expanding as semiconductor fabs demand sub-nanometer repeatability. Renishaw plc leverages its encoder heritage to dominate multi-axis machine tool verification. ZEISS Group anchors high-end optical metrology through captive lens manufacturing. SIOS Meßtechnik GmbH specializes in vacuum-compatible designs for EUV lithography subsystem suppliers.
A laser interferometer measures displacement, surface topography, or refractive index changes by detecting phase shifts between a reference beam and a measurement beam, typically achieving resolution below one nanometer using stabilized helium-neon or frequency-doubled solid-state sources. Its primary purpose is providing traceable dimensional control for precision manufacturing, lithography, and gravitational wave detection. Fiber laser systems lead in telecommunications testbeds across France and Italy due to coherence length advantages, while solid-state architectures capture margin pools in semiconductor wafer inspection where thermal stability commands premium pricing. Gas laser variants retain entrenched positions in national metrology institutes despite slower unit growth.
CE marking under the EU Machinery Directive and REACH substance restrictions on optical coatings shape product design cycles and supplier qualification timelines. The EU Chips Act funding conditions are pushing fabs toward interferometers with documented EU supply chains. Germany's PTB calibration mandates and France's LNE traceability protocols create divergent compliance pathways. Stakeholders must decide whether to qualify dual-standard product lines or concentrate on the German-Dutch manufacturing cluster where capital deployment is most aggressive.
Market Dynamics
The EU Chips Act is compressing supplier qualification timelines while mandating documented EU supply chains for metrology equipment deployed in semiconductor fabrication facilities across Germany and the Netherlands.
Growth Catalysts
- EUV lithography subsystem demand:Vacuum-compatible interferometer architectures are capturing procurement contracts from lithography equipment suppliers serving fabs in the Netherlands and Germany. REACH-compliant optical coatings are becoming a mandatory specification in vendor selection.
- PTB calibration mandates:Germany's national metrology institute requires traceable dimensional control for precision manufacturing, forcing machine tool builders in Stuttgart and Munich to upgrade verification systems.
- Fiber laser coherence advantages:Telecommunications testbeds in France and Italy are specifying fiber-based architectures for long-path applications, displacing legacy gas laser installations in R&D environments.
Market Restraints
- Helium-neon gas laser supply concentration:Sourcing stabilized He-Ne tubes depends on a shrinking supplier base concentrated in Central Europe, creating single-source vulnerability for calibration-grade systems.
- REACH substance restrictions:ECHA restrictions on optical coating materials are extending product redesign cycles by 12-18 months and forcing qualification of alternative deposition processes.
- Displacement sensor substitution:Capacitive and optical encoder technologies are capturing price-sensitive applications below 10 nanometer resolution requirements in general manufacturing.
Strategic Opportunities
- Poland and Czech Republic precision engineering:Automotive and aerospace subcontractors in these markets are installing first-generation interferometer-based verification systems as OEM traceability requirements cascade downstream.
- Quantum sensing convergence:Integration of squeezed-light interferometry with classical laser systems is opening gravitational wave research contracts and next-generation geodesy applications.
- EU Chips Act funding access:Equipment vendors with documented EU supply chains qualify for accelerated payment terms and co-investment structures in publicly supported fab projects.
Industry Challenges
- Vacuum engineering talent scarcity:Designing EUV-compatible interferometers requires rare cross-training in optical metrology and ultrahigh-vacuum systems, constraining product development velocity.
- Dual-standard certification burden:Suppliers must simultaneously satisfy Germany's PTB protocols and France's LNE traceability requirements, fragmenting product lines and testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Laser Interferometer Market |
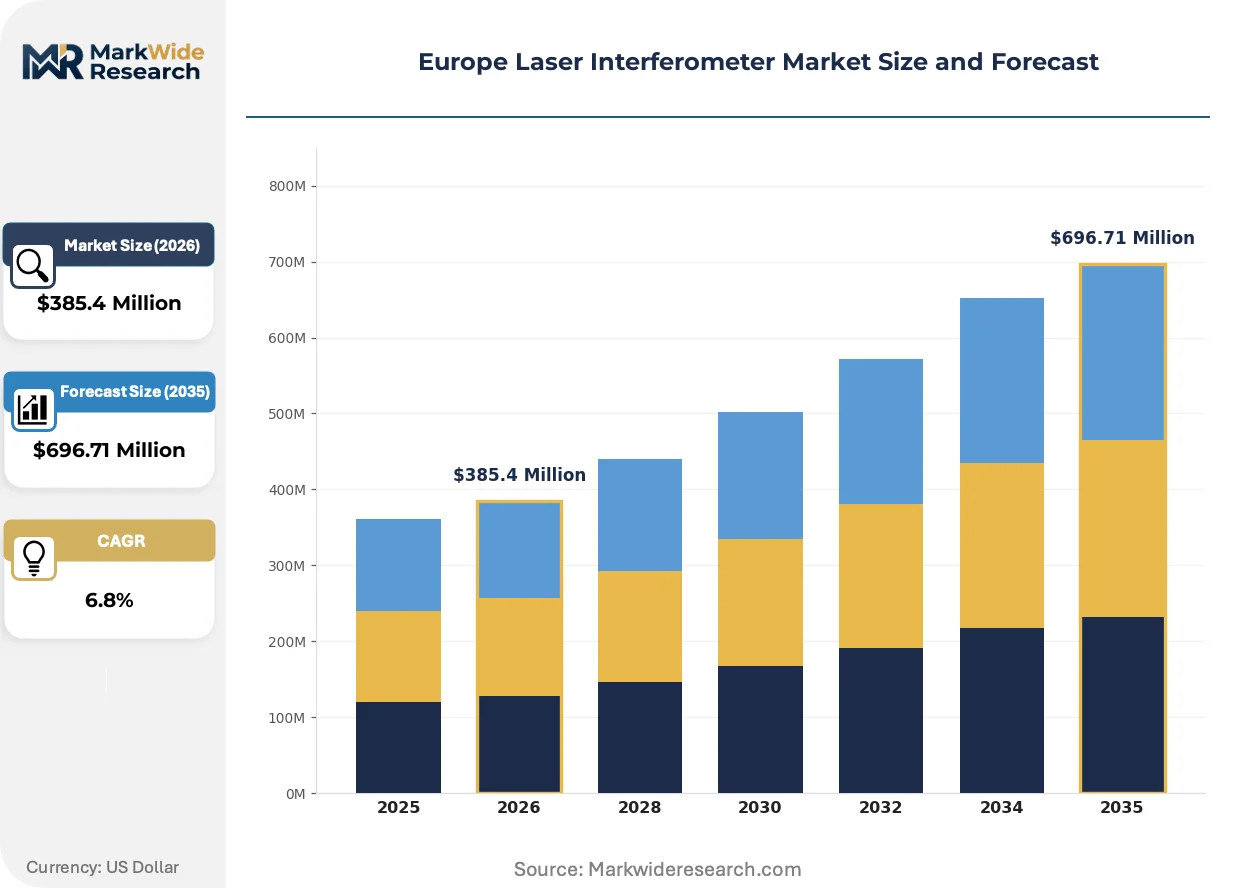
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Laser, Solid-State Laser, Gas Laser, Semiconductor Laser Application: Metrology, Communication, Material Processing, Aerospace End User: Manufacturing, Defense, Research Institutions, Automotive Technology: Optical Interferometry, Digital Signal Processing, Integrated Circuit, Super Resolution |
| Companies Covered | Renishaw plc, ZEISS Group, SmarAct GmbH, SIOS Meßtechnik GmbH, Trioptics GmbH, Mahr GmbH, Keysight Technologies, Adloptica Optical Systems GmbH, LAMTECH Lasermesstechnik GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Laser Interferometer Market Trends and Innovations
Interferometer architectures are fragmenting between modular, field-configurable systems for multi-axis machine tools and fixed-configuration instruments for lithography subsystems, with software-defined measurement paths displacing hardware-dedicated channels.
Multi-axis interferometer electronics is modularizing around standardized optical heads and swappable signal processing units. Semiconductor fabs in Dresden and Eindhoven are specifying this architecture to reduce spare parts inventory. The approach is compressing vendor margins on complete systems while expanding recurring revenue from firmware and calibration subscriptions.
CE marking under the EU Machinery Directive is tightening electromagnetic compatibility requirements for interferometer electronics deployed in industrial environments. Manufacturers are redesigning power supplies and shielding to satisfy updated harmonized standards. German machine tool builders are demanding pre-certified subassemblies to accelerate their own conformity assessment timelines.
Buying committees at precision engineering firms are unbundling hardware procurement from calibration service contracts, previously sold as integrated packages. Distributors in the DACH region are capturing service revenue through third-party metrology accreditations. This pattern is most visible among mid-tier automotive suppliers in Bavaria and Baden-Württemberg facing pressure to reduce total cost of ownership.
Europe Laser Interferometer Market Segmentation
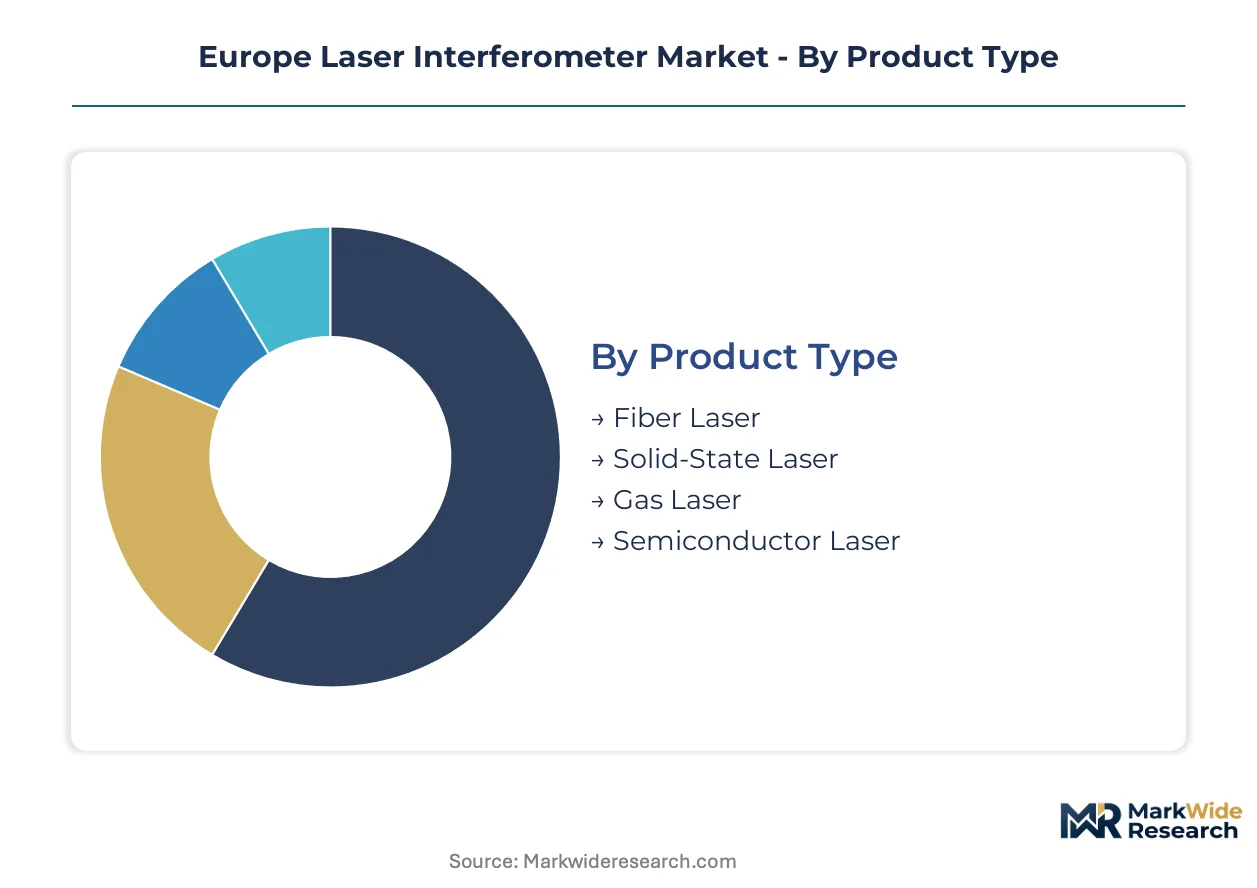
Segmentation in the Europe Laser Interferometer Market reveals how technical specifications, application environments, and procurement authority shape vendor positioning. Understanding these divides exposes where margin pools concentrate and where standardization pressures erode pricing power.
Product Type:
Technical architecture determines thermal stability, coherence length, and vacuum compatibility, creating divergent qualification pathways for semiconductor and metrology applications.
- Fiber Laser:Erbium-doped or ytterbium-doped fiber architectures deliver extended coherence lengths exceeding 100 meters. Telecommunications testbeds in France and Italy specify these systems for long-path R&D applications, displacing legacy gas laser installations where path length flexibility matters more than absolute stability.
- Solid-State Laser:Frequency-doubled Nd:YAG or diode-pumped solid-state sources achieve sub-nanometer thermal drift coefficients through monolithic resonator designs. Semiconductor wafer inspection systems in Dresden and Eindhoven demand this stability for multilayer metrology, commanding premium pricing against fiber alternatives.
- Gas Laser:Stabilized helium-neon tubes remain entrenched in national metrology institutes across Germany and France due to established traceability chains, though sourcing concentration in Central Europe creates supply vulnerability.
- Semiconductor Laser:Compact diode architectures serve portable alignment tools and embedded displacement sensors, capturing volume in automotive production lines where form factor overrides absolute precision requirements.
Solid-state systems lead on scale within semiconductor capital equipment procurement; fiber architectures lead on momentum in telecommunications infrastructure expansion.
Application:
End-use environment dictates environmental sealing, software integration depth, and calibration frequency, fragmenting vendor specialization across industrial and laboratory contexts.
- Metrology:Dimensional control applications in precision engineering corridors spanning Munich, Stuttgart, and Jena require interferometers with documented PTB traceability. Machine tool builders face compressed upgrade cycles as calibration mandates tighten.
- Communication:Fiber optic testbeds and free-space optical link validation drive demand for long-coherence sources. French and Italian research consortia specify modular architectures to accommodate evolving protocol standards.
- Material Processing:Laser welding and additive manufacturing feedback systems prioritize real-time displacement measurement over absolute accuracy, opening the segment to lower-cost heterodyne configurations.
- Aerospace:Vibration isolation and thermal vacuum qualification requirements limit qualified suppliers for satellite optical bench verification, concentrating procurement among vendors with heritage in space-qualified photonics.
Metrology commands the largest installed base; communication applications are climbing the fastest as telecom infrastructure investment accelerates.
End User:
Procurement authority and technical staff sophistication create distinct sales cycles, from integrated system sales to defense contracting protocols.
- Manufacturing:Precision component suppliers in Germany's automotive and aerospace supply chains deploy interferometers for incoming inspection and process verification. REACH-compliant coating documentation has become a mandatory vendor qualification step.
- Defense:National security procurement across France, Germany, and Italy imposes cybersecurity and supply chain provenance requirements that exclude non-EU component sources, favoring vendors with captive manufacturing within the region.
- Research Institutions:Gravitational wave detection and quantum sensing collaborations between PTB, LNE, and university consortia drive demand for custom vacuum-compatible configurations with extended development timelines.
- Automotive:OEM traceability requirements cascading to Tier-2 and Tier-3 suppliers in Poland and the Czech Republic are triggering first-generation interferometer installations among precision subcontractors.
Manufacturing represents the deepest volume concentration; automotive end users are gaining share fastest as traceability mandates propagate downstream.
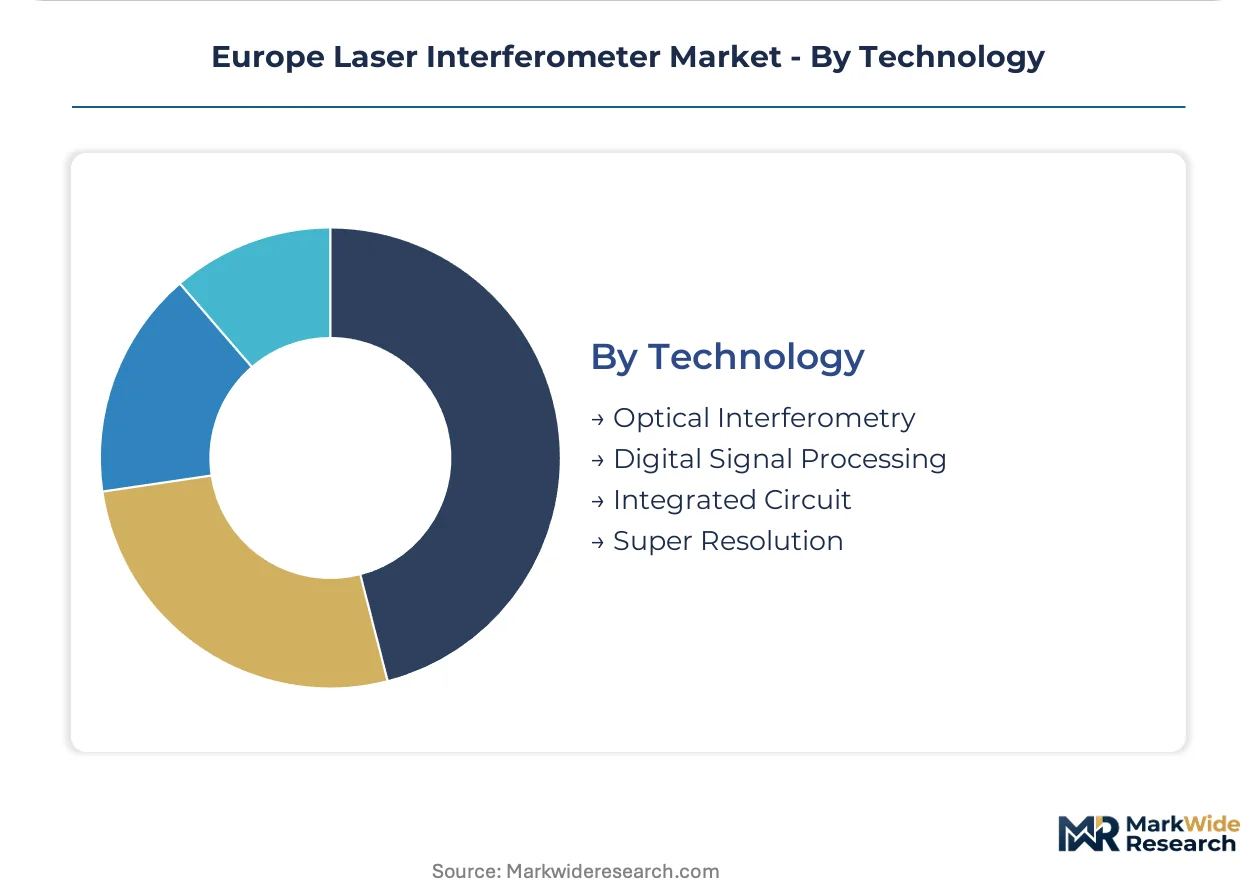
Technology:
Signal processing and integration depth determine system flexibility, with software-defined architectures displacing hardware-fixed configurations in multi-axis applications.
- Optical Interferometry:Classical homodyne and heterodyne architectures remain dominant in calibration-grade systems where phase measurement linearity is paramount. German machine tool verification protocols specify these configurations exclusively.
- Digital Signal Processing:FPGA-based real-time phase extraction enables modular electronics platforms with swappable optical heads. Semiconductor fabs in the Netherlands specify this architecture to compress spare parts inventory and enable remote firmware updates.
- Integrated Circuit:CMOS-integrated photodetector arrays are emerging in compact displacement sensors for embedded machine tool monitoring, though European foundry capacity constraints limit domestic sourcing.
- Super Resolution:Structured illumination and pupil-function engineering techniques extend lateral resolution below the diffraction limit for semiconductor mask inspection, capturing niche applications in EUV lithography development.
Digital signal processing leads on scale through semiconductor fab standardization; super resolution shows the steepest expansion trajectory in next-generation lithography research.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters anchor European interferometer demand through concentrated metrology talent in Stuttgart, Munich, and Jena. Dutch lithography equipment suppliers drive vacuum-compatible architecture procurement. French and Italian telecommunications research consortia specify fiber-based systems for long-path validation.
Germany
Stuttgart and Munich machine tool builders face compressed upgrade cycles under PTB calibration mandates requiring traceable dimensional control. REACH substance restrictions on optical coatings extend vendor qualification timelines by 12-18 months. The precision engineering corridor spanning Jena, Stuttgart, and Munich concentrates EUV lithography subsystem demand from ASML suppliers.
Netherlands
Eindhoven-area lithography equipment manufacturers specify vacuum-compatible interferometer architectures for EUV subsystem integration. EU Chips Act funding conditions mandate documented EU supply chains for metrology equipment deployed in semiconductor fabs. Dutch semiconductor capital expenditure is redirecting procurement toward interferometers with verified component provenance.
France
LNE traceability protocols create divergent compliance pathways from German PTB standards, fragmenting product certification requirements. Telecommunications testbeds in Paris and Grenoble specify fiber laser architectures for free-space optical link validation. French research consortia prioritize modular systems accommodating evolving protocol standards.
Italy
Turin and Milan precision automotive suppliers install first-generation interferometer-based verification systems under cascading OEM traceability requirements. CE marking under the EU Machinery Directive tightens electromagnetic compatibility specifications for industrial deployment. Italian telecommunications infrastructure expansion drives fiber laser demand for long-path R&D applications.
Poland
Warsaw and Krakow aerospace subcontractors deploy interferometer systems as defense procurement imposes cybersecurity and supply chain provenance requirements excluding non-EU component sources. Automotive Tier-2 suppliers face pressure to reduce total cost of ownership through unbundled hardware and calibration service contracts. Polish precision engineering is capturing EU Chips Act supply chain diversification mandates.
Europe Laser Interferometer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European interferometer market, with captive optical manufacturing determining thermal stability performance. The vendor base stratifies between integrated metrology conglomerates, precision motion specialists, and lithography subsystem suppliers. Three archetypes dominate: encoder-heritage verification system builders, captive lens manufacturers anchoring high-end optical metrology, and vacuum-engineering specialists serving EUV lithography. Competitive positioning depends on backward integration into stabilized laser sources and qualification speed under EU Chips Act procurement timelines.
Within the encoder-heritage tier, Renishaw plc occupies a position exemplifying multi-axis machine tool verification dominance. Among German precision specialists, SIOS Meßtechnik GmbH and SmarAct GmbH represent vacuum-compatible and micro-positioning archetypes respectively. ZEISS Group anchors the captive-manufacturing vector through integrated optical component production. These three entities collectively illustrate how heritage in adjacent metrology domains translates into interferometer market positioning without requiring identical technical architectures.
| Leading Market Players |
|---|
| Renishaw plc |
| ZEISS Group |
| SmarAct GmbH |
| SIOS Meßtechnik GmbH |
| Trioptics GmbH |
| Mahr GmbH |
| Keysight Technologies |
| Adloptica Optical Systems GmbH |
| LAMTECH Lasermesstechnik GmbH |
| Others |
Pricing and Supply Chain Analysis
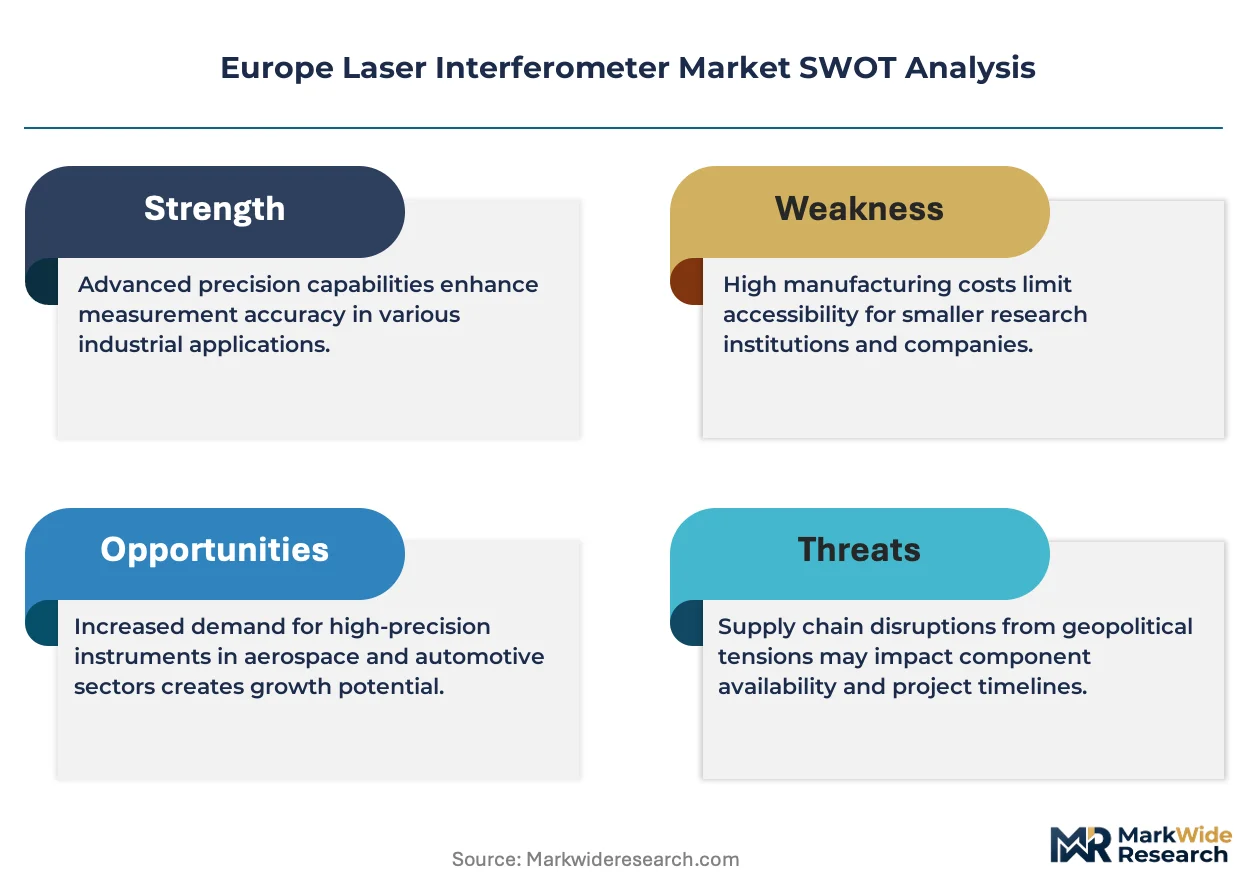
EU Chips Act procurement mandates for documented supply chains are forcing buyers to absorb qualification premiums on interferometers with verified component provenance, compressing margin pools for vendors unable to demonstrate backward integration into stabilized laser sources or captive optical manufacturing.
Pricing Analysis
The bundled-versus-unbundled service split is fragmenting procurement patterns across Europe's precision engineering sector. Three-tier pricing structure across premium, standard, and economy levels separates calibration-grade systems with PTB traceability from modular configurations for semiconductor fabs and displacement sensors for general manufacturing. Price differentiation hinges on certification tier and after-sales service bundling, with German machine tool builders demanding pre-certified subassemblies to accelerate conformity timelines. Cost compression in the standard tier is intensifying because distributors in the DACH region are capturing service revenue through third-party metrology accreditations. Automotive Tier-2 suppliers in Poland and the Czech Republic exhibit the highest price sensitivity, while lithography equipment manufacturers in the Netherlands show minimal elasticity for vacuum-compatible architectures.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and recalibration of interferometer subassemblies are concentrating service revenue among distributors with metrology accreditations in Germany and the Netherlands. Geographic supply concentration centers on Germany for precision optical components, the Netherlands for lithography subsystem integration, and Central Europe for stabilized helium-neon laser tubes. Raw material dependencies draw from specialized optical glass, rare-earth doped fibers, and REACH-compliant coating precursors. Single-source vulnerability for He-Ne tube supply creates structural risk for calibration-grade system manufacturers. Distribution runs through direct OEM relationships for lithography applications and specialized metrology distributors for precision engineering customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe laser interferometer market represents a late-cycle quality story as semiconductor fabs and precision engineering firms prioritize sub-nanometer repeatability over cost minimization, redirecting procurement toward vendors with documented traceability chains and captive manufacturing capabilities.
For Market Incumbents: To counter displacement sensor substitution in general manufacturing applications, Renishaw plc and ZEISS Group should deepen backward integration into stabilized laser sources to secure supply chains and compress qualification timelines under EU Chips Act mandates. Channel control through pre-certified subassembly partnerships with German machine tool builders offers a second defensive lever against margin erosion. For New Entrants and Emerging Players: Begin with Poland and Czech Republic precision engineering subcontractors facing first-generation interferometer installations under cascading OEM traceability requirements, where established vendor relationships remain underdeveloped. A calibration-service-first go-to-market angle, partnering with local metrology laboratories for PTB-aligned accreditation, bypasses the capital intensity of captive optical manufacturing while capturing recurring revenue streams. For Investors and Strategic Acquirers: Asymmetric upside sits with vacuum-engineering specialists possessing cross-trained talent in optical metrology and ultrahigh-vacuum systems, given the scarcity constraining EUV-compatible product development velocity. Long-term viability over a multi-year horizon favors acquisition targets with documented EU supply chains already qualified under EU Chips Act funding conditions. Practitioners should monitor REACH substance restriction expansions and helium-neon supplier consolidation for early signals of supply chain disruption premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stabilized Laser Sources | Secures supply chains against He-Ne tube concentration risk and accelerates EU Chips Act qualification timelines. |
| Calibration Service Unbundling | Enables distributors to capture recurring revenue through third-party metrology accreditations in the DACH region. |
| Vacuum-Compatible Architecture Development | Opens procurement contracts from ASML suppliers serving EUV lithography subsystem demand in the Netherlands. |
| Modular Electronics Platform Standardization | Reduces spare parts inventory for semiconductor fabs in Dresden and Eindhoven while expanding firmware subscription revenue. |
| Dual-Standard Certification Investment | Addresses fragmented compliance pathways between Germany's PTB protocols and France's LNE traceability requirements. |
Research Methodology
Direct dialogue with interferometer design engineers, semiconductor fab metrology managers, precision machine tool procurement leads, and national metrology institute calibration specialists grounded the qualitative foundation of this study. Secondary validation drew from EU Chips Act funding disclosures, REACH substance restriction filings, PTB and LNE calibration protocol documentation, and SEC filings of listed metrology equipment vendors. Bottom-up and top-down triangulation reconciled unit shipment estimates with capital expenditure patterns across European semiconductor fabrication facilities.
Bottom-up modeling segmented the market by laser source architecture, application environment, and end-user procurement authority, while top-down validation cross-checked aggregate value against disclosed metrology equipment budgets at major lithography and machine tool OEMs. CAGRs were derived from installation base growth, replacement cycle compression, and average selling price trajectories across the projection horizon. Industry-specific forecast inputs included EUV lithography subsystem procurement pipelines and PTB mandate implementation timelines for precision manufacturing traceability.
Several conditions sit outside the modeled scope, including potential relaxation of EU Chips Act domestic content requirements, breakthrough advances in quantum sensing displacement measurement, and helium-neon laser tube supplier exit or consolidation. Forecasts reflect assumptions about continued REACH compliance burden stability and sustained semiconductor capital expenditure in Germany and the Netherlands. Practitioners should monitor ECHA coating substance restriction expansions and national metrology institute protocol harmonization initiatives for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Excimer Laser Market
Optics
Optical Microscope Market
Optics
Fiber Optic Connectivity Market
Optics
Fiber-Optic Couplers Market
Optics
Solid State Lasers Market
Optics
Latin America Optical Imaging Market
Optics
Asia-Pacific Optical Imaging Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Collimating Lens Market
Optics
Europe Smart Glass Market
Optics
Photonics Sensor Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Residential 1080P Laser Television Projector Market
Optics
Laser Transmitter Market
Optics
Optical Receivers Market
Optics
Optical Gratings Market