
 Deburring Machine Market | 2026-2036
Deburring Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Deburring Machine Market Analysis
Robotic integration with CNC finishing platforms is narrowing the precision gap between manual craft and automated throughput. Kennametal leverages its tooling heritage to anchor high-performance abrasive solutions across aerospace supply chains. Rosler competes through captive control over media chemistry and process parameters. Emmegi Group specializes in compact automated cells that target job shops with limited floor space.
A deburring machine removes burrs, sharp edges, and residual material from machined, cast, or molded components using mechanical abrasion, pressurized fluid, thermal energy, or directed chemical action. These systems achieve surface roughness values between Ra 0.4 and 3.2 micrometers, enabling downstream coating adhesion, seal integrity, and component fatigue life. CNC deburring equipment leads the product type landscape due to its repeatability in high-volume automotive and electronics production. Water jet technology is gaining share in medical device applications where heat-affected zones must be eliminated. Abrasive finishing dominates tooling company installations where aggressive stock removal on hardened steels remains essential.
ISO 9001 quality management frameworks and EU Machinery Directive 2006/42/EC compliance requirements shape equipment specifications across European manufacturing bases. EPA air quality standards in the United States restrict dry abrasive emissions, accelerating wet-process and enclosed-system adoption. China's GB standards on industrial machinery safety create parallel certification pathways for equipment imports. Stakeholders must monitor how dual carbon goals in Asia-Pacific jurisdictions redirect capital toward energy-efficient spindle and pump technologies.
Market Dynamics
EU Machinery Directive 2006/42/EC compliance mandates are forcing automotive and aerospace OEMs to replace manual deburring stations with automated platforms that guarantee operator safety and process traceability.
Growth Catalysts
- Automotive surface quality mandates:Tier-1 suppliers in Germany's industrial belt are installing CNC deburring cells to meet OEM specifications for powertrain component fatigue resistance.
- EU Green Deal industrial decarbonization:Wet-process abrasive systems are displacing dry blasting to satisfy EPA air quality restrictions and REACH chemical safety protocols.
- ISO 9001 certification expansion:Medical device manufacturers require documented surface roughness validation, pulling precision finishing equipment into contract machining operations.
Market Restraints
- Abrasive media cost volatility:Ceramic and silicon carbide supply concentrates in Chinese processing facilities, exposing European machine builders to input price swings.
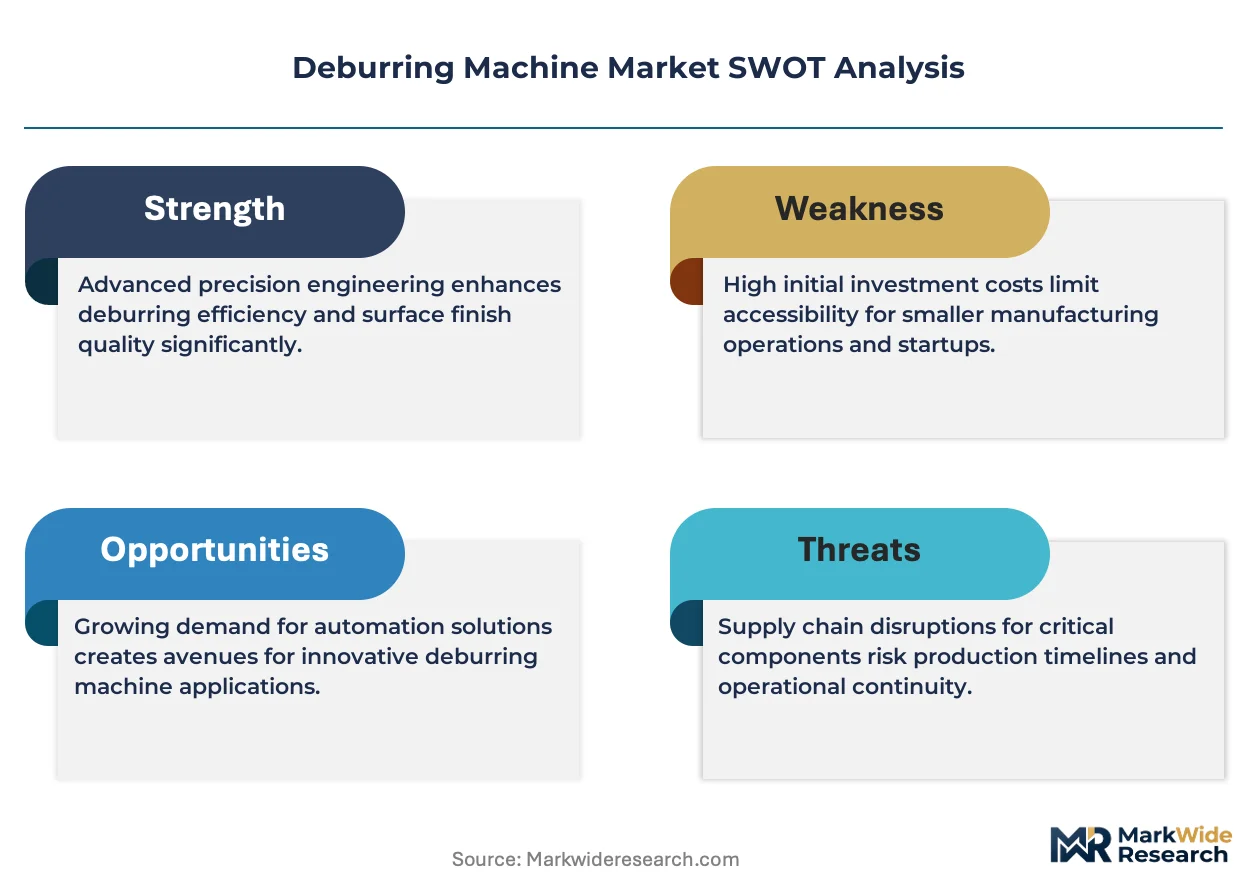
- Technical limitation in micro-deburring:Thermal energy methods generate heat-affected zones that compromise titanium implant biocompatibility, restricting process selection.
- Regulatory friction from dual certification:Equipment must satisfy both CE marking under EU Machinery Directive and China's GB standards, extending validation timelines.
Strategic Opportunities
- Underpenetrated Indian precision manufacturing:PLI scheme incentives for automotive component production are creating first-time demand for automated finishing in Pune and Chennai clusters.
- Technology convergence of robotics and fluid dynamics:Adaptive water jet systems with real-time pressure modulation are opening medical stent and catheter applications.
- Regulatory tailwind from MDR compliance:Europe's Medical Device Regulation mandates validated surface treatments, accelerating replacement of manual finishing in orthopedic supply chains.
Industry Challenges
- Multi-axis programming skill scarcity:CNC deburring cell operation requires simultaneous mastery of robotic path planning and abrasive parameter optimization.
- Legacy ERP integration complexity:New automated platforms must communicate with decades-old manufacturing execution systems common in German Mittelstand job shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deburring Machine Market |
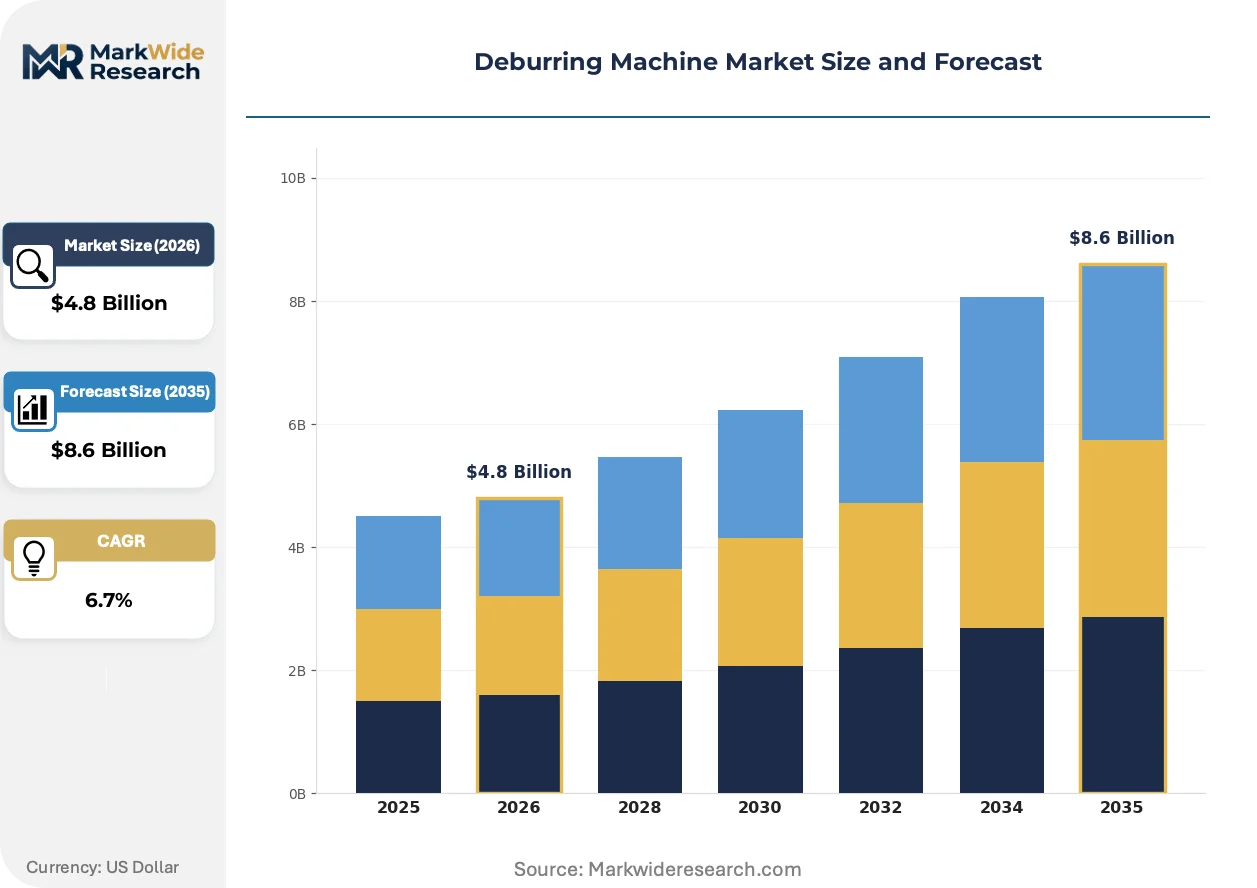
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, CNC Application: Aerospace, Automotive Parts, Medical Devices, Electronics End User: Manufacturers, Job Shops, OEMs, Tooling Companies Technology: Water Jet, Laser, Mechanical, Abrasive |
| Companies Covered | ALFRA, Kramer, Kennametal, GERIMA, Fimat, Rosler, Osborn International, Assfalg, Emmegi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deburring Machine Market Emerging Trajectories
Adaptive process control and closed-loop feedback systems are compressing the precision gap between high-volume automotive production and low-volume medical device finishing.
Electrochemical deburring is rendering obsolete mechanical abrasive methods for internal passage finishing in hydraulic valve bodies. Aerospace tier-1 suppliers in France and Germany are adopting these systems at pilot scale. The technology is rendering obsolete capital-intensive five-axis CNC platforms for complex internal geometries, compressing equipment footprints and eliminating media consumption.
REACH restrictions on hexavalent chromium compounds are prohibiting traditional chemical deburring baths across European surface treatment facilities. Manufacturers are retrofitting thermal energy and plasma electrolytic oxidation systems to maintain throughput. Medical implant processors in Switzerland and Ireland face the steepest compliance deadlines, accelerating wet-process equipment procurement.
Contract manufacturers are unbundling after-sales service from equipment purchases, demanding outcome-based availability guarantees rather than traditional spare parts contracts. Machine builders in Germany's Baden-Württemberg region are responding with remote diagnostics subscriptions. This shift is most visible among automotive stamping suppliers in Stuttgart and Munich industrial corridors managing 24-hour production schedules.
Deburring Machine Market Segmentation
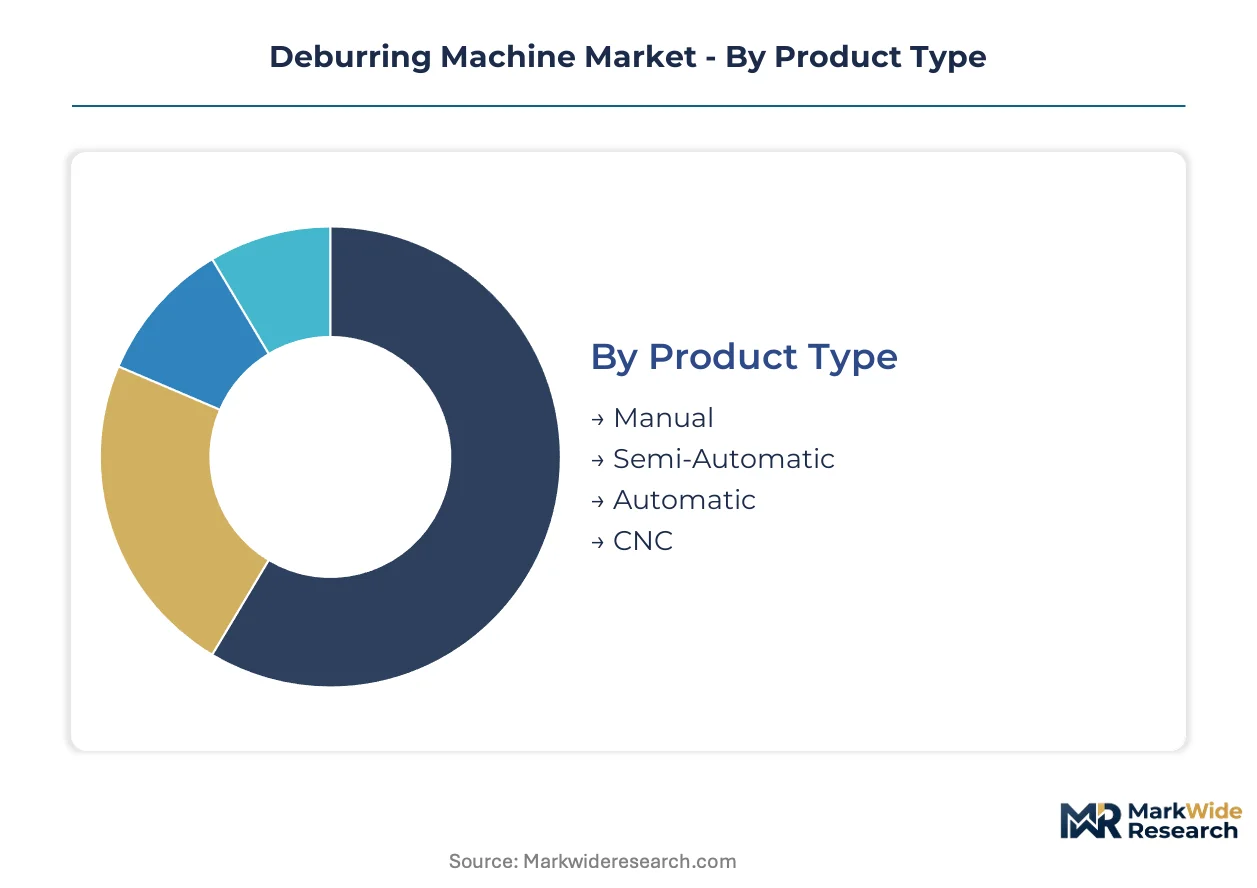
Deburring equipment selection hinges on production velocity, part complexity, and surface integrity requirements. Cycle time differentials between manual stations and automated cells often exceed 10:1, making segmentation decisions capital-intensive and strategically consequential for manufacturers balancing flexibility against throughput.
Product Type:
CNC and automatic platforms compress cycle times dramatically for high-volume automotive runs, while manual and semi-automatic systems retain relevance in prototype shops where setup frequency erodes automated efficiency gains.
- CNC:Computer-numerical control architectures synchronize multi-axis motion with real-time abrasive parameter adjustment. German automotive OEMs in Stuttgart and Munich corridors deploy these cells for powertrain component finishing where Ra 0.4 surface specifications are mandatory.
- Automatic:Fixed-program systems execute repetitive deburring sequences without operator intervention between load cycles. Electronics contract manufacturers in China's Pearl River Delta favor these for smartphone chassis processing where batch sizes justify dedicated automation.
- Semi-Automatic:Operator-assisted platforms blend manual loading with mechanized abrasive application. Job shops in India's Pune cluster deploy these for mixed automotive component runs where changeover frequency defeats full automation economics.
- Manual:Hand-held or bench-mounted tools demand skilled craft labor for irregular geometries. Tooling companies serving aerospace aftermarket repair in France maintain these capabilities for one-off turbine blade restoration.
CNC dominates installed base in high-volume corridors. Automatic is where expansion concentrates as mid-tier manufacturers close the automation gap.
Application:
Surface integrity requirements stratify sharply across end-use sectors, with medical and aerospace demanding validated process documentation that automotive and electronics often bypass.
- Automotive Parts:Powertrain and chassis components require aggressive stock removal on hardened steels and cast iron. Tier-1 suppliers in Germany's industrial belt deploy wet-process abrasive systems to satisfy EPA air quality restrictions while maintaining fatigue-resistant surface finishes.
- Medical Devices:Orthopedic implants and surgical instruments demand biocompatible surface states without heat-affected zones. Swiss and Irish processors facing REACH compliance deadlines accelerate wet-process equipment procurement to eliminate hexavalent chromium exposure risks.
- Aerospace:Turbine blades and structural components combine exotic alloys with tight dimensional tolerances. French tier-1 suppliers pilot electrochemical systems that render obsolete five-axis CNC platforms for complex internal geometries.
- Electronics:Miniaturized connectors and heat sinks require micro-deburring without conductive residue. Thermal energy methods generate heat-affected zones that compromise signal integrity, restricting process selection to fluid-based approaches.
Automotive Parts anchors volume demand. Medical Devices is climbing the fastest as MDR compliance mandates validated surface treatments.
End User:
Procurement authority and technical sophistication diverge between integrated manufacturers with captive finishing operations and independent job shops serving fragmented demand.
- OEMs:Original equipment manufacturers specify surface requirements and increasingly mandate supplier automation levels. Automotive OEMs in Germany's industrial belt demand documented Ra values from powertrain component suppliers.
- Tooling Companies:Cutting tool and die manufacturers operate abrasive finishing as core capability. Kennametal leverages tooling heritage to anchor high-performance abrasive solutions across aerospace supply chains.
- Job Shops:Contract manufacturers face equipment utilization pressure from irregular demand patterns. Emmegi Group targets these operators with compact automated cells designed for limited floor space.
- Manufacturers:Integrated producers with captive machining operations balance make-versus-buy decisions for finishing capacity. Electronics manufacturers in China's Shenzhen corridor internalize deburring to protect proprietary geometries.
OEMs dictate specification standards. Job Shops is gaining share fastest as contract manufacturers unbundle after-sales service from equipment purchases.
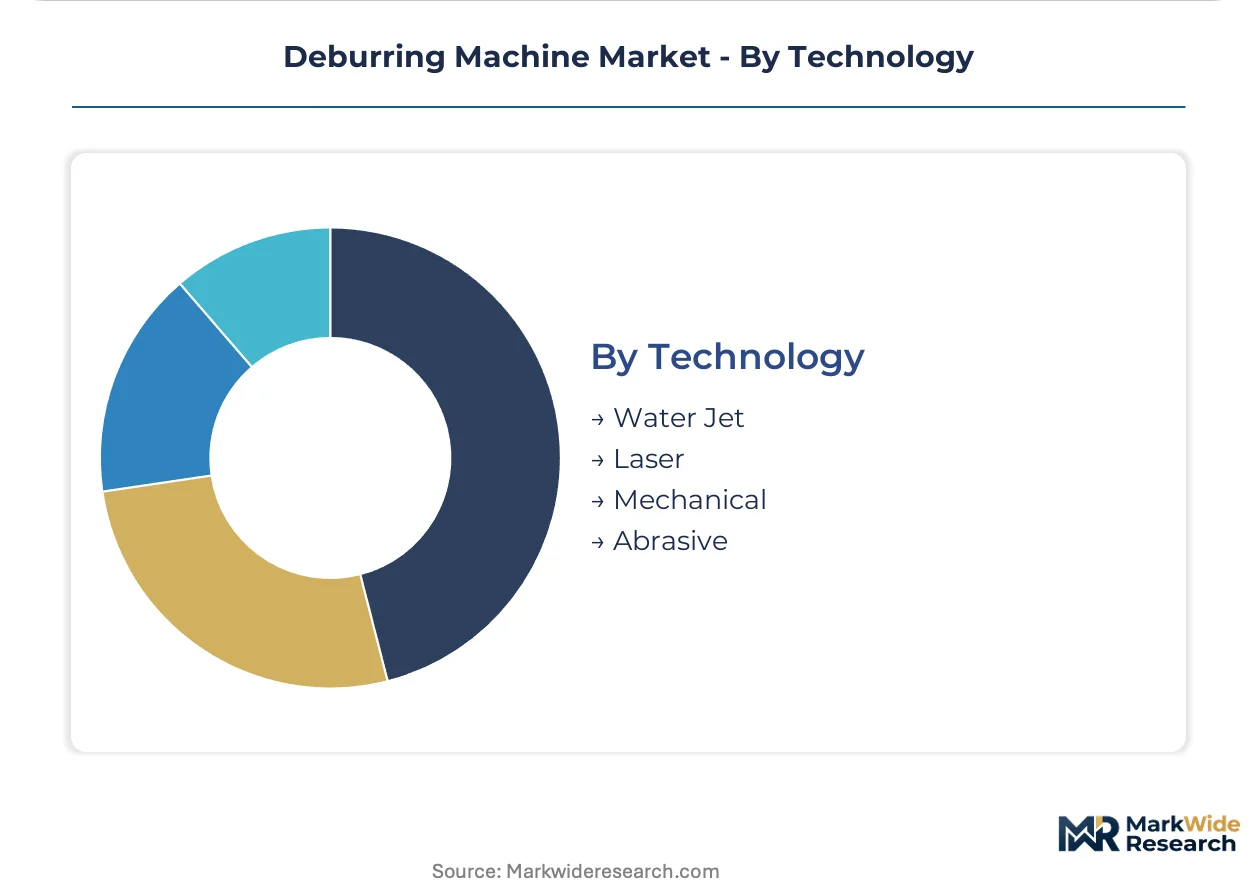
Technology:
Process selection trades material removal rate against thermal damage risk, with fluid-based methods displacing thermal approaches in temperature-sensitive applications.
- Abrasive:Mechanical abrasion with ceramic or silicon carbide media achieves aggressive stock removal on hardened steels. Supply concentration in Chinese processing facilities exposes European machine builders to input price volatility.
- Water Jet:Pressurized fluid cutting eliminates heat-affected zones critical for titanium implant biocompatibility. Adaptive systems with real-time pressure modulation are opening medical stent and catheter applications.
- Mechanical:Fixed-tool abrasion with brushes or cutters suits predictable geometries and high throughput. Automotive stamping suppliers favor these for consistent edge break specifications.
- Laser:Directed thermal energy vaporizes burrs with minimal mechanical contact. REACH restrictions on processing residues are accelerating adoption in European surface treatment facilities.
Abrasive dominates installed base. Water Jet is where expansion concentrates as medical device validation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs concentrate precision finishing demand through documented surface roughness mandates that cascade into supplier automation requirements. Tier-1 suppliers in Stuttgart and Munich corridors anchor equipment procurement volumes, while medical device processors in Switzerland and Ireland accelerate wet-process adoption to meet REACH compliance deadlines.
Germany
Powertrain component suppliers deploy CNC deburring cells to satisfy Ra 0.4 surface specifications from BMW and Mercedes-Benz. EU Machinery Directive 2006/42/EC mandates automated platforms that guarantee operator safety and process traceability. Baden-Württemberg machine builders serve aerospace tier-1 suppliers in the Stuttgart industrial corridor with electrochemical pilot systems.
United States
EPA air quality standards restrict dry abrasive emissions, accelerating wet-process and enclosed-system adoption among automotive stamping suppliers. OSHA workplace safety requirements push manufacturers toward automated platforms that eliminate manual handling of sharp-edged components. Detroit-area powertrain facilities install wet-process abrasive systems to maintain fatigue-resistant finishes while satisfying environmental constraints.
China
Electronics contract manufacturers in the Pearl River Delta favor automatic deburring systems for smartphone chassis processing where batch sizes justify dedicated automation. GB standards on industrial machinery safety create parallel certification pathways for equipment imports from European builders. Shenzhen-based manufacturers internalize finishing capacity to protect proprietary geometries from external exposure.
Switzerland
Orthopedic implant processors face steep REACH compliance deadlines for eliminating hexavalent chromium exposure risks from traditional chemical deburring baths. Swissmedic medical device regulations mandate validated surface treatments with documented process parameters. Zurich-area finishing facilities retrofit thermal energy and plasma electrolytic oxidation systems to maintain throughput under tightening chemical restrictions.
India
PLI scheme incentives for automotive component production create first-time demand for automated finishing in Pune and Chennai manufacturing clusters. BIS industrial machinery safety standards establish certification requirements for imported European equipment. Job shops in Maharashtra deploy semi-automatic platforms for mixed component runs where changeover frequency defeats full automation economics.
Deburring Machine Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. German and Swiss manufacturers anchor premium positioning through proximity to automotive and medical device clusters. The vendor base stratifies into three archetypes: integrated tooling conglomerates with captive abrasive supply, dedicated finishing equipment specialists with process chemistry expertise, and compact automation providers targeting space-constrained job shops. Competitive moves concentrate on M&A for regional channel access and strategic partnerships for technology convergence between robotics and fluid dynamics.
Among German-based specialists, Rosler and GERIMA occupy positions within the process-chemistry tier, while Kennametal represents the integrated tooling conglomerate archetype. These companies exemplify divergent strategic paths: dedicated equipment builders versus diversified industrial suppliers leveraging abrasive heritage across aerospace supply chains. Emmegi Group sits within the compact automation segment, targeting contract manufacturers with limited floor space requirements. The competitive terrain rewards players who combine equipment hardware with outcome-based service models, particularly among automotive stamping suppliers managing continuous production schedules.
| Leading Market Players |
|---|
| ALFRA |
| Kramer |
| Kennametal |
| GERIMA |
| Fimat |
| Rosler |
| Osborn International |
| Assfalg |
| Emmegi Group |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Chinese ceramic and silicon carbide processing facilities compresses pricing power for European machine builders while simultaneously forcing supply chain restructuring toward dual-sourcing arrangements. Abrasive media cost volatility determines both the spread between premium CNC platforms and economy semi-automatic systems and the geographic distribution of component inventory buffers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange-linked indexation dominate equipment procurement between German automotive OEMs and Baden-Württemberg machine builders. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked CNC cells with full MDR documentation from semi-automatic platforms with limited traceability. Price differentiation hinges on ISO 9001 certification grade and bundled after-sales service intensity. Cost compression in the economy tier is intensifying because Indian job shops prioritize capital efficiency over automation depth. Tier-1 automotive suppliers demonstrate lowest price sensitivity due to OEM-mandated surface specifications; prototype shops exhibit highest sensitivity with extended capital approval cycles.
Supply Chain Analysis
Contract manufacturing concentration among Foxconn and BYD Electronics facilities in China's Pearl River Delta anchors automatic deburring system demand. Geographic supply concentrates in Germany for precision spindle assemblies, China for abrasive media processing, and Switzerland for medical-grade control electronics. Raw material dependencies encompass silicon carbide grit, high-grade aluminum oxide, and specialized pump components. Single-source vulnerability in ceramic media supply exposes European builders to input price swings. Distribution runs through direct OEM sales teams for high-value CNC platforms and regional distributors for compact job shop equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU Machinery Directive, China's GB standards, and India's BIS certifications fragments vendor consolidation trajectories while creating specialist niches for compliance-focused equipment builders.
For Market Incumbents: Insulate installed base positions through captive control over media chemistry supply chains and predictive maintenance subscription models. Electrochemical deburring substitution threatens traditional five-axis CNC platforms; backward integration into abrasive media production secures margin protection against Chinese supply volatility. CE-MDR dual certification investments defend specification authority in orthopedic supply chains. For New Entrants and Emerging Players: India's Pune and Chennai manufacturing clusters offer the most penetrable white-space for first-time automated finishing demand under PLI scheme incentives. Medical device contract machining in Switzerland presents adjacent entry opportunity given REACH-driven equipment replacement cycles. Target outcome-based availability guarantees rather than traditional spare parts contracts to differentiate from legacy German vendors. For Investors and Strategic Acquirers: Europe's Medical Device Regulation reshapes the acquisition landscape by elevating validated process documentation capabilities above pure equipment manufacturing scale. Long-term viability centers on service-revenue attachment rates and recurring media consumables. Acquire process-chemistry specialists with captive abrasive formulation expertise. Monitor MDR compliance deadline acceleration as inflection signal for replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Abrasive Media | Captive silicon carbide supply insulates Kennametal and Rosler from Chinese processing price volatility. |
| MDR Compliance Certification Investment | Validated surface treatment documentation opens orthopedic implant supply chains to equipment vendors. |
| Remote Diagnostics Subscription Launch | Outcome-based availability guarantees capture automotive stamping suppliers managing continuous production. |
| Adaptive Water Jet Platform Development | Real-time pressure modulation technology penetrates medical stent and catheter finishing applications. |
| Compact Cell Geographic Expansion | Emmegi Group targets Indian job shops with space-constrained Pune and Chennai facilities. |
Methodological Framework
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this deburring machine analysis. Primary fieldwork across German automotive corridors, Swiss medical device clusters, and Chinese electronics manufacturing zones combined with secondary validation from SEC filings, EU Machinery Directive compliance databases, and customs trade records. Bottom-up equipment shipment tallies and top-down industrial automation expenditure estimates provided triangulation integrity.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions encompassed product architecture, application sector, end-user procurement authority, and process technology type. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline mapping, and industrial capital expenditure elasticity modeling. Industry-specific forecast inputs included EU Green Deal decarbonization timelines and MDR implementation phase schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-sponsored equipment builders or accelerated electrochemical deburring adoption would shift outcomes beyond modeled ranges. Quarterly review of abrasive media price indices, MDR audit failure rates, and PLI scheme disbursement velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Centerless Grinding Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
India Power Tool Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Micro Welders Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Height Gauge Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Plasma Arc Cutting Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Jigs and Other Tools Market