
 Jigs and Other Tools Market | 2026-2036
Jigs and Other Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Jigs and Other Tools Market Foresight
Digital twin integration is fragmenting traditional jig design workflows across manufacturing ecosystems. Kennametal, Inc. leverages its materials science portfolio to dominate carbide-based fixturing for aerospace turbine blade machining. MISUMI Group, Inc. anchors its competitive position through a catalog-driven distribution model that compresses procurement cycles for standardized jig components. ASAHI Tools Mfg. Co. Ltd. specializes in high-precision angle jigs for Japanese automotive tier-one suppliers, sustaining regional manufacturing density.
Jigs and other tools encompass mechanically guided devices fabricated from hardened steel, aluminum alloys, or engineered composites that constrain workpiece position during drilling, routing, milling, or assembly operations to achieve repeatable dimensional tolerances. Drill jigs and fixture jigs represent mature margin pools where steel construction dominates heavy-duty metalworking, while router jigs in aluminum and composite variants capture expanding demand from furniture makers and aerospace fabricators seeking weight reduction. The application split between metalworking and manufacturing reflects diverging tooling complexity, with automotive and aerospace end users driving specification upgrades toward modular, quick-change architectures.
ISO standards for dimensional metrology, OSHA machine guarding requirements in the US, and CE marking obligations under EU machinery directives collectively elevate product certification costs while filtering low-specification competitors from OEM supply chains. Japan's METI industrial standards and China's GB standards for machine tool accessories further fragment compliance architectures for multinational tooling suppliers. Stakeholders must monitor how carbon accounting rules under the EU Green Deal reshape material sourcing decisions for steel-intensive jig fabrication.
Market Dynamics
Digital twin integration is collapsing traditional jig design cycles from months to weeks, forcing fabricators to restructure engineering workflows around real-time simulation and generative fixture algorithms.
Growth Catalysts
- ISO 9001 quality mandates:Aerospace OEMs in Germany and Japan now require certified jig traceability, expanding precision tooling procurement across tier-one supply chains.
- Automotive localization corridors:OEMs in China, India, and Mexico are captive-sourcing jig fabrication to compress lead times and shield against logistics volatility.
- Carbide material advances:Hardened carbide fixturing extends tool life in turbine blade machining, reducing per-part tooling costs for aerospace fabricators.
Market Restraints
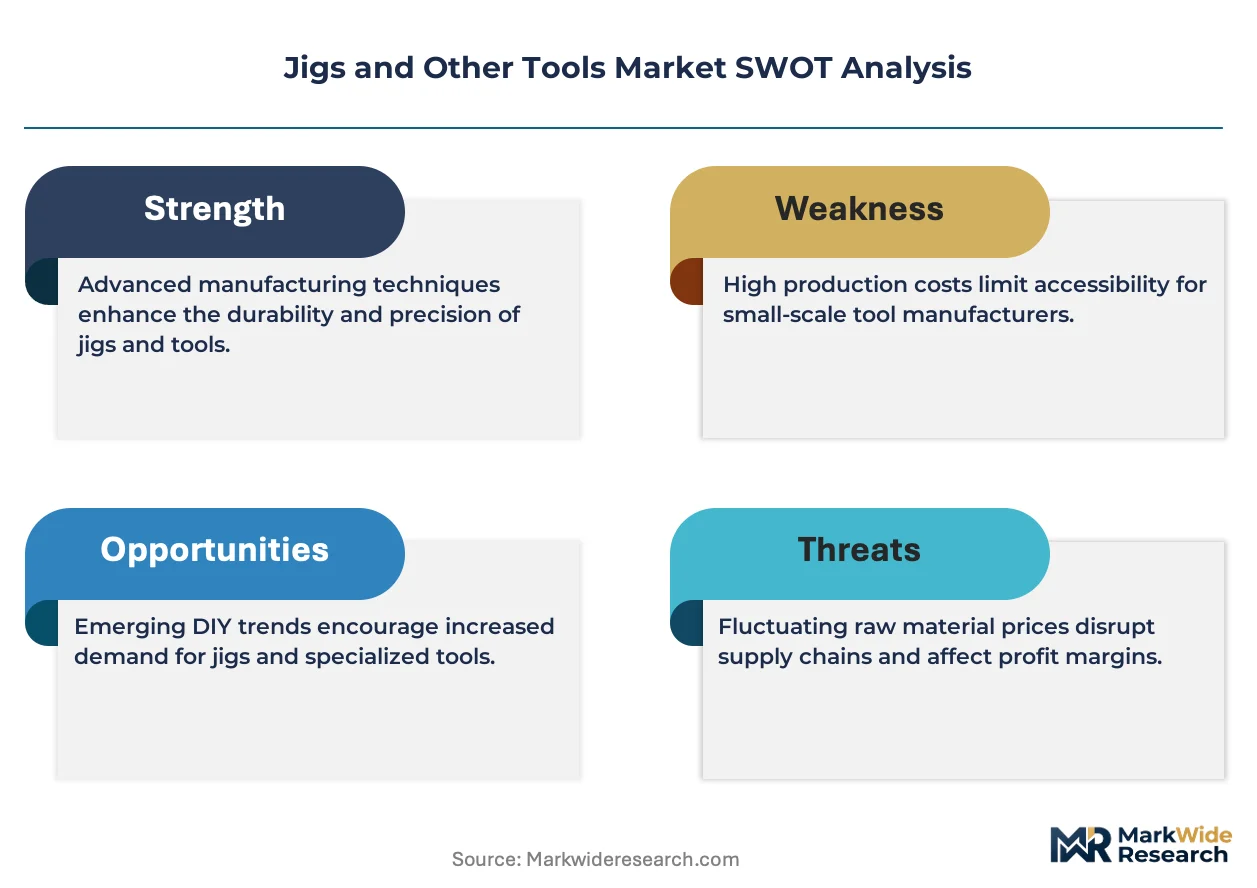
- Alloy input cost volatility:Hardened steel and aluminum alloy prices fluctuate with energy markets, squeezing margin pools for standardized jig producers.
- Regional certification fragmentation:Japan's METI industrial standards, China's GB standards, and EU CE marking create compliance cost stacking for multinational suppliers.
- Polymer composite substitution:Engineered thermoplastics and carbon-fiber fixtures displace metal jigs in weight-sensitive aerospace applications.
Strategic Opportunities
- EU Green Deal carbon accounting:Steel-intensive jig fabricators can capture premium positioning by documenting Scope 3 emissions for automotive OEMs.
- Quick-change modular architectures:Automotive and aerospace end-users are retrofitting legacy lines with reconfigurable fixturing to accommodate model mix proliferation.
- Catalog-driven distribution platforms:Standardized component suppliers can compress procurement cycles by bypassing traditional distributor markups.
Industry Challenges
- CAD-to-fabrication skill gaps:Generative design tools require cross-trained engineers fluent in both simulation software and subtractive manufacturing constraints.
- Multi-standard certification timelines:Simultaneous ISO, CE, and METI approvals delay product launches by 6-12 months for entry into Japanese and European automotive supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jigs and Other Tools Market |
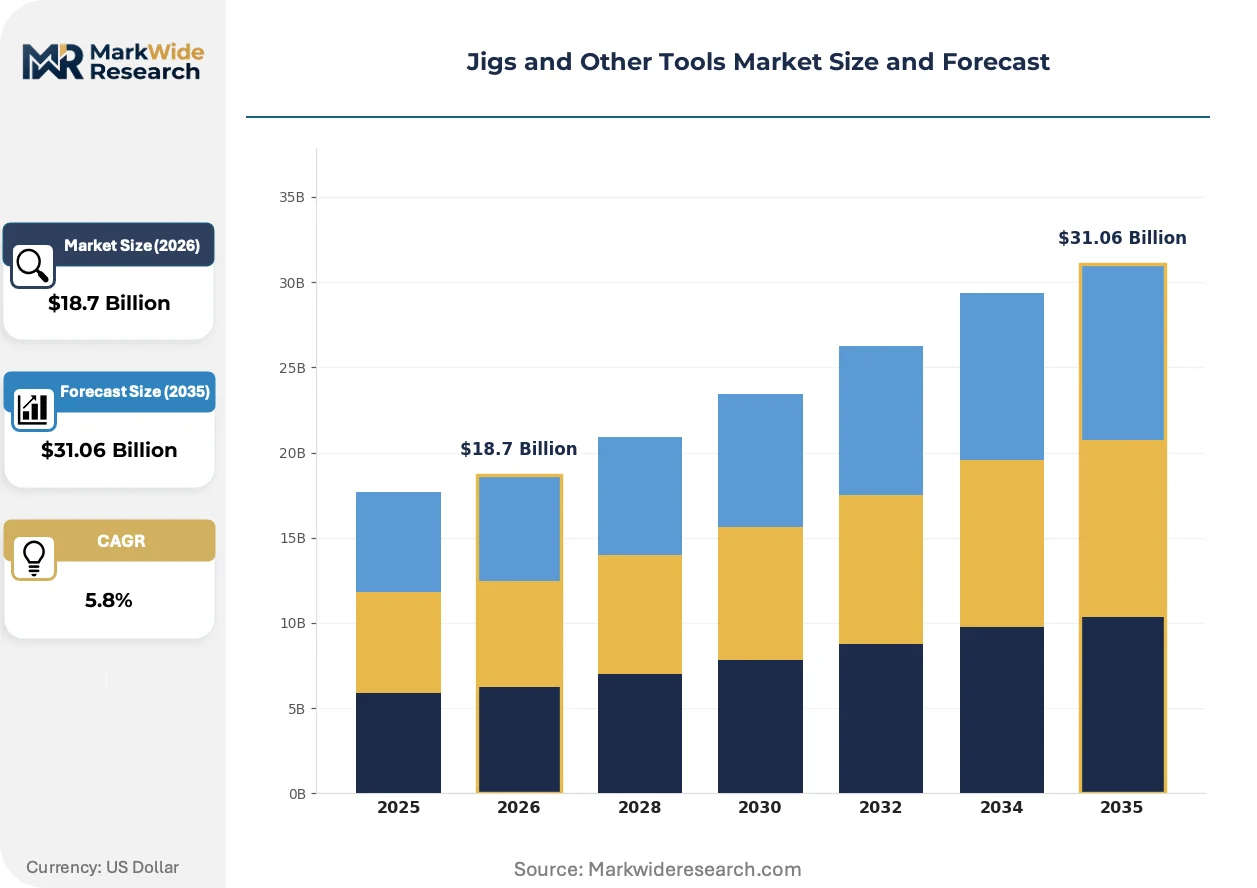
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Drill Jigs, Angle Jigs, Fixture Jigs, Router Jigs Material: Steel, Aluminum, Plastic, Composite Application: Woodworking, Metalworking, Assembly, Manufacturing End User: Construction, Furniture Making, Automotive, Aerospace |
| Companies Covered | Kennametal, Inc., MISUMI Group, Inc., Tipco Punch Inc., Unique Tool and Gauge Inc., ASAHI Tools Mfg. Co. Ltd., Dies Plus, RotoMetrics, ALLMATIC- Jacob Spannsysteme GmbH, AWEBA Werkzeugbau GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jigs and Other Tools Market Shifts & Advancements
Generative design algorithms and cloud-native simulation platforms are rewiring how fixtures move from concept to production floor, compressing traditional engineering handoffs.
Cloud-based generative design software is collapsing the iteration cycle between fixture concept and machinable geometry. Automotive tier-one suppliers in Stuttgart and Toyota City now deploy topology-optimized jigs that reduce material usage by 30-40% while maintaining clamping force specifications. This capability is collapsing the competitive advantage of legacy pattern shops that rely on manual CAD workflows and empirical testing protocols.
The EU Green Deal's carbon border adjustment mechanism is reshaping material sourcing decisions for steel-intensive fabrication. German automotive OEMs now require documented Scope 3 emissions for jig components, pressuring Eastern European suppliers to upgrade energy-intensive heat treatment processes. Aerospace fabricators in Toulouse and Hamburg are responding by qualifying recycled aluminum alloys for non-structural fixturing applications.
Automotive OEMs are unbundling after-sales service from initial equipment contracts, creating standalone lifecycle management agreements. Tier-one suppliers in Mexico and India now compete on predictive maintenance algorithms and spare-part availability rather than upfront tooling cost. This shift is most visible in Volkswagen Group's Puebla operations and Tata Motors' Pune assembly corridors, where uptime guarantees now dominate vendor selection criteria.
Jigs and Other Tools Market Segmentation
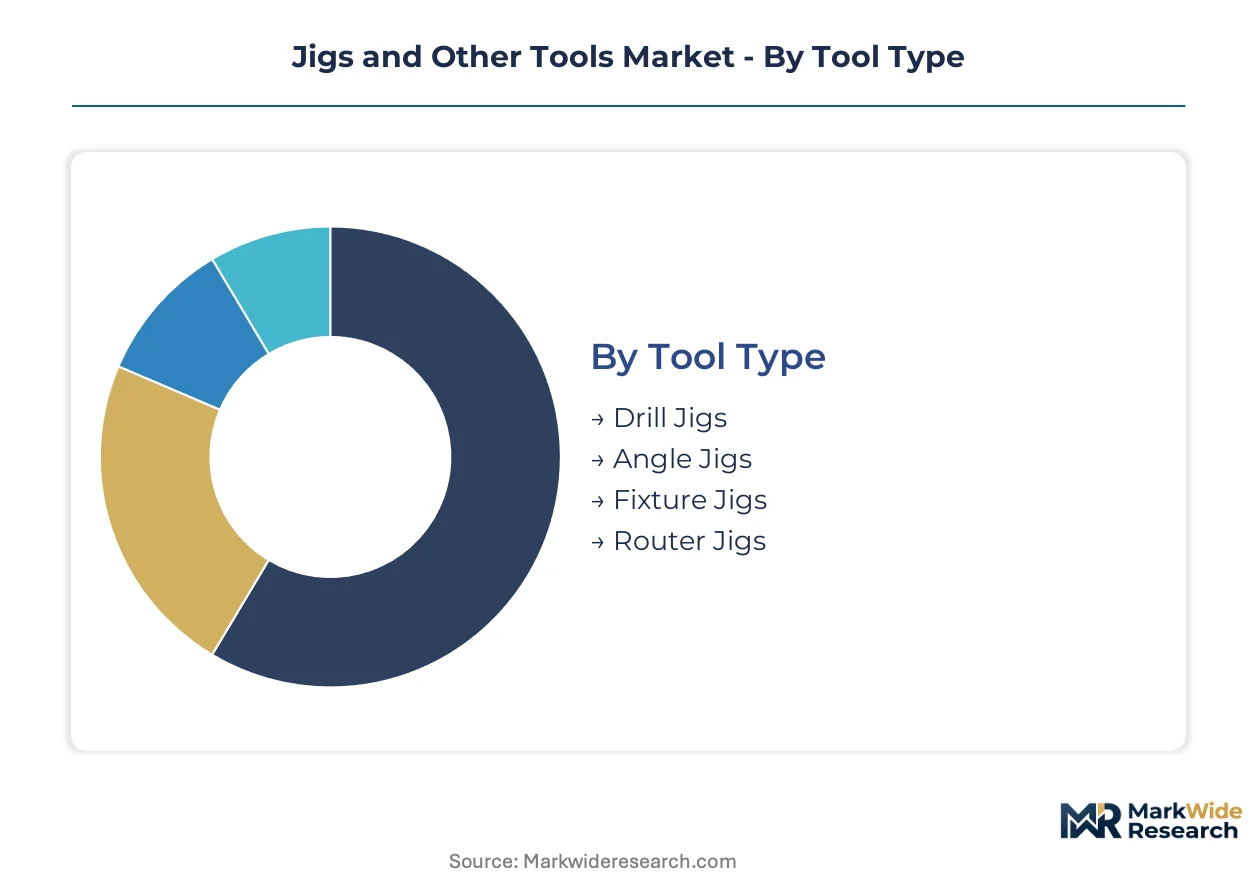
Jig procurement cycles vary dramatically by tool complexity and end-use criticality, creating distinct inventory velocity profiles across manufacturing supply chains. Understanding these turnover patterns helps suppliers align fabrication capacity with demand pulsation in automotive and aerospace corridors.
Tool Type:
Drill jigs and router jigs turn over fastest in high-volume automotive assembly, while fixture jigs for aerospace turbine machining sit on capital budgets for years.
- Drill Jigs:Hardened steel or carbide-lined templates guide twist drills to precise hole patterns in engine blocks and transmission housings. Automotive OEMs in Stuttgart and Detroit burn through drill jig inventories fastest, replacing worn bushings quarterly on high-throughput lines.
- Fixture Jigs:Modular clamping systems secure irregular workpieces during multi-axis machining operations. Aerospace fabricators in Toulouse and Hamburg amortize these assets over decade-long production runs for single-aisle jet programs, stretching replacement cycles.
- Angle Jigs:Precision-machined brackets maintain orthogonal relationships during assembly, common in Japanese automotive tier-one supply chains.
- Router Jigs:Aluminum or composite templates guide cutting paths in furniture and aerospace panel fabrication, with Mexican woodworking clusters driving steady replacement demand.
Drill jigs anchor the volume base while fixture jigs gain share at the steepest rate as aerospace OEMs localize precision tooling.
Material:
Cost tiers separate commodity steel from certified aerospace composites, with aluminum occupying the mid-market sweet spot for weight-conscious automotive applications.
- Steel:Heat-treated alloy constructions dominate heavy-duty metalworking where clamping forces exceed 50 kN. German machine builders specify DIN-standard steel jigs for durability in 24/7 automotive powertrain lines.
- Composite:Carbon-fiber reinforced fixtures cut weight by 60% versus steel equivalents for robotic handling in Airbus final assembly. Qualification timelines stretch 18 months, limiting adoption to programs with decade-long production commitments.
- Aluminum:7075-T6 and similar alloys balance machinability with strength for router jigs and light assembly fixtures across furniture and automotive sectors.
- Plastic:Engineered thermoplastics serve prototype shops and low-force clamping applications where metal fatigue is irrelevant.
Steel commands the installed base while composites climb the fastest as EU carbon accounting rules reshape material selection criteria.
Application:
Volume concentrates in metalworking corridors, though assembly applications are expanding most quickly as OEMs retrofit lines for electric vehicle platform flexibility.
- Metalworking:Drilling, milling, and turning operations consume the broadest jig variety across automotive and aerospace machine shops. China's Yangtze River Delta metalworking clusters source locally fabricated steel fixtures to compress lead times.
- Assembly:Reconfigurable fixturing for mixed-model lines demands quick-change architectures. Volkswagen's Puebla operations and Tata Motors' Pune facilities now specify modular jigs that retool in under 30 minutes.
- Woodworking:Router jigs for furniture makers favor aluminum and composite constructions to reduce operator fatigue during handheld operations.
- Manufacturing:General-purpose fixtures span multiple processes in job shops with irregular product mixes.
Metalworking generates the revenue base while assembly applications expand most quickly as automotive model proliferation accelerates fixturing refresh cycles.
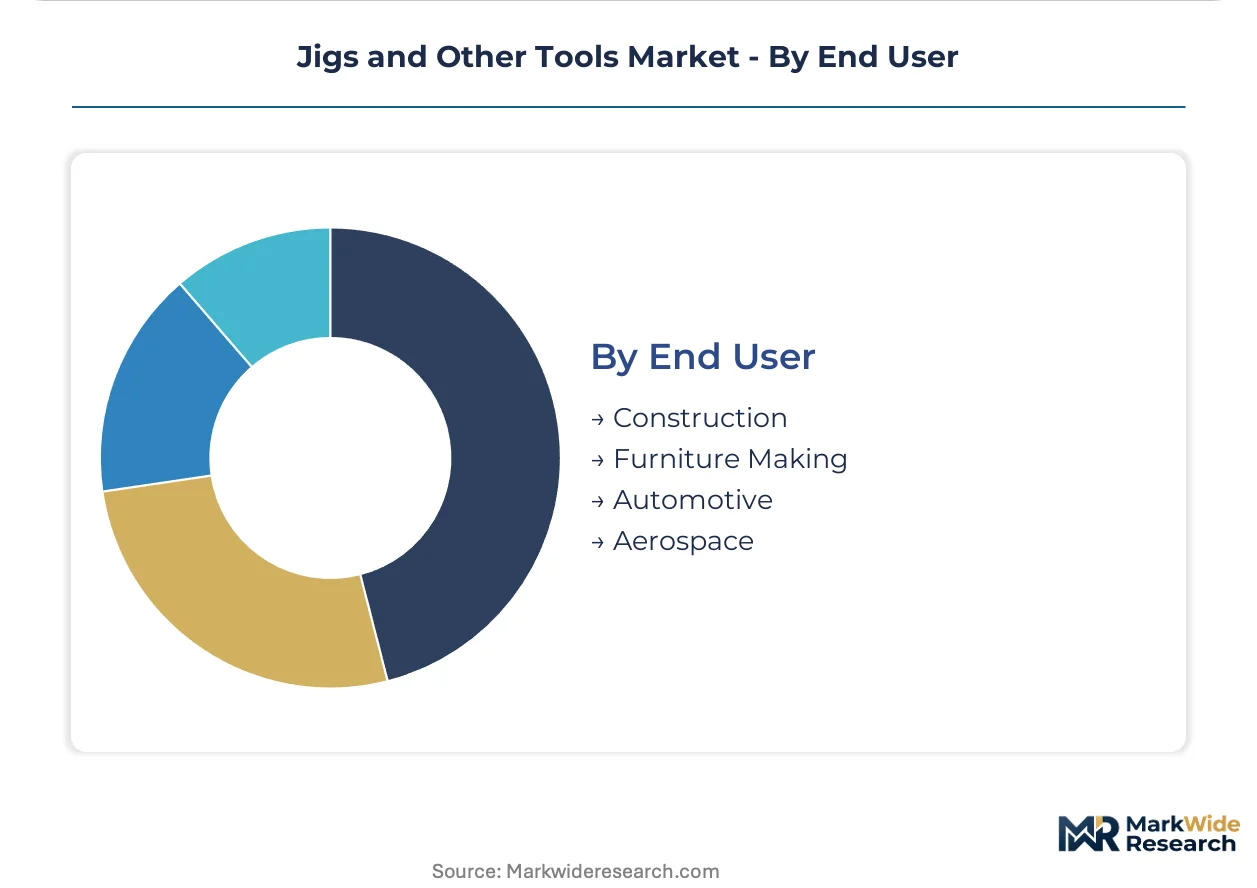
End User:
Specification intensity separates aerospace certification requirements from construction's price-driven procurement, with automotive occupying the demanding middle ground.
- Automotive:OEMs and tier-one suppliers drive the largest absolute demand for drill jigs and assembly fixtures. Mexico's Bajío automotive corridor has emerged as a captive fabrication hub where local suppliers serve Nissan, GM, and Volkswagen operations with 48-hour turnaround.
- Aerospace:Turbine blade machining and airframe assembly demand traceable, certified fixturing with documented heat treatment histories. Japan's METI standards and EU CE marking create dual compliance burdens for suppliers serving both Boeing and Airbus chains.
- Construction:Structural steel fabrication and concrete formwork use standardized, low-cost jigs with minimal specification overhead.
- Furniture Making:Italian and Polish manufacturers favor aluminum router jigs for batch production of cabinet and seating components.
Automotive anchors procurement volumes while aerospace commands the steepest specification upgrade trajectory as ISO 9001 traceability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision tooling exports flow into Airbus supply chains in Toulouse and Hamburg, while Japanese fabricators serve Boeing tier-one suppliers across the Pacific corridor. These bilateral trade patterns concentrate specification authority in Stuttgart and Nagoya, forcing regional suppliers to align with divergent certification architectures.
Germany
Automotive powertrain manufacturers in Stuttgart and Munich drive demand for DIN-standard steel drill jigs with 24/7 durability specifications. EU CE marking and the EU Green Deal's carbon border adjustment mechanism now require documented Scope 3 emissions for heat-treated components. Bavarian machine builders in Augsburg and Nuremberg are retrofitting energy-intensive heat treatment lines to maintain automotive OEM qualification.
Japan
Aerospace turbine blade machining in Nagoya and Toyota City sustains long-cycle fixture jig procurement with METI-certified traceability requirements. Japan's METI industrial standards mandate documented heat treatment histories for precision fixturing entering Boeing and Airbus supply chains. Chubu region fabricators specialize in high-precision angle jigs for automotive tier-one suppliers, sustaining regional manufacturing density around Toyota headquarters.
China
Automotive localization in the Yangtze River Delta and Pearl River Delta compresses lead times for jig fabrication serving Volkswagen and GM joint ventures. GB standards for machine tool accessories create compliance burdens distinct from ISO and CE architectures. Suzhou and Shanghai metalworking clusters source locally fabricated steel fixtures, bypassing import logistics for high-volume assembly lines.
United States
OSHA machine guarding requirements elevate certification costs for jig suppliers serving Detroit automotive powertrain corridors. Michigan and Ohio assembly plants specify quick-change modular fixtures to accommodate model mix proliferation on mixed-model lines. Aerospace fabricators in Seattle and Wichita qualify carbide-based fixturing for turbine blade machining, extending tool life in high-value operations.
Mexico
The Bajío automotive corridor has emerged as a captive fabrication hub where local suppliers serve Nissan, GM, and Volkswagen operations with compressed turnaround times. Mexican federal labor regulations and USMCA origin requirements shape procurement decisions for cross-border supply chains. Querétaro and Guanajuato fabrication shops now compete on predictive maintenance algorithms and spare-part availability rather than upfront tooling cost.
Jigs and Other Tools Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven distributors and precision-focused fabricators occupy distinct margin pools. The vendor base clusters around three strategic archetypes: catalog-driven component distributors, materials-science-led precision specialists, and regional captive fabricators serving single OEMs. Consolidation pressure concentrates among mid-scale pattern shops unable to fund generative design capabilities. Dominant competitive moves include backward integration into heat treatment processes and geographic expansion into automotive localization corridors.
Within the materials-science tier, Kennametal, Inc. and ASAHI Tools Mfg. Co. Ltd. occupy positions anchored by hardened carbide and precision angle jig expertise respectively. MISUMI Group, Inc. exemplifies the catalog-driven distribution archetype, compressing procurement cycles for standardized components across fragmented buyer bases. These three entities represent divergent competitive vectors: materials innovation, geographic specialization, and channel control.
| Leading Market Players |
|---|
| Kennametal, Inc. |
| MISUMI Group, Inc. |
| Tipco Punch Inc. |
| Unique Tool and Gauge Inc. |
| ASAHI Tools Mfg. Co. Ltd. |
| Dies Plus |
| RotoMetrics |
| ALLMATIC- Jacob Spannsysteme GmbH |
| AWEBA Werkzeugbau GmbH |
| Others |
Supply & Pricing Matrix
Steel and carbide input concentration in Germany and Japan concentrates margin capture among heat-treatment-certified fabricators serving automotive and aerospace OEMs. Cost-plus contracts with aluminum and energy indexation pass through alloy volatility to end-users while locking in fabrication margins for qualified suppliers.
Pricing Analysis
Cost-plus contracts with quarterly aluminum and energy indexation dominate long-term automotive supply agreements, insulating German and Japanese fabricators from alloy volatility. Price differentiation rests on ISO 9001 certification tier and documented Scope 3 emissions compliance for EU automotive OEMs. Pricing pressure stems from polymer composite substitution in aerospace weight-reduction programs. Construction and furniture-making buyers exhibit highest price sensitivity, while aerospace turbine-blade fabricators accept premiums for traceable heat-treatment histories.
Supply Chain Analysis
Contract manufacturing capacity clusters with Bavarian heat-treatment specialists, Chubu-region precision fabricators, and Yangtze River Delta metalworking clusters. Supply chains draw from hardened steel mills in Germany, aluminum smelters in China, and carbide powder producers in Japan. Single-source vulnerability concentrates in certified heat-treatment lines serving aerospace qualification requirements. Distribution runs through catalog-driven platforms like MISUMI for standardized components and direct OEM relationships for custom fixture jigs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative design platforms and cloud-native simulation ecosystems are transforming jig procurement into interoperability-driven platform economics, where CAD-to-fabrication workflow integration determines vendor lock-in.
For Market Incumbents: Insulate core margins by backward integration into heat-treatment processes and captive certification capacity for METI and CE dual compliance. Defend against generative-design entrants by embedding predictive maintenance algorithms into lifecycle service contracts for automotive OEMs in Mexico and India.
For New Entrants and Emerging Players: Establish a beachhead in quick-change modular fixturing for electric vehicle platform retrofits, where incumbent pattern shops lack generative design fluency. Target mid-scale automotive tier-one suppliers in China's Pearl River Delta with cloud-native topology optimization tools that compress design-to-fabrication cycles.
For Investors and Strategic Acquirers: Capital is best deployed toward catalog-driven distribution platforms with captive buyer bases and heat-treatment-certified precision fabricators serving dual aerospace compliance requirements. Monitor EU Green Deal carbon border adjustment implementation as the inflection signal for material sourcing preference shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Bavarian fabricators secure DIN-standard certification capacity against Eastern European competitors. |
| Generative Design Platform Deployment | Stuttgart automotive suppliers reduce jig material usage through topology-optimized clamping architectures. |
| Carbon Accounting Documentation Investment | German OEMs now require Scope 3 emissions traceability for steel-intensive jig components. |
| Quick-Change Modular Architecture Development | Volkswagen Puebla operations specify sub-30-minute retooling fixtures for mixed-model EV lines. |
| Catalog-Driven Distribution Expansion | MISUMI's component marketplace compresses procurement cycles for standardized jig bushings and plates. |
Research Methodology
The analysis maps drill jig, fixture jig, router jig, and angle jig sub-sectors, each validated through plant engineers at automotive OEMs, procurement leads at aerospace tier-one suppliers, heat-treatment facility operators, and aftermarket service heads. Primary interviews triangulated against customs trade data for machine tool accessories, SEC filings of listed tooling suppliers, METI industrial standard registries, and EU CE marking databases. Bottom-up fabrication capacity estimates cross-checked with top-down OEM procurement spend patterns.
Forecast assumptions held ISO 9001 certification penetration and EU Green Deal carbon accounting implementation fixed across the projection horizon, while varying automotive localization intensity and generative design adoption curves. Segmentation modeled tool type, material tier, application criticality, and end-user specification intensity. CAGRs derived from elasticity-adjusted demand curves for aerospace turbine-blade machining and automotive powertrain assembly.
Macroeconomic conditions sit as an overlay; deviation in aluminum alloy prices, energy costs, or trade tariff regimes would shift the trajectory for import-dependent supply chains. Quarterly review of OEM localization announcements, carbon border adjustment implementation timelines, and generative design software adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Height Gauge Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Die Grinders Market
Industrial Tools
India Power Tool Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Electric Tools Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Tool Holder Market
Industrial Tools
Digital Tool Presetter Market