
 Air Screwdrivers Market | 2026-2036
Air Screwdrivers Market Size, Share, and Industry Trends Forecast 2026-2036
Air Screwdrivers Market Analytics
Equipment leasing and tool-as-a-service financing is fragmenting the competitive landscape for capital-intensive pneumatic tooling. Atlas Copco AB leverages captive finance subsidiaries to lock in long-term fleet contracts with tier-one manufacturers. Ingersoll Rand anchors its position through backward integration into compressor systems that bundle screwdriver deployments. Desoutter Industrial Tools specializes in torque-audited assembly solutions for aerospace fastening protocols.
An air screwdriver is a pneumatically powered rotary fastening tool that converts compressed air into controlled torque output, typically operating at 1,000 to 3,000 RPM with adjustable clutch mechanisms for repeatable screw driving cycles. Its primary industrial purpose is delivering consistent torque in high-volume assembly environments where manual fastening introduces unacceptable variance. Pistol grip models dominate volume sales in automotive assembly due to ergonomic compatibility with overhead fastening positions, while digital controls represent the fastest-expanding technology segment as manufacturers retrofit lines with torque-data-logging capabilities. Inline models occupy a mature niche in confined-space maintenance operations where clearance constraints eliminate pistol alternatives.
FAA airworthiness directives and EASA certification standards govern aerospace-grade screwdriver calibration intervals, forcing maintenance providers into documented tool traceability systems. OSHA lockout-tagout regulations and ISO 5393 torque testing protocols shape industrial procurement specifications, effectively filtering non-compliant suppliers from certified facility bids. Stakeholders must monitor how digital torque verification requirements propagate from aerospace into general manufacturing specifications.
Market Dynamics
Equipment leasing and tool-as-a-service financing is fragmenting the competitive landscape for capital-intensive pneumatic tooling. Atlas Copco AB leverages captive finance subsidiaries to lock in long-term fleet contracts with tier-one manufacturers. Ingersoll Rand anchors its position through backward integration into compressor systems that bundle screwdriver deployments. Desoutter Industrial Tools specializes in torque-audited assembly solutions for aerospace fastening protocols.
Growth Catalysts
- OSHA Workplace Safety Mandates:OSHA lockout-tagout regulations and ISO 5393 torque testing protocols tighten tool specification requirements, filtering non-compliant suppliers from certified facility bids and expanding demand for precision fastening tools.
- Automotive Assembly Line Expansion:Precision fastening tools see expanding adoption across automotive assembly lines where repeatable screw driving cycles eliminate unacceptable variance from manual fastening.
- Germany's Industrial Manufacturing Corridor:Demand concentrates in Germany's industrial manufacturing corridor, where tier-one manufacturers retrofit lines with torque-data-logging capabilities.
Market Restraints
- Compressed Air Infrastructure Dependency:Pneumatic screwdriver deployment requires captive compressor systems, creating capital intensity barriers for smaller maintenance providers.
- Calibration Interval Burden:FAA airworthiness directives and EASA certification standards govern aerospace-grade screwdriver calibration intervals, forcing maintenance providers into documented tool traceability systems with recurring compliance costs.
- Electric Tool Substitution:Battery-powered alternatives eliminate compressor infrastructure requirements and appeal to facilities without existing pneumatic distribution networks.
Strategic Opportunities
- Digital Torque Verification Propagation:Digital torque verification requirements from aerospace specifications propagate into general manufacturing, creating retrofit demand across industrial sectors.
- Tool-as-a-Service Channel Innovation:Equipment leasing fragments capital-intensive pneumatic tooling procurement, enabling fleet contract penetration among mid-tier manufacturers previously excluded from outright purchase.
- Inline Model Niche Expansion:Confined-space maintenance operations in aging industrial facilities create sustained demand for inline models where clearance constraints eliminate pistol alternatives.
Industry Challenges
- ISO Torque Certification Timeline:ISO 5393 certification processes create extended vendor qualification periods, compressing competitive response windows for new market entrants.
- Legacy System Integration Friction:Torque-data-logging retrofits face integration complexity with legacy manufacturing execution systems, delaying digital control adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Screwdrivers Market |
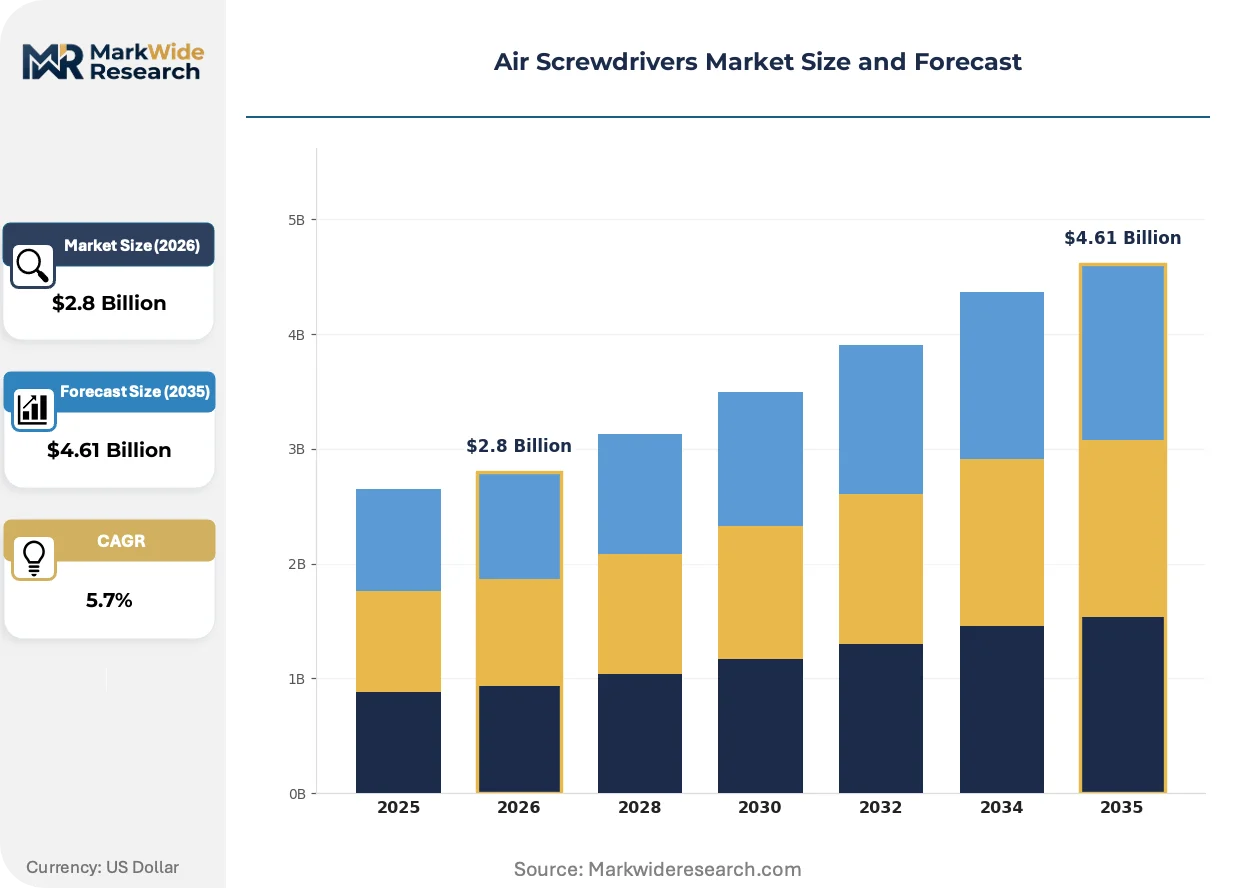
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Air Screwdrivers, Pistol Grip Models, Inline Models, Specialty Screwdrivers End User: Manufacturing, Automotive Assembly, Construction, Aerospace Application: Industrial Repairs, Assembly Lines, Maintenance Operations, Precision Fastening Technology: Pneumatic Technology, Electric Hybrid, Mechanical Drive, Digital Controls |
| Companies Covered | Atlas Copco AB, Ingersoll Rand, Desoutter Industrial Tools, Stanley Black & Decker, Chicago Pneumatic, Snap-on, Makita, Nitto Kohki, Dynabrade, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Screwdrivers Market Evolving Landscape
Digital controls represent the fastest-expanding technology segment as manufacturers retrofit lines with torque-data-logging capabilities. Pistol grip models dominate volume sales in automotive assembly due to ergonomic compatibility with overhead fastening positions.
Digital torque verification technology is collapsing the distinction between aerospace-grade and general industrial fastening specifications. The technology captures real-time torque curves and stores calibration certificates in cloud-accessible databases. Automotive assemblers in Germany's industrial corridor adopt these systems at accelerating pace, compressing the certification gap between premium and standard tool tiers.
REACH substance restrictions and RoHS compliance mandates in Europe tighten material specifications for pneumatic tool housings and internal components. Manufacturers reformulate polymer blends and surface coatings to eliminate restricted substances. Aerospace fastener suppliers face the steepest compliance burden, requalifying entire tool fleets to maintain EASA certification standing.
Buyer consolidation among tier-one automotive manufacturers concentrates procurement decisions into centralized fleet management offices. Long-term service contracts displace transactional tool purchases, binding vendors to uptime guarantees and preventive maintenance schedules. This pattern is most visible in Germany, where captive finance subsidiaries from major tool suppliers lock in multi-year agreements with Volkswagen Group and BMW assembly networks.
Air Screwdrivers Market Segmentation
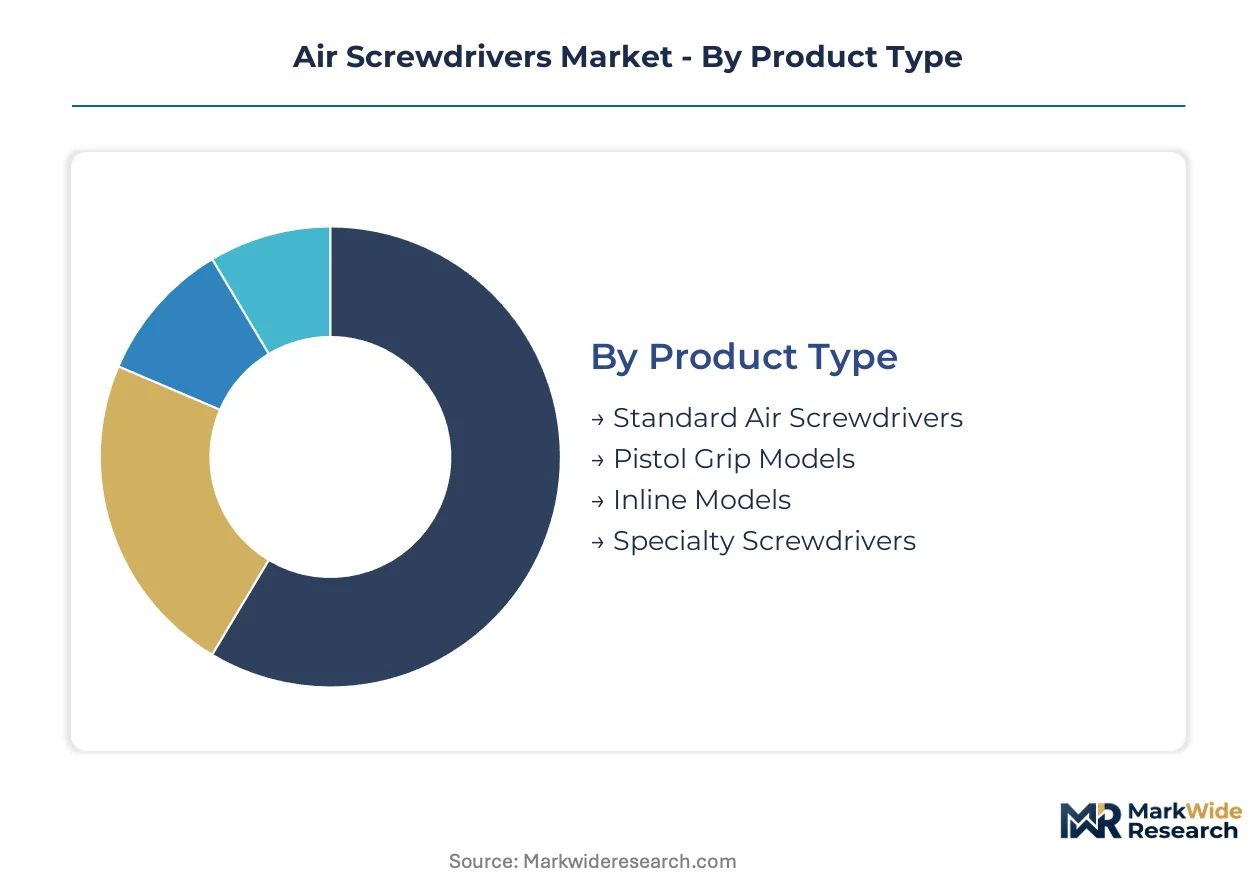
Air screwdriver segmentation reveals how torque precision requirements fragment demand across tool geometries, end-use certification tiers, and data-capture capabilities. Procurement patterns diverge sharply between high-volume automotive fleet contracts and low-volume aerospace calibration-intensive deployments.
Product Type:
Mature pistol configurations dominate installed base volumes while emerging digital-integrated form factors reshape replacement cycles.
- Pistol Grip Models:Ergonomic angled housings position the drive axis perpendicular to the handle, optimizing wrist alignment for overhead fastening in automotive body shops. Volkswagen Group and BMW assembly networks in Germany standardize on these configurations for line-worker fatigue reduction during 8-hour shift rotations.
- Inline Models:Straight-barrel designs extend drive collets axially from the grip, enabling access to confined spaces in aging European industrial facilities where overhead clearance falls below 30 centimeters. Maintenance providers in Germany's Ruhr manufacturing corridor sustain demand despite slower RPM throughput.
- Standard Air Screwdrivers:Conventional clutch-adjustable tools without specialized ergonomic features serve price-sensitive maintenance operations in general manufacturing.
- Specialty Screwdrivers:Application-specific designs including angle-head and telescoping configurations address niche aerospace fastening geometries.
Pistol grip configurations handle the majority of throughput; inline models are gaining share fastest in retrofit maintenance contracts.
End User:
Cost tier stratification separates capital-intensive fleet purchasers from intermittent-use maintenance contractors.
- Automotive Assembly:Tier-one manufacturers deploy torque-audited screwdriver fleets across synchronized production lines, binding suppliers to 99.5% uptime guarantees and preventive maintenance schedules. Germany's industrial corridor concentrates the most sophisticated procurement specifications.
- Aerospace:FAA airworthiness directives and EASA certification standards mandate documented calibration intervals and cloud-accessible torque curve databases, filtering suppliers without aerospace-grade quality systems.
- Manufacturing:General industrial facilities purchase standard clutch tools for non-critical fastening without torque-data-logging requirements.
- Construction:Intermittent-use contractors favor portable electric alternatives over pneumatic systems lacking compressor infrastructure.
Automotive assembly commands the largest fleet volumes; aerospace specifications are climbing fastest on certification stringency.
Application:
Volume concentration separates continuous-flow production environments from sporadic maintenance interventions.
- Assembly Lines:Synchronized fastening stations demand repeatable torque curves with statistical process control integration, driving digital control adoption in Germany's automotive sector.
- Precision Fastening:Torque-critical joints in aerospace structures require real-time curve verification and automatic shutoff at target values.
- Industrial Repairs:Breakdown maintenance operations prioritize tool availability over calibration documentation.
- Maintenance Operations:Scheduled preventive work in aging facilities sustains demand for inline configurations in space-constrained environments.
Assembly line deployments absorb the bulk of premium tool shipments; precision fastening applications are expanding most quickly on aerospace specification propagation.
Technology:
Margin structure diverges between mature pneumatic hardware and data-integrated digital systems commanding service attach rates.
- Digital Controls:Embedded torque sensors capture real-time fastening curves and transmit calibration certificates to manufacturing execution systems, collapsing the certification gap between aerospace and general industrial specifications.
- Pneumatic Technology:Conventional vane motors converting compressed air to rotary output remain the cost baseline for high-volume automotive fastening without data-capture requirements.
- Electric Hybrid:Battery-augmented designs eliminate compressor dependency for facilities lacking pneumatic distribution infrastructure.
- Mechanical Drive:Basic clutch mechanisms without electronic feedback serve price-sensitive intermittent users.
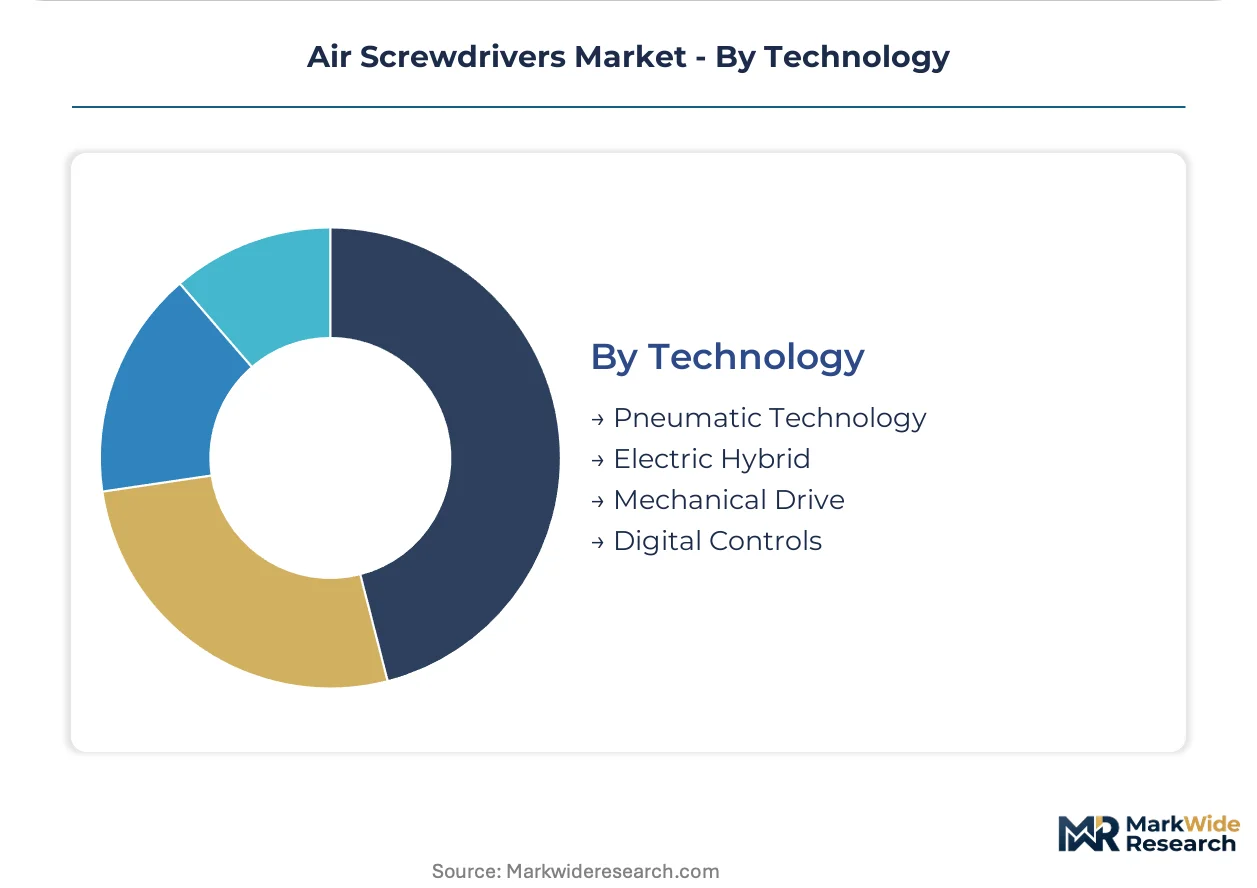
Pneumatic technology retains the largest installed base; digital controls are capturing replacement demand fastest on retrofit specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German assemblers extract 40% price premiums for torque-certified screwdriver fleets against Mexican maintenance contractors operating on spot procurement. This asymmetry reflects divergent certification burdens and fleet management sophistication across manufacturing corridors.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg mandate ISO 5393 torque verification for all assembly line tools, creating captive demand for precision fastening systems. The KBA enforces traceability standards that propagate from vehicle safety regulations into tool procurement specifications. Stuttgart's manufacturing cluster hosts Volkswagen Group and BMW fleet management offices binding suppliers to multi-year service contracts with uptime guarantees.
United States
Aerospace maintenance providers in the Pacific Northwest and Southeast absorb calibration-intensive screwdriver deployments driven by FAA airworthiness directives. OSHA lockout-tagout regulations filter non-compliant pneumatic tool suppliers from certified facility bids across automotive and general manufacturing sectors. Detroit's automotive corridor concentrates fleet purchasing decisions into centralized procurement offices demanding preventive maintenance schedules.
China
Domestic automotive assembly expansion in the Yangtze River Delta and Pearl River Delta drives demand for cost-optimized pneumatic tooling without full aerospace-grade certification. The MIIT promotes smart manufacturing initiatives that accelerate digital torque verification adoption among tier-one suppliers. Shanghai's industrial zone hosts retrofit programs integrating screwdriver data-logging with manufacturing execution systems.
Japan
Precision electronics and automotive assembly in the Chubu and Kansai regions sustain demand for compact inline screwdriver configurations in space-constrained production environments. METI industrial efficiency standards encourage torque-data integration for statistical process control. Nagoya's manufacturing belt concentrates high-volume fleet contracts with integrated tool service providers.
Mexico
Nearshoring automotive assembly in Nuevo León and the Bajío Region generates intermittent screwdriver demand from contract manufacturers without established pneumatic infrastructure. Mexican workplace safety regulations lack the certification stringency of US OSHA mandates, enabling price-sensitive procurement patterns. Querétaro's aerospace maintenance cluster represents an exception, importing US-calibrated tool fleets for MRO operations serving North American carriers.
Air Screwdrivers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying torque modules and clutch mechanisms. The vendor base concentrates among diversified industrial conglomerates with captive compressor and tooling divisions, alongside focused fastening specialists serving aerospace certification tiers. Three archetypes dominate: full-system bundlers leveraging backward integration into compressed air infrastructure; torque-audited specialists capturing aerospace-grade certification premiums; and diversified power tool manufacturers competing on volume scale. Consolidation pressure operates through fleet contract centralization among tier-one automotive buyers, while technology licensing agreements spread digital torque verification capabilities across tier-two assemblers.
Among European-based industrial conglomerates, Atlas Copco AB exemplifies the full-system bundler archetype through captive finance subsidiaries locking in long-term agreements. Ingersoll Rand occupies a parallel position representing compressed air infrastructure integration with screwdriver deployments. Desoutter Industrial Tools anchors the torque-audited specialist tier, exemplifying aerospace-grade certification positioning for precision fastening protocols. These three entities represent divergent strategic responses to procurement centralization among German automotive manufacturers.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand |
| Desoutter Industrial Tools |
| Stanley Black & Decker |
| Chicago Pneumatic |
| Snap-on |
| Makita |
| Nitto Kohki |
| Dynabrade |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's container cost dynamics amplify supply concentration effects for German automotive OEMs while compressing margins for Mexican maintenance contractors lacking pneumatic infrastructure. This logistics asymmetry translates into three-tier pricing structure across premium, standard, and economy levels based on certification burden and fleet management sophistication.
Pricing Analysis
Configured-to-order pricing spreads 40% above standard catalog pricing for torque-audited screwdriver fleets with ISO 5393 certification and cloud-accessible calibration databases. Contract-based long-term offtake dominates tier-one automotive procurement, with price differentiation driven by certification grade and after-sales service bundling. Cost compression in the standard tier intensifies because battery-powered substitutes eliminate compressor infrastructure requirements. Mexican maintenance contractors exhibit highest price sensitivity due to intermittent demand patterns, while German OEMs accept premium positioning for uptime guarantees.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for pneumatic component sourcing. Manufacturing concentrates in Germany, China, and Japan, with vane motor assemblies and precision clutch mechanisms drawing from specialized machine tool suppliers. Single-source vulnerability persists for aerospace-grade torque sensor modules. Distribution runs through captive finance subsidiaries and integrated service providers rather than transactional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
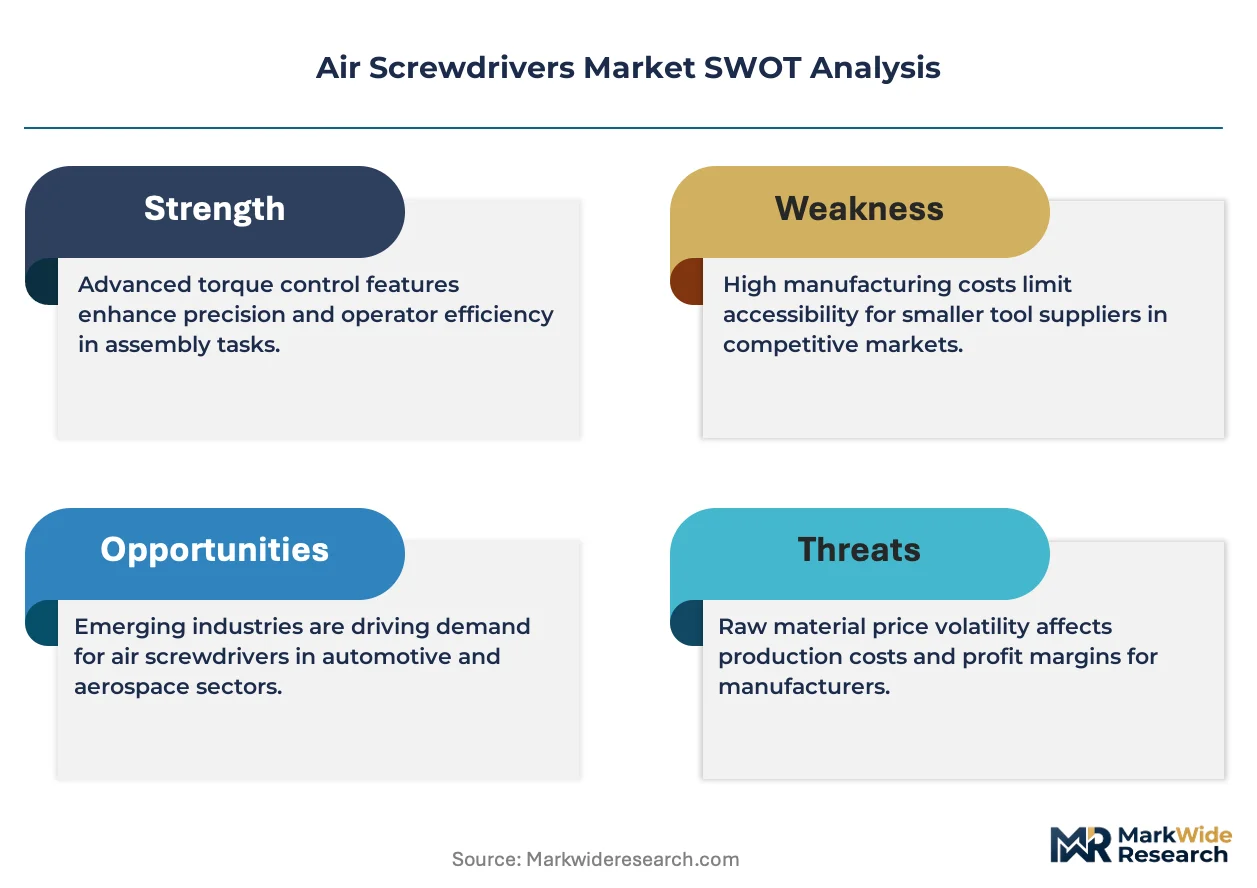
Service-attach revenue layers expand faster than hardware sales as fleet management contracts absorb calibration, maintenance, and data-analytics subscriptions. Torque-data-logging retrofits and preventive maintenance scheduling represent the fastest-expanding recurring-revenue streams.
For Market Incumbents: Harden position through backward integration into compressor systems that bundle screwdriver deployments and lock in long-term agreements. Battery-powered tool substitution from diversified power tool manufacturers threatens pneumatic market share in facilities lacking compressed air infrastructure. Certification investment in FAA and EASA torque verification protocols defends aerospace-grade margins against general industrial commoditization.
For New Entrants and Emerging Players: Mid-market automotive suppliers in Mexico's Bajío Region represent the most penetrable entry point for tool-as-a-service financing models previously excluded from outright purchase. Chinese tier-one suppliers accelerating digital torque verification adoption under MIIT smart manufacturing initiatives offer second white-space target. Go-to-market angle centers on equipment leasing that fragments capital-intensive procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core fastening tool divisions lacking captive finance capabilities. Long-term viability hinges on service-attach rate expansion and fleet contract centralization among automotive OEMs. Signal to watch is propagation of digital torque verification requirements from aerospace into general manufacturing specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Systems | Atlas Copco AB and Ingersoll Rand leverage captive air infrastructure to bundle screwdriver deployments and lock in multi-year fleet contracts. |
| Digital Torque Verification Platform Launch | Real-time fastening curve capture collapses certification gaps between aerospace and automotive specifications, accelerating retrofit demand. |
| Tool-as-a-Service Channel Expansion | Equipment leasing fragments capital-intensive pneumatic tooling procurement, enabling penetration among mid-tier manufacturers. |
| Aerospace Certification Investment | FAA airworthiness directive compliance and EASA traceability standards filter non-compliant suppliers from premium tier bids. |
| Inline Model Niche Development | Confined-space maintenance operations in aging European facilities sustain demand where clearance constraints eliminate pistol alternatives. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across maintenance directors at automotive assembly plants, OEM procurement teams, aftermarket service heads, and plant engineers managing pneumatic tool fleets. Secondary validation drew from OSHA regulatory filings, FAA airworthiness directives, ISO 5393 certification databases, and customs trade data for pneumatic tool imports. Bottom-up triangulation across screwdriver unit deployments and top-down reconciliation against manufacturing execution system integration spending anchored value estimates.
Calibration against historical adoption curves for digital torque verification technology shaped projections across the analysis window. Segmentation dimensions modeled include product geometry, end-use certification tier, application volume concentration, and data-capture technology. CAGRs derived from weighted average of equipment replacement cycles and retrofit penetration rates. Industry-specific inputs encompassed automotive fleet contract durations and aerospace calibration interval mandates.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles and automotive production volumes would shift the trajectory. Forecasts reflect documented assumptions regarding OSHA enforcement stringency and EASA certification propagation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Electric Tools Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Digital Tool Presetter Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Plasma Arc Cutting Market
Industrial Tools
Tool Holder Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Micro Welders Market
Industrial Tools
Jigs and Other Tools Market