
 Cookies Market | 2026-2036
Cookies Market Size, Share, and Industry Trends Forecast 2026-2036
Cookies Market Analysis
Bakery technician shortages across industrial cookie lines is unwinding capacity expansion plans in several manufacturing hubs. Mondelez International sustains global scale through dedicated chocolate chip production infrastructure. Britannia Industries Limited anchors its position in South Asian markets with localized flavor development. Nestlé S.A. competes through direct-to-retail channel control in European convenience networks.
Cookies are baked flour-based confections typically containing fat, sugar, and eggs, with moisture content ranging from two to eight percent depending on formulation and bake profile; they serve as shelf-stable packaged snacks for retail and foodservice channels. Chocolate chip formulations occupy the largest volume share among product types, while gluten-free ingredient categories are expanding fastest as celiac awareness rises. Supermarkets dominate distribution channel value capture, though online retail is gaining traction among health-conscious demographics seeking subscription-based specialty assortments.
The FDA governs nutrition labeling and added-sugar disclosure requirements in the United States, while EFSA oversees novel ingredient approvals and health claims across European markets, with both frameworks pushing reformulation toward reduced-sodium and clean-label profiles. India's FSSAI enforces fortification standards and limits on artificial additives that affect import eligibility for multinational suppliers. Stakeholders must monitor evolving front-of-pack labeling rules and decide whether to regionalize production or absorb cross-border compliance costs.
Market Dynamics
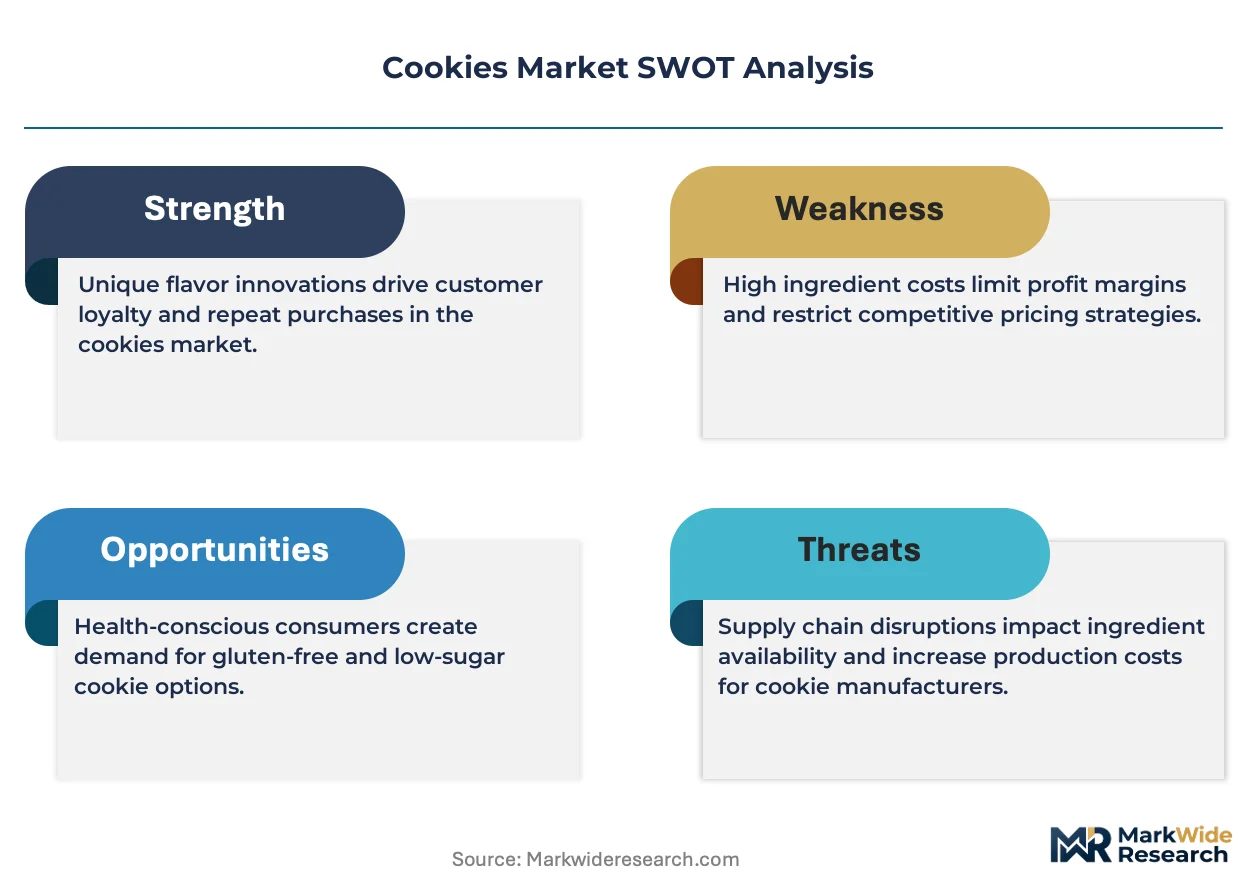
Clean-label reformulation mandates from the FDA and EFSA are forcing industrial-scale ingredient substitution across chocolate chip and sandwich cookie portfolios, compressing margins while opening premium positioning for compliant suppliers.
Growth Catalysts
- Convenience-driven snacking:Urban consumers in India and Germany prioritize shelf-stable, portion-controlled formats that align with on-the-go consumption patterns and single-serve retail packaging.
- FSSAI fortification standards:India's micronutrient enrichment requirements for packaged foods create mandatory upgrade cycles that favor domestic manufacturers with localized R&D infrastructure.
- Enzymatic flour treatment:Novel enzyme systems reduce bake times and energy consumption, enabling capacity expansion without proportional capital outlay for new oven lines.
Market Restraints
- Cocoa butter price volatility:Chocolate chip formulations depend on cocoa butter futures that swing with West African harvest conditions, squeezing margin predictability for mid-tier producers.
- Industrial bakery technician scarcity:Specialized skills for automated cookie line calibration concentrate in Germany and the Netherlands, limiting expansion feasibility in emerging manufacturing hubs.
- EFSA novel ingredient timelines:Approval pathways for alternative sweeteners and fiber additives extend 18-24 months, delaying reformulation launches behind competitor first-movers.
Strategic Opportunities
- Subscription-based specialty assortments:Direct-to-consumer channels in the United States capture health-conscious households seeking allergen-free and low-glycemic assortments with recurring delivery.
- Gluten-free ingredient convergence:Blends of rice flour, tapioca starch, and binding hydrocolloids open formulation space previously dominated by wheat-dependent incumbents.
- FDA added-sugar disclosure:Front-of-pack labeling requirements create competitive differentiation for brands achieving sub-threshold sugar content without sensory compromise.
Industry Challenges
- Automated line integration:Legacy semi-automatic equipment in South Asian facilities requires phased retrofitting to match throughput of European continuous-bake systems without production halts.
- Clean-label certification complexity:Multiple third-party non-GMO and organic standards demand parallel audit trails, fragmenting quality assurance resources across overlapping claim portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cookies Market |
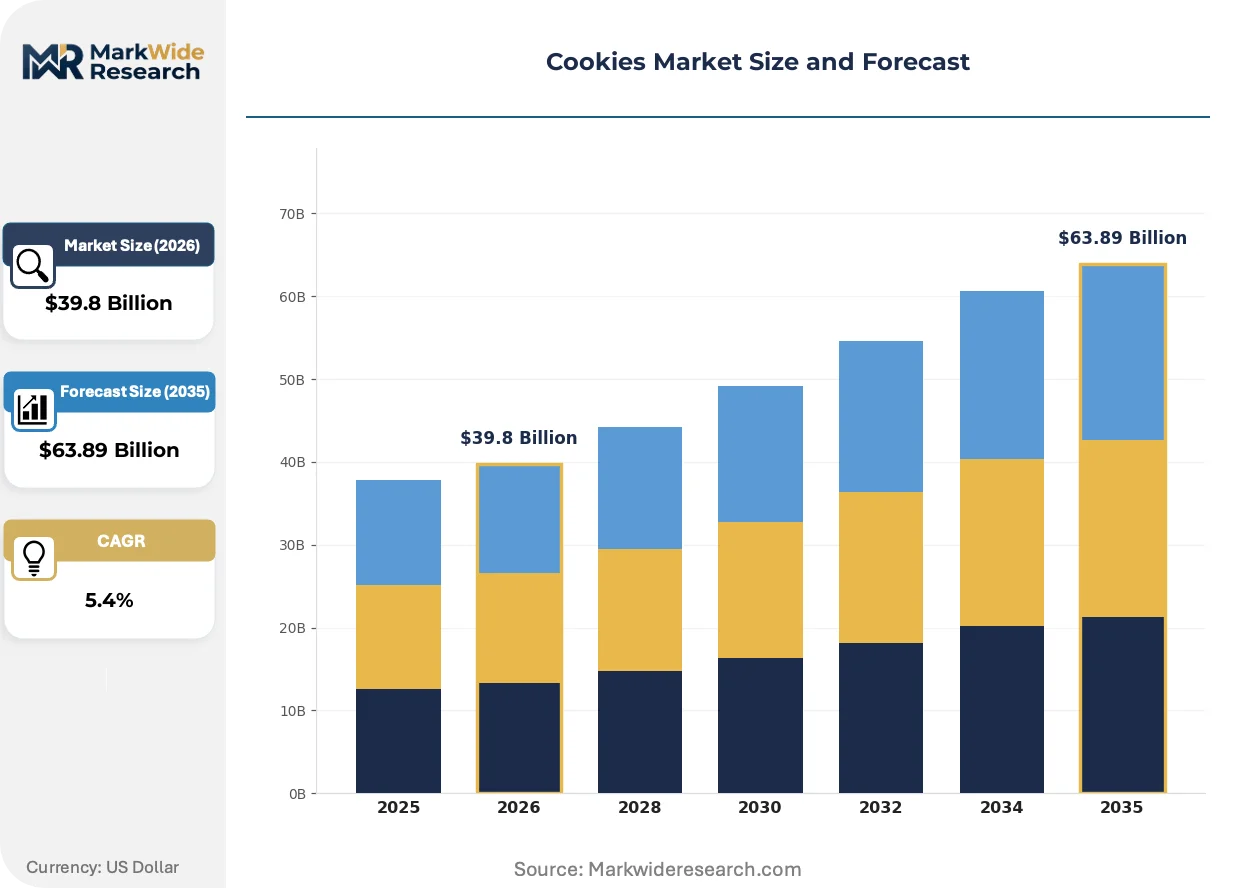
| Market Size in 2026 | $39.8 Billion |
| Market Size in 2035 | $63.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
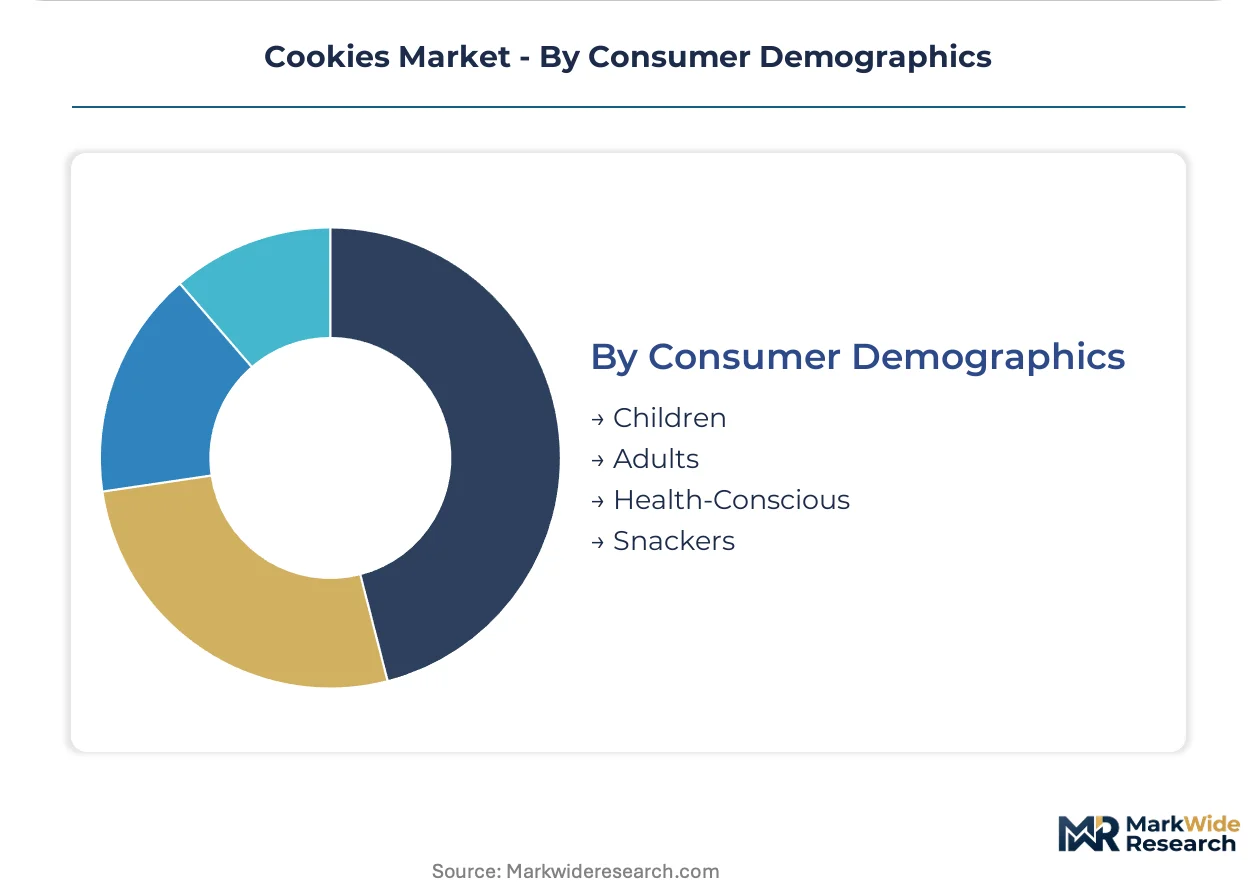
| Segmentation | Product Type: Chocolate Chip, Oatmeal Raisin, Peanut Butter, Sugar Cookies Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops Ingredient Type: Gluten-Free, Organic, Sugar-Free, Vegan Consumer Demographics: Children, Adults, Health-Conscious, Snackers |
| Companies Covered | Mondelez International, Inc., Nestlé S.A., PepsiCo, Inc., Campbell Soup Company, Grupo Bimbo, Britannia Industries Limited, Kellogg Company, Ferrero Group, General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cookies Market Emerging Trajectories
Reformulation science and digital manufacturing controls are compressing product development cycles while regulatory transparency mandates reshape competitive positioning around ingredient disclosure.
Oven humidity sensing systems coupled with AI-driven bake profile adjustment are displacing fixed-parameter thermal processing. Premium manufacturers in Germany deploy these systems to reduce reject rates and achieve consistent moisture targets across high-speed lines. The technology is displacing manual operator intervention and post-bake quality sorting, compressing labor costs while tightening specification windows.
EFSA's evolving stance on health claims for fiber-enriched products is tightening evidentiary requirements for digestive wellness marketing. Cookie manufacturers must now commission clinical substantiation or retreat to generic nutritional positioning. European brands with established fiber cookie portfolios face the steepest compliance recalibration, while US exporters encounter border friction from divergent FDA-EFSA claim frameworks.
Health-conscious demographics in the United States are rotating procurement toward subscription-based specialty assortments that bundle allergen-free, low-sugar, and functional ingredient variants. This channel disintermediates conventional supermarket slotting fees and builds direct customer data assets. The shift concentrates initially in coastal metropolitan markets before diffusing to secondary cities through influencer-driven trial.
Cookies Market Segmentation
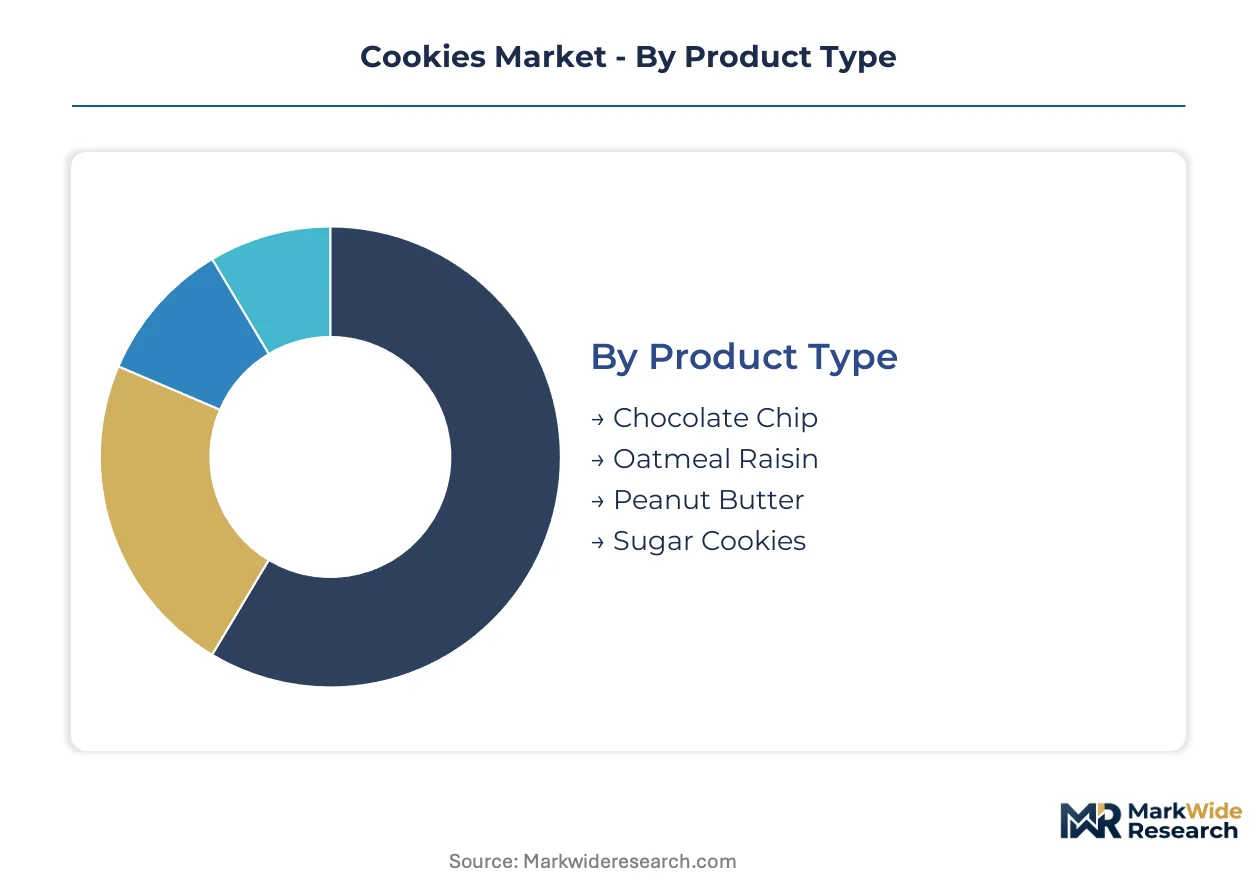
Segmentation in the cookies market reveals how reformulation pressures and channel fragmentation are redrawing competitive boundaries. Manufacturers must align R&D investment with ingredient certification tiers while calibrating distribution presence across convenience and digital touchpoints.
Product Type:
Margin pools concentrate in chocolate chip formulations where cocoa butter input costs create pricing power for scale operators, while oatmeal raisin and alternative formats serve niche health-positioning strategies.
- Chocolate Chip:Wheat-flour base with cocoa butter and chocolate inclusions, moisture content calibrated between 3-6 percent for shelf stability. Demand concentrates in the United States and Germany where portion-controlled single-serve packs dominate convenience channel resets; Mondelez International maintains dedicated production infrastructure to defend this position.
- Oatmeal Raisin:Rolled oat and dried fruit composition delivering higher fiber content and chewier texture profile. Health-conscious demographics in coastal US metropolitan markets rotate procurement toward this segment as FDA added-sugar disclosure rules tighten; subscription-based specialty assortments favor oatmeal raisin for clean-label positioning.
- Peanut Butter:Ground legume paste binding with standard cookie dough bases, protein content elevated versus conventional formulations. Allergen labeling requirements from FDA and EFSA compress margin predictability for mid-tier producers.
- Sugar Cookies:High-sucrose formulations with minimal fat interference, achieving crisp fracture mechanics through extended bake profiles. India's FSSAI fortification standards are forcing micronutrient enrichment upgrades in this traditionally commodity segment.
Chocolate Chip holds installed capacity. Oatmeal Raisin is rotating up the share rankings.
Distribution Channel:
Channel economics diverge sharply between slotting-fee-heavy supermarket networks and digitally native subscription models that bypass traditional retail gatekeepers.
- Supermarkets:Dominant value capture through controlled-temperature aisle placement and promotional calendar coordination. Germany and the United States concentrate volume here; Britannia Industries Limited leverages localized flavor development to secure shelf space in Indian supermarket chains.
- Online Retail:Direct-to-consumer fulfillment enabling allergen-free and low-glycemic assortment bundling with recurring delivery infrastructure. Health-conscious households in US coastal cities drive initial concentration before influencer diffusion to secondary markets.
- Convenience Stores:Impulse-purchase positioning with single-serve and grab-and-go packaging formats. Urban consumers in India prioritize on-the-go consumption patterns through this channel.
- Specialty Shops:Curated premium assortments with transparent ingredient sourcing and small-batch production claims. Clean-label certification complexity fragments quality assurance resources across parallel audit trails here.
Supermarkets anchor volume throughput. Online Retail is climbing the fastest.
Ingredient Type:
Certification premiums and reformulation compliance costs are stratifying margin structures across conventional and specialty ingredient tiers.
- Gluten-Free:Rice flour, tapioca starch, and binding hydrocolloid blends substituting for wheat-dependent formulations. Celiac awareness rises across the United States and Germany; enzymatic flour treatment reduces bake times for gluten-free lines without proportional capital outlay.
- Organic:USDA or EU organic certified inputs with prohibited synthetic pesticide and fertilizer restrictions. Multiple third-party standards demand parallel audit trails that fragment quality assurance resources.
- Sugar-Free:Alternative sweetener systems including polyols and high-intensity sweeteners. EFSA novel ingredient timelines extend 18-24 months, delaying reformulation launches.
- Vegan:Plant-based fat and protein replacements eliminating egg and dairy inputs. Clean-label reformulation mandates from FDA and EFSA force industrial-scale ingredient substitution across this portfolio.
Gluten-Free holds installed capacity. Vegan is gaining share fastest.
Consumer Demographics:
Usage occasion and nutritional priority segmentation determines packaging format and fortification strategy across life-stage cohorts.
- Children:Portion-controlled formats with micronutrient fortification aligned to growth-stage nutritional requirements. India's FSSAI fortification standards create mandatory upgrade cycles favoring domestic manufacturers with localized R&D infrastructure.
- Adults:Convenience-driven snacking with shelf-stable, single-serve packaging for workplace and commute consumption. Urban consumers in Germany prioritize on-the-go formats.
- Health-Conscious:Allergen-free, low-glycemic, and functional ingredient variants with transparent supply chain disclosure. This demographic rotates procurement toward subscription-based specialty assortments in the United States.
- Snackers:Impulse-driven purchase patterns with minimal nutritional scrutiny and price sensitivity. Convenience stores and supermarkets capture this volume across all analyzed geographies.
Snackers hold installed capacity. Health-Conscious is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling mandates anchor the United States as the dominant geography, with EFSA novel ingredient pathways and India's FSSAI fortification standards creating parallel compliance frameworks that reshape regional production strategies.
United States
Subscription-based specialty assortments and health-conscious household procurement drive demand concentration in coastal metropolitan markets. FDA added-sugar disclosure requirements compress reformulation timelines for chocolate chip and sandwich cookie portfolios. Chicago and the Midwest industrial corridor host automated cookie line infrastructure where oven humidity sensing systems displace fixed-parameter thermal processing.
Germany
Urban consumers prioritize on-the-go consumption patterns with portion-controlled single-serve packaging formats. EFSA oversight of novel ingredient approvals and health claims extends 18-24 month timelines for alternative sweetener integration. The North Rhine-Westphalia manufacturing belt concentrates industrial bakery technician skills for automated line calibration.
India
Convenience store impulse purchasing and workplace snacking occasions expand shelf-stable cookie demand in Mumbai, Delhi, and Bangalore. FSSAI fortification standards mandate micronutrient enrichment cycles that favor domestic manufacturers with localized R&D infrastructure. Britannia Industries Limited anchors South Asian market position through flavor development tailored to regional palate preferences.
United Kingdom
Supermarket promotional calendars and controlled-temperature aisle placement sustain volume throughput in London and the Southeast retail corridor. Divergent FDA-EFSA claim frameworks create border friction for US exporters seeking health positioning authorization. The Midlands manufacturing cluster processes gluten-free ingredient blends for specialty channel distribution.
Brazil
Snack-driven consumption patterns with minimal nutritional scrutiny support commodity cookie segments in São Paulo and Rio de Janeiro retail networks. Import eligibility standards for artificial additive limits affect multinational supplier market access. The Southeast industrial region hosts legacy semi-automatic equipment requiring phased retrofitting to match European continuous-bake throughput.
Cookies Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated scale operators controlling chocolate chip production infrastructure while regional specialists defend localized flavor portfolios. The structure stratifies across multinational conglomerates with dedicated baking divisions, domestic champions with fortified distribution networks, and emerging challengers targeting allergen-free subscription channels. Strategic moves concentrate on backward integration into cocoa butter supply chains and enzymatic flour treatment licensing to compress bake times without proportional capital outlay.
Within the integrated multinational tier, Mondelez International, Inc. and Nestlé S.A. occupy positions exemplifying global scale defense through dedicated production infrastructure and direct-to-retail channel control. Britannia Industries Limited represents the domestic champion archetype, anchoring South Asian market presence through localized R&D capabilities aligned to FSSAI compliance requirements.
| Leading Market Players |
|---|
| Mondelez International, Inc. |
| Nestlé S.A. |
| PepsiCo, Inc. |
| Campbell Soup Company |
| Grupo Bimbo |
| Britannia Industries Limited |
| Kellogg Company |
| Ferrero Group |
| General Mills, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term cocoa butter offtake contracts lock in supply access and price visibility for chocolate chip manufacturers, insulating scale operators from West African harvest volatility while compressing margin predictability for spot-market-dependent mid-tier producers in the United States and Germany.
Pricing Analysis
Geographic price spreads between German industrial bakeries and Indian convenience channels reflect divergent input cost structures and certification premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by clean-label certification and fortification compliance, with FDA added-sugar disclosure rules intensifying cost compression in the standard tier. Health-conscious households in US coastal markets exhibit lowest price sensitivity, while Indian snackers through convenience stores drive volume at tightest margins.
Supply Chain Analysis
Just-in-time flour and sugar procurement dominates in Germany and the United States, whereas Indian manufacturers maintain strategic stockpiles of micronutrient premixes to buffer FSSAI fortification mandate compliance. Supply concentrates in Germany for industrial bakery technician skills, in West Africa for cocoa butter, and in India for localized flavor R&D. Cocoa butter futures volatility and single-source enzyme system dependencies create structural exposure. Distribution runs through supermarket slotting-fee networks in developed markets and direct-to-consumer subscription channels for allergen-free assortments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial-scale cookie production hinges on scarce automated line calibration expertise concentrated in Germany and the Netherlands, creating defendable moats for incumbents while raising entry barriers for emerging manufacturers in South Asia and Brazil.
For Market Incumbents: Fortify backward integration into cocoa butter supply chains and enzymatic flour treatment licensing to compress bake times without proportional capital outlay. Defend chocolate chip volume share through dedicated production infrastructure against gluten-free ingredient convergence threats. Prioritize certification investment in parallel organic and non-GMO audit trails to capture clean-label premiums. For New Entrants and Emerging Players: Subscription-based specialty assortment fulfillment represents a service-layer gap where incumbents under-serve health-conscious US households seeking allergen-free bundling. Target direct-to-consumer channels in coastal metropolitan markets before influencer diffusion to secondary cities. Deploy low-glycemic formulation expertise as the primary go-to-market angle. For Investors and Strategic Acquirers: Domestic champions with localized FSSAI compliance infrastructure and fortified distribution networks in India present attractive acquisition profiles. Long-term viability favors operators controlling both reformulation science and direct retail channel access. Watch EFSA novel ingredient approval timelines as the inflection indicator for alternative sweetener portfolio viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cocoa Butter Supply | Captive supply of West African cocoa butter insulates margin predictability from harvest volatility. |
| Enzymatic Flour Treatment Licensing | Novel enzyme systems reduce bake times and energy consumption without oven line capital expansion. |
| Direct-to-Consumer Channel Launch | Subscription-based specialty assortments bypass supermarket slotting fees and build proprietary customer data assets. |
| Clean-Label Certification Investment | Parallel USDA organic and non-GMO audit trails capture premium positioning in specialty shop channels. |
| Localized Flavor R&D Expansion | FSSAI-aligned fortification capabilities in India defend market share against multinational import eligibility restrictions. |
Methodological Framework
Desk research of FDA and EFSA regulatory filings, FSSAI fortification standards, and cocoa butter futures market data preceded structured interviews with industrial bakery plant managers, supermarket category buyers, supply chain planners at multinational confectioners, and R&D directors at enzymatic ingredient suppliers. Secondary validation drew from trade customs records, Nielsen retail audit data, and SEC 10-K disclosures from listed food manufacturers. Bottom-up volume modeling triangulated against top-down category spend estimates.
Variance decomposition across product type, distribution channel, ingredient certification tier, and consumer demographic segments shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Modeled inputs included FDA added-sugar disclosure compliance timelines and EFSA novel ingredient approval pathway durations.
Forecasts assume regulatory continuity in FDA nutrition labeling, EFSA health claim evidentiary requirements, and FSSAI fortification mandates; material policy shifts would require re-modeling. Cocoa butter price volatility and industrial technician migration patterns represent specific risk factors. Revision becomes warranted when clean-label certification adoption crosses mass-market penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread Slicer Blades Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
Pastry Premixes Market
Bakery Products
South America Ice Cream Market
Bakery Products
Teaseed Cake Market
Bakery Products
South America Bakery Products Market
Bakery Products
Specialty Bakery Market
Bakery Products
Laminated Dough Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Low Fat Chocolate Cake Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
North America Bakery Products Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Low-Calorie Toast Market