
 Industrial Starch Market | 2026-2036
Industrial Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Starch Market Intelligence
The EU Green Deal is recalibrating procurement priorities across European paper and packaging converters, pushing industrial starch formulations toward lower-carbon feedstocks and verified sustainability credentials. Cargill Incorporated leverages its North American corn processing infrastructure to supply modified starch grades at scale to multinational adhesive and corrugated board customers. Roquette Frères anchors European supply through its pea and potato starch expertise, competing on non-GMO and allergen-free positioning in food and pharmaceutical applications.
Industrial starch comprises carbohydrates extracted from corn, wheat, potato, tapioca, and pea sources, then processed through wet milling, drying, and chemical or physical modification to achieve specific viscosity, gelatinization temperature, and film-forming properties for binding, thickening, and sizing operations. Modified starch commands the dominant value share because customization for paper surface sizing and textile warp sizing commands consistent premium positioning over commodity native grades. Native starch retains volume leadership in food processing where cost-sensitive manufacturers favor unmodified functionality, while resistant starch and dextrin segments are gaining structural momentum from gut-health positioning and soluble fiber fortification trends.
REACH registration requirements govern chemical modifications and cross-linking agents used in European starch derivatives, compelling reformulation investments and supply chain documentation upgrades. FDA food additive regulations and GRAS self-affirmation pathways shape US market access for novel starch variants targeting clean-label claims. Stakeholders must monitor evolving EFSA guidance on resistant starch dietary fiber classifications and emerging state-level packaging extended producer responsibility laws that could redirect volume toward compostable adhesive and bioplastic applications.
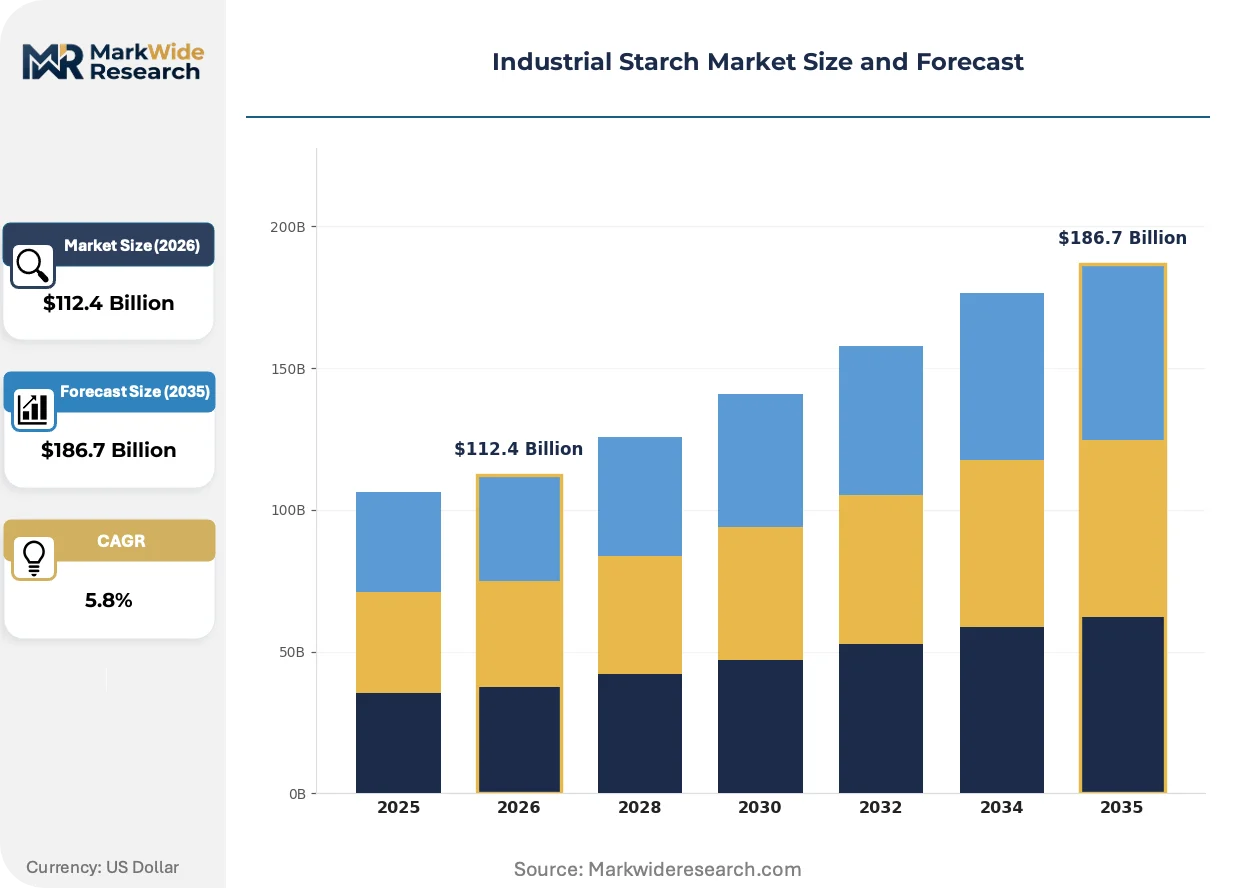
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing the carbon footprint of paper and packaging converters, forcing rapid feedstock transitions toward bio-based binders and verified low-carbon starch derivatives.
Growth Catalysts
- Clean-label formulation mandates:Food processors across Germany and France are absorbing larger volumes of modified and resistant starch variants as packaged goods manufacturers eliminate synthetic additives from ingredient decks.
- REACH registration pathways:Chemical modification documentation upgrades are compelling supply chain transparency investments that favor established European starch derivative networks with existing compliance infrastructure.
- Paperboard cluster concentration:Hamburg and Rhine-Ruhr corrugated packaging hubs are sourcing heavily from regional pea and potato starch production networks, anchoring demand for non-GMO and allergen-free grades.
Market Restraints
- Feedstock cost volatility:Corn and wheat input prices fluctuate with agricultural commodity cycles, squeezing margin stability for native starch producers serving cost-sensitive food manufacturing segments.
- Supply concentration in Rhine-Ruhr:Heavy reliance on Emsland Group and Roquette Frères production networks creates geographic vulnerability to logistics disruptions or regional energy price spikes.
- Technical substitution pressure:Synthetic polymer adhesives retain performance advantages in high-moisture packaging applications where starch-based alternatives exhibit inferior bond durability.
Strategic Opportunities
- Compostable packaging mandates:Emerging extended producer responsibility laws in German states are redirecting adhesive volume toward biodegradable starch formulations for corrugated board sealing.
- Resistant starch fiber fortification:EFSA guidance evolution on dietary fiber classifications is opening pharmaceutical and nutraceutical applications for gut-health positioned dextrin variants.
- Pea starch technology convergence:Wet milling process innovations combined with protein extraction co-product economics are expanding viable feedstock options beyond traditional corn and potato bases.
Industry Challenges
- Reformulation capex intensity:Cross-linking agent substitution and process line modifications to meet REACH chemical modification standards require substantial capital deployment with multi-year payback horizons.
- GRAS self-affirmation complexity:Novel starch variants targeting US clean-label claims face extended FDA food additive review timelines that delay market entry against established competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Starch Market |
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Starch, Modified Starch, Resistant Starch, Dextrin Application: Paper Manufacturing, Textile Processing, Adhesive Production, Food Processing, Bioplastics End User Industry: Packaging Manufacturers, Cosmetics Producers, Pharmaceutical Companies, Animal Feed Producers Form: Powder, Granules, Paste, Liquid |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Roquette Frères, AGRANA Beteiligungs-AG, Grain Processing Corporation, Tereos Group, Emsland Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Starch Market Strategic Shifts & Innovations
Active reformulation of industrial starch derivatives is compressing the gap between commodity native grades and premium modified variants as regulatory pressure and end-use performance requirements converge.
Resistant starch extraction technology is expanding into pharmaceutical and functional food applications beyond traditional thickening roles. Nutraceutical manufacturers in Germany and France are adopting these variants at accelerated pace for prebiotic fiber fortification. This expansion is enabling new revenue streams that offset commodity margin compression in conventional food processing segments.
REACH chemical modification documentation requirements are recalibrating European supply chain transparency standards. Wet milling operations must now maintain granular cross-linking agent traceability from feedstock through finished derivative. Paper surface sizing and textile warp sizing segments are responding by consolidating procurement relationships with vertically integrated processors possessing in-house regulatory compliance capabilities.
Buyer concentration among multinational corrugated board and adhesive manufacturers is compressing switching cycles and intensifying price negotiation leverage. Direct procurement relationships with starch processors are displacing traditional distributor intermediaries in the Hamburg and Rhine-Ruhr packaging clusters. This channel consolidation is most visible in Germany, where paperboard converters are demanding volume-based sustainability certifications and verified carbon footprint data as standard contract terms.
Industrial Starch Market Segmentation
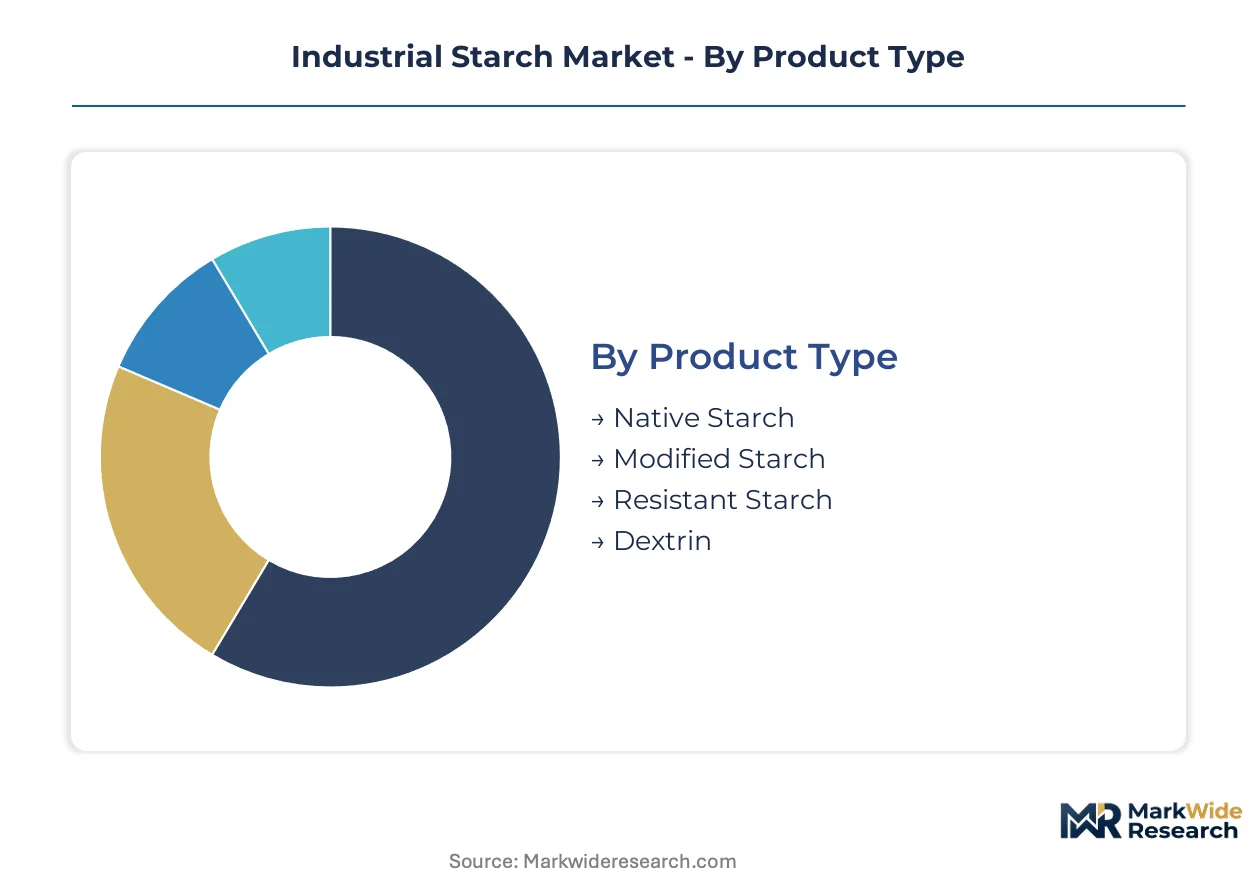
Industrial starch procurement patterns diverge sharply between cost-driven commodity buyers and performance-focused premium segments. Understanding these splits enables suppliers to align wet milling investments and modification capabilities with distinct margin profiles across paper, food, and pharmaceutical channels.
Product Type:
Modified starch commands premium positioning through chemical customization for film-forming and viscosity specifications, while native starch dominates volume flows to price-sensitive food manufacturers.
- Modified Starch:Cross-linked and esterified derivatives achieve controlled gelatinization temperatures for paper surface sizing and textile warp sizing. Hamburg and Rhine-Ruhr corrugated packaging clusters source heavily from regional processors demanding verified carbon footprint data as standard contract terms.
- Native Starch:Unmodified carbohydrates extracted through wet milling retain cost advantages for thickening applications. Food processors across Germany absorb larger volumes as clean-label mandates eliminate synthetic additives from packaged goods ingredient decks.
- Resistant Starch:Enzyme-modified or heat-treated variants resist small intestine digestion, enabling prebiotic fiber fortification in nutraceutical applications.
- Dextrin:Partially hydrolyzed starch polymers serve adhesive binders and encapsulation matrices for pharmaceutical coatings.
Mature deployment sits with native starch in conventional food processing. Newer deployment is concentrated in resistant starch variants for gut-health positioning.
Application:
Paper manufacturing absorbs the largest volume flows, while bioplastics represents the steepest expansion trajectory as EU Green Deal mandates compress packaging carbon footprints.
- Paper Manufacturing:Surface sizing and corrugated board adhesive operations consume modified starch grades for bond strength and printability. Emsland Group and Roquette Frères production networks anchor supply to Hamburg packaging clusters facing F-Gas Regulation compliance pressures.
- Food Processing:Clean-label formulation mandates across Germany and France drive resistant starch absorption for fiber fortification without synthetic additive declarations.
- Textile Processing:Warp sizing applications require specific viscosity profiles to protect yarn integrity during high-speed weaving operations.
- Adhesive Production:Corrugated board sealing and paperboard lamination utilize starch-based binders as synthetic polymer substitution accelerates under extended producer responsibility laws.
- Bioplastics:Thermoplastic starch compounds serve compostable packaging films and injection-molded disposables targeting single-use plastic bans.
Volume concentration remains in paper manufacturing. Margin expansion is concentrating in bioplastics as certification requirements filter out commodity suppliers.
End User Industry:
Packaging manufacturers drive bulk procurement with sustainability verification demands, while pharmaceutical companies pay steep premiums for allergen-free and non-GMO documentation.
- Packaging Manufacturers:Corrugated board and paperboard converters in the Rhine-Ruhr region consolidate direct procurement relationships, displacing distributor intermediaries. REACH chemical modification documentation requirements favor vertically integrated processors with in-house compliance capabilities.
- Pharmaceutical Companies:Excipient and coating applications demand pea and potato starch variants for allergen-free positioning. EFSA guidance evolution on dietary fiber classifications opens additional prebiotic formulation opportunities.
- Cosmetics Producers:Powder and liquid starch derivatives serve as natural texturizers and film-formers in clean beauty formulations.
- Animal Feed Producers:Native starch provides carbohydrate energy density in compound feed rations for livestock operations.
Procurement sophistication is highest among pharmaceutical companies. Feed producers remain most sensitive to agricultural commodity price cycles.
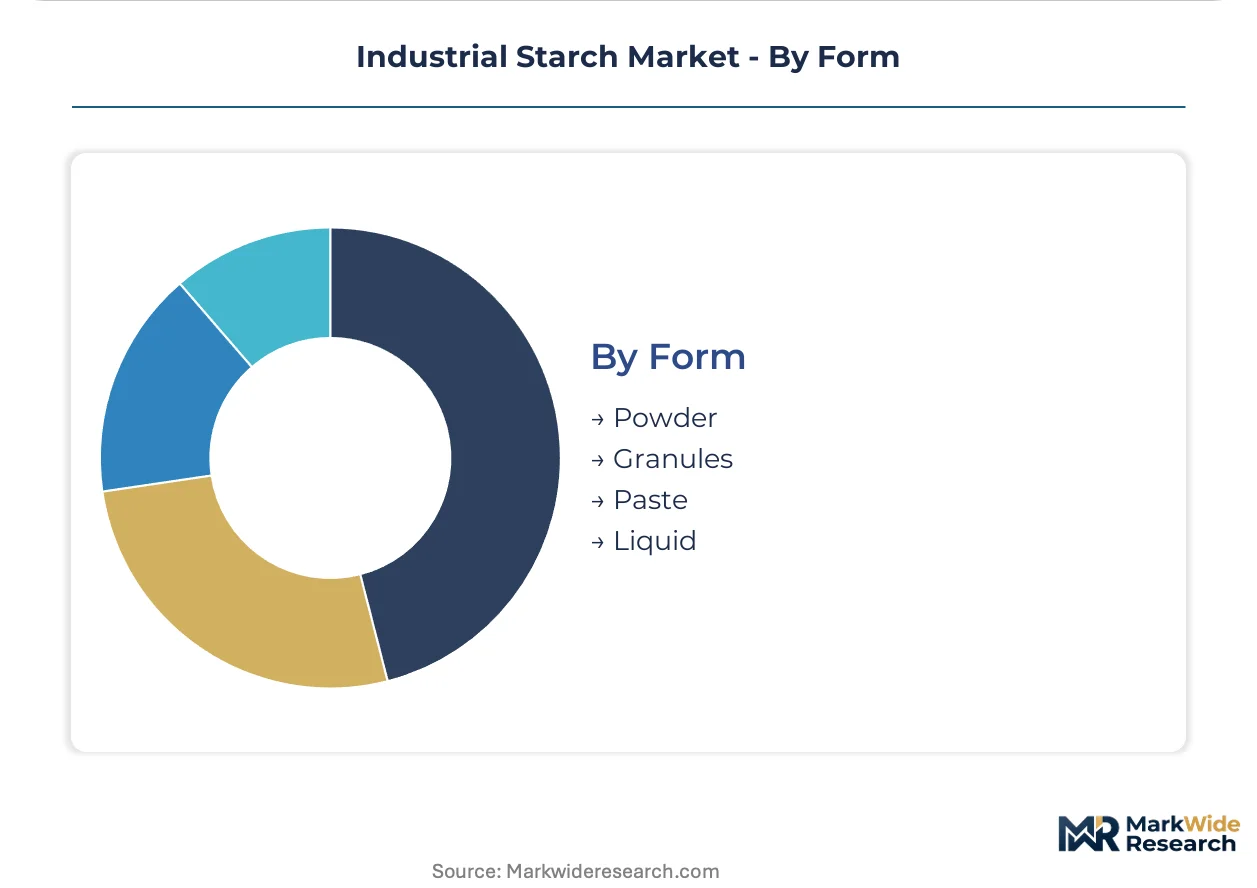
Form:
Powder dominates bulk industrial handling, while liquid formulations capture adhesive and coating applications requiring ready-to-use viscosity.
- Powder:Spray-dried starch derivatives enable extended shelf stability and precise dosing in dry-blend food and feed formulations. Paper surface sizing operations prefer powder for controlled slurry preparation.
- Liquid:Pre-gelatinized starch suspensions eliminate cooking steps in adhesive production and textile warp sizing, reducing energy costs for high-volume converters.
- Granules:Intermediate particle sizes balance dissolution speed with dust control in pharmaceutical tableting and cosmetic compounding.
- Paste:High-solids preparations serve immediate-use applications in manual adhesive application and specialty textile finishing.
Processing efficiency favors powder in large-scale manufacturing. Liquid deployment is expanding in continuous production lines seeking energy reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in agricultural heartlands while consumption concentrates in coastal manufacturing belts. Corn and potato processing infrastructure dominates supply geography. Paper packaging and food processing clusters drive demand distribution.
Germany
Corrugated board manufacturers in Hamburg and the Rhine-Ruhr region absorb modified starch volumes for surface sizing and adhesive applications. REACH chemical modification documentation requirements favor established processors with in-house compliance infrastructure. Emsland Group and Roquette Frères production networks anchor supply to regional packaging clusters facing EU Green Deal carbon reduction mandates.
United States
Midwest corn processing infrastructure supplies native and modified starch grades to multinational food and adhesive customers. FDA GRAS self-affirmation pathways shape market access for novel starch variants targeting clean-label claims. Cargill Incorporated leverages North American wet milling capacity to serve paperboard and packaged goods manufacturers concentrated in the Great Lakes industrial corridor.
China
Expanding food processing and packaging industries absorb growing volumes of modified starch for instant noodle coatings and corrugated board adhesives. National dual carbon goals pressure converters toward lower-carbon feedstock sourcing. Yangtze River Delta manufacturing clusters source heavily from domestic corn and cassava processing networks serving export-oriented packaged goods producers.
France
Pea starch extraction expertise concentrates in northern agricultural regions supplying allergen-free grades to pharmaceutical and nutraceutical formulators. EFSA guidance evolution on resistant starch dietary fiber classifications opens prebiotic fortification applications. Roquette Frères anchors European non-GMO positioning from production facilities serving clean-label food processors across the Benelux and German border regions.
India
Domestic food processing expansion drives native starch absorption for cost-sensitive snack and convenience food manufacturers. FSSAI food additive regulations govern modified starch deployment in packaged goods. Gujarat and Maharashtra industrial corridors host wet milling operations supplying textile warp sizing and paper surface sizing segments serving regional manufacturing clusters.
Industrial Starch Market Key Industry Players
The competitive structure tilts toward agricultural-commodity processors with captive feedstock supply. Wet milling operations with backward integration into grain procurement dominate volume leadership. Three archetypes define positioning: multinational agribusiness conglomerates with global distribution networks, regional specialists in non-GMO and allergen-free grades, and captive processors serving integrated paper and packaging operations. Capacity expansion and sustainability certification acquisition represent the dominant competitive moves as buyers demand verified carbon footprint documentation.
Within the multinational agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through North American corn processing infrastructure. Roquette Frères occupies a specialist position anchored in European pea and potato starch expertise. Tate & Lyle PLC represents the diversified ingredients archetype with modified starch portfolios spanning food, pharmaceutical, and industrial applications. These three anchors demonstrate how geographic feedstock access and regulatory compliance capabilities determine competitive viability across divergent end-use segments.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Roquette Frères |
| AGRANA Beteiligungs-AG |
| Grain Processing Corporation |
| Tereos Group |
| Emsland Group |
| Others |
Cost & Logistics Intelligence
Backward integration into corn and potato wet milling operations anchors pricing power for processors serving Hamburg and Rhine-Ruhr packaging clusters, while fragmented food manufacturers downstream absorb commodity-grade native starch without equivalent leverage. REACH chemical modification documentation requirements compound this asymmetry, forcing smaller buyers toward established processors possessing in-house compliance infrastructure and captive feedstock supply.
Pricing Analysis
Margin tightening in modified starch tiers reflects REACH-driven reformulation capex intensity and cross-linking agent substitution costs. Three-tier pricing structure across premium certified, standard modified, and economy native grades separates pharmaceutical excipient buyers from corrugated packaging converters and cost-sensitive food processors. Cost-down pressure on native starch accelerates because agricultural commodity volatility squeezes producers without captive grain procurement. Food manufacturers in Germany exhibit highest price sensitivity, while pharmaceutical companies pay steep premiums for allergen-free pea starch documentation.
Supply Chain Analysis
Domestic-content requirements under EU Green Deal carbon accounting rules reshape sourcing toward verified low-carbon feedstocks from Emsland Group and Roquette Frères production networks. Supply concentrates in Germany, France, and the United States, with wet milling infrastructure drawing from regional corn, potato, and pea harvests. Raw material dependencies rest on agricultural commodity cycles, energy-intensive drying operations, and specialized enzyme inputs for resistant starch extraction. Single-source vulnerability concentrates around Rhine-Ruhr logistics corridors exposed to regional energy price spikes. Distribution runs through direct procurement relationships displacing traditional distributor intermediaries in multinational corrugated board and adhesive manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capacity constraints in REACH-compliant wet milling operations prop pricing premiums for established processors, creating a supply-constrained market structure favoring incumbents with existing chemical modification infrastructure and backward-integrated feedstock control.
For Market Incumbents: Hedge margin erosion in commodity native starch by accelerating resistant starch extraction capacity for pharmaceutical prebiotic applications. Prioritize sustainability certification acquisition to capture compostable packaging mandates emerging under German extended producer responsibility laws. Defensive consolidation around pea starch technology convergence offsets corn price volatility through protein extraction co-product economics. For New Entrants and Emerging Players: EU Green Deal carbon reduction mandates in Germany open a window for regional pea starch processors with verified low-carbon positioning. Target pharmaceutical excipient segments where allergen-free documentation commands premium pricing unavailable to commodity corn starch suppliers. White-space exists in biodegradable adhesive formulations for corrugated board sealing as F-Gas Regulation compliance pressures intensify. Go-to-market leverage rests on direct procurement relationships with sustainability-verification capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap wet milling specialists with captive regional feedstock supply and existing REACH compliance infrastructure. Long-term viability favors processors with resistant starch technology platforms serving gut-health positioning trends in nutraceutical applications. Acquisition target archetype: regional European operators with pea or potato starch expertise and pharmaceutical-grade certification. Signal to watch: EFSA guidance finalization on resistant starch dietary fiber classifications as inflection indicator for pharmaceutical volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn and potato procurement control insulates margin stability against agricultural commodity volatility cycles. |
| REACH Compliance Infrastructure Investment | Chemical modification documentation capabilities lock in pharmaceutical and paper packaging procurement relationships. |
| Resistant Starch Extraction Scale-Up | Prebiotic fiber fortification demand from German nutraceutical manufacturers opens premium revenue streams. |
| Sustainability Certification Acquisition | Verified carbon footprint data satisfies EU Green Deal procurement terms in Hamburg packaging clusters. |
| Pea Starch Technology Convergence | Protein extraction co-product economics expand viable feedstock options beyond traditional corn bases. |
Research Approach
Trade databases, customs records, and SEC filings from Cargill Incorporated, Archer Daniels Midland Company, and Tate & Lyle PLC formed the secondary backbone, supplemented by wet milling capacity reports and agricultural commodity price indices. Primary interviews with plant managers at Emsland Group and Roquette Frères facilities, procurement leads at Rhine-Ruhr corrugated packaging converters, and regulatory affairs specialists navigating REACH chemical modification requirements validated secondary findings. Technical R&D directors at resistant starch extraction operations and distribution channel partners serving pharmaceutical excipient segments provided segmentation inputs. Bottom-up volume modeling across product types, applications, and end-user industries triangulated against top-down macroeconomic drivers.
Historical trendline analysis established baseline growth patterns across the projection horizon, with CAGRs derived from regression modeling against industrial production indices and packaging output data. Segmentation dimensions spanned product type tiers, end-use industry verticals, and regional production hub clusters. Industry-specific forecast inputs incorporated EU Green Deal carbon reduction trajectory assumptions and EFSA guidance evolution timelines for resistant starch dietary fiber classifications.
The model assumes a particular technology adoption path; alternative pathways for enzyme-modified resistant starch extraction would alter the outlook if breakthrough prebiotic efficacy claims accelerate pharmaceutical absorption beyond baseline projections. Forecasts reflect assumptions around REACH chemical modification compliance timelines and agricultural commodity price normalization. Alternative regulatory scenarios or sustained feedstock volatility would revise volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Corn Glucose Market
Ingredients
Non-GMO Soya Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
Phytogenic Market
Ingredients
South America Lipid Market
Ingredients
Malted Wheat Flour Market
Ingredients
Instant Dry Yeast Market
Ingredients
India Gelatin Market
Ingredients
North America Soy Protein Market
Ingredients
North America Gums Market
Ingredients
Dry Blended Products Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Potato & Yam Derivatives Market
Ingredients
Global Egg White Peptide Market
Ingredients
Almond Ingredients Market
Ingredients
Asia-Pacific Bakery Ingredients Market