
 Pastry Premixes Market | 2026-2036
Pastry Premixes Market Size, Share, and Industry Trends Forecast 2026-2036
Pastry Premixes Market Analytics
The EU Green Deal is recalibrating ingredient sourcing standards across European food manufacturing. Puratos Group leverages its vertically integrated fermentation capabilities to secure clean-label supply chains. Lesaffre anchors its position through intensive enzyme R&D programs. Bakels Group competes by controlling specialty distribution networks in Northern Europe.
Pastry premixes are industrially blended formulations combining flour, leavening agents, emulsifiers, and functional ingredients in precise ratios, designed to deliver batch-to-batch consistency with minimal on-site preparation. Cake mix leads product type revenue due to extended shelf stability and broad household penetration, while dough mix represents the fastest-growing segment as quick-service restaurants expand frozen-to-oven programs. Bakeries dominate end-user demand through high-volume procurement contracts, whereas retail chains concentrate margin pools through private-label premix programs.
EFSA governs additive safety thresholds for premix formulations across EU member states, while REACH regulates chemical inputs in processing aids and packaging materials. The EU AI Act will soon shape automated quality-control deployments in premix manufacturing facilities. Stakeholders must monitor how evolving clean-label enforcement in Brussels reshapes formulation portfolios and supplier qualification timelines.
Market Dynamics
Europe's F-Gas Regulation is forcing manufacturers to abandon hydrofluorocarbon-dependent cooling systems in premix production facilities, triggering capital reallocation toward ammonia-based refrigeration and magnetic bearing compressors.
Growth Catalysts
- Clean-label fermentation infrastructure:Vertically integrated enzyme production secures supply chain resilience against input volatility. Artisan bakeries leverage these inputs to maintain consistency without expanding kitchen labor.
- EU Green Deal sourcing mandates:Ingredient qualification timelines now embed carbon footprint thresholds, accelerating supplier consolidation around low-emission wheat and specialty fat sources.
- Frozen-to-oven program expansion:Quick-service restaurants deploy dough premixes through centralized commissary models, compressing preparation labor at franchise locations.
Market Restraints
- Wheat protein concentrate volatility:Drought cycles in Black Sea sourcing regions disrupt gluten functionality specifications, forcing reformulation cycles that strain R&D bandwidth.
- Specialty leavening agent concentration:Three chemical suppliers dominate sodium acid pyrophosphate production for industrial premixes, creating single-source vulnerability.
- Clean-label enzyme substitution limits:Chemical emulsifiers still outperform biological alternatives in frozen dough stability, constraining full ingredient replacement.
Strategic Opportunities
- Artisan bakery cooperative procurement:Germany's Mittelstand baking clusters present consolidated volume potential currently served through fragmented distributor networks.
- EU AI Act quality-control deployment:Automated vision systems for batch consistency monitoring qualify for green technology investment credits under national recovery frameworks.
- Specialty diet formulation white space:Diabetic-friendly and keto-adapted cake premixes remain underdeveloped relative to gluten-free saturation.
Industry Challenges
- Retro-commissioning production lines:Legacy mixing equipment lacks precision dosing capabilities required for micro-ingredient premixes, demanding seven-figure capital outlays.
- Multi-jurisdiction additive approvals:Novel enzyme GRAS petitions face eighteen-month EFSA evaluation queues, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pastry Premixes Market |
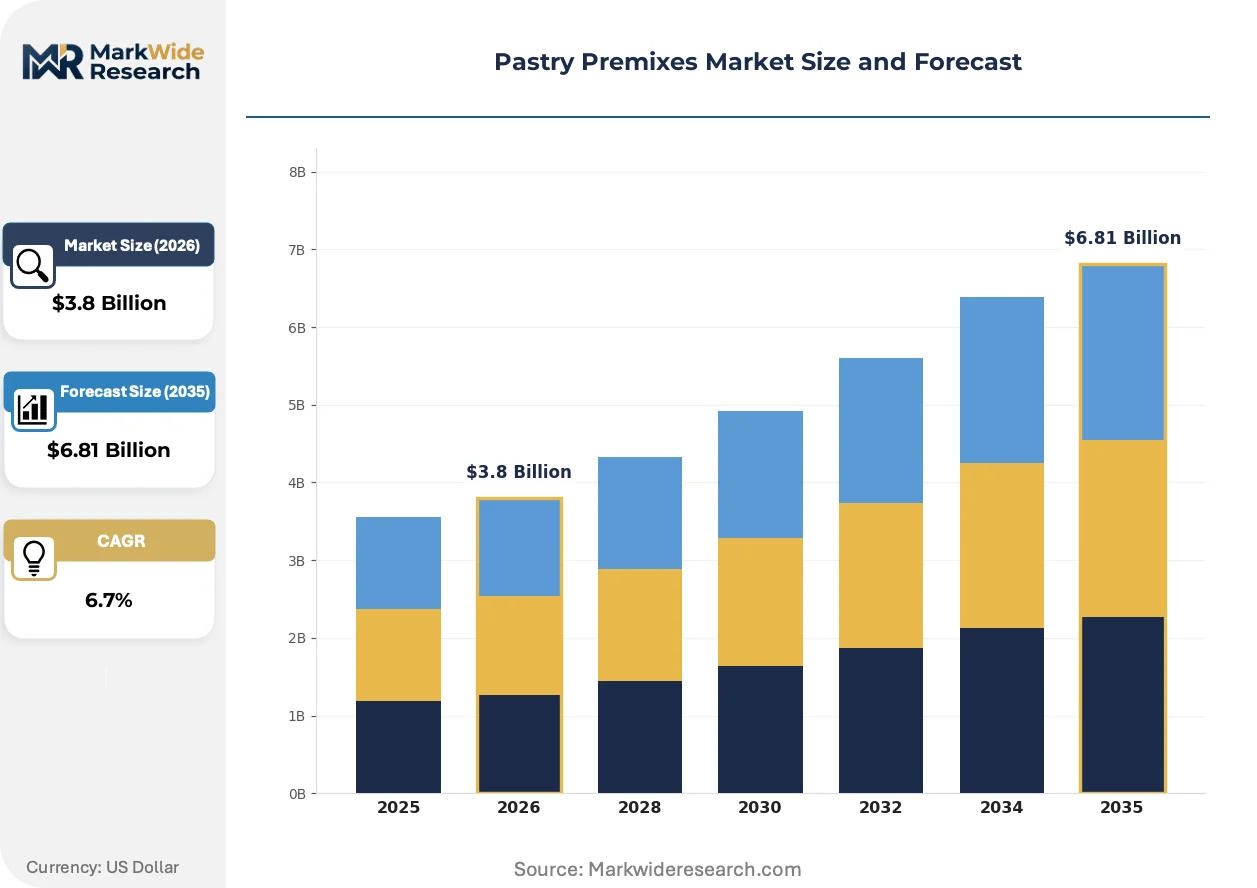
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cake Mix, Dough Mix, Filling Mix, Dessert Mix End User: Bakeries, Restaurants, Retail Chains, Catering Services Packaging Type: Bags, Boxes, Bulk Containers, Sachets Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Puratos Group, Lesaffre, Bakels Group, AB Mauri, ADM, Dawn Foods, Cargill, General Mills, Premia Food Additives, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pastry Premixes Market Evolving Landscape
Active fermentation science is displacing chemical conditioning in premix formulation, with live culture stability emerging as the critical technical frontier separating commodity and premium positioning.
Encapsulated live yeast cultures with extended ambient shelf stability are expanding into frozen dough premix applications. Industrial bakeries in Northern Europe adopt these formats at accelerating rates to reduce cold-chain dependency. The technology is expanding into previously unserved convenience retail channels where refrigeration infrastructure remains limited.
REACH chemical authorization reviews are tightening emulsifier and processing aid approval pathways. ECHA's substance evaluation work program now prioritizes food-contact chemicals with endocrine disruption potential. Cake premix manufacturers reformulate around lecithin and enzyme-based alternatives, accepting higher unit costs to secure regulatory continuity.
Buyer consolidation among retail private-label programs compresses supplier negotiation cycles from annual to quarterly reviews. Supermarket chains in Germany and France now demand real-time inventory visibility through vendor-managed replenishment systems. This concentration shifts margin pressure upstream to premix manufacturers while rewarding logistics-integrated suppliers with contract renewals.
Pastry Premixes Market Segmentation
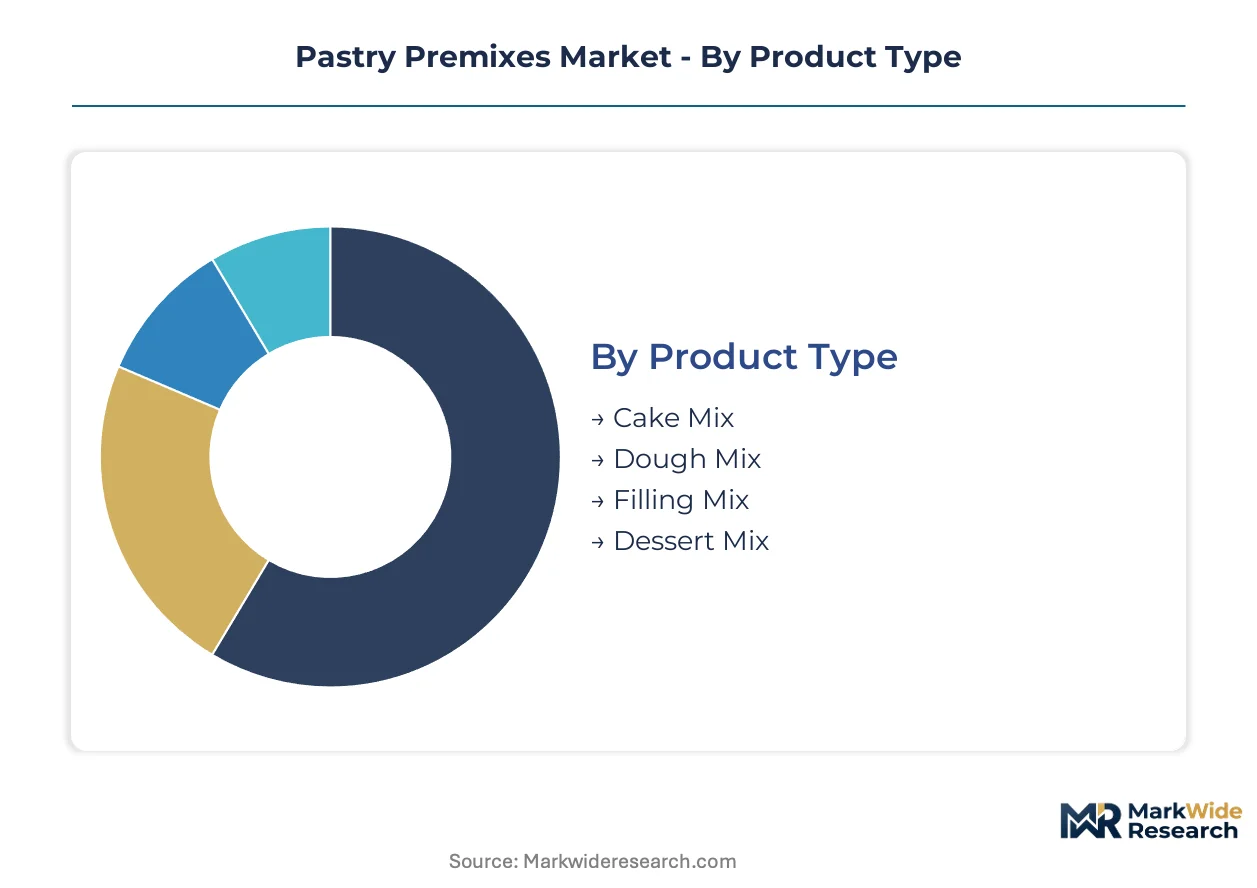
Pastry premix segmentation reflects divergent supply chain configurations across artisan, industrial, and retail channels. Each dimension—product formulation, end-use application, packaging format, and distribution pathway—carries distinct margin structures and capital intensity requirements that reshape supplier positioning.
Product Type:
Supply concentration in wheat milling and specialty fat sourcing disproportionately shapes product-level competitive dynamics, with formulation complexity determining backward integration feasibility.
- Cake Mix:Industrially blended formulations combining refined wheat flour, chemical leavening systems, and emulsifier packages calibrated for extended ambient shelf stability. Germany's industrial baking clusters anchor procurement volumes through annual contracting frameworks, though EFSA additive safety thresholds now compress reformulation cycles for clean-label migration.
- Dough Mix:Frozen-to-oven formulations integrating vital wheat gluten, enzyme-conditioned starches, and encapsulated yeast cultures for cold-chain distribution. Quick-service restaurant commissary programs in France and the Netherlands are expanding centralized procurement, compressing preparation labor at franchise locations while demanding batch-to-batch fermentation consistency.
- Filling Mix:Stabilized starch and hydrocolloid blends for cream, fruit, and custard applications.
- Dessert Mix:Specialized formulations targeting mousse, meringue, and gelatin-based preparations for foodservice.
Cake mix absorbs the bulk of installed capacity; dough mix is expanding most quickly.
End User:
Customer-type segmentation reveals starkly divergent procurement patterns, with volume concentration versus margin capture pulling suppliers in opposite strategic directions.
- Bakeries:Artisan and industrial operators purchasing multi-tonne batches through distributor networks or direct manufacturer relationships. Germany's Mittelstand baking cooperatives are consolidating procurement volumes previously fragmented across regional distributors, creating consolidated negotiation leverage.
- Restaurants:Mid-scale foodservice operators sourcing through broadline distributors with limited technical specification control.
- Retail Chains:Supermarket private-label programs in France and Germany now demand real-time inventory visibility through vendor-managed replenishment systems, compressing supplier negotiation cycles from annual to quarterly reviews and shifting margin pressure upstream.
- Catering Services:Event and institutional foodservice purchasing standardized formats for volume consistency.
Bakeries command the largest share of production volume; retail chains are climbing the fastest in procurement sophistication.
Packaging Type:
Packaging configuration directly determines logistics economics and customer accessibility, with format selection tracking end-use scale and cold-chain availability.
- Bulk Containers:Industrial totes and silo-ready formats for high-throughput bakery operations, dominating tonnage flows into Northern European industrial clusters where ammonia-based refrigeration systems are replacing F-Gas-dependent cooling under regulatory mandate.
- Bags:Multi-kilogram formats for mid-scale artisan and foodservice procurement.
- Boxes:Retail-ready packaging for supermarket shelf placement and household penetration.
- Sachets:Single-use portions targeting convenience retail channels with limited refrigeration infrastructure, gaining traction as encapsulated live yeast cultures extend ambient shelf stability.
Bulk containers handle the greatest throughput; sachets are gaining share fastest in underpenetrated convenience channels.
Distribution Channel:
Channel structure reflects the tension between technical service intensity and logistics efficiency, with each pathway embedding distinct supplier capability requirements.
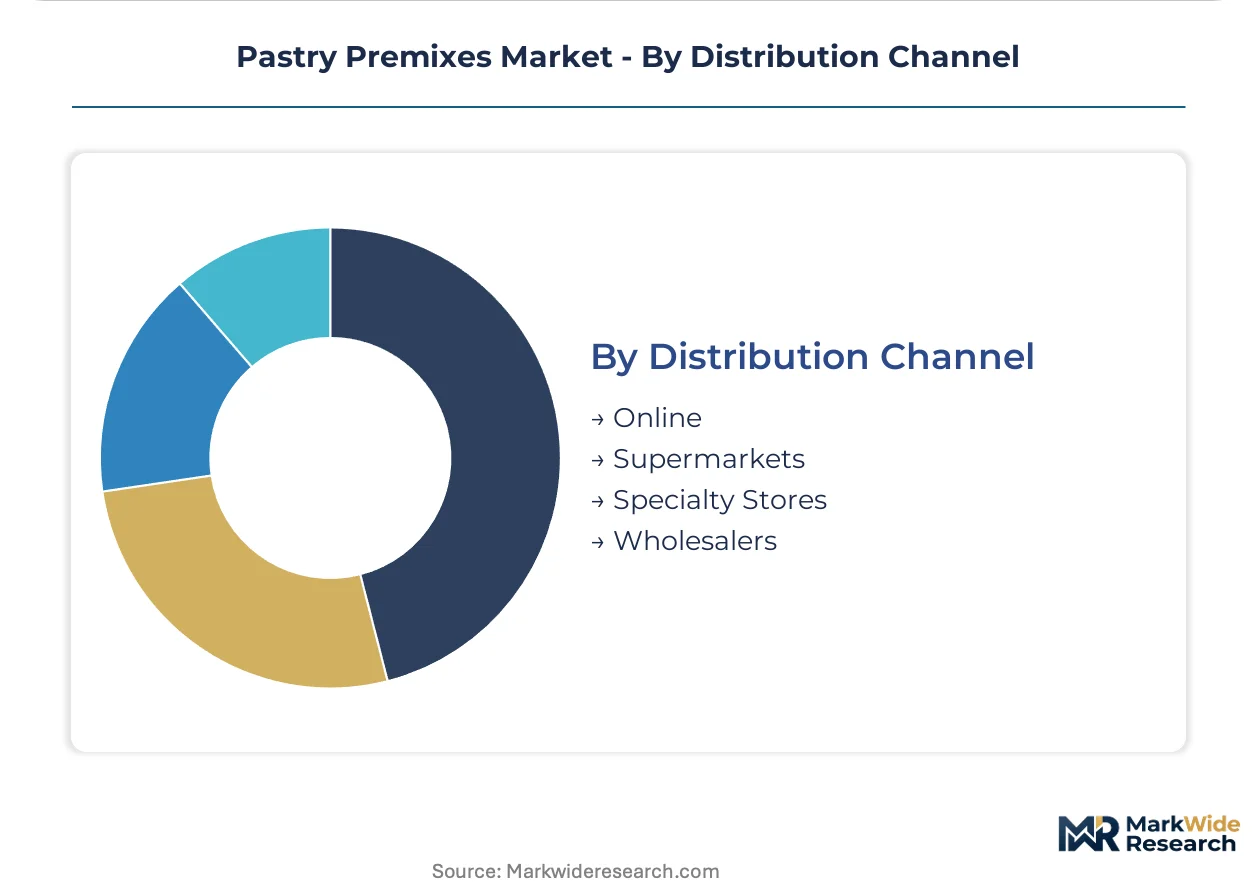
- Wholesalers:Traditional bakery supply distributors controlling Northern European specialty networks, maintaining technical consultation relationships with artisan operators while facing consolidation pressure from manufacturer-direct programs.
- Supermarkets:Centralized retail procurement with private-label concentration and vendor-managed inventory systems.
- Specialty Stores:Gourmet and professional kitchen retailers serving enthusiast bakers with premium positioning.
- Online:Direct-to-operator and marketplace platforms expanding technical content and reorder convenience, particularly for specialty diet formulations where diabetic-friendly and keto-adapted premixes remain underdeveloped relative to gluten-free saturation.
Wholesalers retain the deepest installed relationships; online channels are expanding at the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premix production clusters concentrate in Northern Europe while consumption spreads across diversified bakery networks. Germany's industrial baking infrastructure anchors manufacturing capacity. France and the Netherlands drive formulation innovation through commissary program expansion.
Germany
Mittelstand baking cooperatives consolidate procurement volumes previously fragmented across regional distributors. The F-Gas Regulation mandates ammonia-based refrigeration retrofits in production facilities. Industrial clusters in Lower Saxony and North Rhine-Westphalia host the continent's densest premix manufacturing infrastructure.
France
Quick-service restaurant commissary programs expand centralized dough premix procurement at accelerating rates. EFSA additive safety thresholds compress reformulation cycles for clean-label migration. The Paris basin and Hauts-de-France anchor frozen-to-oven distribution networks serving franchise operations.
Netherlands
Rotterdam's port logistics integrate specialty fat and wheat protein supply chains for premix manufacturers. REACH chemical authorization reviews tighten emulsifier approval pathways. Food processing clusters in Randstad municipalities adopt vendor-managed inventory systems demanded by retail private-label programs.
United Kingdom
Artisan bakery operators seek consistency solutions without scaling kitchen labor. The EU Green Deal's carbon footprint thresholds reshape ingredient qualification timelines for cross-border suppliers. Greater London and the Midlands concentrate distribution network control points for specialty premix formats.
Italy
Traditional panettone and regional pastry producers adopt enzyme-conditioned premixes for standardized seasonal output. ECHA's substance evaluation work program prioritizes food-contact chemicals with endocrine disruption potential. Lombardy and Emilia-Romagna maintain heritage bakery density while industrializing procurement through distributor consolidation.
Pastry Premixes Market Competitive Landscape
The competitive structure tilts toward fermentation-science specialists with captive enzyme production. Three tiers separate global ingredient conglomerates from regional bakery supply distributors and niche clean-label formulators. Consolidation pressure concentrates around private-label contract renewal cycles and logistics integration mandates. Capacity expansion and backward integration into wheat milling represent the dominant competitive moves.
Among fermentation-science specialists, Puratos Group, Lesaffre, and Bakels Group occupy positions defined by vertical integration depth. Puratos exemplifies the archetype leveraging in-house fermentation capabilities to secure supply chain resilience. Lesaffre anchors enzyme R&D intensity as a competitive differentiator. Bakels represents specialty distribution network control in Northern European markets. These three sit within a tier where biological conditioning expertise separates premium positioning from commodity premix supply.
| Leading Market Players |
|---|
| Puratos Group |
| Lesaffre |
| Bakels Group |
| AB Mauri |
| ADM |
| Dawn Foods |
| Cargill |
| General Mills |
| Premia Food Additives |
| Others |
Value Network & Pricing Analysis
Wheat futures volatility in Black Sea sourcing corridors cascades through three-tier pricing structure across premium, standard, and economy levels, compressing margins at the commodity tier while fermentation-science specialists capture value through enzyme-conditioned premium formulations. Buyers in Germany's Mittelstand baking cooperatives leverage consolidated volumes to extract price concessions, whereas quick-service restaurant commissaries accept premium positioning for batch-to-batch fermentation consistency guarantees.
Pricing Analysis
Yield-guaranteed throughput pricing anchors value capture for industrial bakery clients, with per-kilogram rates scaling to fermentation performance metrics rather than commodity flour input costs. Price differentiation separates encapsulated live yeast cultures with extended ambient stability from commodity chemical-leavening alternatives, with certification tier—EFSA clean-label approval versus standard additive packages—driving secondary spreads. Pricing pressure stems from retail private-label concentration in France and Germany, where quarterly vendor-managed inventory reviews compress supplier negotiation leverage. Artisan cooperatives exhibit highest price sensitivity due to fragmented procurement volumes, while frozen-to-oven commissary operators prioritize consistency premiums over unit cost minimization.
Supply Chain Analysis
EFSA additive safety qualification gates supplier entry, with eighteen-month GRAS petition queues creating defensive moats for incumbent enzyme producers with established dossiers. Geographic supply concentration centers on Germany, France, and the Netherlands, where industrial baking clusters anchor wheat milling and specialty fat processing infrastructure. Raw material dependencies rest on Black Sea wheat protein concentrates, sodium acid pyrophosphate from three dominant chemical suppliers, and encapsulated yeast cultures with limited qualified producers. Single-source vulnerability in specialty leavening agents exposes formulators to disruption. Distribution runs through wholesaler technical-consultation networks in Northern Europe, with manufacturer-direct programs gaining share among consolidated cooperative buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active fermentation science is displacing chemical conditioning as the dominant formulation paradigm, creating asymmetric opportunity for biological-science specialists against legacy chemical-leavening suppliers. This technology transition favors operators with captive enzyme production and extended-shelf-stability live culture capabilities.
For Market Incumbents: To counter private-label margin compression from retail chain consolidation, secure backward integration into wheat milling in Lower Saxony industrial clusters and accelerate EFSA clean-label certification pipelines to defend premium positioning against commodity erosion. For New Entrants and Emerging Players: Direct-to-artisan digital platforms offer the most penetrable route, targeting Germany's fragmented Mittelstand baking cooperatives with specialty diet formulations—diabetic-friendly and keto-adapted cake premixes—where gluten-free saturation leaves white space unclaimed, using technical content marketing to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-science mid-caps in Benelux with qualified EFSA dossiers but constrained working capital, where five-to-ten-year viability hinges on live-culture stability patent estates; watch for inflection when retail private-label programs begin mandating real-time inventory visibility as a contract renewal condition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Milling | Captive supply of low-emission wheat secures EU Green Deal compliance for German industrial clusters. |
| Encapsulated Live Yeast Scale-Up | Extended ambient shelf stability opens convenience retail channels with limited refrigeration infrastructure. |
| EFSA Clean-Label Certification Pipeline | Accelerated GRAS petitions defend premium positioning against commodity chemical-leavening alternatives. |
| Vendor-Managed Inventory Integration | Real-time replenishment systems satisfy French and German retail private-label contract renewal mandates. |
| Ammonia-Based Refrigeration Retrofit | F-Gas Regulation compliance secures production continuity in Northern European manufacturing facilities. |
Research Methodology
EFSA additive safety filings, REACH chemical authorization databases, and EU customs trade records formed the secondary backbone, cross-referenced against primary interviews with industrial bakery procurement directors, artisan cooperative managers, enzyme R&D technical leads, and specialty distribution channel partners. Bottom-up volume estimates from facility-level capacity assessments and top-down demand triangulation from end-use consumption patterns were reconciled to establish market sizing boundaries.
Bottom-up segmentation modeling tracked product type, end-user channel, packaging format, and distribution pathway across the projection horizon, with CAGRs derived from trend extrapolation of fermentation-science adoption rates and frozen-to-oven program expansion trajectories. Input variables included wheat protein concentrate price indices, EFSA petition approval timelines, and retail private-label concentration metrics by national market.
The model holds under stable EFSA regulatory interpretation and continued EU Green Deal enforcement; deviation in clean-label acceleration timelines or Black Sea supply disruption severity would shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Doughnuts Market
Bakery Products
Wedding Cakes Market
Bakery Products
Fortified Bakery Market
Bakery Products
Fondant Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Waffle Market
Bakery Products
Ezekiel Bread Market
Bakery Products
India Cake Market
Bakery Products
Dough Whitener Market
Bakery Products
Baked Foods Market
Bakery Products
Toasted Flour Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Cookies Market