
 North America Fortified Bakery Products Market | 2026-2036
North America Fortified Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fortified Bakery Products Market Analytics
Premium micronutrient density tiers are rotating toward the center of competitive strategy in North American bakery aisles. Grupo Bimbo SAB de CV leverages its continental plant network to sustain uniform fortification standards across temperature zones. Flowers Foods Inc anchors its position through deep channel control in the southeastern United States. General Mills Inc competes by specializing in fiber-enhanced formulations that command shelf-space premiums.
Fortified bakery products are baked goods to which vitamins, minerals, fiber, or protein are added during mixing or post-bake application to elevate nutritional value beyond conventional recipes. The primary purpose is to address dietary deficiencies in populations consuming grain-based staples as daily caloric foundations. Breads lead volume within product type segments due to their breakfast and sandwich utility, while protein fortification grows fastest among ingredient types as fitness-oriented consumers shift meal-replacement expectations. Online distribution channels capture expanding margin pools by bypassing traditional slotting fees and enabling direct-to-consumer subscription models for specialized mineral blends.
The FDA governs nutrient content claims and fortification ceilings under the Federal Food, Drug, and Cosmetic Act, while Health Canada sets parallel standards through its Food and Drug Regulations and fortification policies. Both frameworks shape demand by defining permissible health claims and mandatory label disclosures that determine which formulations qualify for front-of-package positioning. Stakeholders must monitor evolving bioavailability testing requirements and state-level sodium reduction mandates that could force simultaneous reformulation of existing fortified lines.
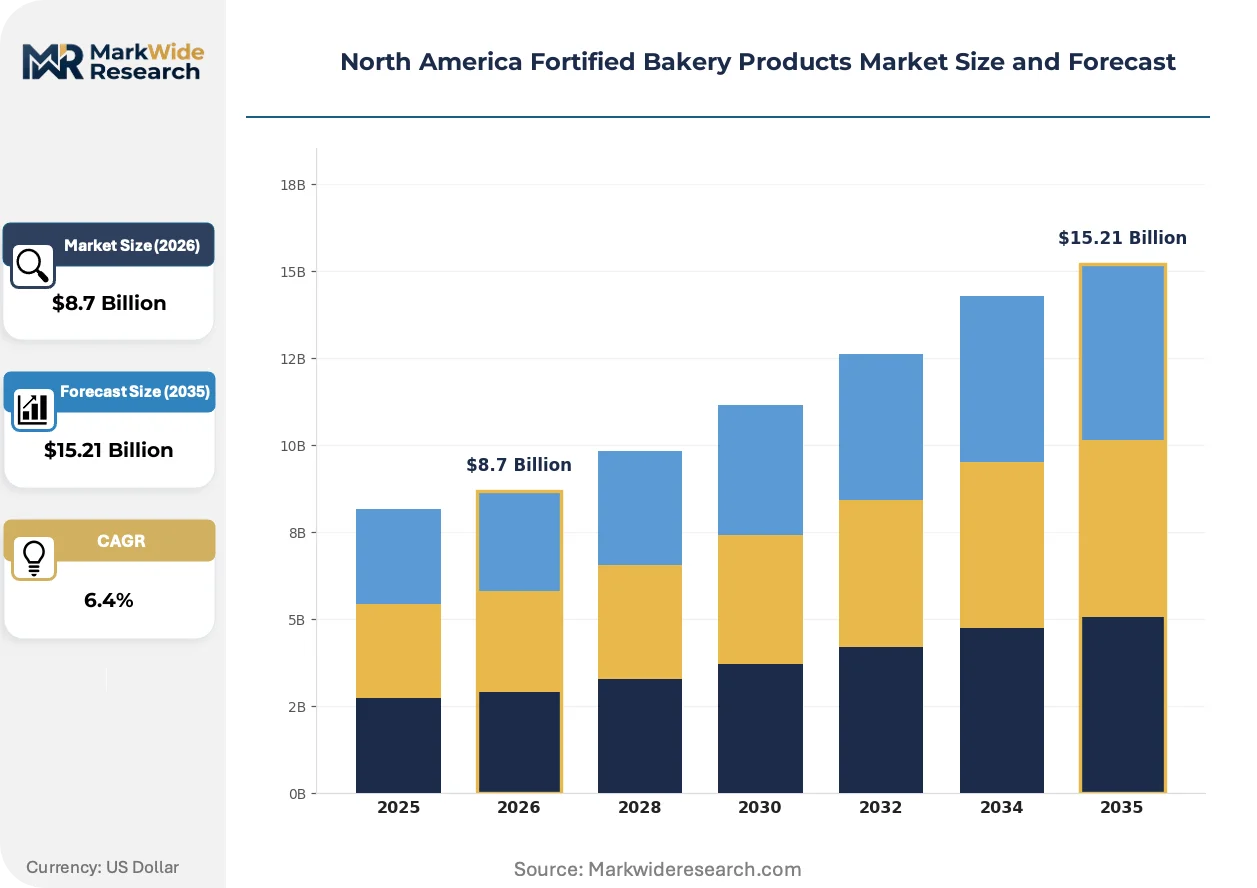
Market Dynamics
Fortification mandates from the FDA and Health Canada are compressing reformulation timelines across North American bakery supply chains, forcing simultaneous investments in micronutrient testing infrastructure and label redesign capabilities.
Growth Catalysts
- School Nutrition Procurement:United States and Canadian K-12 meal programs are expanding volume commitments for vitamin-enriched bread loaves, creating institutional demand anchors that stabilize production planning.
- FDA Guideline Pressure:Updated fortification ceilings under the Federal Food, Drug, and Cosmetic Act are compelling manufacturers to elevate micronutrient density in staple formulations to retain shelf positioning.
- Protein Fortification Technology:Microencapsulation advances are enabling heat-stable protein integration into pastries without texture degradation, opening formulation possibilities previously limited to cold-application products.
Market Restraints
- Wheat Input Volatility:North American milling wheat prices fluctuate with drought cycles in the Great Plains, compressing margin predictability for fortified product lines that already carry premium ingredient costs.
- Supply Concentration Risk:Vitamin premix production concentrates among a handful of domestic suppliers, creating single-source vulnerability for B-vitamin and iron fortification blends.
- Bioavailability Testing Limits:Current in-vitro simulation protocols inadequately predict mineral absorption in high-fiber matrices, forcing expensive human studies that delay product launches.
Strategic Opportunities
- Direct-to-Consumer Subscriptions:Online channels bypass traditional grocery slotting fees and enable recurring revenue models for specialized mineral blend products targeting fitness-oriented households.
- Urban Food Service Penetration:The U.S. Northeast corridor presents underexploited demand from coffee chains and corporate cafeterias seeking protein-fortified breakfast pastries for commuter consumers.
- State Sodium Reduction Alignment:California and New York sodium mandates create regulatory tailwinds for reformulated fortified lines that simultaneously address mineral enrichment and salt reduction.
Industry Challenges
- Reformulation Talent Scarcity:Food science programs produce insufficient graduates with dual expertise in baking technology and micronutrient stability under thermal processing.
- Dual-Compliance Complexity:Parallel FDA and Health Canada disclosure requirements force separate label runs and documentation systems for cross-border product lines.
- Legacy Equipment Retrofit Costs:Existing dough handling systems require stainless steel upgrades and dosing mechanism installations to handle hygroscopic vitamin premixes without clumping or degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fortified Bakery Products Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Muffins, Cookies, Pastries Ingredient Type: Vitamins, Minerals, Fiber, Protein Distribution Channel: Supermarkets, Health Food Stores, Online, Convenience Stores End User: Retail Consumers, Food Service, Bakeries, Restaurants |
| Companies Covered | Grupo Bimbo SAB de CV, Flowers Foods Inc, General Mills Inc, Mars Incorporated, H&S Bakery Inc, Super Bakery Inc, Nestlé, Mondelez International, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fortified Bakery Products Market Evolving Landscape
Enzymatic fortification systems and precision fermentation-derived proteins are rewriting formulation possibilities, while regulatory disclosure requirements and channel fragmentation reshape how nutritional claims reach end consumers.
Microencapsulated mineral systems are displacing conventional spray-dried fortificants in high-temperature baking applications. Artisan and industrial producers throughout the U.S. Northeast and Ontario are adopting these systems at accelerating rates to prevent iron and zinc degradation during proofing and oven cycles. This technology is displacing legacy fortification methods that required post-bake topical application, collapsing process steps and reducing contamination risk in shared production facilities.
Health Canada's updated Food and Drug Regulations fortification policies are tightening permissible health claim language for bakery products. Manufacturers must now substantiate bioavailability claims through clinical evidence rather than compositional analysis alone, elevating R&D documentation burdens. The protein-fortified pastry segment faces the steepest compliance curve, as amino acid scoring requirements now apply to front-of-package positioning previously available through simpler protein gram declarations.
Food service operators are consolidating procurement through specialized broadline distributors that bundle fortified bakery SKUs with nutritional reporting services. These distributors are replacing traditional bake-from-frozen programs with thaw-and-serve fortified alternatives that carry verified micronutrient certificates for institutional compliance. This pattern concentrates most visibly in urban Canadian school districts and U.S. hospital systems where dietary audit requirements have intensified.
North America Fortified Bakery Products Market Segmentation
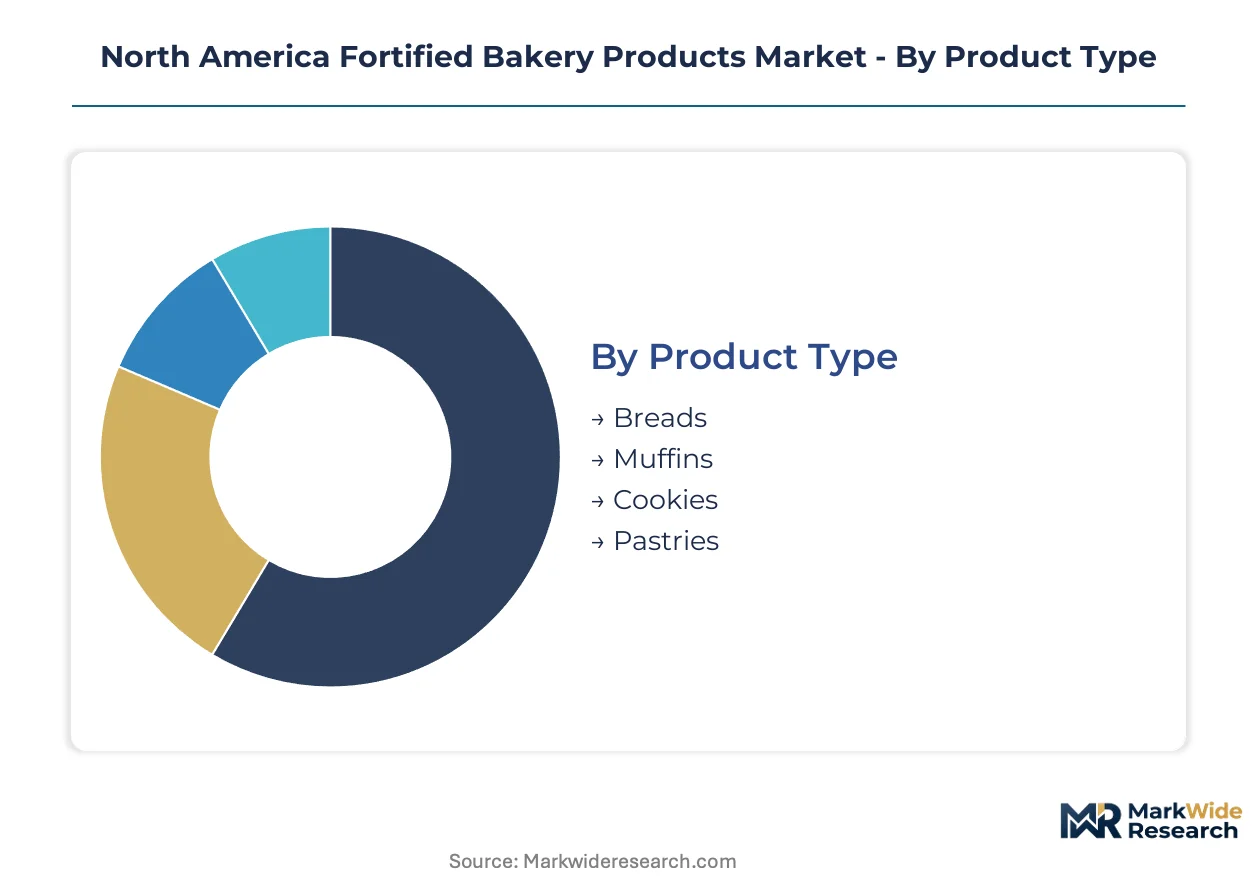
Segmentation in fortified bakery products reveals how nutritional positioning, channel access, and end-use requirements fragment demand across North American supply chains. Manufacturers must align fortification intensity and label claims with distinct buyer specifications that vary by consumption occasion and procurement authority.
Product Type:
Domestic consumption dominates bread and muffin volumes through institutional feeding programs, while pastries and cookies carry higher export orientation to Caribbean and Latin American markets seeking U.S.-formulated fortified goods.
- Breads:Vitamin-enriched loaves serve as the caloric foundation for U.S. and Canadian school nutrition programs, with iron and folic acid fortification mandated by FDA and Health Canada standards for institutional procurement eligibility. Northeast corridor urban food service operators specify protein-fortified sandwich carriers for commuter breakfast programs, compressing production runs toward higher micronutrient density tiers.
- Pastries:Microencapsulation technology enables heat-stable protein integration into croissants and Danish without texture degradation, opening formulation possibilities previously limited to cold-application products. Coffee chains throughout Ontario and New England are expanding procurement of these items for morning commuter traffic.
- Muffins:Fiber-enhanced varieties command shelf-space premiums in health food retail channels across California and British Columbia.
- Cookies:Mineral-fortified formats target direct-to-consumer subscription models bypassing traditional grocery slotting fees.
Breads commands the established base. The steepest expansion runs through pastries.
Ingredient Type:
Cost tier differentiation separates commodity fortification from premium bioavailable formulations, with vitamin and mineral blends occupying standard price bands while protein and targeted fiber command formulation premiums.
- Protein:Precision fermentation-derived and microencapsulated protein systems are displacing conventional spray-dried fortificants in high-temperature baking applications throughout the U.S. Northeast and Ontario. Fitness-oriented consumers in urban centers are shifting meal-replacement expectations toward baked goods delivering 15-20g protein per serving.
- Fiber:Resistant starch and soluble fiber blends enable front-of-package positioning for digestive health claims, with General Mills Inc specializing in formulations that meet Health Canada's amended bioavailability documentation requirements.
- Vitamins:B-complex and folic acid premixes face supply concentration risk among domestic suppliers.
- Minerals:Iron and zinc fortification requires expensive human studies under tightened Health Canada disclosure rules.
Vitamin fortification provides volume foundation. Protein is climbing the fastest.
Distribution Channel:
Customer type fragmentation splits procurement between institutional buyers seeking verified micronutrient certificates and individual consumers prioritizing convenience and subscription reliability.
- Online:Direct-to-consumer channels bypass traditional grocery slotting fees and enable recurring revenue models for specialized mineral blend products targeting fitness-oriented households. These platforms capture expanding margin pools through subscription bundling of protein-fortified pastries and fiber-enhanced muffins.
- Supermarkets:Deep channel control by Flowers Foods Inc in the southeastern United States anchors fortified bread volumes through everyday low-price positioning and uniform fortification standards sustained by Grupo Bimbo SAB de CV's continental plant network.
- Health Food Stores:Premium micronutrient density tiers rotate toward the center of competitive strategy in these aisles.
- Convenience Stores:Thaw-and-serve fortified alternatives are replacing bake-from-frozen programs in urban locations.
Supermarkets anchor the volume base. Online channels are gaining share fastest.
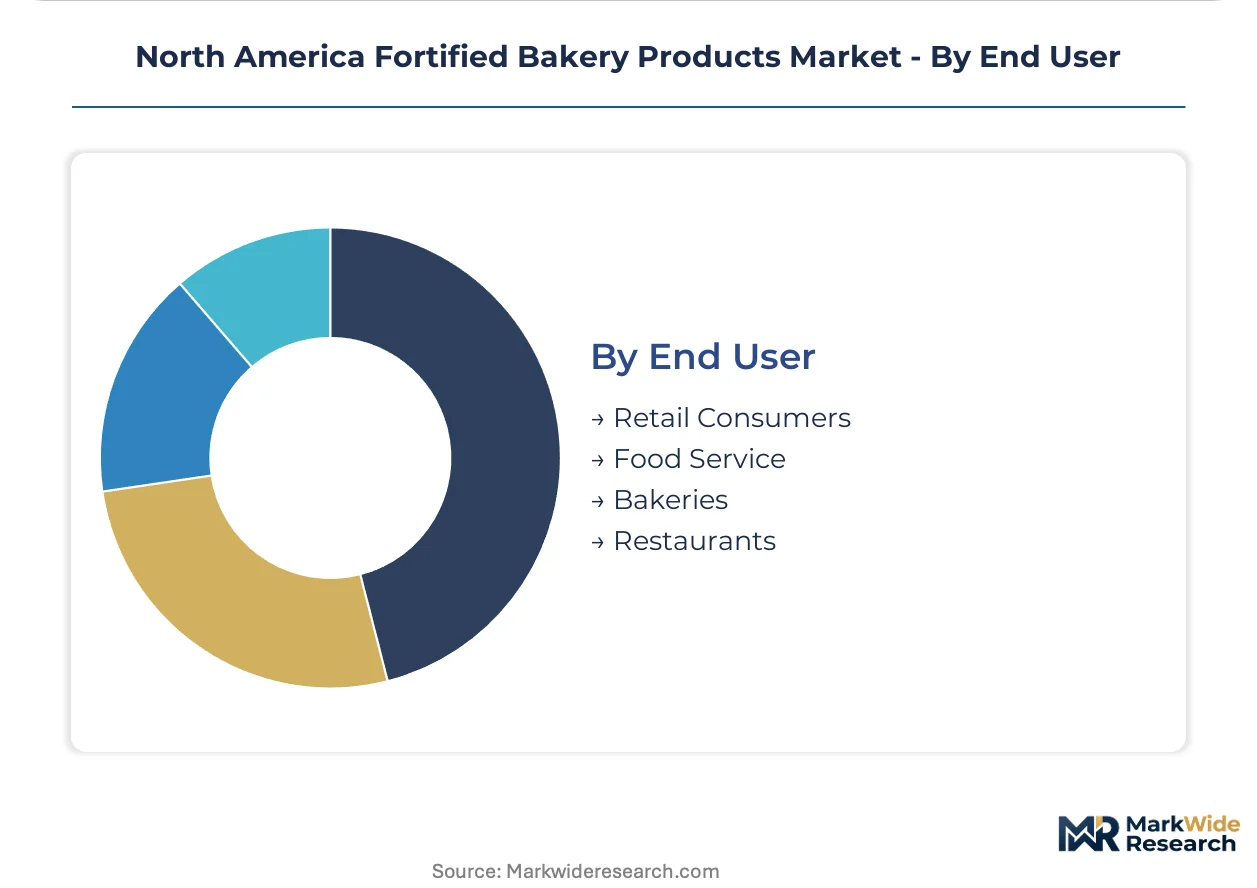
End User:
Application maturity varies sharply, with food service and institutional feeding representing established demand while restaurant and specialty bakery channels remain underpenetrated for premium fortified formats.
- Food Service:Specialized broadline distributors are consolidating procurement through bundled fortified bakery SKUs with nutritional reporting services, replacing traditional programs in urban Canadian school districts and U.S. hospital systems where dietary audit requirements have intensified. These operators require verified micronutrient certificates for institutional compliance.
- Retail Consumers:Subscription models and health food channel penetration drive demand for fiber-enhanced and protein-fortified formats in fitness-oriented households across the U.S. Northeast corridor.
- Bakeries:Artisan producers in Ontario are adopting enzymatic fortification systems at accelerating rates.
- Restaurants:Corporate cafeterias present underexploited demand for protein-fortified breakfast pastries.
Food service commands the established base. Restaurants show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across North American markets, with Canadian institutional buyers demanding verified micronutrient certificates while U.S. urban food service operators prioritize protein density premiums over per-unit cost.
United States
School nutrition programs in the U.S. Northeast corridor anchor institutional demand for vitamin-enriched bread loaves, with Massachusetts and New York expanding procurement volumes. The FDA's updated fortification guidelines under the Federal Food, Drug, and Cosmetic Act compress reformulation timelines for staple products. Boston and New York Metro food service operators specify protein-fortified breakfast pastries for commuter traffic, driving microencapsulation adoption.
Canada
Health Canada's tightened Food and Drug Regulations fortification policies elevate documentation burdens for bioavailability claims, particularly affecting Ontario's artisan bakery sector. Provincial school districts in Toronto and Ottawa consolidate procurement through broadline distributors bundling fortified SKUs with nutritional reporting services. Vancouver health food retail channels command shelf-space premiums for fiber-enhanced muffin varieties.
Mexico
Grupo Bimbo SAB de CV leverages its continental plant network to sustain uniform fortification standards across temperature zones, with Mexico City operations serving as a production hub for cross-border distribution. Mexican regulators align micronutrient density requirements with evolving FDA frameworks to maintain export eligibility. Monterrey industrial bakeries supply fortified bread formats to northern border states with dual U.S.-Canada compliance documentation.
North America Fortified Bakery Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American fortified bakery sector. The market structure consolidates around three strategic tiers: multinational conglomerates with continental plant networks, regional specialists with deep channel control, and niche direct-to-consumer operators. Dominant competitive moves include portfolio diversification into protein-fortified formats and strategic partnerships with institutional distributors bundling nutritional reporting services.
Among Mexico-based conglomerates with continental reach, Grupo Bimbo SAB de CV exemplifies the scale-driven archetype sustaining uniform fortification standards. U.S.-based Flowers Foods Inc and General Mills Inc occupy distinct positioning vectors within the North American market, with the former representing deep channel control in southeastern states and the latter exemplifying fiber-enhanced formulation specialization commanding shelf-space premiums.
| Leading Market Players |
|---|
| Grupo Bimbo SAB de CV |
| Flowers Foods Inc |
| General Mills Inc |
| Mars Incorporated |
| H&S Bakery Inc |
| Super Bakery Inc |
| Nestlé |
| Mondelez International |
| Campbell Soup Company |
| Others |
Value Network & Pricing Analysis
Microencapsulated mineral systems displacing conventional spray-dried fortificants are redrawing procurement geography and collapsing price premiums previously attached to post-bake topical application. This substitution simultaneously concentrates premix sourcing among domestic suppliers and compresses margins for bakeries lacking enzymatic dosing infrastructure.
Pricing Analysis
After-sales revenue from nutritional reporting services bundled with fortified SKUs drives lifetime value for institutional distributors. Three-tier pricing structure across premium bioavailable, standard vitamin-fortified, and economy commodity tiers separates verified micronutrient certificate holders from compositional-only claimants. Pricing pressure stems from wheat input volatility in the Great Plains compressing margin predictability. Food service operators show least price sensitivity due to compliance audit requirements, while convenience retail channels exhibit highest elasticity.
Supply Chain Analysis
Vitamin premix production concentration among domestic U.S. and Canadian suppliers creates single-source vulnerability for B-vitamin and iron fortification blends. North American milling wheat draws from Great Plains cultivation zones, microencapsulated proteins rest on precision fermentation facilities in the U.S. Northeast, and mineral premixes hinge on Ontario-based compounders. Tariff exposure on cross-border formulations forces dual label runs. Distribution runs through specialized broadline distributors consolidating institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern this market as nutritional reporting services bundled with fortified SKUs create interoperability lock-in between distributors and institutional buyers.
For Market Incumbents: Compound defensive positioning through backward integration into vitamin premix production and captive microencapsulation capacity additions in Ontario. Precision fermentation entrants threaten protein fortification margins. Deepen channel control through exclusive nutritional reporting service contracts with urban Canadian school districts. For New Entrants and Emerging Players: Differentiate on bioavailability certification speed to capture Health Canada compliance documentation demand. White-space targets include corporate cafeterias in the U.S. Northeast corridor and direct-to-consumer mineral blend subscriptions. Thaw-and-serve fortified alternatives present the most penetrable segment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional bakery networks lacking enzymatic fortification infrastructure. Long-term viability favors operators with dual FDA-Health Canada compliance systems and in-house micronutrient testing capabilities. Watch microencapsulation patent expirations as inflection indicators for formulation cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Premix Production | Captive B-vitamin supply secures margin control against domestic supplier concentration. |
| Microencapsulation Capacity Expansion | Ontario facilities enable heat-stable protein integration without texture degradation. |
| Direct-to-Consumer Subscription Launch | Bypasses grocery slotting fees and captures recurring revenue from fitness households. |
| Nutritional Reporting Service Partnership | Bundled compliance documentation locks in institutional distributor relationships. |
| Dual-Compliance Label System Investment | Parallel FDA and Health Canada documentation enables cross-border production flexibility. |
Research Methodology
A standing panel of food science directors, institutional procurement managers at K-12 districts, broadline distributor category buyers, and regulatory affairs specialists at cross-border manufacturers provided ongoing calibration. Primary interviews combined with secondary validation against FDA fortification guideline filings, Health Canada Food and Drug Regulations updates, USDA school nutrition program procurement databases, and Nielsen retail audit data. Bottom-up volume triangulation across product type and ingredient segments converged with top-down market sizing.
Consistency checks validated outputs against external benchmarks including customs records for fortified bakery imports and SEC filings from publicly traded manufacturers. The analytical framework modeled product type, ingredient technology tier, distribution channel, and end-user application dimensions across the projection horizon. CAGRs derived from segment-level growth rate synthesis incorporating protein fortification adoption curves, institutional procurement expansion patterns, and online channel penetration trajectories.
Material uncertainties — drought cycles in Great Plains wheat belts, Health Canada bioavailability documentation rule changes, and vitamin premix supplier consolidation — sit outside the modeled envelope. Forecasts reflect assumptions about sustained institutional procurement growth and microencapsulation cost reduction. Practitioners should keep alternative scenarios live as regulatory alignment between FDA and Health Canada frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
Global Cake Mix Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Pastry Dough Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Flatbread Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Bakery Fillings Market
Bakery Products
Global Bakery Product Market
Bakery Products
No-Fat Cake Market
Bakery Products
Bread Premix Market
Bakery Products
Pastries Market