
 South America Bakery Products Market | 2026-2036
South America Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
South America Bakery Products Market Analytics
ANVISA's Good Manufacturing Practices certification for food establishments is collapsing the supplier base as smaller bakeries struggle to meet sanitation documentation and facility upgrade requirements. Grupo Bimbo SAB de CV leverages its vertically integrated distribution network to sustain shelf presence across Brazilian retail chains. M Dias Branco S.A. anchors the Northeast region with flour-to-shelf operational control. Alicorp S.A.A. differentiates through its concentrated Lima-Callao logistics hub serving Peruvian modern trade.
South America bakery products encompass wheat-based and alternative-grain formulations processed through mechanical dough development, fermentation control, and thermal baking to yield shelf-stable carbohydrate staples and indulgence items. Industrial pan bread typically achieves 24-72 hour shelf life through emulsifier and enzyme systems, while artisan variants rely on sourdough acidification for preservation without chemical additives. Breads and pastries capture the dominant value share as breakfast and snacking rituals deepen across urban households, though cookies and snacks expand faster through convenience store impulse placement and single-serve packaging formats. The Food Service channel commands premium margin pools as hotels and cafes in Buenos Aires, Santiago, and Bogotá upgrade their pastry programs to compete with European-style offerings.
Brazil's ANVISA enforces progressive sodium reduction targets and front-of-package warning labels that reshape formulation priorities and packaging real estate across the category. Argentina's national food code and Colombia's INVIMA standards add compliance layers for cross-border suppliers operating in Mercosur-adjacent trade corridors. Peru's DIGESA import registration requirements for industrial bakery inputs further filter market access. Stakeholders must monitor regulatory divergence across these national frameworks while calibrating regional production footprints to avoid redundant compliance costs.
Market Dynamics
ANVISA's sodium reduction mandates and front-of-package warning label requirements are compressing formulation timelines and forcing manufacturers to rebuild product portfolios around reformulated recipes and redesigned packaging systems.
Growth Catalysts
- Convenience store expansion:Brazil's southeastern corridor retailers are enlarging fresh bakery sections to capture commuter traffic and impulse purchasing moments.
- ANVISA labeling reform:Brazil's updated nutritional declaration standards are accelerating portfolio rationalization toward cleaner-label products with transparent ingredient sourcing.
- Enzyme system adoption:Industrial bakeries are deploying advanced emulsifier and enzyme combinations to extend shelf life without chemical preservatives.
Market Restraints
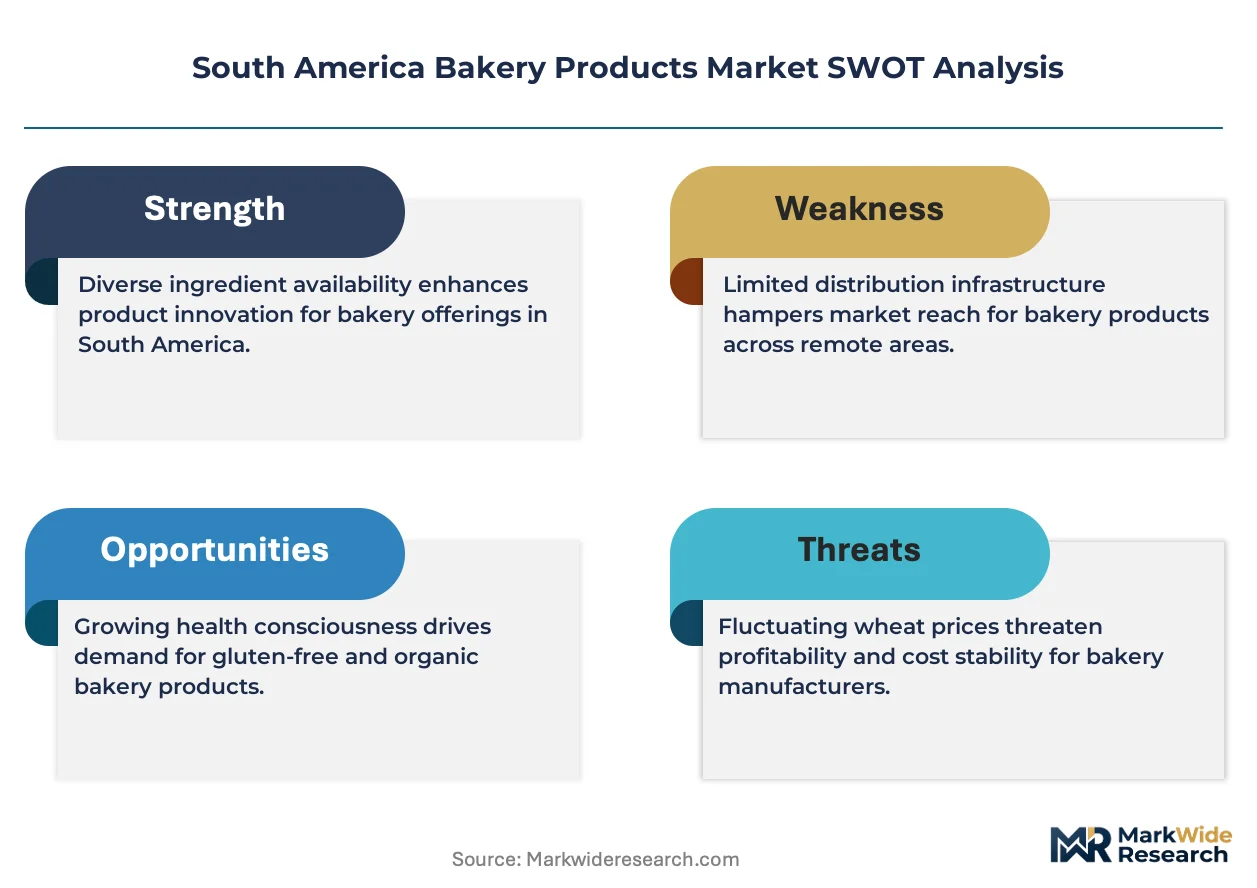
- Wheat input volatility:Argentina's grain export restrictions and currency instability create unpredictable flour cost structures for cross-border suppliers.
- Supplier base contraction:ANVISA's Good Manufacturing Practices certification requirements are eliminating smaller bakeries unable to fund facility documentation and sanitation upgrades.
- Regional regulatory fragmentation:Divergent standards across Brazil's ANVISA, Colombia's INVIMA, and Peru's DIGESA impose redundant compliance burdens on centralized production networks.
Strategic Opportunities
- Northeast Brazil penetration:Ceará and Pernambuco states show underdeveloped modern trade bakery presence relative to per capita consumption potential.
- Food service premiumization:Hotels and cafes in Buenos Aires, Santiago, and Bogotá are upgrading pastry programs to compete with European-style offerings at higher margin tiers.
- Alternative grain convergence:Cassava and quinoa flour integration with traditional wheat processing is opening formulation differentiation for gluten-adjacent positioning.
Industry Challenges
- Sanitation documentation backlog:ANVISA's certification queue is extending facility approval timelines beyond planned product launch windows.
- Reformulation capex intensity:Sodium reduction targets require capital investment in taste-masking technologies and accelerated stability testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Bakery Products Market |
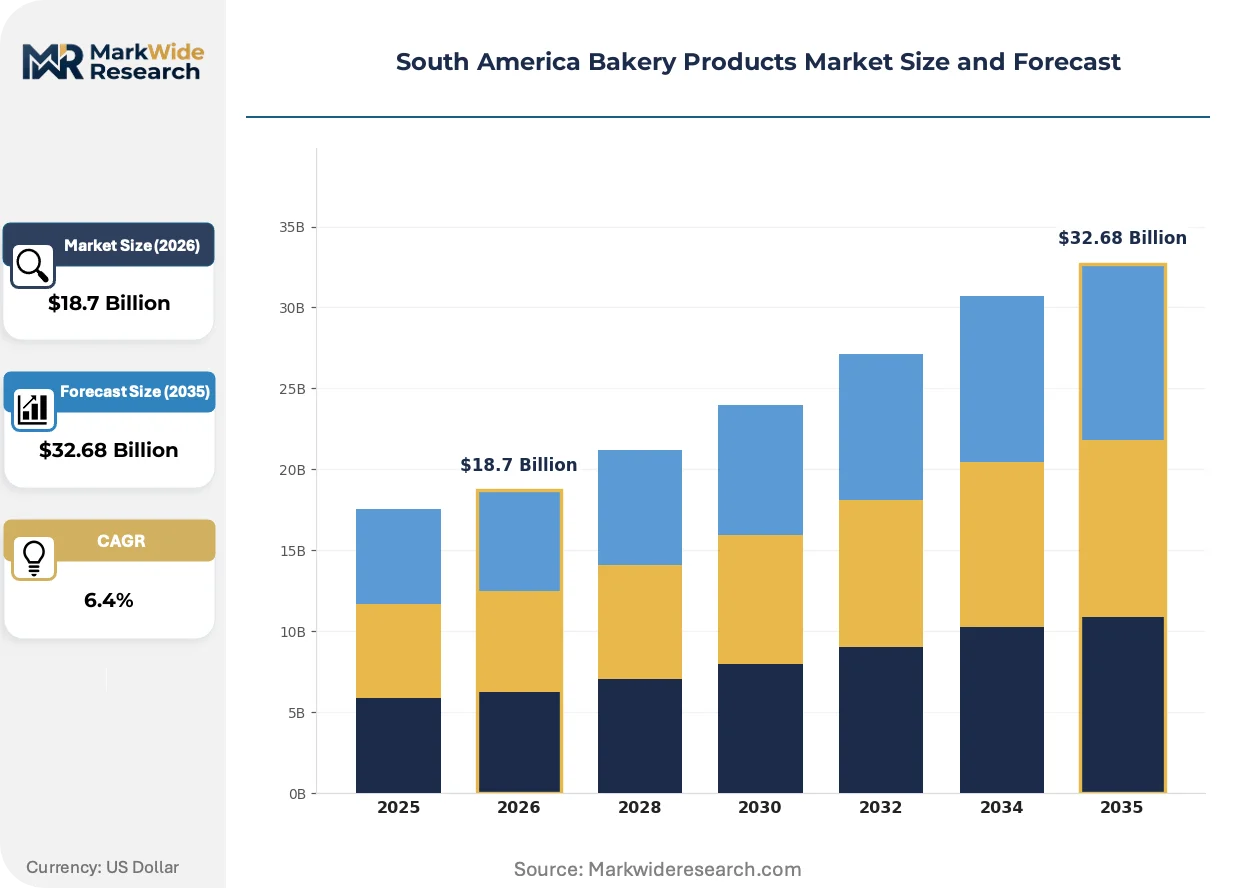
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Pastries, Cookies, Snacks Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service End User: Households, Bakeries, Hotels, Cafes Ingredient Type: Flour, Sugar, Yeast, Fillings |
| Companies Covered | Grupo Bimbo SAB de CV, M Dias Branco S.A., Europastry, S.A., Alicorp S.A.A., Grupo Arcor S.A.I.C., Bauducco, Pullman, Panamar Bakery Group, Moderna Alimentos SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Bakery Products Market Evolving Landscape
Sourdough acidification and clean-label preservation systems are displacing chemical additive dependencies across industrial production lines. Regulatory pressure on sodium and sugar content is compressing acceptable formulation ranges. Channel evolution toward convenience retail is reshaping pack size and shelf-life specifications.
Controlled fermentation technology is displacing traditional chemical preservation in industrial pan bread manufacturing. Large-scale bakeries in São Paulo and Rio de Janeiro metro areas are adopting automated sourdough systems to achieve acidification-based shelf stability without calcium propionate or sorbate additives. This shift is displacing conventional 24-72 hour chemically extended products from premium retail positioning.
ANVISA's front-of-package octagonal warning label mandate is forcing packaging redesign across Brazil's processed bakery category. Manufacturers must now reserve substantial label real estate for high-sodium, high-sugar, and high-fat alerts. Industrial bread and cookie segments are responding with accelerated reformulation to avoid triggering multiple warning symbols that depress purchase intent.
Single-serve impulse formats are capturing share from traditional family-size packaging in convenience retail channels. Convenience stores across Colombia and Argentina are prioritizing grab-and-go pastry and cookie placements over bulk bread sections. This rotation is most visible in Bogotá and Buenos Aires urban cores where commuter traffic patterns favor immediate consumption over pantry stocking.
South America Bakery Products Market Segmentation
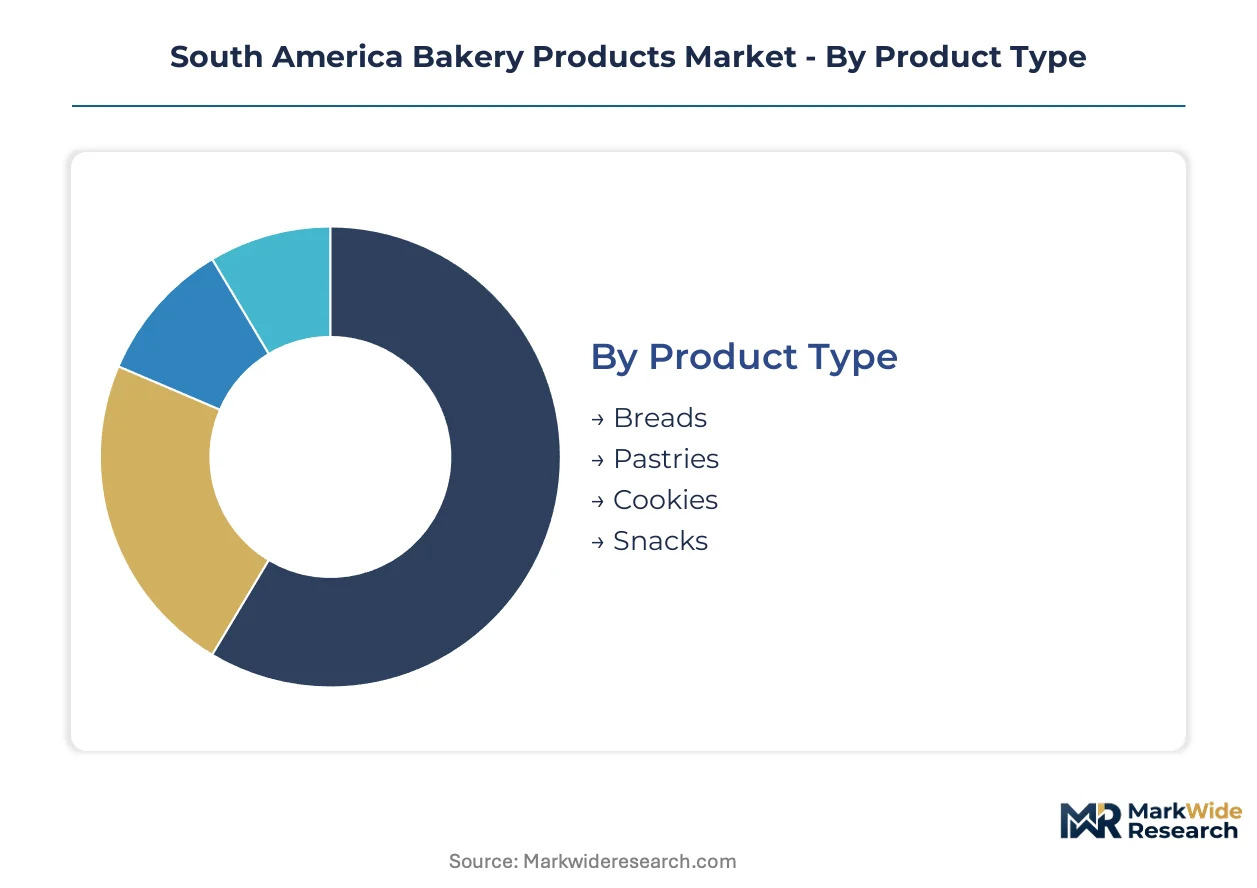
Segmentation across South America's bakery market reveals divergent margin structures, with industrial pan bread commanding volume scale while food service channels extract premium pricing. Understanding these segment boundaries enables targeted resource allocation across formulation, packaging, and channel strategies.
Product Type:
Premium margin pools concentrate in indulgence categories where brand equity and impulse purchasing override commodity pricing dynamics.
- Breads:Industrial pan bread achieves shelf stability through emulsifier and enzyme systems, dominating São Paulo and Rio de Janeiro metro area retail shelves. ANVISA's sodium reduction mandates are forcing reformulation investments across Brazilian industrial bakeries to maintain shelf presence under front-of-package warning label regimes.
- Pastries:European-style laminated dough products command food service premiums in Buenos Aires, Santiago, and Bogotá hotel pastry programs. Demand concentrates where cafes compete on visual merchandising and artisan positioning rather than price.
- Cookies:Single-serve impulse formats are displacing family-size packaging in Colombian and Argentine convenience retail channels.
- Snacks:Savory bakery-based items capture commuter traffic through grab-and-go placement in urban convenience stores.
The dominant share belongs to Breads, while Pastries is closing the gap fastest through food service premiumization.
Distribution Channel:
Channel selection determines shelf-life specifications, pack size economics, and regulatory exposure across national boundaries.
- Supermarkets:Modern trade chains in Brazil's southeastern corridor dictate packaging real estate requirements and promotional calendar intensity. ANVISA-compliant labeling and GMP certification serve as non-negotiable entry tickets for supplier negotiations.
- Convenience Stores:Fresh bakery section expansion across Brazil, Argentina, and Colombia is reshaping product mix toward immediate-consumption formats with abbreviated shelf-life requirements.
- Online Retail:Direct-to-consumer channels in Peruvian and Chilean urban centers are experimenting with subscription bread models and flash-frozen pastry delivery.
- Food Service:Hotels and institutional buyers in Bogotá and Buenos Aires specify custom formulations with traceability documentation and consistent batch performance.
Supermarkets retain the volume anchor position, though Convenience Stores is expanding most quickly through commuter-capture format innovation.
End User:
User type segmentation separates pantry-stocking behavior from immediate-consumption occasions with distinct quality and price sensitivities.
- Households:Breakfast and snacking rituals in Brazilian urban households drive recurring purchase of industrial pan bread and cookie varieties, with brand loyalty moderated by promotional intensity.
- Bakeries:Independent operators in Northeast Brazil's Ceará and Pernambuco states source flour and pre-mix inputs, facing ANVISA certification barriers that favor consolidated supplier relationships.
- Hotels:Buenos Aires and Santiago property upgrades are sourcing European-style laminated pastries through specialized distributors with cold-chain reliability.
- Cafes:Bogotá's urban core cafes prioritize visual differentiation and Instagram-compatible presentation over cost minimization.
Households dominate transaction frequency, while Hotels is climbing the fastest through premium pastry program investment.
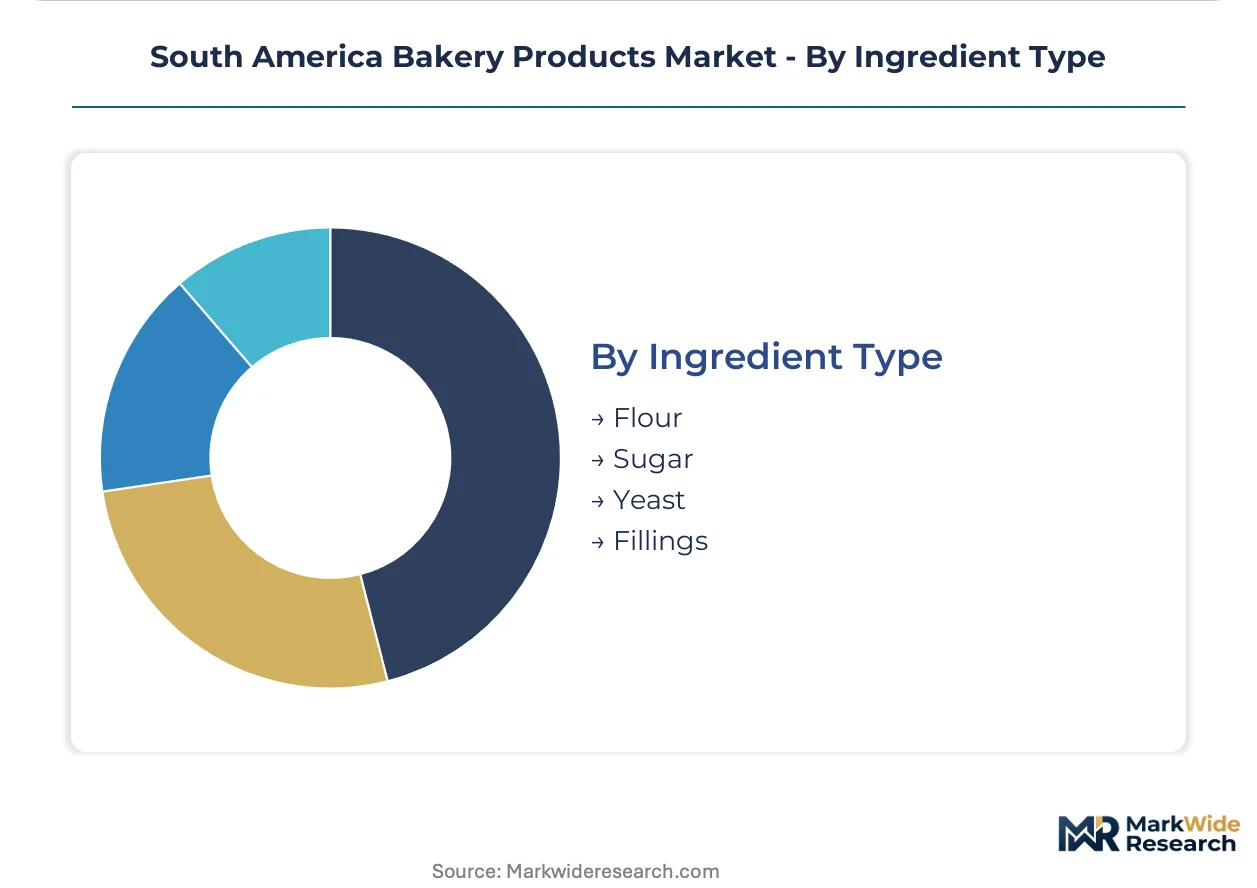
Ingredient Type:
Input segmentation tracks supply concentration risks and reformulation flexibility under tightening nutritional regulations.
- Flour:Wheat flour supply chains face Argentina's export restriction volatility and currency instability, pushing Brazilian bakers toward alternative grain experimentation. M Dias Branco's Northeast flour-to-shelf integration offers regional hedge against cross-border disruption.
- Sugar:ANVISA's front-of-package warning label thresholds are compressing permissible sugar content ranges, forcing taste-masking technology investments.
- Yeast:Controlled fermentation system adoption in São Paulo industrial bakeries is displacing chemical preservation dependencies.
- Fillings:Fruit and cream formulations face DIGESA import registration requirements in Peru, filtering supplier access.
Flour commands the largest procurement spend share, though Fillings is gaining strategic attention fastest through differentiation potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's sodium reduction mandates and front-of-package labeling reforms are redrawing competitive boundaries across South America's bakery sector. Brazil's regulatory leadership is forcing cross-border suppliers to recalibrate formulation and packaging investments. Argentina's currency volatility and Peru's import registration requirements add operational complexity for regional producers.
Brazil
São Paulo and Rio de Janeiro metro areas concentrate industrial bakery capacity and modern trade penetration. ANVISA's Good Manufacturing Practices certification requirements are eliminating smaller operators unable to fund facility upgrades. Grupo Bimbo leverages its vertically integrated distribution network to sustain shelf presence across southeastern retail chains.
Argentina
Buenos Aires anchors food service premiumization as hotels and cafes upgrade pastry programs to European-style offerings. The national food code imposes compliance layers for Mercosur-adjacent trade corridors. Grain export restrictions and currency instability create unpredictable flour cost structures for cross-border suppliers.
Colombia
Bogotá's urban core drives convenience store expansion with grab-and-go pastry placements capturing commuter traffic. INVIMA standards add regulatory complexity for imported bakery inputs. Fresh bakery section enlargement across retail chains is reshaping product mix toward immediate-consumption formats.
Peru
Lima-Callao logistics hubs serve modern trade penetration with concentrated distribution efficiency. DIGESA import registration requirements for industrial bakery inputs filter supplier access. Direct-to-consumer channels in urban centers experiment with subscription bread models and flash-frozen pastry delivery.
Chile
Santiago's food service sector demands custom formulations with traceability documentation from institutional buyers. Regulatory alignment with Mercosur-adjacent frameworks facilitates cross-border supply relationships. European-style laminated pastry demand concentrates where cafes compete on visual merchandising rather than price.
South America Bakery Products Market Competitive Landscape
Listed leaders compete with private specialists across distribution reach and formulation compliance capabilities. The supplier base contracts under ANVISA certification burdens as smaller bakeries exit. Three archetypes dominate: multinational packaged goods conglomerates with captive distribution, regional flour-to-shelf integrators controlling input costs, and specialized food service distributors with cold-chain reliability. Competitive moves center on M&A for geographic footprint and strategic partnerships for reformulation technology access.
Within the multinational conglomerate tier, Grupo Bimbo SAB de CV and Grupo Arcor S.A.I.C. exemplify scale-driven positioning across Brazilian and Argentine retail chains. M Dias Branco S.A. anchors the regional integrator archetype with Northeast Brazil flour-to-shelf operational control. Among specialized distributors, Alicorp S.A.A. occupies a position serving Peruvian modern trade through its concentrated Lima-Callao logistics infrastructure.
| Leading Market Players |
|---|
| Grupo Bimbo SAB de CV |
| M Dias Branco S.A. |
| Europastry, S.A. |
| Alicorp S.A.A. |
| Grupo Arcor S.A.I.C. |
| Bauducco |
| Pullman |
| Panamar Bakery Group |
| Moderna Alimentos SA |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty days of flour inventory held by São Paulo industrial bakeries compresses procurement flexibility while amplifying exposure to Argentina's export restriction cycles and currency swings. This working capital intensity concentrates pricing power among M Dias Branco and Grupo Bimbo, whose captive milling operations buffer margin volatility that smaller competitors cannot absorb.
Pricing Analysis
Certification level under ANVISA's Good Manufacturing Practices regime creates the primary spread between premium and commodity tiers. Three-tier pricing structure across GMP-certified, standard industrial, and artisan economy levels stratifies the Brazilian market, with food service buyers in Buenos Aires and Santiago showing lowest price sensitivity for traceability documentation. Cost compression in the standard industrial tier is intensifying as enzyme system investments for sodium-compliant reformulation flow through to contract renegotiations with modern trade chains.
Supply Chain Analysis
Strategic stockpiling of Argentine wheat during harvest windows dominates inventory strategy, though just-in-time enzyme and emulsifier deliveries from European suppliers reduce working capital drag. Supply concentrates in Argentina for wheat, Brazil for industrial processing capacity, and Peru for quinoa and cassava alternative grain experimentation. Downstream distribution runs through Grupo Bimbo's captive retail network and specialized food service cold-chain operators serving Bogotá and Santiago hotels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity deepens as ANVISA certification requirements eliminate smaller bakeries, creating acquisition targets and white-space openings for compliant operators. Convenience store channel expansion across Brazil's Northeast and Colombia's urban corridors generates niche demand for immediate-consumption formats that legacy industrial bakeries underserve.
For Market Incumbents: Shield shelf position in São Paulo and Rio de Janeiro metro areas by accelerating GMP certification completion for remaining facilities before ANVISA's documentation backlog extends further. Backward integration into alternative grain milling in Ceará and Pernambuco hedges wheat import volatility while capturing Northeast penetration upside. For New Entrants and Emerging Players: ANVISA certification fast-track through partnership with existing GMP-compliant co-manufacturers unlocks immediate modern trade access without facility capex. Target Colombia's INVIMA-regulated convenience store channel with single-serve pastry formats, leveraging Bogotá's commuter density and underdeveloped fresh bakery sections relative to Brazilian benchmarks. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates divesting non-core South American bakery assets amid portfolio rationalization. Mid-cap Brazilian bakeries with partial GMP compliance and established Northeast distribution relationships represent the most defensible acquisition profile. Watch ANVISA's certification queue clearance rate as the inflection signal for supply base contraction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA GMP Certification Completion | Unlocks modern trade negotiations with Brazilian retail chains requiring documentation. |
| Alternative Grain Formulation Investment | Positions products outside ANVISA's front-of-package warning label thresholds for sodium. |
| Food Service Cold-Chain Partnership | Captures premium margin pools in Buenos Aires and Santiago hotel pastry programs. |
| Northeast Brazil Distribution Expansion | Addresses underpenetrated Ceará and Pernambuco states with localized production. |
| Controlled Fermentation Technology Adoption | Displaces chemical preservatives in São Paulo industrial bakeries for clean-label positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, Brazilian customs trade records, and modern trade promotional calendars. Interviews with industrial bakery plant managers, retail category buyers, food service procurement directors, and flour mill procurement leads informed demand-side calibration. Top-down market sizing from per capita consumption benchmarks triangulated against bottom-up capacity estimates from facility-level production data.
Segmentation dimensions modeled span product type, distribution channel, end user, and ingredient composition across the projection horizon. CAGRs derive from regression analysis against macroeconomic indicators and regulatory implementation timelines. Forecast inputs incorporate ANVISA sodium reduction phase-in schedules and convenience store format expansion pipelines reported by retail operators.
Underlying assumptions cover stable ANVISA enforcement intensity and continued Argentine wheat export availability, with deviation risk concentrated in currency volatility and certification queue extensions. Revision becomes warranted when ANVISA's facility approval timelines exceed six months or Argentine export restrictions tighten beyond historical ranges.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Pastry Dough Market
Bakery Products
Gluten-Free Bakery Products Market
Bakery Products
Low Fat Muffin Market
Bakery Products
South America Ice Cream Market
Bakery Products
India Cake Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market
Bakery Products
Matcha Cookie Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Waffle Market