
 North America Bakery Products Market | 2026-2036
North America Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bakery Products Market Analytics
Commercial baking labor shortages across the United States and Canada are unwinding production capacity at regional facilities. Grupo Bimbo leverages its vertically integrated flour milling network to stabilize input costs across its North American plant footprint. Flowers Foods sustains direct-store-delivery dominance in the southeastern United States through a captive distribution infrastructure that competitors struggle to replicate. Mondelēz International differentiates through R&D intensity in shelf-stable snack cakes, occupying a premium position in convenience channel resets.
North America bakery products comprise wheat-based and alternative-grain formulations manufactured through sponge-and-dough or straight-dough processes, with controlled fermentation and thermal treatment yielding specific crumb structure, moisture retention, and shelf stability for retail and food service distribution. Bread remains the volume anchor across supermarkets and convenience stores, though cookies capture disproportionate margin contribution through gift-packaging and seasonal assortment strategies. Online retailers represent the fastest-growing distribution channel, as fulfillment networks adapt to ship fragile pastry formats without quality degradation.
The FDA governs ingredient declarations and allergen labeling under FSMA, while Health Canada enforces parallel compositional standards through the Safe Food for Canadians Regulations, collectively elevating compliance costs for cross-border suppliers. The USDA's bioengineered food disclosure standard and evolving state-level sodium reduction targets in California and New York further constrain formulation flexibility. Stakeholders must monitor how state-level patchworks of packaging and ingredient rules reshape regional production footprints and capital allocation decisions.
Market Dynamics
Labor scarcity across U.S. and Canadian commercial bakeries is compressing production capacity while FDA added-sugar labeling mandates force rapid reformulation of legacy product lines.
Growth Catalysts
- Clean-label reformulation:Health Canada and FDA parallel enforcement of added-sugar disclosure is accelerating ingredient transparency investments across North American manufacturing facilities.
- Food service SKU expansion:U.S. Northeast corridor operators are increasing bread and pastry menu placements to capture dense urban breakfast and snacking occasions.
- E-commerce fulfillment adaptation:Packaging engineers are developing shock-resistant pastry formats that withstand last-mile shipping without crumb degradation or moisture loss.
Market Restraints
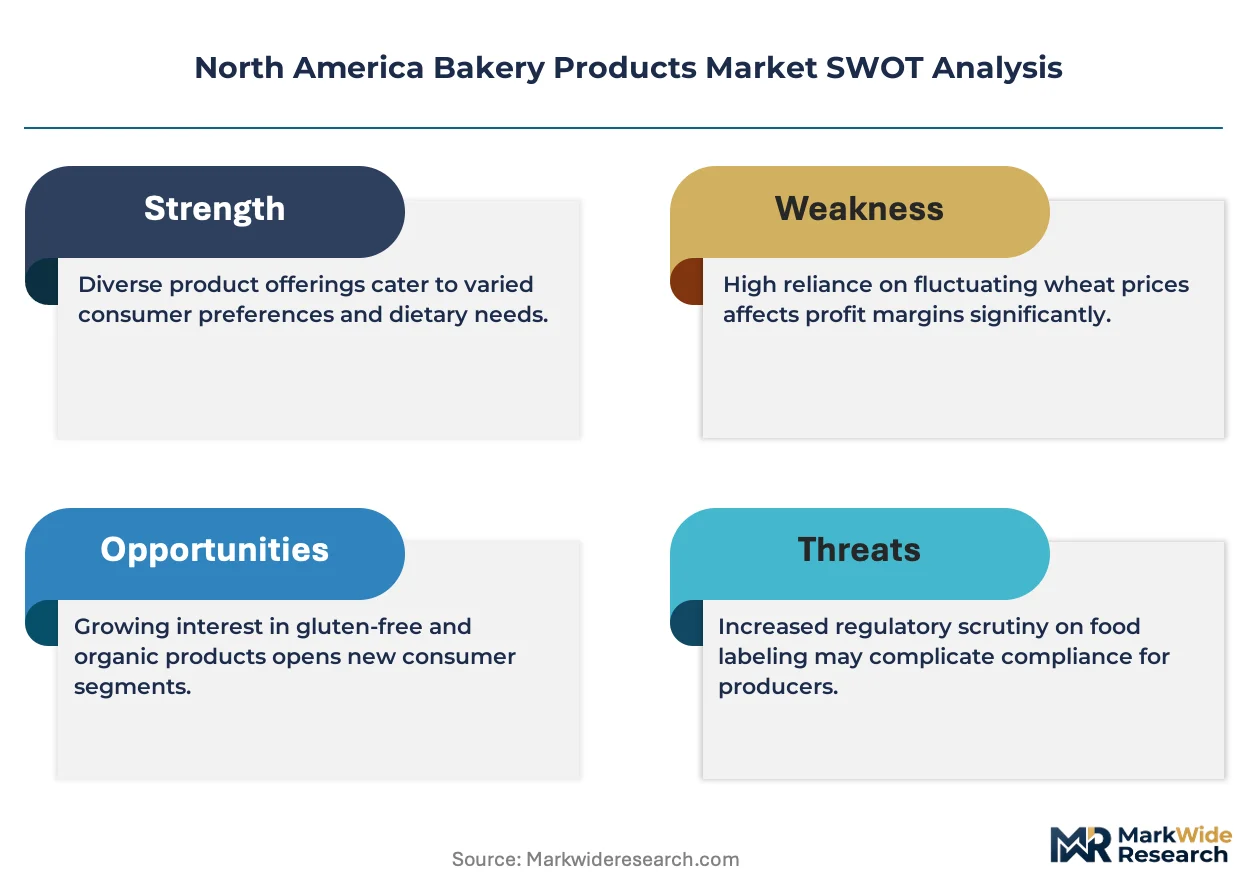
- Wheat input volatility:Regional flour milling concentration in the Great Plains exposes bakers to weather-driven supply disruptions and price spikes.
- Cross-border compliance friction:Divergent FDA and Health Canada allergen labeling thresholds force dual-label SKUs that inflate packaging complexity and inventory costs.
- Plant-based fat substitution limits:Technical barriers in mimicking butter's aeration and shelf-stability properties constrain clean-label cookie and pastry development.
Strategic Opportunities
- Canadian prairie organic wheat:Saskatchewan and Alberta certified organic grain production offers untapped supply for premium positioning in U.S. coastal markets.
- California sodium reduction mandates:First-mover reformulation to meet Assembly Bill 418 thresholds creates regulatory-compliant product lines exportable to other restrictive jurisdictions.
- Direct-to-consumer subscription:Weekly artisan bread delivery models bypass conventional retail slotting fees and build recurring revenue streams in metropolitan zones.
Industry Challenges
- Skilled mixer and oven operator scarcity:Retirement waves in U.S. heartland baking facilities outpace vocational training pipeline output, constraining line speed optimization.
- Legacy equipment retrofit costs:Installing continuous mixing systems to replace batch processes demands capital deployment that mid-tier bakeries struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bakery Products Market |
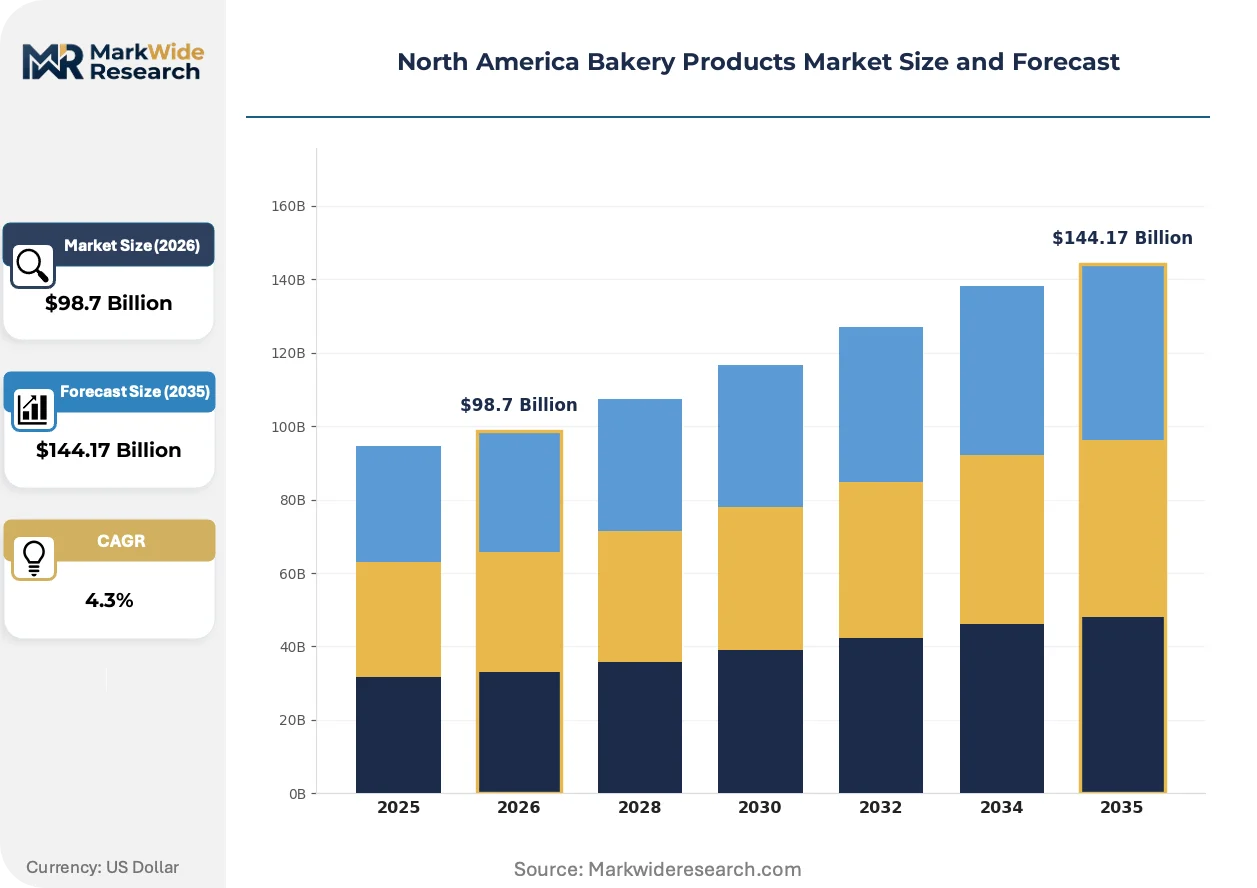
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $144.17 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cakes, Cookies Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Food Service Customer Type: Retail Consumers, Wholesalers, Food Manufacturers, Bakeries Ingredient Type: Flour, Sweeteners, Fats, Additives |
| Companies Covered | McKee Foods, Mondelēz International, Grupo Bimbo, The J.M. Smucker Company, Campbell Soup Company, Flowers Foods, General Mills, Rise Baking Company, Hostess Brands, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bakery Products Market Evolving Landscape
Formulation science and distribution infrastructure are converging to reshape how North American bakeries compete on freshness claims, regulatory compliance, and channel access.
Sourdough fermentation automation is displacing traditional sponge-and-dough timelines in large-scale facilities. Industrial bakers in the U.S. Midwest are deploying sensor-controlled culture propagation systems that compress 24-hour fermentation cycles to 8 hours without flavor degradation. This compression is displacing artisan-positioned regional competitors who rely on extended fermentation as their sole differentiation lever.
FDA updated Nutrition Facts requirements for added sugars are forcing reformulation of legacy sweet baked goods. Manufacturers must now disclose added versus naturally occurring sugars, compelling reformulators to reduce sucrose and invert syrups in favor of fruit purees and enzyme-modified starches. Cookie and snack cake segments face the steepest label redesign costs as they rebalance sweetness profiles without alienating core consumers.
Food service procurement teams are consolidating supplier rosters to reduce audit burden and secure volume commitments. Large U.S. restaurant chains are shifting from multi-vendor bread sourcing to single-source regional partnerships with guaranteed supply continuity. This consolidation is most visible in the quick-service sandwich segment, where national operators now demand bakery partners operate within 300-mile delivery radii to ensure day-fresh product standards.
North America Bakery Products Market Segmentation
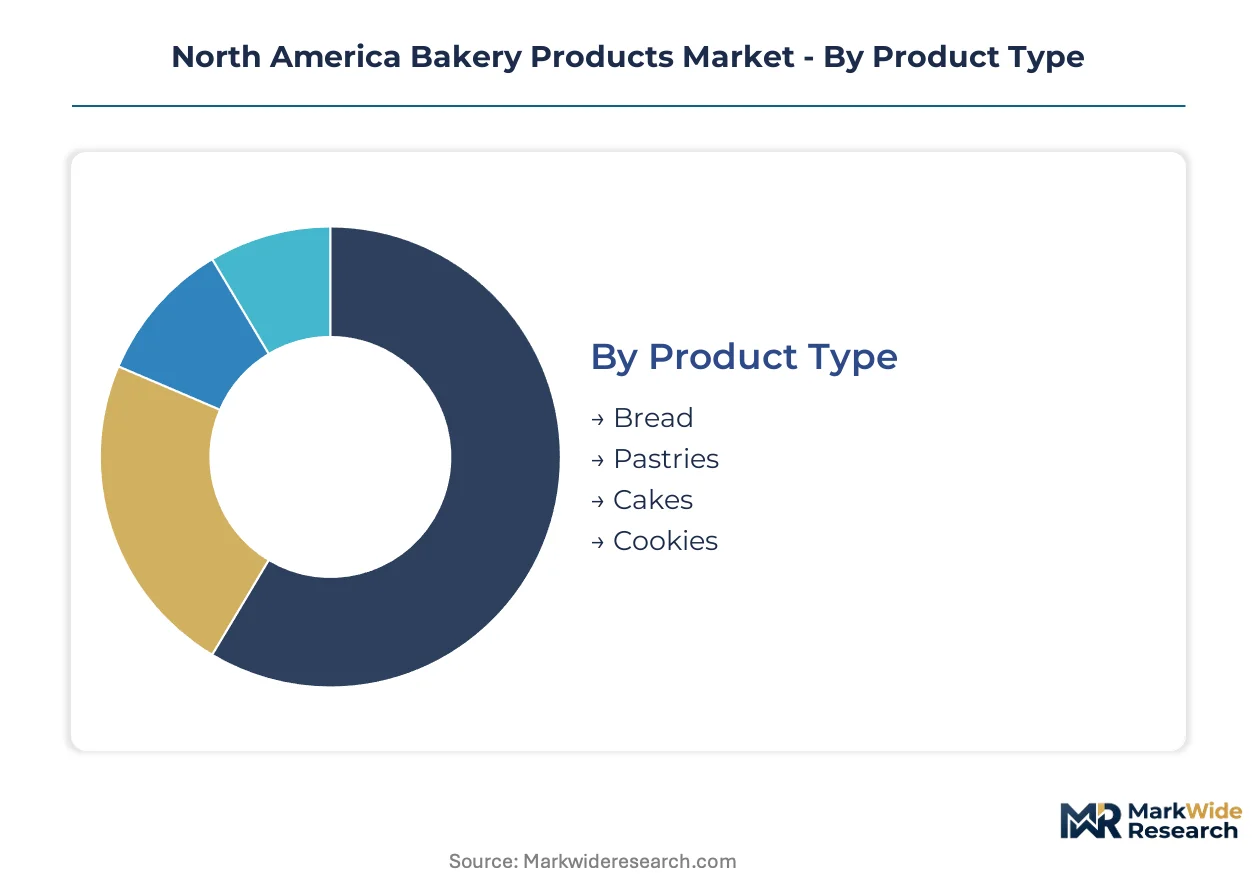
Segmentation in the North America bakery products market exposes where substitution pressures and channel shifts are redrawing competitive boundaries. Understanding how product formats, distribution pathways, and ingredient specifications partition demand reveals where reformulation investments and logistics adaptations will yield returns.
Product Type:
Bread faces the most intense substitute threat from low-cohydrate wraps and vegetable-based alternatives, while pastries and cakes confront frozen dessert and confection encroachment.
- Bread:Sponge-and-dough or straight-dough processes yield loaf structures ranging from dense artisan ryes to enriched sandwich breads. U.S. Northeast corridor supermarkets and quick-service sandwich chains sustain volume, though FDA added-sugar disclosure is forcing reformulation of sweetened varieties like Hawaiian and brioche.
- Pastries:Laminated and chemically leavened formats including croissants, danishes, and puff products with specific butter-fat layering requirements. Food service operators in dense urban Canadian and U.S. markets are expanding breakfast pastry SKUs, though labor-intensive lamination constrains scalable production.
- Cakes:Aerated, chemically leavened celebration and snacking formats with extended shelf-life through emulsifier systems.
- Cookies:Drop, molded, and wire-cut varieties with moisture content calibrated for crisp or chewy texture profiles.
Bread anchors the volume base while pastries gain share at the steepest rate.
Distribution Channel:
Channel segmentation maps how fulfillment economics and freshness requirements stratify access to end consumers.
- Supermarkets:High-velocity bread and cookie categories dominate perimeter bakery and center-store aisles, with slotting fees and trade promotion calendars shaping supplier economics. U.S. Southeast direct-store-delivery networks maintain day-fresh standards that centralized distribution struggles to match.
- Online Retailers:Fragile pastry formats now ship through shock-resistant packaging innovations, with weekly subscription artisan bread models bypassing conventional retail slotting structures in metropolitan zones.
- Convenience Stores:Shelf-stable snack cakes and single-serve cookie packs target immediate consumption occasions.
- Food Service:Institutional and commercial bakery procurement with specified delivery radii and audit requirements.
Supermarkets retain the largest revenue footprint while online retailers are expanding most quickly.
Customer Type:
Customer segmentation distinguishes between price-sensitive volume buyers and specification-driven premium purchasers.
- Retail Consumers:Individual and household purchasers making brand and format selections based on label claims, price points, and convenience. Clean-label and organic wheat positioning from Saskatchewan and Alberta certified production commands premiums in U.S. coastal markets.
- Food Manufacturers:Industrial buyers incorporating bakery components into finished consumer goods, requiring precise moisture and shelf-stability specifications.
- Wholesalers:Intermediate distributors aggregating volume for redistribution to smaller retail and food service accounts.
- Bakeries:Independent and artisan producers sourcing ingredients and semi-finished goods for final production.
Retail consumers drive absolute volume while food manufacturers deliver the most stable contract structures.
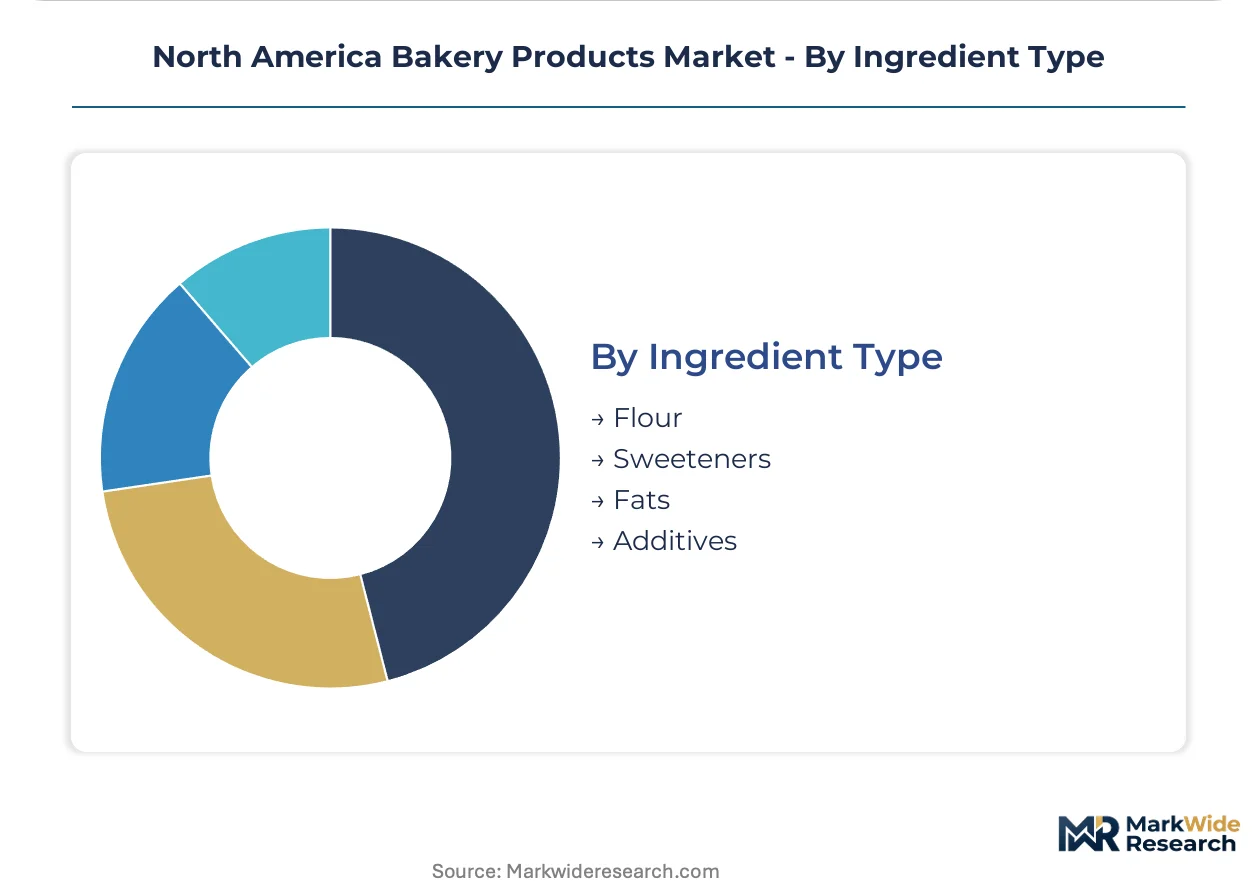
Ingredient Type:
Ingredient segmentation tracks how input cost volatility and regulatory disclosure requirements are restructuring formulation priorities.
- Flour:Wheat-based and alternative-grain milled products with protein content and ash specifications determining gluten development and crumb structure. Great Plains concentration exposes bakers to weather-driven supply disruptions.
- Sweeteners:Sucrose, invert syrups, and alternative systems including fruit purees and enzyme-modified starches. FDA added-sugar labeling mandates are accelerating displacement of traditional caloric sweeteners in cookie and snack cake segments.
- Fats:Butter, shortening, and oil systems providing aeration, mouthfeel, and shelf-stability.
- Additives:Emulsifiers, preservatives, and conditioning agents extending shelf life and standardizing process tolerance.
Flour constitutes the largest input cost category while sweeteners face the most intense reformulation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA labeling mandates and Health Canada compositional standards anchor regulatory complexity across the dominant United States and Canadian markets. Mexico rounds out the trilateral coverage with distinct procurement patterns tied to food service and retail modernization.
United States
Quick-service sandwich chains and supermarket perimeter bakeries drive bread and pastry volume in the Northeast corridor and Southeast. The FDA's updated Nutrition Facts requirements for added sugars force reformulation of sweetened loaves and snack cakes. Chicago and Minneapolis-St. Paul host industrial baking clusters where automated sourdough systems compress fermentation timelines.
Canada
Urban breakfast pastry expansion and clean-label organic wheat demand concentrate in Toronto, Montreal, and Vancouver metropolitan zones. Health Canada enforces allergen labeling thresholds through the Safe Food for Canadians Regulations that diverge from FDA standards. Saskatchewan and Alberta certified organic grain production supplies premium positioning for coastal U.S. export.
Mexico
Traditional panadería formats coexist with modern retail bakery penetration in Mexico City and Guadalajara. The country's national food safety regulator enforces compositional standards that facilitate cross-border ingredient trade with U.S. facilities. Monterrey and Querétaro industrial corridors attract North American bakery component manufacturing for regional redistribution.
California
Assembly Bill 418 sodium reduction targets and clean-label consumer preferences reshape formulation priorities for bakers supplying Pacific Coast markets. Los Angeles and San Francisco metropolitan areas sustain direct-to-consumer artisan bread subscription models. The state's packaging waste regulations accelerate compostable wrapper adoption for e-commerce pastry shipments.
New York Metro
High-density urban snacking occasions and food service procurement consolidation sustain per-capita bread and pastry consumption above national averages. State-level sodium reduction initiatives parallel California mandates, creating dual-compliance pressure for regional suppliers. Brooklyn and Queens host independent artisan bakeries competing with automated sourdough facilities on freshness claims.
North America Bakery Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-scale regional operators filling geographic gaps. The structure rewards captive distribution infrastructure and backward integration into flour milling. Three archetypes dominate: vertically integrated giants with national DSD networks, R&D-intensive shelf-stable snack specialists, and artisan-positioned regional challengers. Competitive moves concentrate on direct-store-delivery radius expansion and automated fermentation technology licensing.
Within the integrated multinational tier, Grupo Bimbo and Mondelēz International exemplify divergent scale strategies. Grupo Bimbo anchors Mexican-origin vertical integration with captive flour milling across North American plant footprints. Mondelēz International occupies the premium shelf-stable snacking position through R&D intensity in convenience channel resets. Among U.S.-based specialists, Flowers Foods represents the DSD infrastructure archetype with southeastern concentration that competitors struggle to replicate.
| Leading Market Players |
|---|
| McKee Foods |
| Mondelēz International |
| Grupo Bimbo |
| The J.M. Smucker Company |
| Campbell Soup Company |
| Flowers Foods |
| General Mills |
| Rise Baking Company |
| Hostess Brands |
| Others |
Value Network & Pricing Analysis
FDA's updated Nutrition Facts disclosure for added sugars gates both supplier qualification and price differentiation simultaneously. Bakers must reformulate legacy sweetened lines to maintain shelf placement, while organic wheat certification from Canadian prairie operations commands coastal premiums. This regulatory threshold stratifies the market into compliant reformulated tiers and stranded conventional inventory.
Pricing Analysis
Coastal U.S. markets absorb 15-25% premiums for Saskatchewan and Alberta certified organic wheat against Great Plains conventional flour. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost. Pricing pressure stems from labor scarcity compressing margins at mid-tier facilities. Quick-service chains exhibit highest price sensitivity through consolidated procurement, while direct-to-consumer subscription buyers tolerate premium positioning for freshness claims.
Supply Chain Analysis
Just-in-time flour delivery dominates industrial baking, though strategic organic wheat stockpiling is emerging among premium-positioned facilities. Supply concentrates in the United States, Canada, and Mexico under USMCA trade architecture. The chain draws from Great Plains wheat, Canadian prairie organic grain, and Mexican food service redistribution hubs. Single-source vulnerability concentrates in regional flour milling. Distribution runs through direct-store-delivery networks in the U.S. Southeast and centralized fulfillment for e-commerce pastry channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated sourdough fermentation systems are disrupting freshness-claim competition and forcing capital deployment decisions across facility footprints. FDA labeling mandates accelerate this technological inflection by disqualifying reformulation-laggards from retail placement.
For Market Incumbents: Fortify DSD radius coverage through captive distribution infrastructure expansion in the U.S. Southeast and Northeast corridor. Secure backward integration into Canadian prairie organic wheat supply to defend premium positioning against artisan challengers. Accelerate continuous mixing system retrofit to offset skilled operator scarcity constraining line speeds. For New Entrants and Emerging Players: Anchor in direct-to-consumer artisan bread subscription models bypassing supermarket slotting fees in Los Angeles and San Francisco metropolitan zones. Target California sodium reduction compliance as first-mover positioning exportable to New York Metro dual-compliance pressure. Pursue food service procurement consolidation through guaranteed 300-mile delivery radius contracts. For Investors and Strategic Acquirers: FDA added-sugar disclosure deadlines reshape the acquisition landscape by stranding reformulation-deficient legacy portfolios. Long-term viability centers on facilities with automated fermentation technology and organic wheat supply contracts. Monitor Health Canada-Safe Food for Canadians Regulations enforcement as cross-border compliance friction indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sourdough Fermentation Deployment | Industrial bakers compress 24-hour cycles to 8 hours without flavor degradation, displacing artisan competitors. |
| Canadian Prairie Organic Wheat Integration | Backward integration into Saskatchewan and Alberta certified production secures coastal premium positioning. |
| Direct-to-Consumer Subscription Launch | Weekly artisan bread delivery bypasses retail slotting fees and builds recurring revenue in metropolitan zones. |
| California Sodium Reduction Compliance | Assembly Bill 418 first-mover reformulation creates exportable product lines for restrictive jurisdictions. |
| Food Service Procurement Consolidation | Single-source regional partnerships within 300-mile radii secure quick-service sandwich chain volume commitments. |
Research Methodology
The analysis maps bread, pastry, cake, and cookie sub-sectors, each validated through commercial bakery operations directors, food service procurement managers, flour milling supply planners, and retail category buyers. Primary interviews triangulate against FDA filing databases, USDA commodity reports, Health Canada regulatory guidance, and Nielsen retail audit data. Bottom-up facility capacity estimates reconcile with top-down consumption models across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including customs trade flows and industry association production surveys. The projection framework segments by product format, distribution channel, ingredient specification, and customer archetype across the modeling period. CAGRs derive from trend extrapolation adjusted for regulatory inflection points and technology adoption curves, with labor scarcity and wheat input volatility as specific forecast inputs.
Material uncertainties — weather-driven supply disruptions, state-level sodium reduction patchwork expansion, and skilled operator training pipeline gaps — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and e-commerce packaging innovation adoption. Revision becomes warranted when cross-border compliance friction thresholds trigger dual-label SKU proliferation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread and Baked Food Market
Bakery Products
Specialty Bakery Market
Bakery Products
United States Cookies Market
Bakery Products
Sourdough Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Premixed Bread Flour Market
Bakery Products
Laminated Dough Market
Bakery Products
Baked Foods Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Bakery Improvers Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Gluten-Free Pizza Crust Market
Bakery Products
No-Fat Cake Market