
 Bread Slicer Blades Market | 2026-2036
Bread Slicer Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Slicer Blades Market Insights
The capability gap between capital-heavy European manufacturers and smaller Asian suppliers is collapsing as automated grinding and laser-hardening equipment becomes more accessible. Berkel leverages its Italian engineering heritage to sustain premium positioning in artisan bakery segments. Hobart Corporation anchors North American demand through integrated slicer-blade systems and extensive foodservice distribution. KASCO specializes in replacement blade programs that dominate aftermarket channels for independent bakeries and delis.
Bread slicer blades are precision cutting tools, typically manufactured from hardened stainless steel or high-carbon alloys with tooth geometries ranging from scalloped serrations for crusty loaves to straight edges for uniform sandwich slices, designed to maintain edge integrity through thousands of cutting cycles in high-throughput environments. Serrated blade configurations lead commercial installations due to superior performance on crusty artisan breads, while ceramic material variants represent the fastest-growing segment as bakers seek reduced friction and extended sharpening intervals. The standard size category remains the mature volume anchor, though custom blade specifications capture disproportionate margin pools from OEM slicer manufacturers seeking differentiated cutting performance.
FDA food-contact material regulations and EU Framework Regulation 1935/2004 govern stainless steel composition and surface finish requirements, compelling manufacturers to certify chromium and nickel content limits while maintaining NSF/ANSI sanitation standards for commercial food equipment. BIS certification requirements in India and GB standards in China add compliance layers for exporters targeting these production geographies. Stakeholders must monitor evolving PFAS restrictions and sustainability mandates that could reshape coating technologies and blade lifecycle expectations across major baking equipment markets.
Market Dynamics
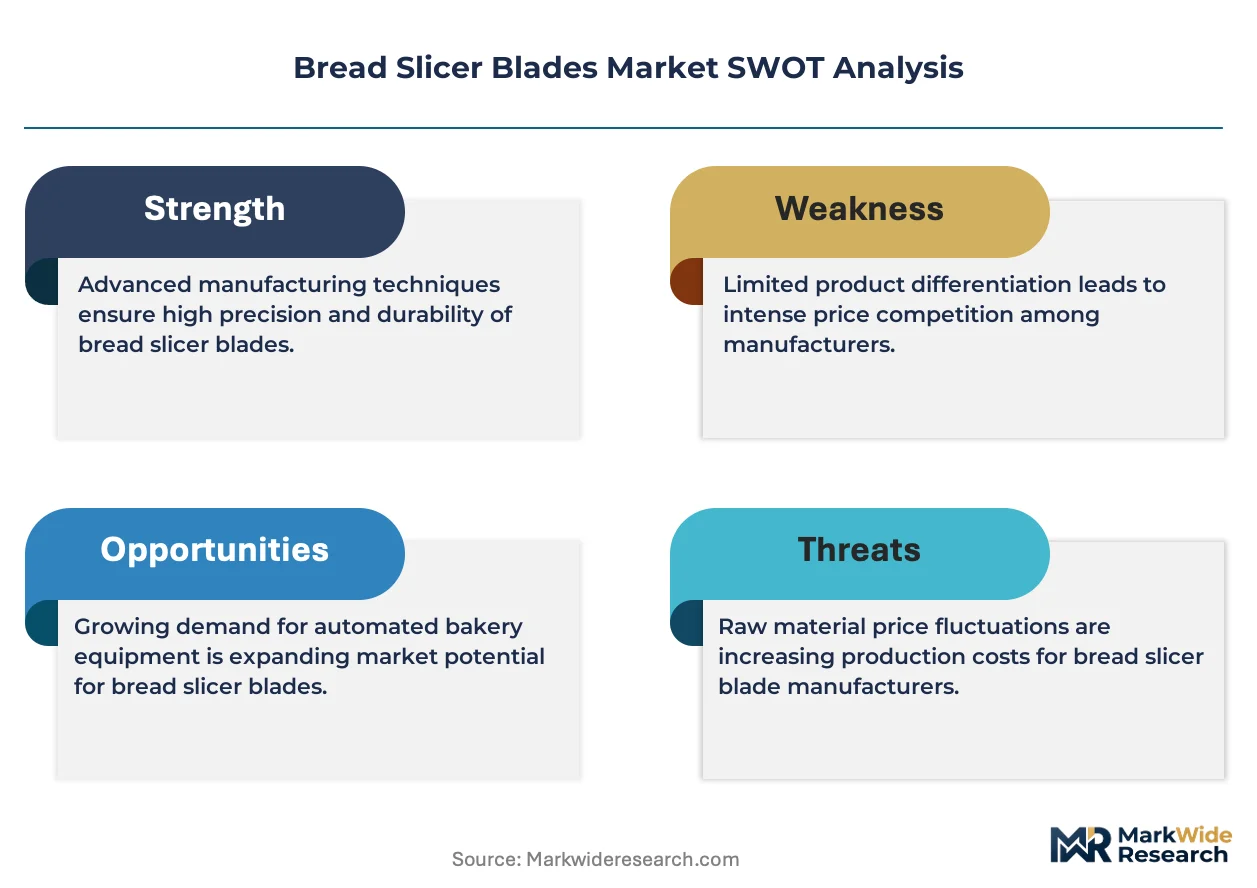
Automated grinding and laser-hardening equipment accessibility is collapsing the capability gap between capital-heavy European manufacturers and smaller Asian suppliers, redistributing competitive advantage across the bread slicer blades supply base.
Growth Catalysts
- EU Framework Regulation 1935/2004:Tightened food-grade stainless steel requirements compel bakeries to upgrade blade fleets, creating replacement demand cycles.
- Artisan bread production:Commercial bakeries expanding crusty loaf portfolios drive serrated blade configurations into high-throughput installations.
- Solingen manufacturing cluster:Germany's blade-making heritage concentrates precision engineering talent and heat-treatment expertise for premium OEM supply.
Market Restraints
- Nickel and chromium price volatility:Food-grade stainless steel input costs fluctuate with mining supply disruptions, compressing margin predictability for blade fabricators.
- Replacement blade aftermarket concentration:Independent bakeries and delis depend on fragmented distributor networks, creating pricing power asymmetries.
- Ceramic material brittleness:Reduced-friction ceramic variants face chipping limitations on frozen bread applications, constraining segment expansion.
Strategic Opportunities
- India BIS certification pathway:Exporters establishing compliant production lines capture emerging commercial bakery modernization in South Asia.
- PFAS restriction tailwinds:Anticipated EPA and ECHA coating mandates position fluorine-free surface treatment developers for regulatory-first mover advantage.
- Direct-to-bakery digital channels:E-procurement platforms displace traditional distributor markups for independent operators seeking transparent blade specifications.
Industry Challenges
- Precision grinding skill scarcity:Automated equipment reduces but does not eliminate demand for technicians capable of tooth geometry calibration.
- NSF/ANSI 169 certification timelines:Commercial food equipment sanitation standards require extended validation periods for new blade surface finishes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Slicer Blades Market |
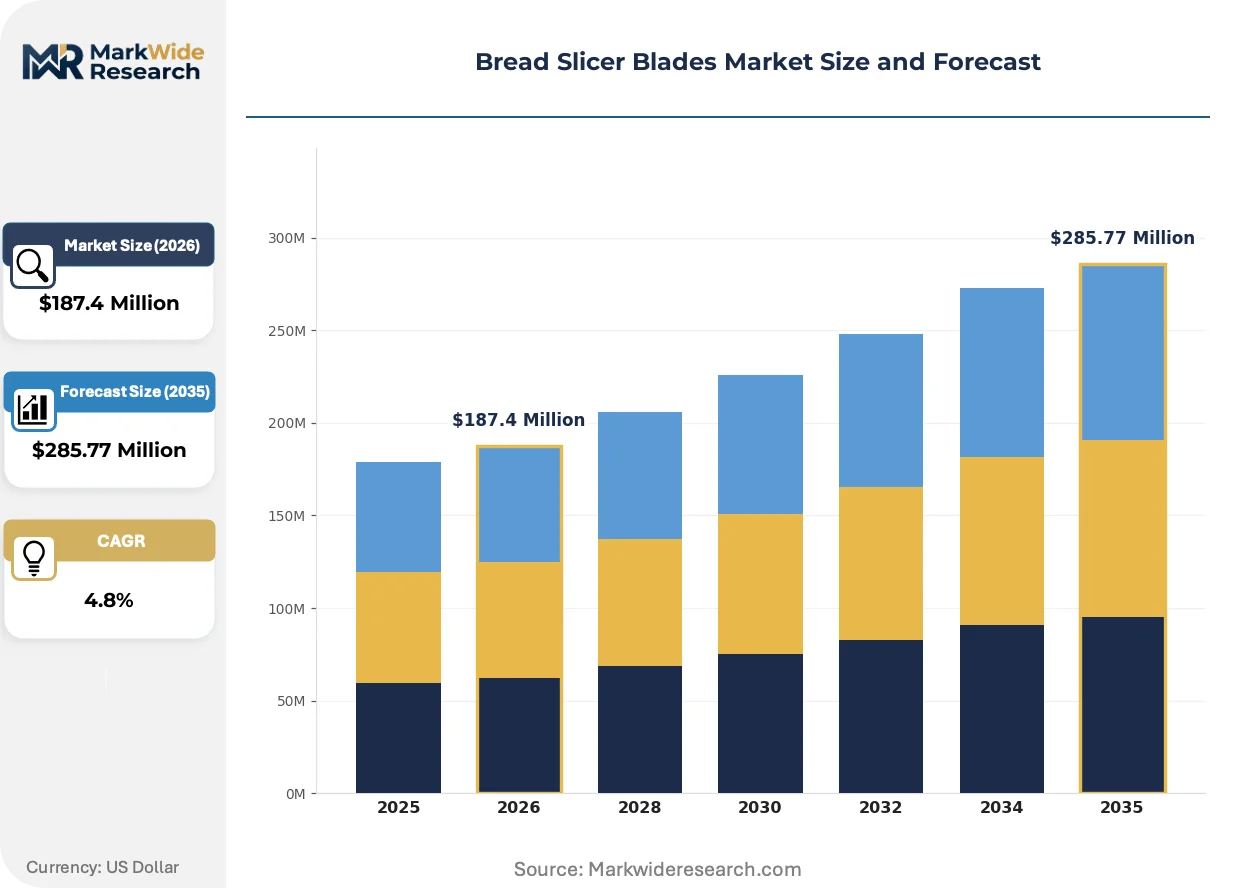
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Blade Type: Serrated, Straight, Offset, Circular Material: Stainless Steel, Carbon Steel, Ceramic, Aluminum Application: Commercial Bakeries, Household Use, Food Processing, Catering Services Size: Standard, Long, Mini, Custom |
| Companies Covered | Berkel, Sammic, Bizerba, MECALBEK, Hobart Corporation, Oliver, KASCO, ADS PRECISION, Debra-Blades, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Slicer Blades Market Trends and Innovations
Ceramic coating technologies and digital procurement platforms are actively redistributing competitive advantage across material tiers and distribution channels in bread slicer blade supply.
Laser-hardened stainless steel tooth geometries is bifurcating the mid-market blade segment. Artisan bakeries with moderate throughput volumes adopt these treatments to extend sharpening intervals without premium ceramic pricing. The technology is bifurcating supplier tiers by enabling automated equipment operators to match European heat-treatment quality benchmarks.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating fluorine-free coating development timelines. Blade manufacturers reformulate surface treatments to eliminate PFAS while maintaining release properties for sticky dough residues. Commercial bakeries in Germany and France face the most compressed compliance deadlines, driving early adoption of certified alternatives.
After-sales service unbundling is fragmenting traditional distributor relationships. Large commercial bakery chains now procure blades directly from manufacturers while contracting sharpening and maintenance separately. This pattern concentrates in North American foodservice operations with centralized procurement functions and established vendor-managed inventory systems.
Bread Slicer Blades Market Segmentation
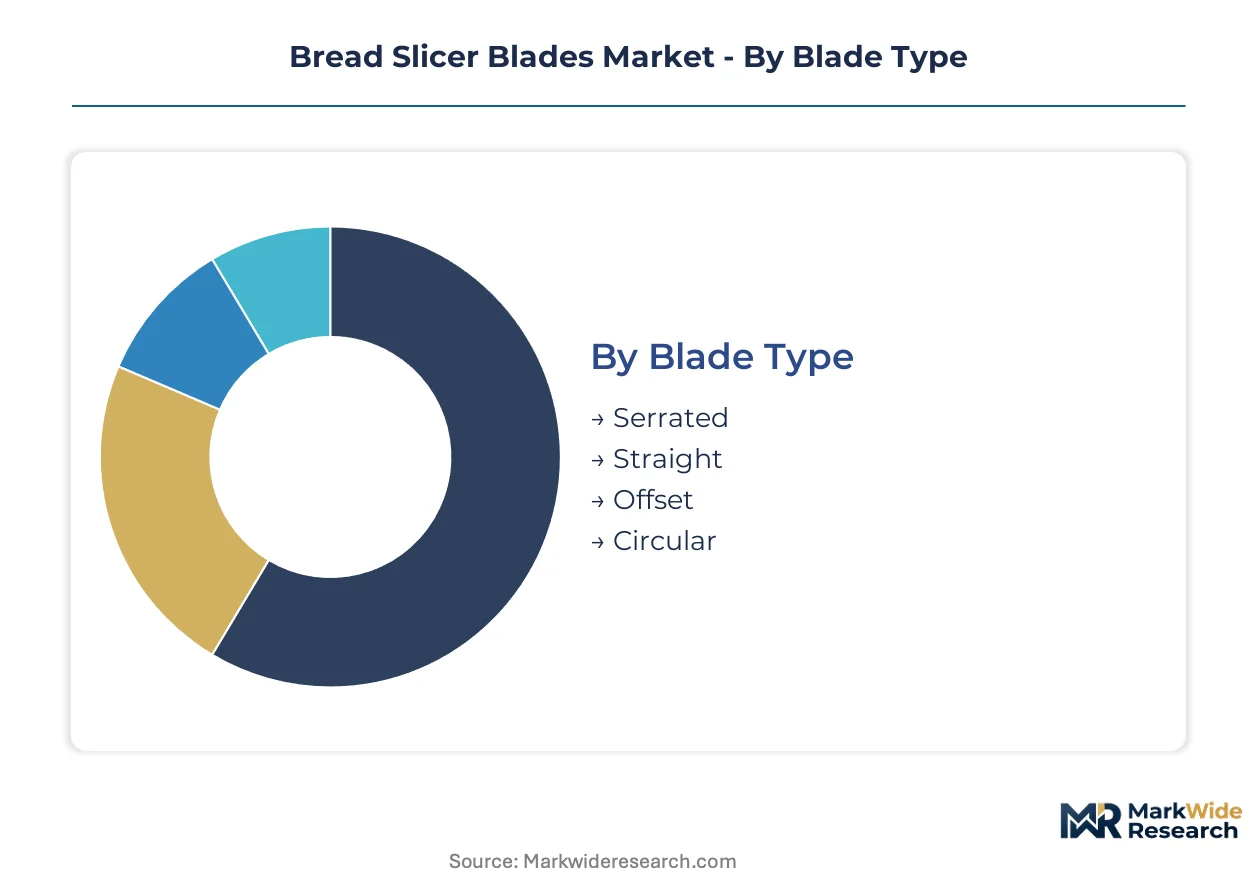
Blade type and material specifications determine performance thresholds for crust integrity, sharpening intervals, and regulatory compliance across bakery operations. Segmentation reveals where capital investment concentrates and where replacement cycles create recurring revenue pools for suppliers.
Blade Type:
Margin pools concentrate in configurations that balance cutting precision with durability under high-throughput conditions.
- Serrated:Scalloped tooth geometries penetrate crusty artisan loaves without compression, maintaining slice integrity through thousands of cycles. Commercial bakeries in Germany and France drive specification demand as crusty bread portfolios expand in European foodservice.
- Straight:Uniform edge profiles deliver consistent sandwich-slice thickness for industrial bread production lines. North American commercial bakeries anchor volume demand through integrated slicer-blade system procurement with standardized maintenance protocols.
- Offset:Angled cutting surfaces reduce friction on dense rye and multigrain formulations common in Northern European baking traditions.
- Circular:Rotary configurations serve specialized continuous-feed industrial installations with automated loaf positioning systems.
Serrated configurations hold installed capacity. Straight blades are rotating up the share rankings in automated production environments.
Material:
Cost tiers separate premium performance grades from commodity replacement markets based on heat-treatment sophistication and coating technologies.
- Stainless Steel:Food-grade alloys with chromium and nickel content certified under FDA and EU Framework Regulation 1935/2004 dominate commercial installations. Solingen manufacturers leverage heat-treatment heritage to command premium positioning in OEM supply contracts.
- Ceramic:Reduced-friction surfaces extend sharpening intervals significantly, though chipping susceptibility limits frozen bread applications. Artisan bakeries in France and Germany adopt these variants fastest as fluorine-free coating alternatives gain regulatory traction.
- Carbon Steel:Higher hardness ratings suit high-volume operations prioritizing edge retention over corrosion resistance in controlled environments.
- Aluminum:Lightweight properties serve portable and household applications where cutting frequency remains moderate.
Stainless steel maintains volume dominance. Ceramic is climbing the fastest as bakers seek extended maintenance cycles.
Application:
Customer type determines procurement patterns, with centralized bakery chains favoring direct manufacturer relationships over distributor channels.
- Commercial Bakeries:High-throughput operations require precision-ground tooth geometries with NSF/ANSI 169 sanitation certification. Germany's industrial baking equipment cluster concentrates specification demand around Solingen blade engineering standards.
- Food Processing:Integrated production lines demand standardized blade fleets with vendor-managed inventory systems. North American facilities lead adoption of unbundled after-sales service models separating blade procurement from sharpening contracts.
- Household Use:Consumer-grade specifications prioritize safety features and compact storage over professional durability metrics.
- Catering Services:Mobile operations require rapid-change blade systems compatible with multi-site equipment fleets.
Commercial bakeries anchor replacement demand. Food processing is gaining share fastest through centralized procurement consolidation.
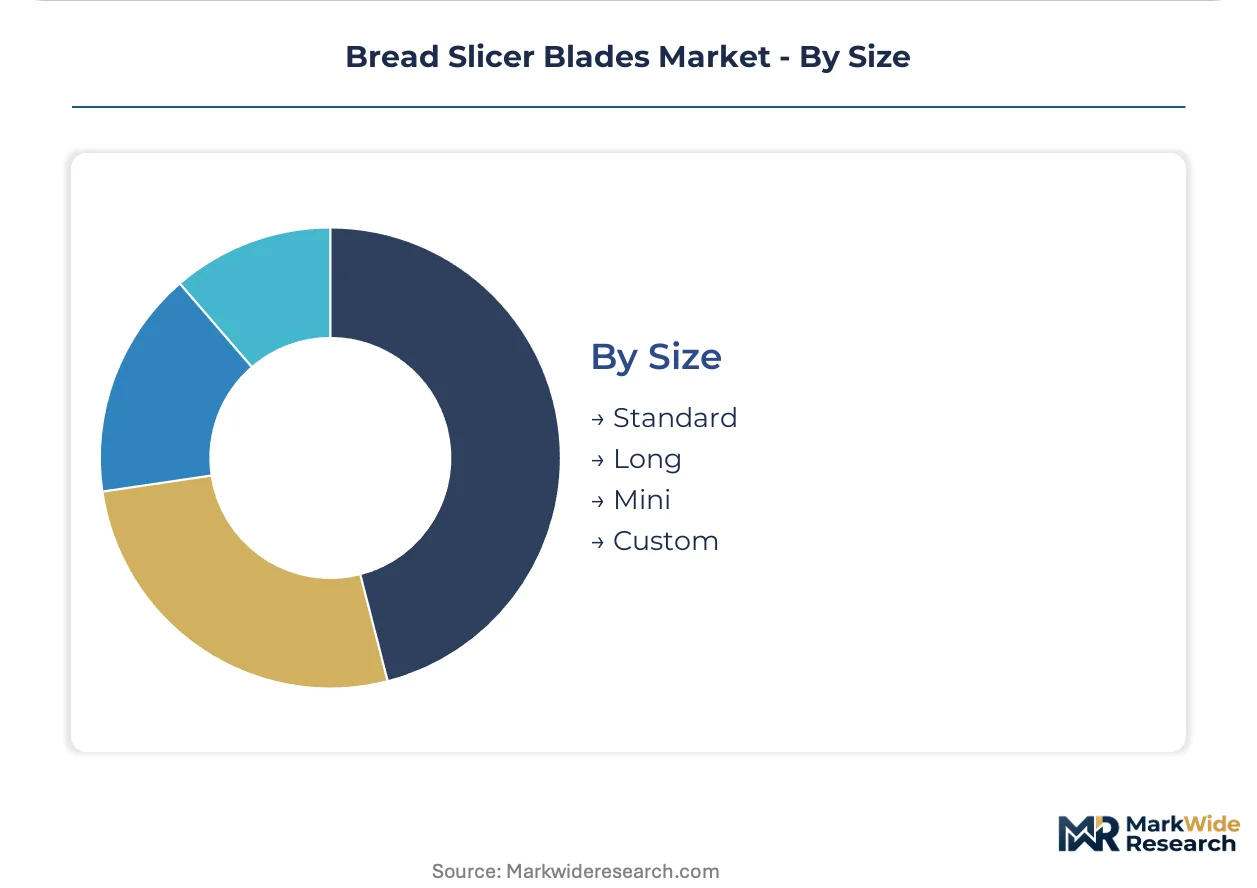
Size:
Volume scales inversely with margin capture, as custom specifications command technical consultation fees and proprietary geometry development.
- Standard:Industry-dimension blades compatible with major slicer OEM platforms dominate replacement part sales. Independent bakeries and delis in fragmented distributor networks drive recurring revenue through predictable wear-cycle replacement.
- Custom:Proprietary specifications tailored to unique loaf dimensions or cutting speeds capture disproportionate margin pools. OEM slicer manufacturers seeking differentiated performance partner with precision grinding specialists for exclusive geometry development.
- Long:Extended cutting surfaces serve industrial continuous-feed installations with automated loading systems.
- Mini:Compact formats address specialty bread categories and constrained-space operations in urban bakery locations.
Standard sizes hold installed capacity. Custom specifications are expanding most quickly as OEMs pursue equipment differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Independent bakeries in India and Southeast Asia prioritize replacement cost over precision specifications. German and Japanese commercial operators accept premium pricing for certified heat-treatment quality and extended sharpening intervals.
Germany
Artisan bread portfolio expansion at commercial bakeries drives specification demand for serrated configurations with scalloped tooth geometries. EU Framework Regulation 1935/2004 governs chromium and nickel content certification for food-grade stainless steel compliance. The Solingen manufacturing cluster concentrates precision grinding expertise and heat-treatment heritage for premium OEM blade supply contracts.
United States
Centralized procurement at foodservice chains and industrial bakery operations anchors volume demand for standardized blade fleets. FDA food-contact material regulations mandate stainless steel composition limits and NSF/ANSI 169 sanitation certification for commercial food equipment. Hobart Corporation's integrated slicer-blade systems dominate replacement channels through extensive distributor networks.
France
Crusty loaf production growth in commercial bakeries accelerates serrated blade adoption for compression-free cutting performance. REACH restrictions on per- and polyfluoroalkyl substances compel fluorine-free coating reformulation for sticky dough release properties. Artisan bakeries in Paris and Lyon lead ceramic material trials as regulatory compliance deadlines compress.
China
Commercial bakery modernization programs drive demand for automated grinding and laser-hardening equipment accessibility. GB standards for food-contact materials add certification layers for exporters targeting domestic production geographies. Yangtze River Delta manufacturing bases expand precision blade fabrication capacity for regional bakery equipment supply.
India
Independent bakeries and fragmented distributor networks create pricing power asymmetries in replacement blade aftermarket channels. BIS certification requirements for food-grade stainless steel compel compliance investment from exporters establishing production lines. Maharashtra and Gujarat commercial bakery clusters drive modernization demand for NSF/ANSI-certified blade specifications.
Bread Slicer Blades Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the bread slicer blades supply base. European heritage manufacturers command premium positioning through heat-treatment expertise and precision grinding heritage. Asian fabricators leverage automated equipment accessibility to compress capability gaps in mid-market segments. Three archetypes dominate: integrated slicer OEMs with captive blade supply, specialized blade fabricators serving aftermarket channels, and diversified foodservice equipment conglomerates. Competitive moves concentrate on direct-to-bakery digital channel expansion and fluorine-free coating technology licensing.
Among European heritage specialists, Berkel and Sammic occupy positions anchored by Italian engineering traditions in artisan bakery segments. Hobart Corporation exemplifies the integrated-systems archetype through North American foodservice distribution anchoring. KASCO represents the aftermarket-focused specialist model with replacement blade programs targeting independent bakeries and deli operations. These three company structures illustrate how geographic origin and organizational form map to distinct competitive positioning vectors in blade supply.
| Leading Market Players |
|---|
| Berkel |
| Sammic |
| Bizerba |
| MECALBEK |
| Hobart Corporation |
| Oliver |
| KASCO |
| ADS PRECISION |
| Debra-Blades |
| Others |
Pricing and Supply Chain Analysis
Automated grinding equipment substitution for manual precision grinding is redistributing supply geography from Solingen to Yangtze River Delta manufacturing bases while compressing price premiums for laser-hardened stainless steel tooth geometries.
Pricing Analysis
After-sales service revenue from sharpening contracts and replacement blade programs drives lifetime value capture for specialized fabricators. Three-tier pricing structure across premium Solingen-certified, mid-market laser-hardened, and economy-grade carbon steel variants separates OEM supply contracts from independent bakery aftermarket channels. Cost compression in the mid-tier is intensifying because Asian fabricators now match European heat-treatment benchmarks. Food processing chains exhibit lowest price sensitivity due to vendor-managed inventory systems, while independent Indian bakeries prioritize replacement cost over precision specifications.
Supply Chain Analysis
Strait of Malacca transit routes for nickel and chromium ores from Indonesian mining operations to Chinese stainless steel mills constitute a critical chokepoint for food-grade alloy supply. Blade fabrication draws from German heat-treatment expertise, Chinese automated grinding capacity, and Indian BIS-certified finishing operations. Single-source vulnerability concentrates in Solingen for premium OEM specifications and Yangtze River Delta for mid-volume production. Distribution runs through fragmented independent distributor networks for replacement blades and direct manufacturer relationships for commercial bakery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward centralized foodservice procurement functions, fragmenting traditional distributor relationships as large bakery chains unbundle blade procurement from sharpening services.
For Market Incumbents: Secure fluorine-free coating technology licensing positions ahead of REACH PFAS enforcement deadlines in France and Germany. Defend against Asian mid-market encroachment by deepening captive supply relationships with OEM slicer manufacturers through exclusive geometry development partnerships. For New Entrants and Emerging Players: Differentiate on ceramic material variants with extended sharpening intervals for artisan bakery segments in Paris and Lyon where regulatory compliance deadlines compress fastest. Penetrate India's Maharashtra and Gujarat commercial bakery clusters through BIS-certified production lines and direct-to-bakery digital procurement platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European heritage specialists holding Solingen heat-treatment expertise but lacking digital channel infrastructure. Long-term viability hinges on coating technology transition timelines and after-sales service unbundling patterns. Watch for inflection signals in EPA PFAS restriction announcements affecting North American coating reformulation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Coating Development | REACH and EPA restrictions on PFAS compounds compel reformulation of blade surface treatments for sticky dough release. |
| Direct-to-Bakery Digital Channel Expansion | E-procurement platforms displace traditional distributor markups for independent operators seeking transparent specifications. |
| Laser-Hardening Equipment Investment | Automated heat-treatment capability enables Asian fabricators to match European quality benchmarks at compressed price points. |
| BIS Certification Pathway Establishment | Exporters capturing India's commercial bakery modernization must comply with food-grade stainless steel standards. |
| After-Sales Service Unbundling | Large bakery chains now separate blade procurement from sharpening contracts, fragmenting traditional distributor relationships. |
Research Methodology
Initial hypotheses were tested against primary input from commercial bakery operations directors, OEM slicer manufacturer procurement teams, aftermarket distributor principals, and precision grinding equipment technicians and refined through secondary validation against EU Framework Regulation 1935/2004 compliance documentation, FDA food-contact material guidance, BIS certification standards, customs trade data for stainless steel blade exports, and SEC filings from diversified foodservice equipment conglomerates. Bottom-up blade unit demand estimates from commercial bakery fleet counts were triangulated with top-down market value assessments.
Variance decomposition across blade type, material specification, application tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate assumptions applied to baseline market sizing. Forecast inputs incorporated artisan bread production expansion rates, PFAS restriction implementation timelines, and automated grinding equipment penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained commercial bakery capital expenditure cycles or accelerated PFAS regulatory enforcement would require recalibration. Practitioners should keep alternative scenarios live as coating technology transition costs and nickel price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Global Bakery Product Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Global Cakes Market
Bakery Products
Waffle Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Pastries Market
Bakery Products
Banana Bread Market
Bakery Products
Specula Market
Bakery Products
Low Fat Bread Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
United States Bread Market