
 Pizza Dough Balls Market | 2026-2036
Pizza Dough Balls Market Size, Share, and Industry Trends Forecast 2026-2036
Pizza Dough Balls Market Analytics
Premium clean-label dough specifications is unwinding commodity-grade production across the pizza dough balls category. Rich Products leverages frozen dough ball scale to anchor supply contracts with national foodservice distributors. Pillsbury competes through refrigerated logistics networks that sustain broad retail penetration. Whole Foods Market differentiates via organic certification requirements that control premium shelf placement.
Pizza dough balls are portioned, fermented wheat-based dough spheres designed for direct stretching and baking, typically containing flour, water, yeast, salt, and optional oil at 55-65% hydration levels for optimal extensibility. Frozen dough balls dominate volume throughput due to extended shelf stability and reduced spoilage rates in foodservice channels. Fresh dough balls command margin concentration among artisan pizzerias and full-service restaurants where proofing control signals quality. Gluten-free dough exhibits the fastest structural expansion as celiac-safe formulations attract specialty diet consumers through supermarkets and online retailers.
The FDA governs allergen labeling and GRAS status for dough additives in the United States while the EFSA enforces acrylamide thresholds and food contact material rules across European markets. USDA organic certification and Non-GMO Project verification increasingly filter supplier eligibility for mainstream retail placement. Stakeholders must monitor how dual regulatory pressure on sodium reduction and clean-label preservation technologies reshapes formulation R&D priorities without eroding dough performance benchmarks.
Market Dynamics
Clean-label ingredient mandates from the FDA and EFSA are forcing reformulation across frozen and fresh dough categories, compressing margins for suppliers dependent on chemical preservatives and synthetic dough conditioners.
Growth Catalysts
- Quick-service pizzeria expansion:National chains in the United States and Italy are standardizing fresh dough ball specifications to ensure consistency across franchise locations, driving procurement volume.
- REACH compliance premiums:European suppliers investing in acrylamide-reduction technologies and clean-label fermentation aids capture shelf space from commodity competitors.
- Gluten-free formulation advances:Celiac-safe dough alternatives using rice and tapioca starches now penetrate supermarket channels previously closed to specialty diet products.
Market Restraints
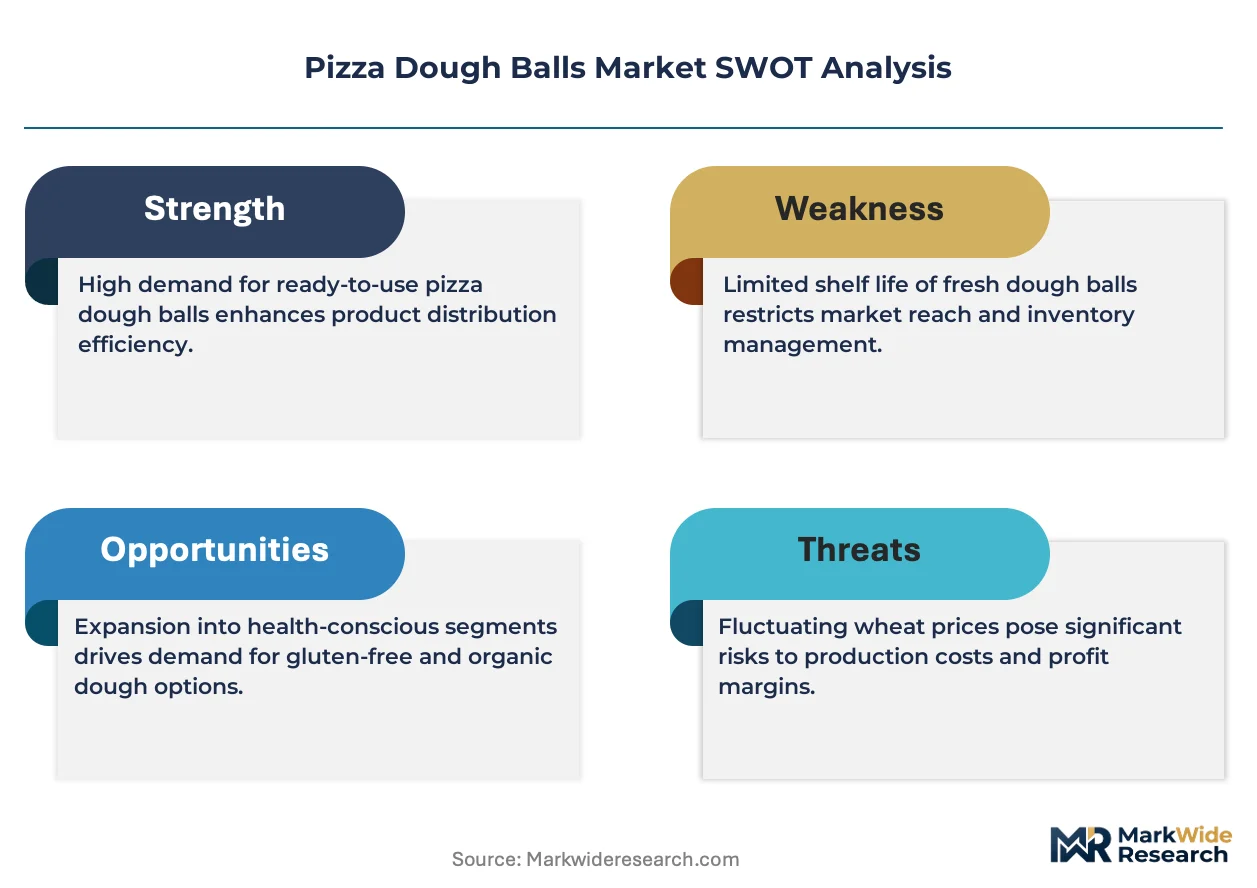
- Wheat price volatility:Hard red winter wheat futures fluctuate with Black Sea supply disruptions, compressing margins for unhedged regional mills.
- Frozen logistics concentration:Cold-chain capacity bottlenecks in the Midwestern United States limit fresh dough ball distribution radius for artisan suppliers.
- Sodium reduction thresholds:FDA draft guidance on voluntary sodium targets conflicts with traditional dough flavor profiles, forcing expensive taste reformulation.
Strategic Opportunities
- India foodservice penetration:Pizza Hut and Domino's franchise expansion into tier-two Indian cities creates demand for ambient-stable dough concentrates requiring minimal refrigeration.
- USDA Organic certification:Premium retail placement at Whole Foods Market and Sprouts Farmers Market rewards suppliers achieving certified organic wheat sourcing and processing.
- Direct-to-restaurant platforms:Web-based ordering systems bypassing traditional foodservice distributors enable smaller mills to capture artisan pizzeria accounts with customized hydration specifications.
Industry Challenges
- Skilled fermentation technician scarcity:Artisan pizzerias struggle to hire staff capable of managing cold-proofing schedules and ambient temperature fluctuations.
- Dual certification timelines:Simultaneous Non-GMO Project verification and USDA Organic approval processes extend supplier qualification periods by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pizza Dough Balls Market |
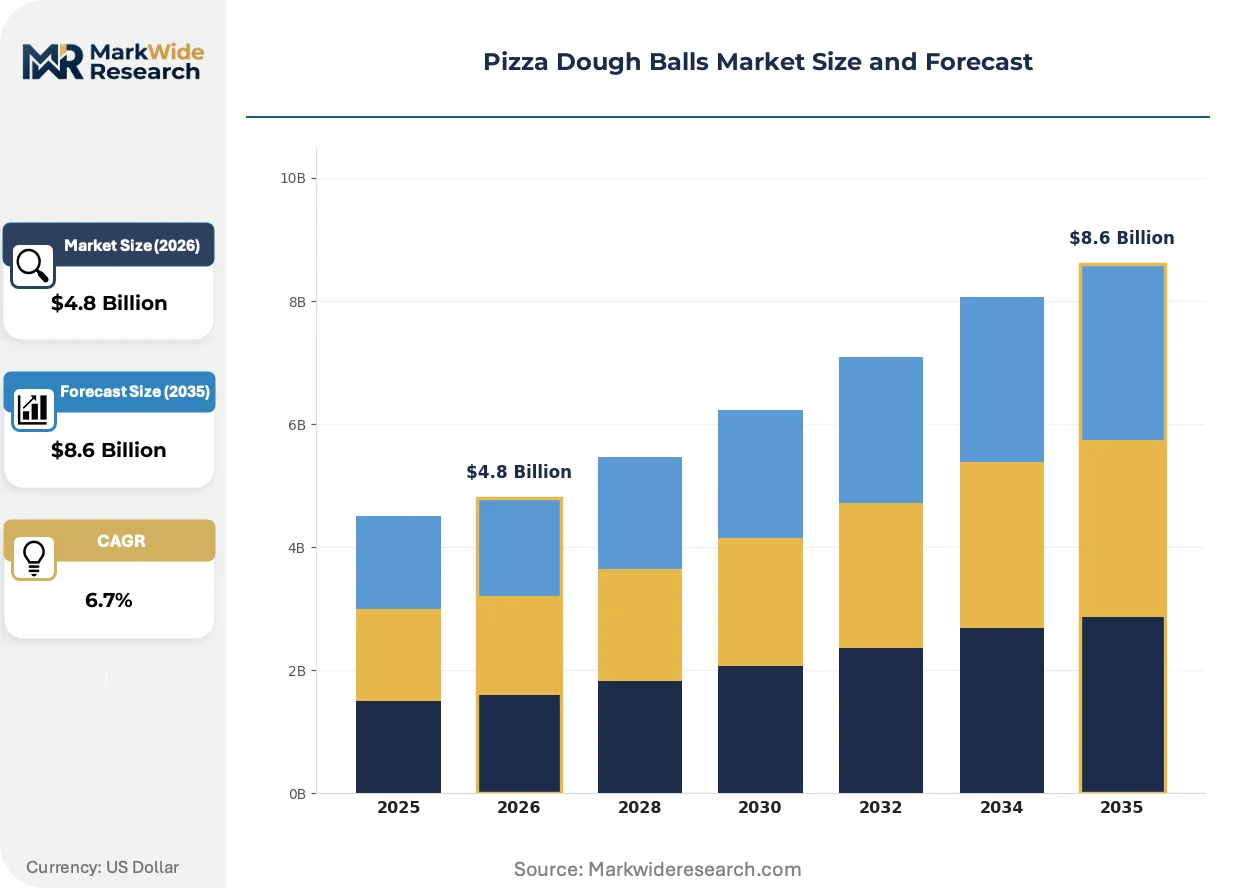
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Dough Balls, Frozen Dough Balls, Pre-Rolled Dough, Gluten-Free Dough Distribution Channel: Supermarkets, Online Retailers, Food Service, Convenience Stores End User: Restaurants, Pizzerias, Bakeries, Home Consumers Packaging Type: Plastic Bags, Boxes, Vacuum-Sealed Packs, Bulk Containers |
| Companies Covered | Rich Products, Trader Joe's, Pillsbury, Whole Foods Market, Signature Cafe, Wholly Gluten Free, Home Chef, Kroger, Birrittella's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pizza Dough Balls Market Evolving Landscape
Controlled-atmosphere packaging and precision fermentation are compressing spoilage windows and enabling longer distribution radii for fresh dough formats previously constrained by microbial limits.
Sourdough starter cryopreservation technology is miniaturizing artisan fermentation programs, allowing regional chains to deploy consistent flavor profiles without maintaining live cultures at every location. Fast-casual concepts in California and Texas adopt these systems to reduce labor training requirements. The technology is miniaturizing the competitive advantage of independent pizzerias into scalable, replicable formats.
EFSA acrylamide mitigation benchmarks are forcing enzyme supplier selection toward asparaginase treatments that reduce Maillard reaction byproducts in high-temperature baking. Industrial bakeries reformulate amino acid profiles to preempt regulatory non-compliance. Frozen dough ball manufacturers targeting European export markets now specify enzyme-treated flours in procurement contracts.
Restaurant operators increasingly specify dough balls by performance metrics—extensibility scores, bubble structure, and bake color consistency—rather than brand loyalty or price. Foodservice distributors respond by certifying supplier quality through third-party laboratory testing. This specification-driven sourcing is most visible in the Northeastern United States, where pizzeria density supports dedicated distribution infrastructure.
Pizza Dough Balls Market Segmentation
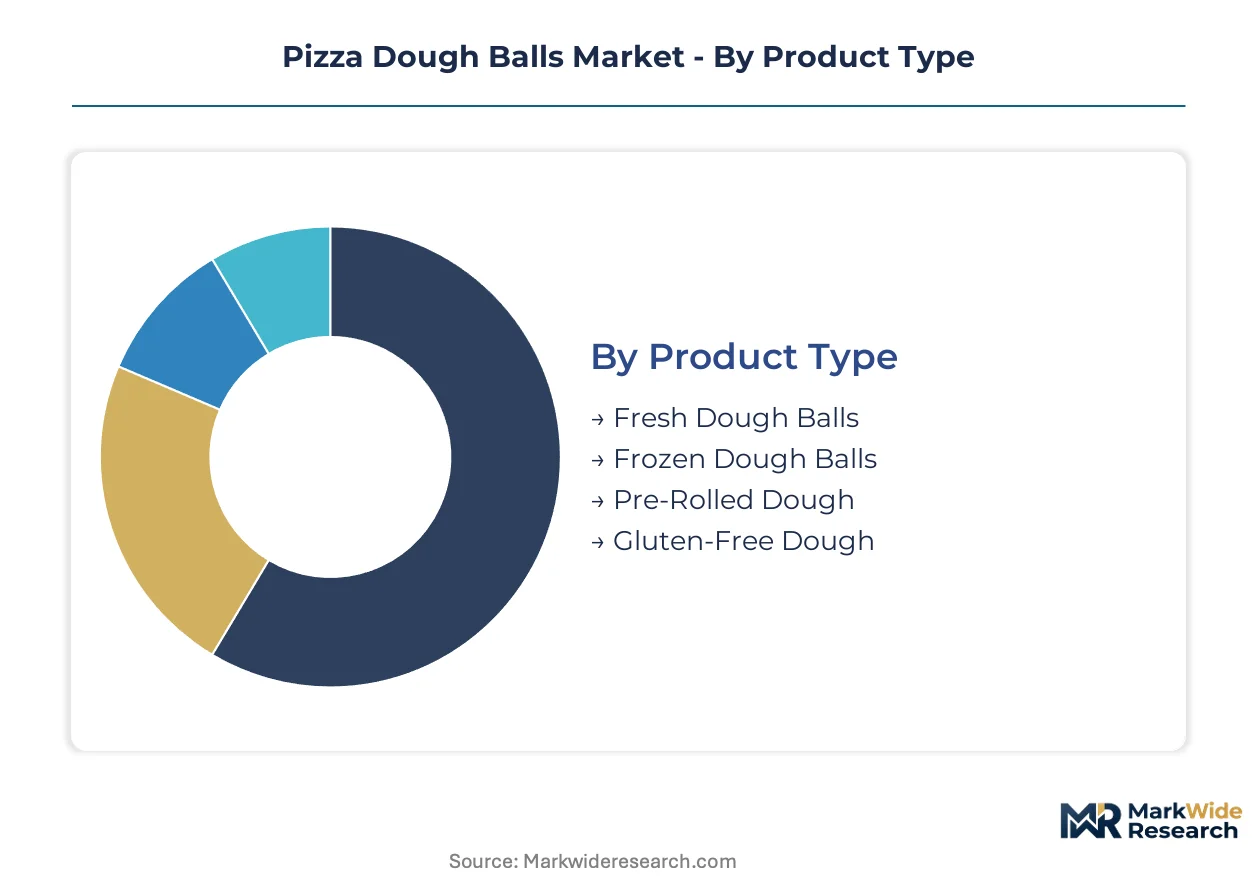
Dough ball segmentation determines cold-chain investment, shelf-life engineering, and margin architecture across the value chain. Suppliers configure production lines and certification pathways around product format and channel access requirements.
Product Type:
FDA and EFSA divergence on frozen versus fresh preservation standards creates compliance complexity for multi-format suppliers.
- Fresh Dough Balls:Unfrozen wheat-based spheres requiring continuous refrigeration at 2-4°C, proofed to 50-70% of final volume before distribution. Quick-service pizzerias in Italy and artisan restaurants in the United States concentrate procurement here, driven by flavor differentiation and proofing control premiums.
- Frozen Dough Balls:Blast-frozen at -18°C with cryoprotectant formulations extending shelf stability to 12-18 months. National foodservice distributors anchor volume throughput, constrained by EFSA acrylamide thresholds that favor enzyme-treated formulations for European export.
- Pre-Rolled Dough:Factory-stretched sheets reducing labor intensity for high-throughput kitchens.
- Gluten-Free Dough:Rice and tapioca starch alternatives penetrating supermarket channels through celiac-safe certification.
Established volume favors frozen dough balls; emerging adoption favors gluten-free formulations.
Distribution Channel:
Channel selection dictates packaging specifications, minimum order quantities, and margin capture rates for mill-direct versus distributor-mediated supply.
- Food Service:Palletized bulk delivery to commissary kitchens and distributor warehouses, with customized hydration specifications negotiated chain-by-chain. Cold-chain reliability and consistent bubble structure certification drive supplier selection for Domino's and Pizza Hut procurement teams.
- Supermarkets:Retail-ready packaging with barcode traceability and organic certification badges commanding shelf placement premiums at Whole Foods Market and Sprouts Farmers Market.
- Online Retailers:Direct-to-consumer fulfillment requiring insulated shippers and dry-ice protocols.
- Convenience Stores:Ambient-stable or short-refrigeration formats for grab-and-go pizza programs.
Food service channels concentrate procurement volume; online retail channels are expanding most quickly.
End User:
User type shapes fermentation expertise requirements, equipment investment, and specification complexity in supplier relationships.
- Pizzerias:Specialist operators demanding extensibility scores, bake color consistency metrics, and cold-proofing schedule flexibility. Independent operators in the Northeastern United States and Naples-area artisans specify dough by performance benchmarks rather than brand.
- Restaurants:Full-service kitchens with limited pizza specialization favor pre-rolled or frozen formats reducing training overhead.
- Bakeries:Multi-product operations integrating dough balls into broader pastry programs.
- Home Consumers:Retail-packaged formats with simplified proofing instructions and shorter fermentation windows.
Pizzerias anchor premium specification development; restaurants drive standardization and scale.
Packaging Type:
Packaging engineering balances microbial control, carbon footprint, and retail visibility requirements across channel formats.
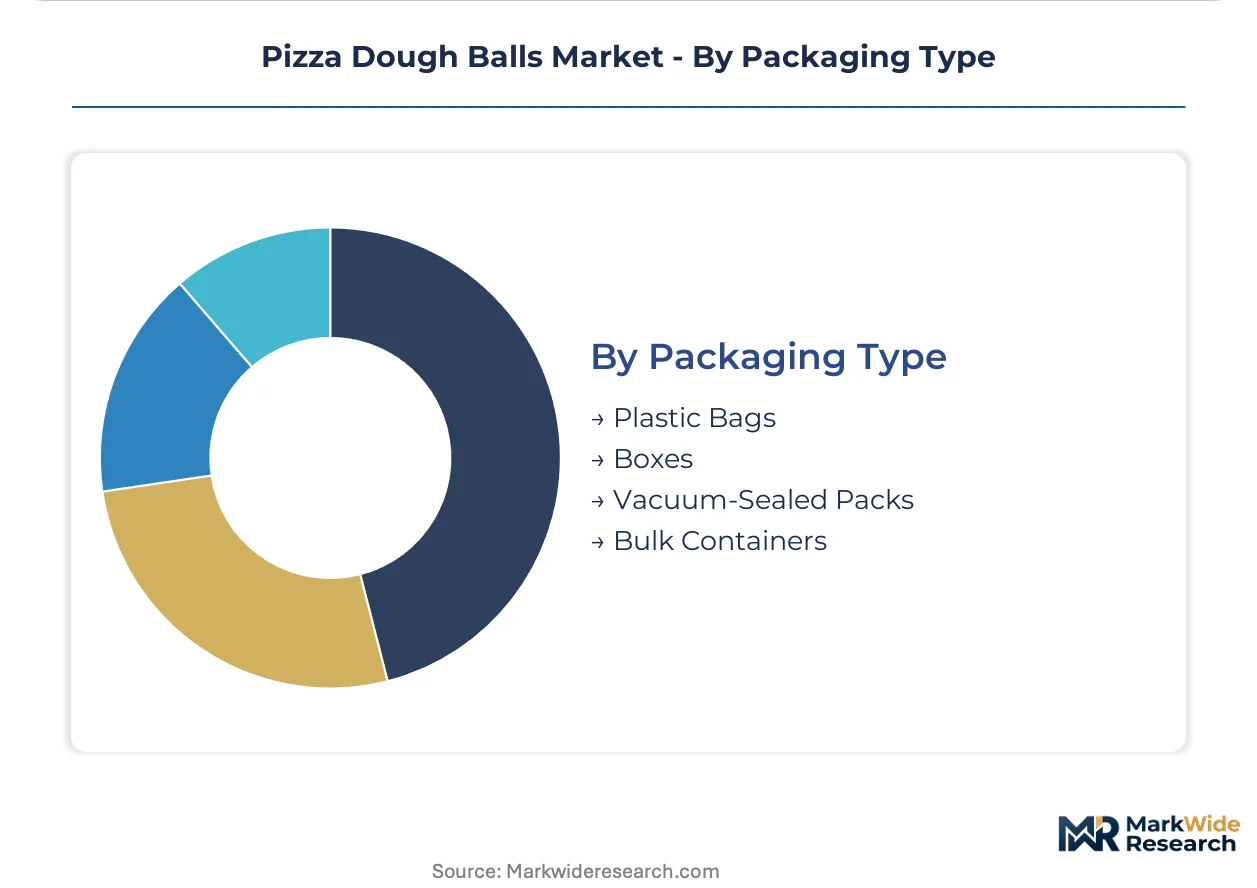
- Vacuum-Sealed Packs:Modified-atmosphere packaging extending fresh dough shelf life from 7 to 21 days, enabling longer distribution radii for regional mills. EFSA food contact material rules and FDA GRAS status for barrier films constrain film supplier selection.
- Plastic Bags:Standard polyethylene formats for frozen dough bulk distribution, lowest unit cost but limited shelf appeal.
- Boxes:Stackable corrugated formats protecting pre-rolled dough geometry in foodservice logistics.
- Bulk Containers:Reusable totes for high-volume commissary delivery with deposit-return systems.
Vacuum-sealed packs are gaining share fastest in fresh formats; plastic bags retain frozen volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in frozen dough balls concentrate between Italy and the United States, with European suppliers shipping enzyme-treated formulations to American foodservice distributors while U.S. mills export refrigerated logistics expertise back to Italian quick-service chains expanding domestically.
United States
Quick-service pizzeria chains in Texas and California drive fresh dough ball procurement volume, with standardized specifications reducing franchise variability. FDA allergen labeling mandates and draft sodium reduction guidance force reformulation investments among regional mills. Northeastern corridor distributors now certify suppliers through third-party laboratory testing for extensibility and bake color consistency metrics.
Italy
Artisan pizzerias in Naples and Rome concentrate demand for fresh dough balls with proofing control premiums, while industrial producers supply frozen formats to European export markets. EFSA acrylamide thresholds and food contact material rules constrain film supplier selection for modified-atmosphere packaging. Northern Italian milling clusters around Milan and Bologna deploy asparaginase enzyme treatments to preempt regulatory non-compliance.
Germany
REACH compliance investments distinguish premium suppliers from commodity competitors in frozen dough ball segments serving discount supermarket channels. ECHA enforcement of chemical safety in food contact materials elevates barrier film costs for vacuum-sealed fresh formats. Bavarian and North Rhine-Westphalian foodservice distributors consolidate procurement around certified organic wheat sourcing for retail placement at REWE and Edeka.
India
Pizza Hut and Domino's franchise expansion into tier-two cities generates demand for ambient-stable dough concentrates requiring minimal cold-chain infrastructure. FSSAI food safety standards and labeling requirements filter supplier eligibility for national chain procurement. Maharashtra and Karnataka foodservice hubs test localized hydration specifications adapted to regional climate conditions and equipment variability.
United Kingdom
Full-service restaurant chains in London and Manchester favor pre-rolled dough formats reducing kitchen labor intensity and training overhead. Food Standards Agency allergen guidance and post-Brexit import certification complexity delay European supplier qualification timelines. Midlands-based distributors develop in-house fermentation expertise to bypass continental supply dependencies for fresh dough ball programs.
Pizza Dough Balls Market Competitive Landscape
Listed leaders compete with private specialists across frozen logistics scale and fresh format certification depth. The vendor base clusters around three tiers: multinational food conglomerates with national distributor contracts, regional mills serving artisan pizzeria accounts, and private-label specialists penetrating supermarket channels. Archetypes include scale-driven frozen throughput operators, clean-label certification specialists, and direct-to-restaurant platform innovators. Dominant competitive moves encompass M&A for cold-chain capacity and strategic partnerships for organic wheat sourcing.
Within the multinational tier, Rich Products and Pillsbury exemplify divergent logistics strategies, with the former anchoring frozen distribution scale and the latter occupying refrigerated network penetration. Trader Joe's and Whole Foods Market represent private-label and retail-channel archetypes respectively, each filtering supplier eligibility through distinct certification requirements. These four entities collectively illustrate how capital structure and channel focus shape competitive positioning without requiring identical operational approaches.
| Leading Market Players |
|---|
| Rich Products |
| Trader Joe's |
| Pillsbury |
| Whole Foods Market |
| Signature Cafe |
| Wholly Gluten Free |
| Home Chef |
| Kroger |
| Birrittella's |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between national foodservice distributors and frozen dough ball manufacturers lock in multi-year supply access while fixing wheat input costs against futures volatility. These arrangements transfer price visibility to quick-service chains while saddling mills with margin compression when Black Sea supply disruptions spike hard red winter wheat futures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across frozen and fresh dough categories. Three-tier pricing structure across premium organic, standard certified, and economy commodity levels separates USDA Organic suppliers from conventional mills. Cost compression in economy tiers intensifies because unhedged regional mills face wheat price volatility without distributor volume guarantees. Quick-service pizzerias exhibit lowest price sensitivity due to standardization premiums, while independent artisan operators negotiate performance-based specifications with limited volume leverage.
Supply Chain Analysis
Strategic stockpile preferences dominate frozen dough ball procurement, with distributors maintaining 30-60 day cold-chain inventories to buffer against fermentation schedule disruptions. Supply concentrates in the United States, Italy, and Germany, with North American hard red winter wheat regions feeding domestic mills and Italian durum clusters serving European artisan channels. Raw material dependencies center on wheat futures, cryoprotectant formulations, and modified-atmosphere barrier films. Single-source vulnerability runs through Midwestern cold-chain capacity bottlenecks that constrain fresh dough distribution radii. Distribution runs through national foodservice distributors with commissary direct delivery, bypassing traditional wholesale layers for chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among national quick-service chains standardizing dough specifications across franchise networks, fragmenting leverage for regional artisan pizzerias and independent mills.
For Market Incumbents: Consolidate cold-chain capacity through captive distribution investments in the Northeastern United States corridor where pizzeria density supports dedicated infrastructure. Deepen backward integration into certified organic wheat sourcing to preempt Whole Foods Market and Sprouts Farmers Market procurement gatekeeping. Lock in multi-year enzyme supply contracts with asparaginase treatment suppliers before EFSA acrylamide thresholds tighten further.
For New Entrants and Emerging Players: USDA Organic certification fast-track programs offer the most penetrable entry path into premium retail placement at Sprouts Farmers Market and REWE. Target tier-two Indian cities where Pizza Hut and Domino's franchise expansion outpaces ambient-stable dough concentrate supply. Deploy direct-to-restaurant web platforms with customized hydration specifications to bypass incumbent distributor relationships in artisan pizzeria clusters.
For Investors and Strategic Acquirers: Capital is best deployed toward regional mills with established cold-proofing expertise and dormant USDA Organic certification pathways. Long-term viability hinges on fermentation technician training infrastructure and cryopreservation technology licensing. Watch for inflection when FDA sodium reduction guidance shifts from voluntary to enforceable thresholds, triggering forced reformulation investments among commodity-grade suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Wheat Sourcing | Captures USDA Organic certification premiums at Whole Foods Market and Sprouts Farmers Market. |
| Cryopreservation Technology Licensing | Enables regional chains to deploy consistent sourdough profiles without live culture maintenance. |
| Direct-to-Restaurant Platform Launch | Bypasses national foodservice distributors for artisan pizzeria accounts with custom specifications. |
| Asparaginase Enzyme Supply Contracting | Preempts EFSA acrylamide non-compliance risk in European export markets. |
| Ambient-Stable Dough Concentrate Development | Unlocks Pizza Hut and Domino's expansion into Indian tier-two cities with minimal refrigeration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA GRAS filings, EFSA food contact material registrations, USDA Organic certification databases, and national foodservice distributor procurement contracts. Primary interviews engaged fermentation technicians at artisan pizzerias, procurement directors at quick-service chains, cold-chain logistics operators, and enzyme supplier technical sales leads. Secondary validation drew from SEC 10-K disclosures of multinational food conglomerates, customs trade data on frozen dough ball export-import flows, and FSSAI food safety compliance records. Bottom-up volume modeling triangulates against top-down category spend estimates.
Segmentation dimensions modeled include product format (frozen, fresh, pre-rolled, gluten-free), distribution channel (foodservice, supermarket, online retail, convenience), and end-user type (pizzeria, restaurant, bakery, home consumer). CAGRs were derived from trend extrapolation across the analysis window, with wheat futures volatility and clean-label reformulation costs as key forecast inputs. Regional splits incorporate EFSA acrylamide threshold compliance rates and FDA sodium reduction guidance progression.
Underlying assumptions cover sustained quick-service pizzeria expansion, stable EFSA enforcement intensity, and gradual FDA sodium guidance adoption, with deviation risk concentrated in Black Sea wheat supply disruptions and dual certification timeline extensions. Revision becomes warranted when FDA sodium targets shift from voluntary to mandatory or when cold-chain capacity bottlenecks trigger regional supply rationing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Premix Bread Flour Market
Bakery Products
Fortified Bakery Market
Bakery Products
Premixed Bread Flour Market
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
Frozen Bakery Products Market
Bakery Products
Pancake Mixes Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Global Cakes Market
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Ezekiel Bread Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Bakery Flavors Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Banana Bread Market