
 Laminated Dough Market | 2026-2036
Laminated Dough Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Dough Market Intelligence
The substitution of traditional hydrogenated fats with sustainable palm oil and butter alternatives is shifting the cost structure across the laminated dough sector. Aryzta AG leverages its global manufacturing footprint to manage ingredient sourcing volatility. Lantmännen Unibake differentiates with a portfolio of premium, butter-based pastries for the foodservice channel. Grupo Bimbo utilizes its extensive distribution network to supply both retail bakeries and convenience store segments.
Laminated dough is a culinary preparation made by repeatedly folding a block of dough around a fat, such as butter or margarine, creating hundreds of alternating layers. This layering process, known as lamination, results in a flaky, light texture upon baking, which is essential for products like croissants and puff pastries. Within product types, butter dough commands a premium, while margarine-based variants cater to cost-sensitive bakeries and foodservice providers. Demand for croissants and Danish pastries continues to dominate the application segment.
Food safety standards enforced by the US FDA and the European Food Safety Authority (EFSA) dictate permissible fats, additives, and microbial limits. Global regulations on allergen labeling, such as for wheat, milk, and soy, directly influence product formulation and packaging information. Producers must navigate evolving consumer preferences for clean-label ingredients while managing the price volatility of key fats like butter and palm oil.
Market Dynamics
The central dynamic in the laminated dough market is the tension between industrial-scale production for foodservice and the consumer-driven push for artisanal, clean-label ingredients like butter, which impacts cost structures and manufacturing processes across the value chain.
Growth Catalysts
- Retail Channel Expansion:The proliferation of in-store bakeries within supermarkets and hypermarkets, particularly in China and India, creates consistent, high-volume demand for standardized frozen dough products.
- Automation in Lamination:Advances in automated sheeting and folding equipment are improving production efficiency and final product consistency, making high-quality pastries more accessible and affordable for smaller bakeries.
- Foodservice Demand for Convenience:Quick-service restaurants and cafes increasingly rely on ready-to-bake laminated dough to ensure product uniformity and reduce on-site labor requirements, accelerating market adoption.
Market Restraints
- Ingredient Price Volatility:Fluctuations in the global prices of key fats, especially butter and certified sustainable palm oil, create significant margin pressure and sourcing instability for producers.
- Stringent Food Safety Regulations:Compliance with microbial limits and allergen labeling mandates from bodies like the US FDA and EFSA adds cost and complexity to formulation and packaging.
- Threat of Healthier Alternatives:Competition from non-laminated breakfast items, whole-grain options, and products with lower fat content poses a substitution risk among health-conscious consumers.
Strategic Opportunities
- Plant-Based and Allergen-Free Formulations:Developing laminated dough using dairy-free fats and gluten-free flours opens access to the growing vegan and celiac consumer segments, commanding premium prices.
- Emerging Market Penetration:Targeting middle-class consumers in Latin American and Southeast Asian countries with a growing appetite for Western-style baked goods represents a significant growth vector.
- Direct-to-Consumer Channels:Establishing online platforms for selling premium, frozen artisanal dough directly to home bakers bypasses retail gatekeepers and builds brand loyalty.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of bakers with the dual expertise to manage traditional lamination techniques and operate sophisticated automated machinery constrains production quality.
- Cold Chain Integrity:Maintaining unbroken, temperature-controlled logistics from factory to point-of-sale is critical and costly, with failures leading to product spoilage and texture degradation.
- Clean-Label Reformulation:Removing artificial additives and preservatives to meet clean-label demands without compromising shelf life or sensory profile is a major technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Dough Market |
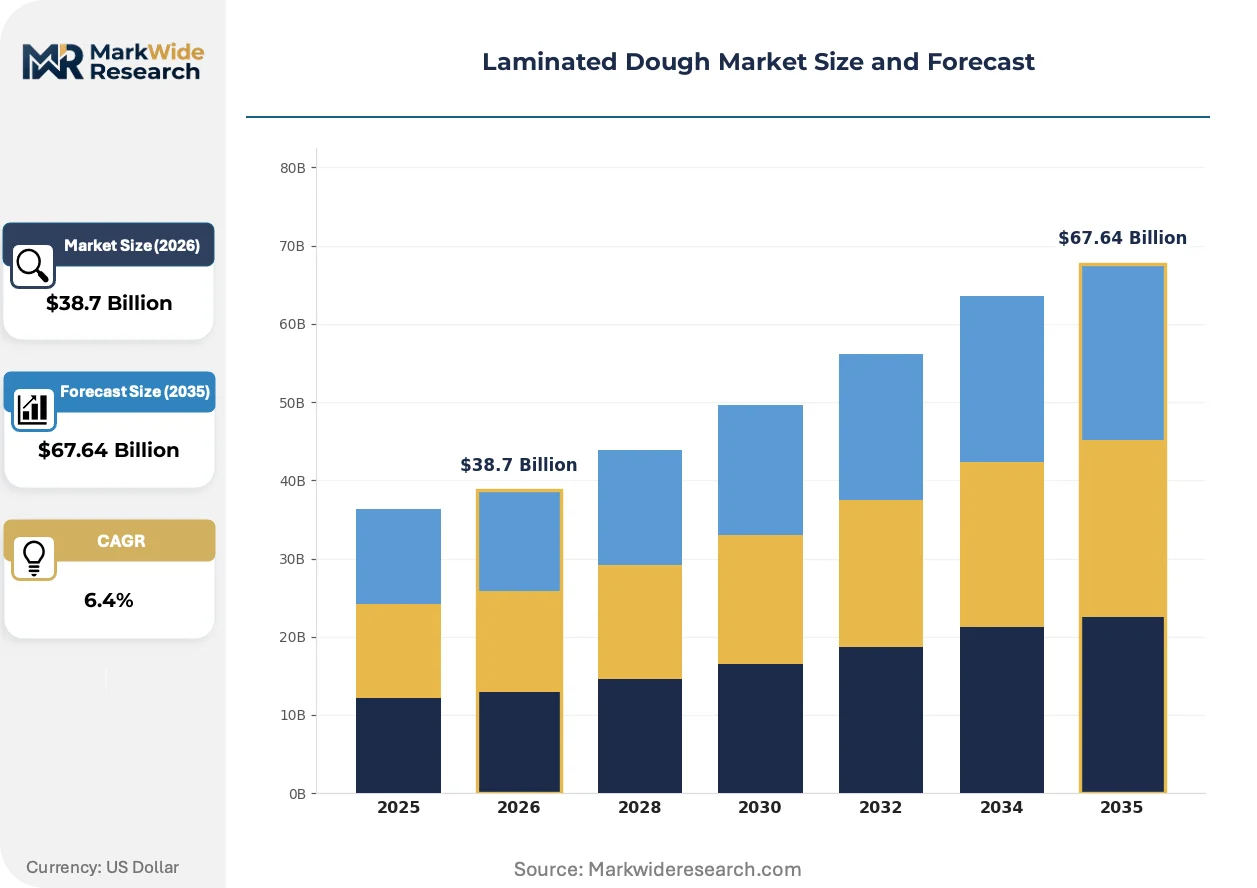
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter Dough, Margarine Dough, Vegetable Shortening Dough, Palm Oil Dough Application: Pastries, Croissants, Danish, Puff Pastry, Strudel End User: Bakeries, Foodservice Providers, Convenience Stores, Specialty Food Manufacturers Packaging Type: Plastic Wrap, Aluminum Foil, Paperboard Boxes, Vacuum Sealed Bags |
| Companies Covered | Aryzta AG, Lantmännen Unibake, CSM Bakery Solutions, Grupo Bimbo, Rich Products Corporation, Dawn Food Products, Inc., General Mills, Creation Food Company, PURATOS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Dough Market Strategic Shifts & Innovations
The market's evolution is defined by a push to industrialize an artisanal process. Innovations focus on achieving craft-quality texture and taste at mass-production scale, while adapting to new ingredient standards and consumer purchasing behaviors.
Automated sheeting and folding systems with integrated sensors provide real-time control over fat and dough layer consistency. Large-scale industrial bakeries are adopting this technology to ensure uniform product quality across high-volume runs. This advanced automation is overtaking traditional manual lamination for mass-market croissants and pastries, reducing labor costs and variability.
Global food safety authorities, including the European Food Safety Authority (EFSA), are enforcing stricter standards for additives and allergen disclosures. This regulatory pressure compels producers to reformulate products, often substituting certain fats with butter or sustainable palm oil. The butter-based dough segment is most impacted by cost volatility, while all producers must update packaging to comply with evolving allergen labeling laws for wheat and milk.
A clear shift in procurement patterns shows foodservice operators favoring frozen, ready-to-bake dough over scratch preparation. This trend disrupts the traditional supply model for bakeries, creating a direct channel for specialized B2B manufacturers to supply chains like hotels and cafes. The behavior is most pronounced within the fast-casual restaurant sector in the United States and Western Europe.
Laminated Dough Market Segmentation
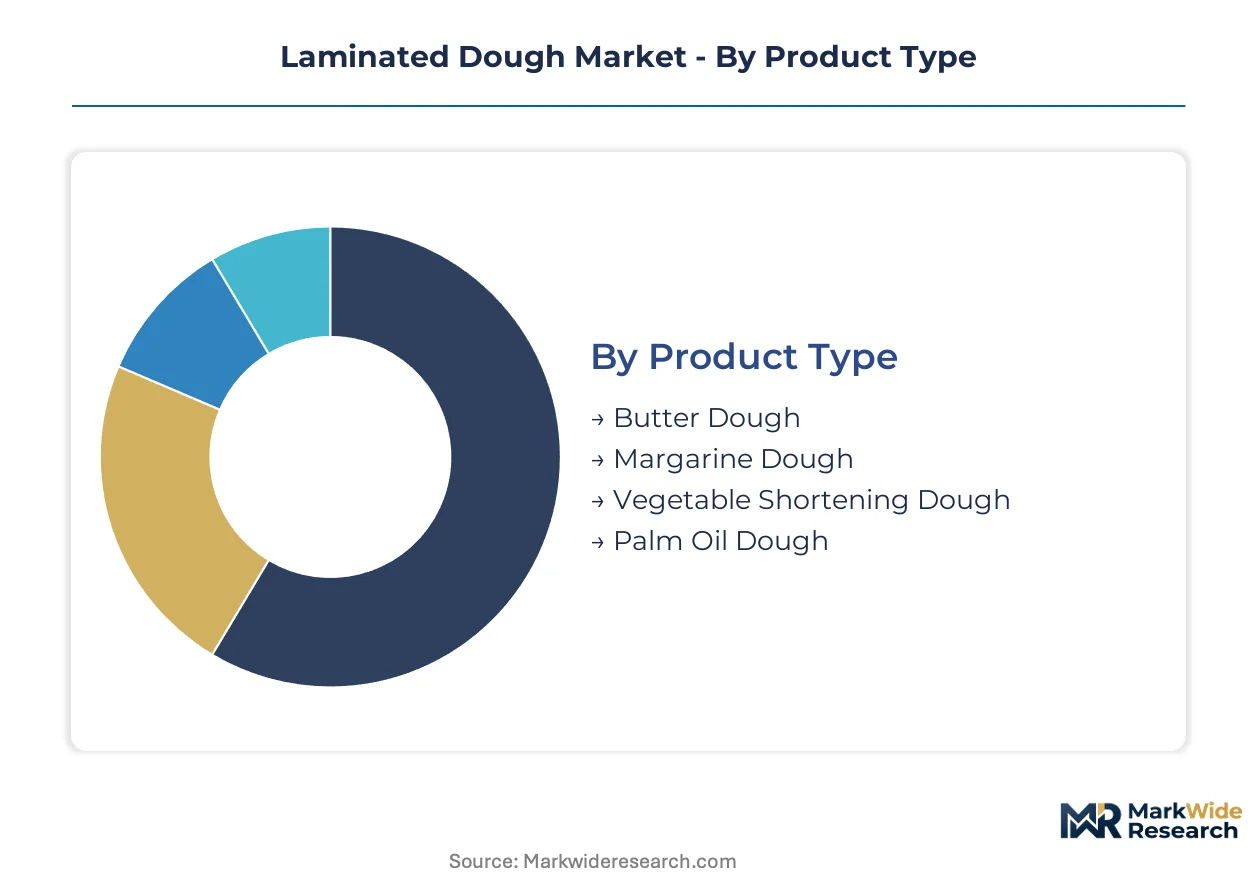
The laminated dough market exhibits distinct segmentation across key dimensions, reflecting varied production methods, end-use applications, and consumer preferences. Understanding these segments is critical for producers to tailor product offerings and distribution strategies effectively.
Product Type:
The product type segmentation highlights the diverse fat compositions employed in laminated dough production.
- Butter Dough:This premium product utilizes dairy butter as the laminating fat, imparting a rich flavor and superior flaky texture. Demand for butter dough concentrates in high-end bakeries and cafes in Western Europe, driven by consumer preference for artisanal quality.
- Margarine Dough:Margarine-based dough offers a cost-effective alternative to butter, providing good flakiness and extended shelf life. Cost-sensitive foodservice providers and industrial bakeries frequently procure margarine dough.
- Vegetable Shortening Dough:Formulations using vegetable shortening provide a neutral flavor profile and high plasticity, suitable for diverse pastry applications. This type is common in regions where specific dietary restrictions or cost pressures are prevalent.
- Palm Oil Dough:Laminated dough made with palm oil offers a stable and cost-efficient fat source, particularly when certified sustainable. Emerging markets in Asia-Pacific show significant procurement of palm oil dough due to its economic viability and functional properties.
Mature deployment sits with Margarine Dough. Newer deployment is concentrated in Palm Oil Dough.
Application:
The application segment illustrates the primary end-uses for laminated dough across various baked goods categories.
- Pastries:This broad category encompasses a wide array of sweet and savory baked goods, leveraging the flaky texture of laminated dough. Retail bakeries and cafes across North America utilize laminated dough for diverse pastry creations.
- Croissants:Croissants represent a dominant application, characterized by their crescent shape and distinct buttery, layered texture. Foodservice chains in the United States drive substantial demand for ready-to-bake frozen croissants.
- Danish:Danish pastries incorporate laminated dough with fruit or cream cheese fillings, popular as breakfast or dessert items. European in-store bakeries consistently feature Danish pastries, appealing to daily consumers.
- Puff Pastry:Puff pastry is a versatile, unsweetened laminated dough used for both sweet and savory dishes, known for its extreme flakiness. Industrial food manufacturers frequently procure puff pastry for frozen savory pies and desserts.
- Strudel:Strudel applications typically involve thin layers of laminated dough wrapped around fruit or cheese fillings, offering a traditional European dessert. Specialty food manufacturers in Germany and Austria maintain consistent demand for strudel dough.
Croissants maintain the largest volume share. Strudel applications show a steeper expansion trajectory.
End User:
Analysis by end user delineates the different commercial entities procuring laminated dough products.
- Bakeries:Traditional and artisanal bakeries utilize laminated dough for scratch-made products, valuing quality and consistency. Small-to-medium sized bakeries in France depend on high-quality laminated dough suppliers.
- Foodservice Providers:Quick-service restaurants, hotels, and cafes rely on ready-to-bake laminated dough for convenience and product uniformity. Large hospitality groups in the United Kingdom prioritize suppliers offering consistent frozen dough products.
- Convenience Stores:These outlets stock pre-baked or ready-to-finish laminated dough products for on-the-go consumption. Convenience store chains in Japan expand their offerings of baked goods using pre-made dough.
- Specialty Food Manufacturers:Companies producing specific frozen desserts, savory snacks, or gourmet items integrate laminated dough into their product lines. Manufacturers of frozen appetizers in Canada source specialized laminated dough.
Foodservice Providers command significant purchasing power. Specialty Food Manufacturers represent a niche yet expanding customer base.
Packaging Type:
The packaging type segment reflects the various material solutions used to preserve and distribute laminated dough.
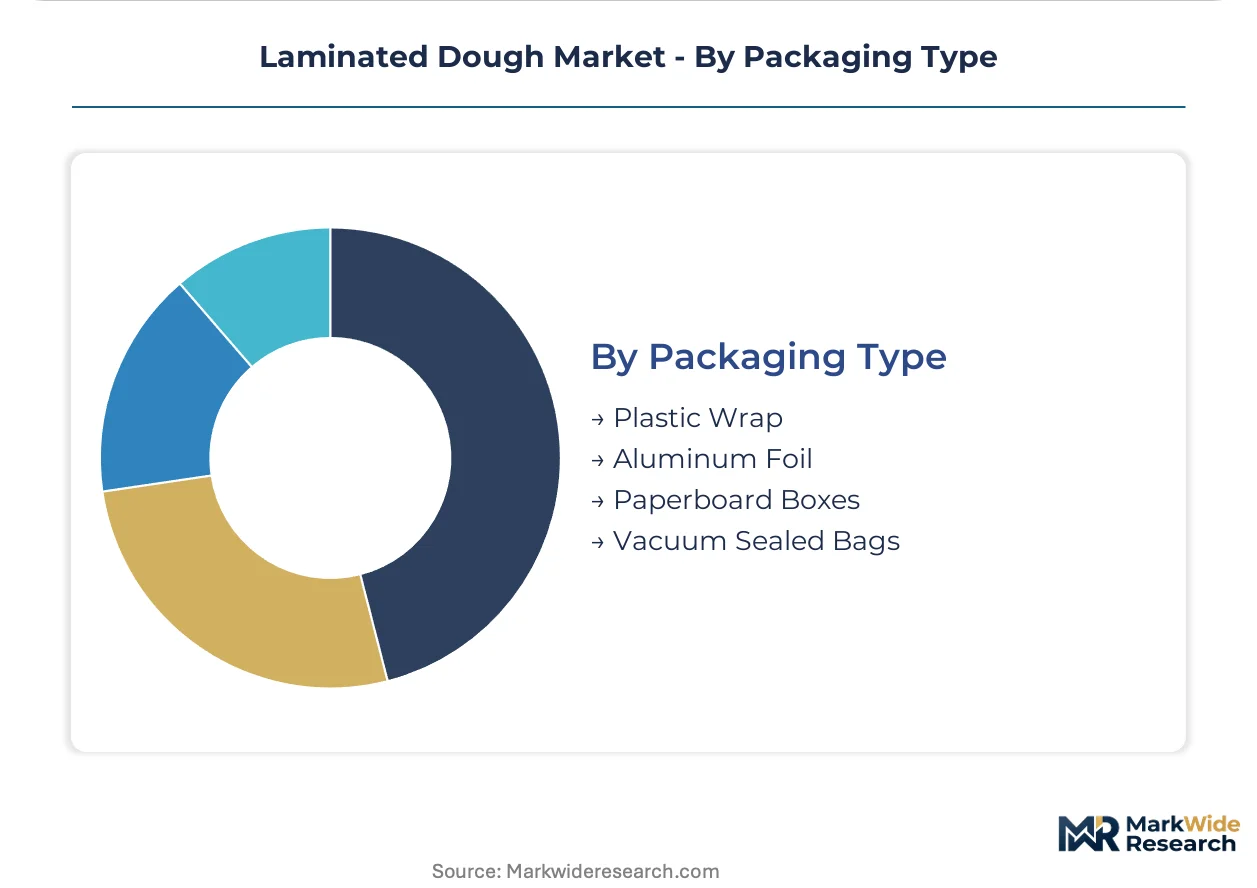
- Plastic Wrap:This cost-effective and flexible packaging protects dough from dehydration and contamination during transport and storage. Industrial bakeries extensively use plastic wrap for bulk frozen dough distribution.
- Aluminum Foil:Aluminum foil provides an excellent barrier against moisture, oxygen, and light, often used for premium or delicate laminated dough products. Specialty bakeries in Italy package delicate puff pastry sheets in aluminum foil.
- Paperboard Boxes:Paperboard boxes offer structural integrity and branding opportunities, commonly used for retail-ready frozen dough products. Supermarket chains in China distribute frozen croissants in branded paperboard boxes.
- Vacuum Sealed Bags:Vacuum sealing removes air, extending the shelf life of laminated dough by inhibiting microbial growth and freezer burn. High-volume foodservice operators in the United States procure vacuum-sealed dough for extended storage.
Plastic Wrap remains a dominant packaging choice for cost efficiency. Vacuum Sealed Bags are gaining share fastest due to extended shelf life requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for laminated dough products is particularly pronounced in key global markets. These regions exhibit strong consumer preferences for convenience and Western-style baked goods. Industrialization of bakery processes also drives procurement volumes across these areas.
China
China's market expansion for laminated dough stems from the westernization of diets and the growth of in-store bakeries. National food safety standards, like GB standards, guide product formulation and allergen labeling requirements for manufacturers. In-store bakeries within modern retail formats across Shanghai and Beijing create consistent, high-volume demand for standardized products.
United States
United States foodservice providers drive substantial demand for ready-to-bake laminated dough due to convenience and product uniformity needs. The US FDA mandates strict food safety and allergen labeling compliance for all imported and domestic goods. Fast-casual restaurant chains in cities like New York and Los Angeles increasingly adopt frozen dough solutions to reduce on-site labor.
Germany
German consumers value premium, butter-based pastries, fueling demand for high-quality laminated dough in traditional bakeries and cafes. The European Food Safety Authority (EFSA) influences permissible fat and additive limits across the country's food manufacturing sector. Specialty food manufacturers in Bavaria maintain consistent demand for strudel dough, focusing on artisanal quality.
India
India's laminated dough market sees significant growth from the proliferation of in-store bakeries within supermarkets and hypermarkets. The Food Safety and Standards Authority of India (FSSAI) regulates ingredients, hygiene, and labeling for baked goods across the nation. Supermarkets in Mumbai and Delhi expand their offerings using standardized frozen dough to cater to evolving consumer preferences.
Laminated Dough Market Key Industry Players
Capacity expansion dominates the current landscape, with major players investing in advanced automation technologies. The laminated dough market exhibits a tiered structure, where large-scale industrial producers coexist with specialized artisanal suppliers. Companies differentiate through ingredient quality, production efficiency, and extensive distribution reach to various end-user segments. Strategic archetypes include global ingredient managers, premium product specialists, and broad-line distributors with vast networks. Geographic expansion into emerging markets and portfolio diversification into plant-based alternatives represent dominant competitive moves.
Within the global ingredient management tier, Aryzta AG leverages its extensive manufacturing footprint to navigate ingredient sourcing volatility and ensure consistent supply. Lantmännen Unibake exemplifies a premium product specialist, differentiating its offerings with a portfolio of high-quality, butter-based pastries specifically for the discerning foodservice channel. Grupo Bimbo occupies a position as a broad-line distributor, utilizing its extensive distribution network to supply both retail bakeries and convenience store segments across diverse geographies, reaching a wide customer base.
| Leading Market Players |
|---|
| Aryzta AG |
| Lantmännen Unibake |
| CSM Bakery Solutions |
| Grupo Bimbo |
| Rich Products Corporation |
| Dawn Food Products, Inc. |
| General Mills |
| Creation Food Company |
| PURATOS Group |
| Others |
Cost & Logistics Intelligence
Certified sustainable palm oil mandates gate qualified supply access for cost-effective laminated dough, impacting pricing for both industrial producers and price-sensitive emerging markets. This regulatory pressure influences ingredient sourcing decisions throughout the supply chain.
Pricing Analysis
Volume-driven sales in the laminated dough market operate on a tiered pricing structure, differentiating between butter, margarine, and palm oil variants. Quality grade, such as butter content, and certification level for sustainable palm oil, are primary price differentiation drivers. Pricing pressure stems from global commodity price fluctuations, particularly for butter. Foodservice providers procuring margarine dough are highly price-sensitive, while premium cafes prioritize butter-based products.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks underpin the laminated dough cold chain, ensuring product integrity across diverse geographies. Supply concentration for butter originates primarily from Western Europe, while palm oil largely draws from Southeast Asian nations. Raw material dependencies include wheat flour, butter, and certified sustainable palm oil. Commodity price volatility represents a significant structural risk. Distribution runs through direct B2B channels to foodservice and retail bakeries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laminated dough market is undergoing a technology-transition phase, as advanced automated sheeting and folding systems increasingly replace traditional manual lamination techniques for mass production.
For Market Incumbents:Acquire specialized automation technology firms to enhance production efficiency and maintain consistent product quality. Incumbents must invest in clean-label reformulation R&D to counter the threat of healthier alternatives. Expanding cold chain infrastructure also mitigates spoilage risks across extended distribution networks. Focus on securing long-term contracts for certified sustainable ingredients.
For New Entrants and Emerging Players:Capture niche segments by developing plant-based and allergen-free laminated dough formulations. The premium direct-to-consumer channel for home bakers represents a highly penetrable segment. Go-to-market strategies should leverage online platforms and emphasize artisanal quality with transparent ingredient sourcing. Target middle-class consumers in Latin American countries.
For Investors and Strategic Acquirers:Significant investment in automated lamination technology is the leading indicator that industrialization is accelerating across the sector. Long-term viability remains strong, driven by convenience demand from foodservice and retail expansion. Acquisition targets should include mid-sized producers with established sustainable sourcing practices or proprietary clean-label dough formulations. Watch for shifts in large-scale ingredient procurement patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Automation Technology Integration | Enhances production consistency and reduces labor costs for industrial bakeries. |
| Plant-Based Portfolio Expansion | Unlocks access to growing vegan consumer segments and premium market niches. |
| Cold Chain Logistics Optimization | Minimizes product spoilage and maintains quality across extended distribution networks. |
| Emerging Market Distribution Partnerships | Facilitates market penetration and captures new consumer demand in high-growth regions. |
| Sustainable Sourcing Certification | Addresses consumer and regulatory demands for ethical and environmentally responsible ingredients. |
Research Approach
Multi-period observation of market volume, ingredient price trends, and regulatory updates anchored the trend analysis, supplemented by interviews with industrial bakery executives, foodservice procurement managers, and ingredient suppliers. Secondary data from food safety authority guidelines, trade publications, and company financial statements informed the analysis. Bottom-up and top-down triangulation validated market sizing.
The segment-weighting approach informed the analytical framework, projecting growth across product type, application, end user, and packaging type dimensions. Compound annual growth rates were derived from historical data and projected growth drivers over the analysis window. Ingredient price forecasts and foodservice expansion rates served as key industry-specific forecast inputs.
The model holds under stable global commodity markets and consistent regulatory enforcement; deviation in consumer health preferences or geopolitical events would shift projections. Forecasts reflect assumptions documented through primary and secondary research. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Pastry Dough Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
North America Sweet Biscuits Market
Bakery Products
Frozen Bakery Market
Bakery Products
Pastry Margarine Market
Bakery Products
Organic Bakery Products Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
Bread Market
Bakery Products
Tunnel Bakery Oven Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Pancake Mixes Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Frozen Bakery Products Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Baked Foods Market