
 Automatic Fish Scaling Machine Market | 2026-2036
Automatic Fish Scaling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Fish Scaling Machine Market Insights
Skilled fish processing labor is collapsing across North Atlantic and Southeast Asian fleets. BAADER sustains its position through captive supply of stainless steel scaling drums and integrated gutting lines. Grupo Josmar dominates Iberian and Latin American shore installations with heavy-duty hydraulic configurations. VMK Fish Machinery specializes in compact electric units for Baltic Sea cooperatives with limited deck space.
An automatic fish scaling machine removes dermal denticles and cycloid scales from fish surfaces using rotating abrasive drums, pressurized water jets, or pneumatic blade arrays operating at 200-800 RPM; the equipment serves commercial processors seeking HACCP-compliant throughput exceeding 50 fish per minute. Electric scalers anchor the installed base in European Union processing halls where MDR-aligned electrical safety certifications gate market access. Air scalers compete in Japanese and Korean facilities where METI energy-efficiency benchmarks favor pneumatic drive trains over hydraulic alternatives. Small-scale units for artisanal cooperatives occupy the fastest-expanding margin pool as developing coastal economies subsidize fleet modernization.
The EU Machinery Directive and CE marking framework mandate interlocked guarding and IP65 washdown ratings for equipment sold within member states. FDA HACCP protocols in the United States require validated scale-removal efficacy documentation for imported seafood entering interstate commerce. China's GB standards and SAMR enforcement impose stainless steel grade specifications that exclude lower-alloy constructions from coastal province tenders. Stakeholders must monitor divergence between EU MDR electrical safety requirements and FDA preventive control rules when configuring unified product platforms for cross-border sales.
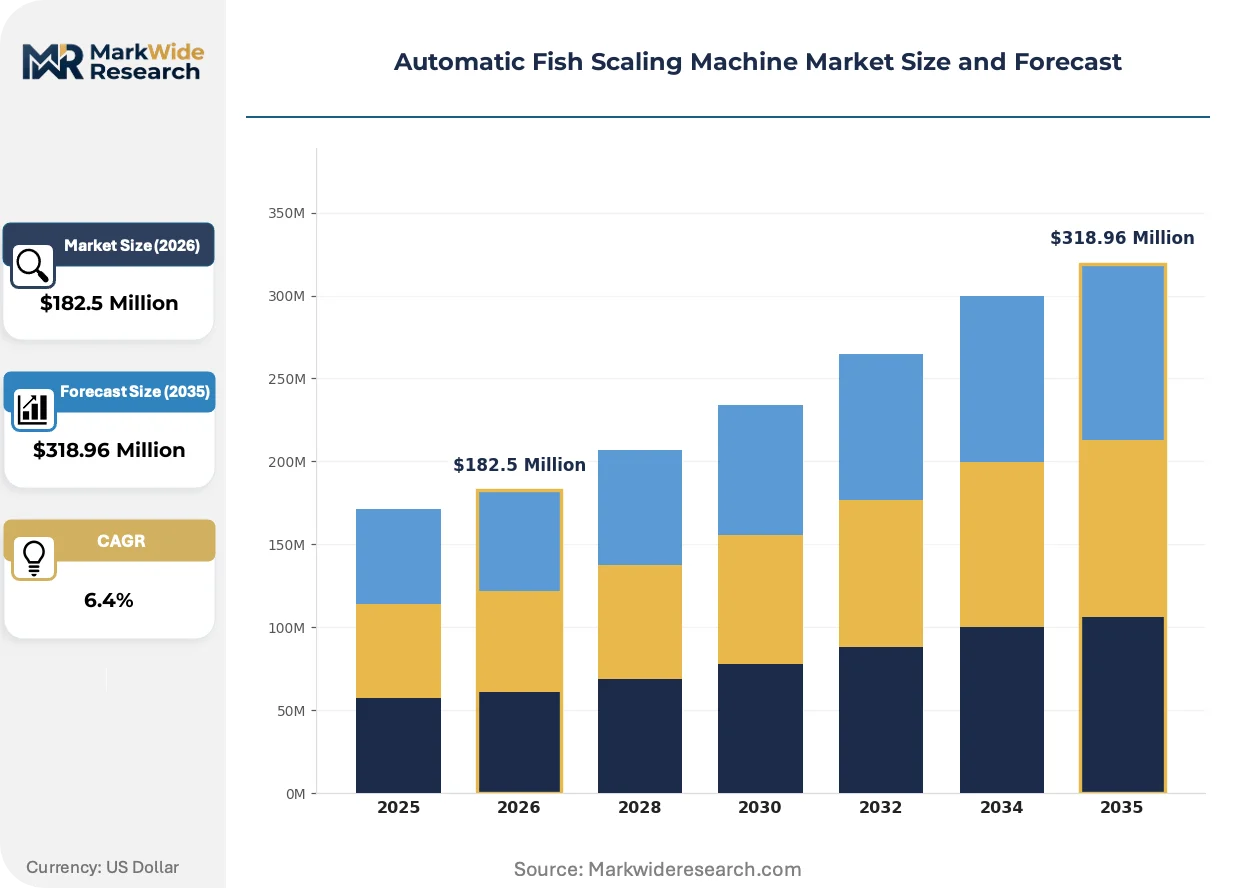
Market Dynamics
Commercial fisheries in Norway and Iceland are automating scaling operations to offset seasonal labor shortages, while EU Machinery Directive hygiene mandates tighten stainless steel specifications across coastal processing clusters.
Growth Catalysts
- EU Machinery Directive compliance:Interlocked guarding and IP65 washdown requirements force processor upgrades, accelerating replacement cycles in member-state harbors.
- Pneumatic drive efficiency:METI energy-efficiency benchmarks in Japan favor air scalers over hydraulic alternatives, redirecting procurement toward pneumatic blade arrays.
- Artisanal fleet modernization:Developing coastal economies subsidize compact electric units for cooperatives, expanding the addressable base beyond industrial processors.
Market Restraints
- Stainless steel grade concentration:China's GB standards and SAMR enforcement exclude lower-alloy constructions, restricting supplier pools for coastal province tenders.
- Input cost volatility:Nickel and chromium price swings directly compress margins on scaling drum fabrication.
- Regulatory divergence friction:MDR electrical safety requirements and FDA preventive control rules conflict, complicating unified product platform design.
Strategic Opportunities
- Vietnam processing cluster expansion:Coastal infrastructure investment creates demand for HACCP-compliant throughput equipment in emerging export hubs.
- Water jet-conveyor convergence:Integration of pressurized jet arrays with automated feed systems opens premium retrofit segments.
- PLI scheme alignment:India's production-linked incentives for food processing machinery reduce effective capex for fleet operators.
Industry Challenges
- Marine electrician scarcity:Salt-resistant wiring and sealed motor maintenance skills are scarce in North Atlantic fishing communities.
- CE-FDA dual certification timelines:Parallel validation for scale-removal efficacy documentation extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Fish Scaling Machine Market |
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $318.96 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Scalers, Manual Scalers, Air Scalers, Hydraulic Scalers End User: Commercial Fisheries, Restaurants, Seafood Processing, Aquaculture Size: Small, Medium, Large, Industrial Application: Freshwater Fish, Saltwater Fish, Fish Processing, Retail |
| Companies Covered | Pisces Fish Machinery Inc., Trifisk Manufacturing Inc., AGK Kronawitter, Varlet, Kroma, Auto Fish Scalers, BAADER, Grupo Josmar, VMK Fish Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Fish Scaling Machine Market Trends and Innovations
Scaling technology is splitting between heavy-throughput harbor installations and compact deck-mounted units, with regulatory pressure and labor availability determining which configuration dominates each geography.
Rotating abrasive drum design is bifurcating into two distinct performance tiers. High-RPM stainless steel configurations serve EU processing halls requiring 50+ fish per minute through validated HACCP lines. Low-RPM compact variants target Baltic Sea cooperatives with severe space constraints and intermittent power supply. This technical schism is compressing mid-range product viability, forcing vendors to commit to one performance archetype.
REACH substance restrictions and F-Gas Regulation phase-down schedules are reshaping hydraulic system specifications in European installations. Seawater-compatible synthetic fluids replace mineral oil formulations in scaling drum actuators. Norwegian processors lead substitution adoption, driven by harbor authority discharge permits and insurance liability clauses.
Buyer contracting patterns are fragmenting across vessel ownership structures. Large integrated fleets negotiate multi-year equipment leases with embedded maintenance. Independent owner-operators increasingly source through cooperative purchasing pools that aggregate demand for compact electric units. Chile's artisanal syndicates exemplify this collective procurement model, securing tiered pricing through volume commitments to regional distributors.
Automatic Fish Scaling Machine Market Segmentation
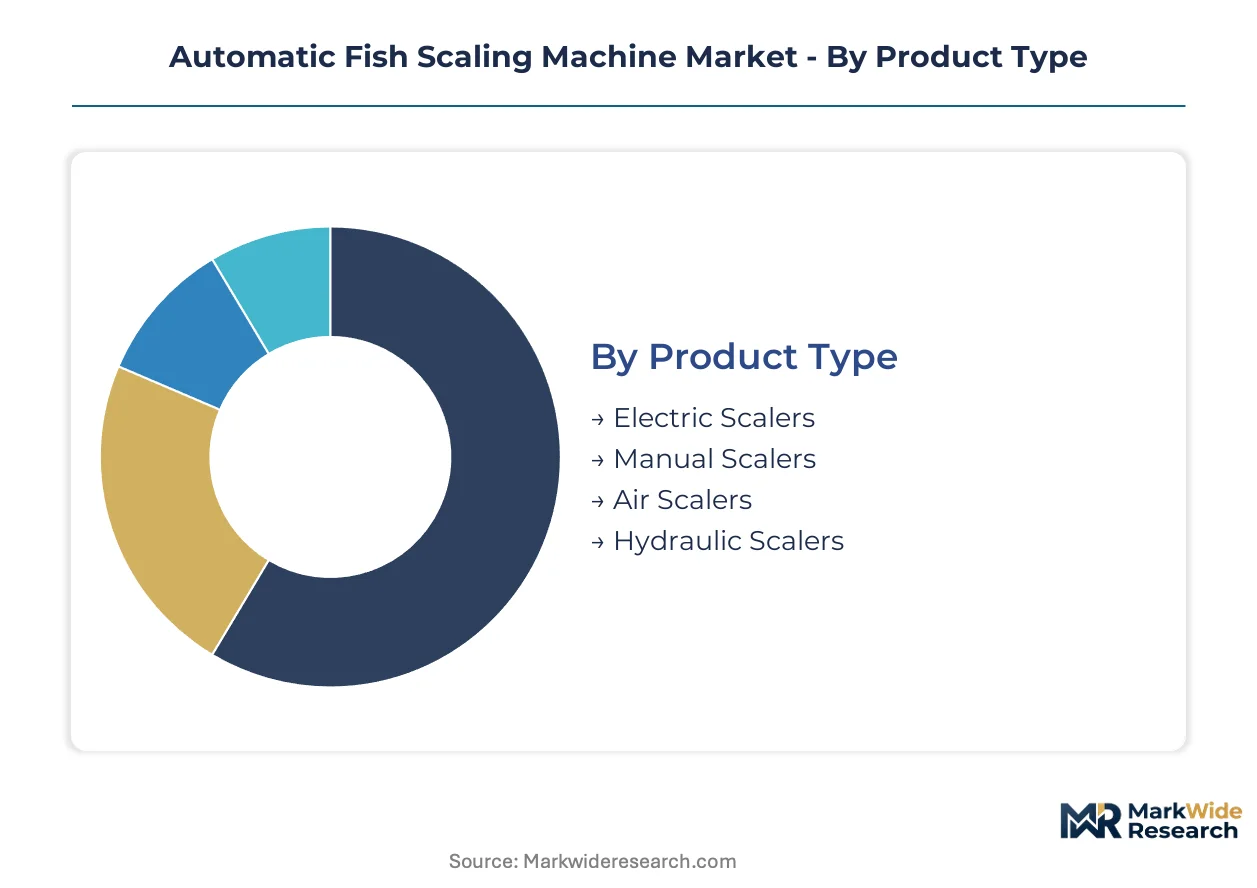
Equipment configuration in the automatic fish scaling machine market splits sharply between harbor-based industrial installations and vessel-deck compact units. Procurement channels diverge accordingly: integrated fleets negotiate direct manufacturer contracts, while artisanal cooperatives route through regional distributor pools.
Product Type:
Channel mix varies by drive mechanism. Electric scalers flow through EU-certified equipment dealers serving processing halls with MDR-aligned electrical safety requirements. Pneumatic and hydraulic units move through marine supply houses catering to vessel operators.
- Electric Scalers:Rotating abrasive drums powered by sealed motors deliver 200-800 RPM operation with IP65 washdown ratings mandatory under EU Machinery Directive. Demand concentrates in Norwegian and Icelandic shore facilities automating to offset seasonal labor shortages, with MDR certification gating market access in member states.
- Air Scalers:Pneumatic blade arrays operate without electrical hazard exposure in wet environments. Japanese and Korean processors favor these units where METI energy-efficiency benchmarks redirect procurement away from hydraulic alternatives, creating dedicated distribution through Pacific Rim marine equipment networks.
- Manual Scalers:Hand-held scraping tools persist in artisanal landing sites with unreliable power infrastructure.
- Hydraulic Scalers:Heavy-duty configurations dominate Iberian and Latin American shore installations requiring sustained high-torque operation.
By volume, electric scalers lead. By growth pace, air scalers are climbing the fastest.
End User:
Customer type determines specification tier and service bundling. Large-scale processors demand validated HACCP documentation and embedded maintenance contracts. Smaller operators prioritize capital efficiency and cooperative purchasing leverage.
- Commercial Fisheries:Fleet operators in Norway and Iceland automate scaling operations to compress labor dependency during peak seasonal landings. Equipment specifications emphasize stainless steel hygiene standards and throughput exceeding 50 fish per minute.
- Seafood Processing:Shore-based facilities in Vietnam, Chile, and coastal China integrate scaling lines with automated gutting and filleting systems. These installations drive demand for HACCP-compliant throughput equipment in emerging export hubs.
- Restaurants:High-volume kitchen operations in coastal tourism zones source compact countertop units through foodservice distributors.
- Aquaculture:Farm-to-processor integration in developing coastal economies creates demand for small-scale equipment subsidized through fleet modernization programs.
Commercial fisheries command the largest installed base. Seafood processing shows the steepest expansion trajectory as export infrastructure investment accelerates.
Size:
Physical footprint constraints split procurement between harbor installations with dedicated equipment halls and vessel-deck applications where cubic meter allocation is contested.
- Industrial:Fixed harbor installations with automated feed systems and pressurized water jet arrays serve high-throughput export processors. These units occupy dedicated equipment halls with integrated wastewater handling and validated scale-removal efficacy documentation for FDA interstate commerce requirements.
- Small:Compact deck-mounted electric units address Baltic Sea cooperatives with severe space constraints and intermittent shore power access. VMK Fish Machinery specializes in this configuration, serving limited-deck vessels through regional marine distributors.
- Medium:Modular configurations bridge harbor and vessel applications with reconfigurable feed mechanisms.
- Large:Semi-permanent shore installations with integrated conveyor systems serve multi-species processing hubs.
Industrial units generate the highest revenue per installation. Small units are gaining share fastest through artisanal fleet modernization subsidies.
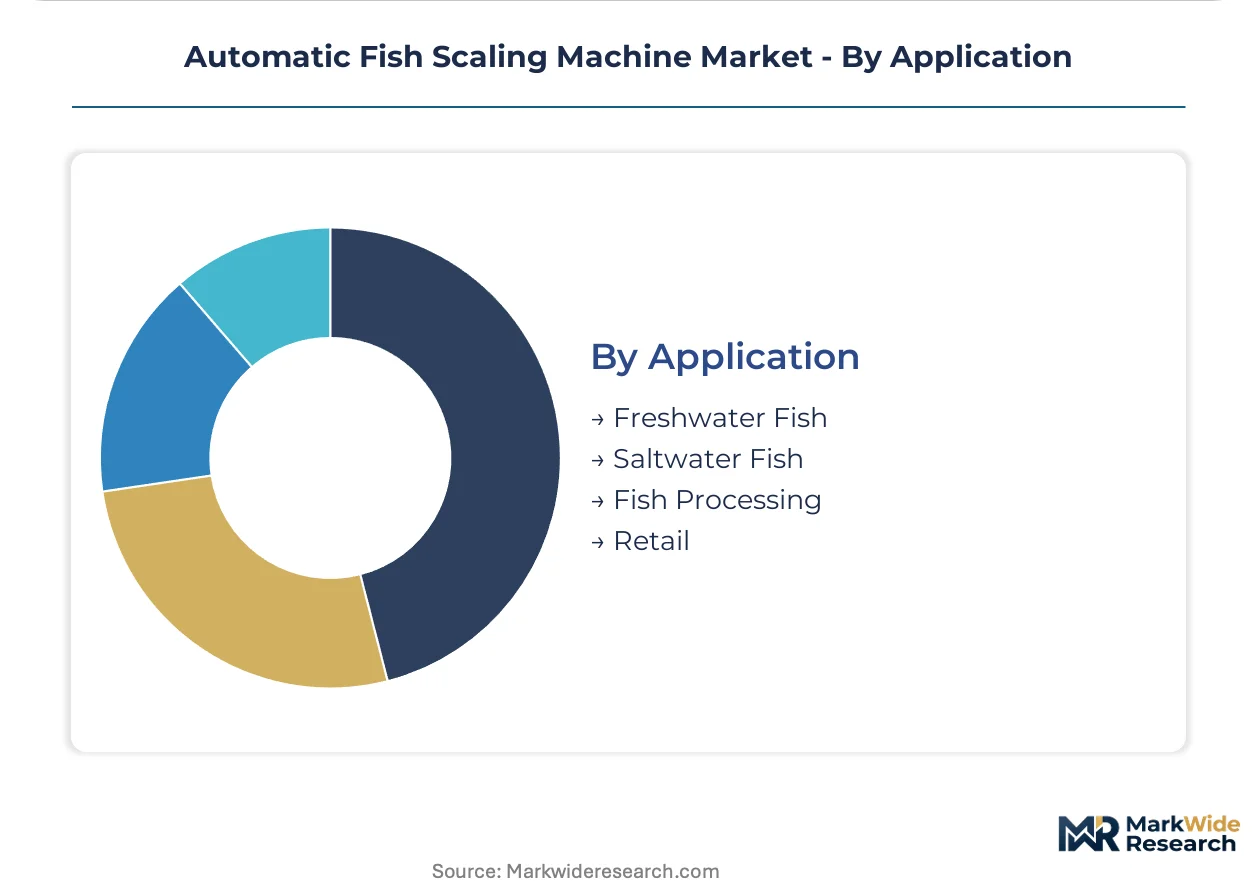
Application:
Species-specific scale morphology and regulatory destination dictate equipment selection. Cycloid scales on freshwater species respond to gentler abrasive treatment than dermal denticles on saltwater catches.
- Saltwater Fish:Dermal denticle removal from marine species requires aggressive abrasive drum configurations or high-pressure water jet arrays. Norwegian processors lead adoption of seawater-compatible synthetic hydraulic fluids under harbor authority discharge permit requirements.
- Fish Processing:Integrated scaling-gutting-filleting lines serve EU processing halls where CE marking and FDA HACCP dual certification extends product launch cycles by 8-14 months. BAADER sustains position through captive supply of stainless steel scaling drums in this segment.
- Freshwater Fish:Cycloid scale removal operates at lower RPM thresholds with reduced abrasive intensity.
- Retail:Point-of-sale scaling services in coastal markets demand compact, visually contained units with minimal splash containment.
Fish processing applications dominate revenue concentration. Saltwater fish handling is expanding most quickly as North Atlantic fleet automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian processors deploy harbor-based electric scalers for 50+ fish per minute throughput, while Vietnamese cooperatives favor compact deck-mounted units subsidized through fleet modernization programs. This consumption-mix differential separates high-automation North Atlantic infrastructure from emerging coastal clusters in Southeast Asia and Latin America.
Norway
Commercial fisheries automate scaling operations to compress labor dependency during peak seasonal landings. The EU Machinery Directive mandates interlocked guarding and IP65 washdown ratings for equipment sold through member-state harbors. Bergen and Tromsø processing clusters lead adoption of seawater-compatible synthetic hydraulic fluids under harbor authority discharge permits.
Vietnam
Coastal infrastructure investment creates demand for HACCP-compliant throughput equipment in emerging export hubs. The country's national food safety regulator enforces documentation requirements for seafood entering international commerce. Da Nang and Vung Tau processing zones integrate scaling lines with automated gutting systems serving EU and US export markets.
China
Shore-based facilities in coastal provinces drive demand for stainless steel equipment meeting GB standards and SAMR enforcement specifications. GB standards exclude lower-alloy constructions from government tenders. Qingdao and Dalian seafood processing clusters require validated scale-removal efficacy documentation for FDA-compliant export shipments.
Japan
Processors favor pneumatic blade arrays where METI energy-efficiency benchmarks redirect procurement away from hydraulic alternatives. METI standards create dedicated distribution channels through Pacific Rim marine equipment networks. Osaka and Hokkaido fishing cooperatives source air scalers to eliminate electrical hazard exposure in wet deck environments.
Chile
Artisanal syndicates aggregate demand through cooperative purchasing pools securing tiered pricing from regional distributors. The country's national fisheries development program subsidizes compact electric units for fleet modernization. Puerto Montt and Talcahuano landing sites exemplify collective procurement models expanding the addressable base beyond industrial processors.
Automatic Fish Scaling Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive supply chains and certification depth separating the two strata. The upper tier commands premium positioning through stainless steel scaling drum fabrication and dual CE-FDA certification capabilities. Specialists compete on compact configurations for space-constrained vessel decks and intermittent power access. Dominant competitive moves include backward integration into stainless steel component supply and geographic expansion through regional distributor partnerships.
Among European fabricators, AGK Kronawitter and Varlet occupy positions within the precision-engineering archetype, while Kroma exemplifies the Nordic specialist tier focused on harbor-scale installations. BAADER anchors the integrated leader category through captive supply of stainless steel scaling drums, with Grupo Josmar representing the heavy-duty hydraulic configuration segment serving Iberian and Latin American markets. VMK Fish Machinery sits within the compact electric unit specialization, serving Baltic Sea cooperatives through regional marine distributors.
| Leading Market Players |
|---|
| Pisces Fish Machinery Inc. |
| Trifisk Manufacturing Inc. |
| AGK Kronawitter |
| Varlet |
| Kroma |
| Auto Fish Scalers |
| BAADER |
| Grupo Josmar |
| VMK Fish Machinery |
| Others |
Pricing and Supply Chain Analysis
Seawater-compatible synthetic hydraulic fluid substitution in Norwegian harbor installations simultaneously shifts procurement geography toward Baltic chemical suppliers and compresses maintenance contract pricing by eliminating mineral oil disposal liability premiums. This input transition reshapes total cost of ownership calculations across North Atlantic fleet operators.
Pricing Analysis
Long-term equipment leases with embedded maintenance dominate contracting among large integrated Norwegian and Icelandic fleets, while spot procurement persists for compact electric units in Chilean artisanal syndicates. Three-tier pricing structure across premium, standard, and economy levels separates CE-FDA dual-certified systems from single-market units and basic hydraulic configurations. Pricing pressure stems from nickel and chromium volatility on scaling drum fabrication, compressing margins on stainless steel components. Artisanal cooperatives exhibit highest price sensitivity due to subsidy-dependent budgets, whereas export processors prioritize throughput validation over capital cost.
Supply Chain Analysis
Inventory lead times for sealed marine motors stretch 14-20 weeks, forcing Norwegian processors to pre-position spares before seasonal peaks. Component fabrication concentrates in Germany, Denmark, and coastal China, with stainless steel scaling drums drawing from specialized Nordic metalworking clusters. Supply chains rest on nickel alloy sheet and precision bearing imports, exposing fabricators to commodity price swings. Single-source vulnerability sits with marine-grade motor suppliers serving the IP65 washdown segment. Distribution runs through EU-certified equipment dealers for shore installations and marine supply houses for vessel-deck units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automatic fish scaling equipment penetration remains in early-cycle expansion, with artisanal fleet modernization subsidies in Chile and Vietnam creating addressable market growth faster than replacement demand in mature North Atlantic harbors.
For Market Incumbents: Consolidate position through captive supply of stainless steel scaling drums and accelerated CE-FDA dual certification pipelines to defend against emerging Asian fabricators with cost-advantaged pneumatic configurations. Deepen backward integration into nickel alloy sourcing to offset raw material volatility. Prioritize harbor authority discharge permit alignment in Norway as a regulatory moat. For New Entrants and Emerging Players: After-sales service networks in Baltic Sea cooperatives represent an incumbent underserve, creating entry opportunity through maintenance bundling with compact electric units. Target Vietnamese coastal processing clusters where HACCP documentation capability gaps persist among local distributors. Pursue cooperative purchasing pool partnerships in Latin America rather than direct fleet sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European precision engineering specialists holding MDR certification depth but limited Asia-Pacific distribution. Five-to-ten year viability hinges on regulatory divergence arbitrage capability. Monitor India's PLI scheme uptake rates as inflection signal for capital expenditure timing in emerging coastal economies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Component Supply | Captive scaling drum fabrication insulates margins from nickel volatility and secures CE marking compliance. |
| Dual Certification Pipeline Investment | Parallel FDA HACCP and EU MDR validation compresses product launch cycles by 8-14 months. |
| Cooperative Purchasing Pool Partnerships | Chilean artisanal syndicate aggregation models expand addressable base beyond industrial processors. |
| Seawater-Compatible Fluid System Development | Synthetic hydraulic formulations satisfy Norwegian harbor authority discharge permits and insurance clauses. |
| Regional Distributor Network Expansion | Vietnam and Baltic Sea marine supply house relationships penetrate emerging coastal clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing fleet maintenance directors at Norwegian commercial fisheries, procurement leads at Vietnamese seafood processing exporters, marine equipment distributors serving Baltic Sea cooperatives, and harbor authority compliance officers. Secondary validation drew from EU Machinery Directive implementation guidance, FDA HACCP seafood processing protocols, METI energy-efficiency benchmark disclosures, and Chilean fisheries development program documentation. Bottom-up equipment shipment tallies were triangulated against top-down coastal processing capacity estimates.
Across the projection horizon, the analytical framework modeled segmentation across drive mechanism type, end-user scale tier, physical footprint category, and species application. CAGRs were derived from equipment replacement cycle analysis, regulatory mandate compliance deadlines, and fleet modernization subsidy allocation trajectories. Forecast inputs incorporated stainless steel grade specification divergence between EU and Chinese regulatory regimes, plus seasonal labor shortage severity indices in North Atlantic fishing communities.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement, FDA preventive control rules, and METI energy-efficiency benchmarks; material policy shifts would require re-modeling of replacement demand timing and certification cost burdens. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Filleting Machines Market
Food Processing Equipment
Food Recycler Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
Freeze-Drying Equipment Market
Food Processing Equipment
Commercial Panini Machine Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Dispensing Systems and Equipment Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
Tomato Processing Machine Market