
 Low-Sugar Rice Cooker Market | 2026-2036
Low-Sugar Rice Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Sugar Rice Cooker Market Insights
Steam-separation engineering is tilting low-sugar rice cooker design toward precision carbohydrate-reduction without texture degradation. Toshiba leverages proprietary vacuum-pressure algorithms to sustain premium positioning in Japanese households. Xiaomi anchors its competitive stance through aggressive cost engineering and ecosystem integration across Chinese smart-home platforms. SUPOR dominates Southeast Asian mass retail through localized voltage configurations and regional warranty networks.
A low-sugar rice cooker employs controlled heating profiles and specialized inner-pot geometry to drain dissolved starch during the cooking cycle, typically reducing carbohydrate content by a measurable fraction compared to conventional boiling. The device serves consumers managing blood-glucose levels while preserving the sensory attributes of steamed rice. Multi-function cookers lead volume shipments by bundling porridge, soup, and slow-cook modes that justify higher price points. Smart rice cookers represent the fastest-expanding technology segment as Wi-Fi-enabled recipe libraries and app-based glycemic tracking attract digitally native health-focused consumers. Electric rice cookers retain the largest installed base but face margin compression from commoditized induction alternatives.
China's SAMR enforces GB standards for food-contact materials and appliance safety certification that determine factory gate access. Japan's METI operates mandatory energy-efficiency labeling that filters import eligibility and shapes consumer purchase calculus. South Korea's MFDS maintains electrical safety protocols for kitchen appliances sold through domestic retail channels. Stakeholders must monitor how evolving national nutrition-labeling frameworks and smart-appliance cybersecurity mandates recalibrate compliance investment thresholds.
Market Dynamics
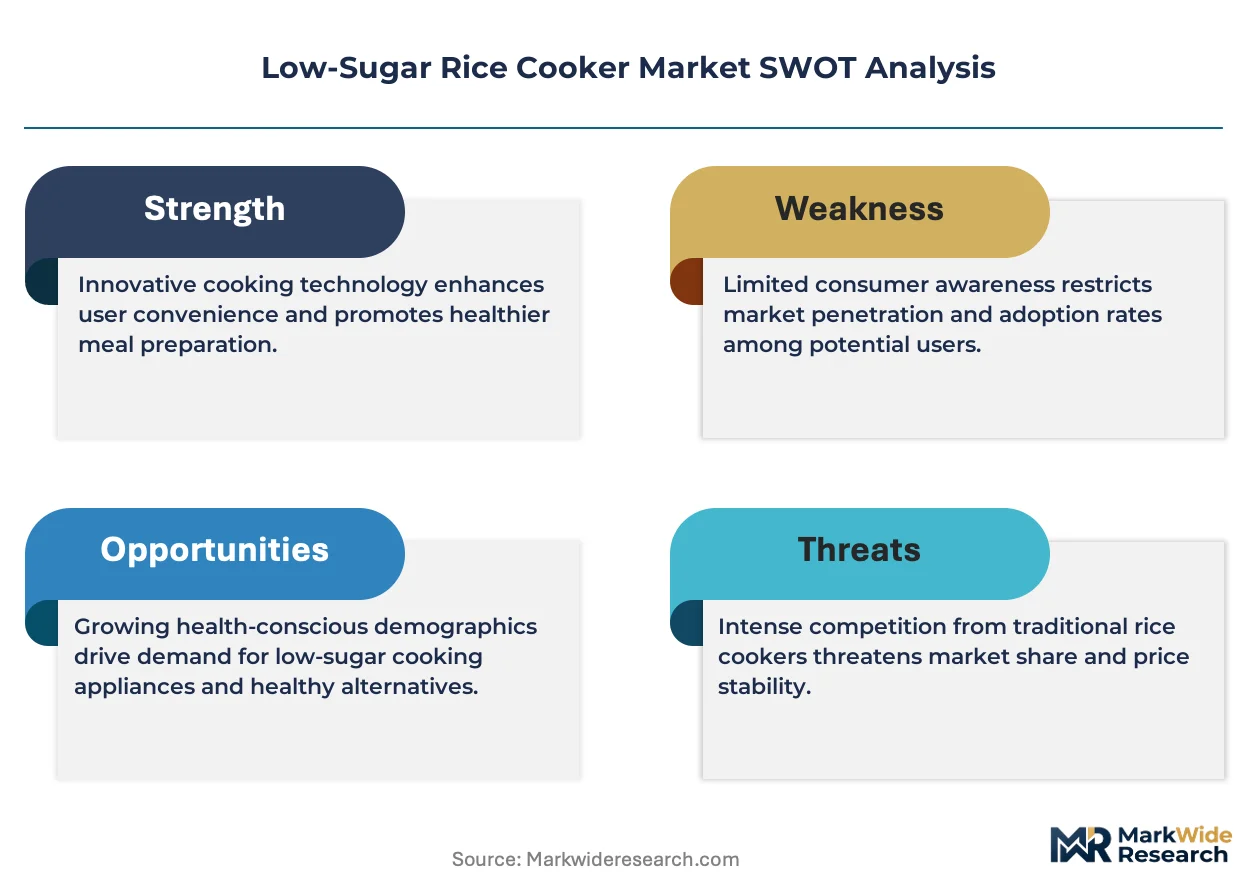
Steam-separation engineering is compressing R&D cycles across the low-sugar rice cooker sector as manufacturers race to patent precision carbohydrate-reduction mechanisms without degrading rice texture. This technical arms race is reshaping factory investment priorities and supplier qualification timelines.
Growth Catalysts
- GB Standards Compliance:China's SAMR enforcement of food-contact material certification is accelerating factory modernization and filtering out subscale producers who cannot absorb testing costs.
- Smart-Home Ecosystem Integration:Wi-Fi-enabled glycemic tracking and recipe libraries are pulling digitally native health-conscious consumers toward app-connected cooking appliances.
- East Asian Urban Households:Concentrated demand in Chinese and Japanese cities where rice remains dietary staple and diabetes-prevention awareness drives replacement cycles.
Market Restraints
- Stainless Steel Input Volatility:Inner-pot grade 304/316 stainless prices swing with nickel and chromium futures, compressing margins on mid-tier induction models.
- Southeast Asian Supply Concentration:SUPOR's dominance in regional mass retail creates channel gatekeeping that limits new entrant shelf access.
- Technical Ceiling on Carbohydrate Reduction:Current steam-separation physics caps measurable starch removal without unacceptable texture degradation, constraining premium pricing justification.
Strategic Opportunities
- Underpenetrated Indian Market:Rising diabetic population and government nutrition awareness campaigns create whitespace for localized voltage and voltage-stabilized models.
- METI Energy-Efficiency Labeling:Japan's mandatory efficiency tiers reward inverter-technology investment with retail visibility and import eligibility advantages.
- Convergence of IoT Sensors and Glycemic Index Databases:Real-time starch-content estimation paired with personalized meal-planning apps opens subscription revenue streams.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for precision temperature profiling and app connectivity outpaces vocational pipeline output in Guangdong and Zhejiang manufacturing clusters.
- MFDS Electrical Safety Certification Timelines:South Korea's multi-stage testing protocol for kitchen appliances extends product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Sugar Rice Cooker Market |
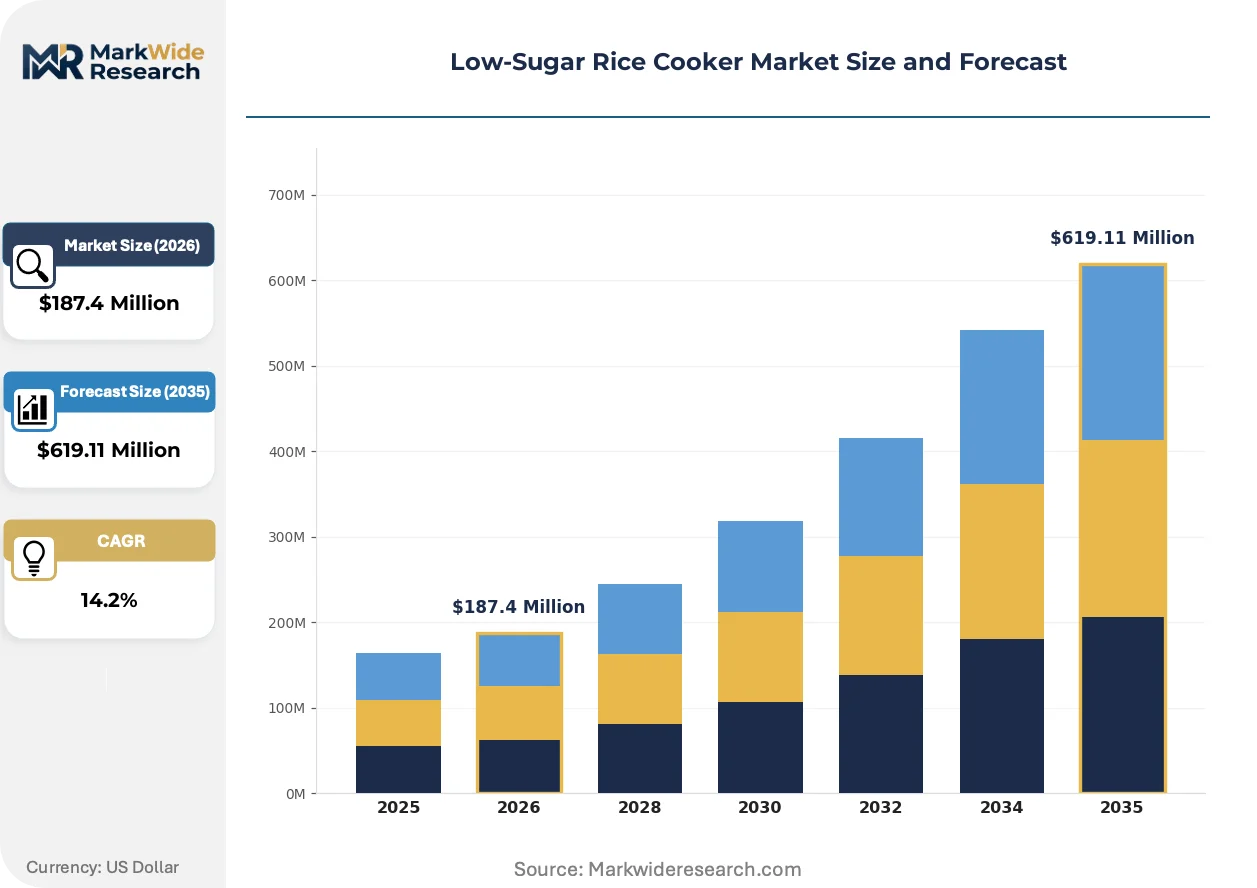
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Function Cookers, Electric Rice Cookers, Induction Rice Cookers, Smart Rice Cookers End User: Home Kitchens, Restaurants, Catering Services, Health-Focused Consumers Technology: Fuzzy Logic, Pressure Cooking, Steam Cooking, Automated Cooking Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Toshiba, Xiaomi, SUPOR, Philips, Panasonic, Zojirushi, Cuckoo Electronics, Midea, Tiger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Sugar Rice Cooker Market Trends and Innovations
Vacuum-pressure algorithms and IoT-enabled cooking profiles are fragmenting the traditional electric rice cooker category into precision-health appliances. Manufacturers now compete on biochemical outcomes rather than basic convenience features.
Induction heating with fuzzy-logic temperature control is hybridizing low-sugar rice cooker engineering by enabling millisecond-level thermal adjustments during starch-draining phases. Health-focused households in Japanese and Chinese urban centers are adopting these systems at replacement-cycle velocity. The technology is hybridizing supply chains as semiconductor-grade temperature sensors displace mechanical thermostats and redraw component sourcing maps.
China's NMPA food-contact material standards are tightening migration limits for heavy metals and plasticizers in inner-pot coatings. Industrial consequence includes mandatory third-party laboratory testing for every production batch and SKU. Premium smart-cooker segments targeting export markets are responding fastest, absorbing certification costs into pricing while economy-tier producers retreat to domestic-only distribution.
Subscription-based recipe and nutrition-tracking services are unbundling from hardware purchases and creating recurring revenue attachments. Direct-to-consumer channels in South Korea and Taiwan are displacing traditional appliance retail for connected models. This shift concentrates most visibly in Seoul and Taipei metropolitan zones where smartphone-native buyers prefer app-managed cooking workflows over standalone device operation.
Low-Sugar Rice Cooker Market Segmentation
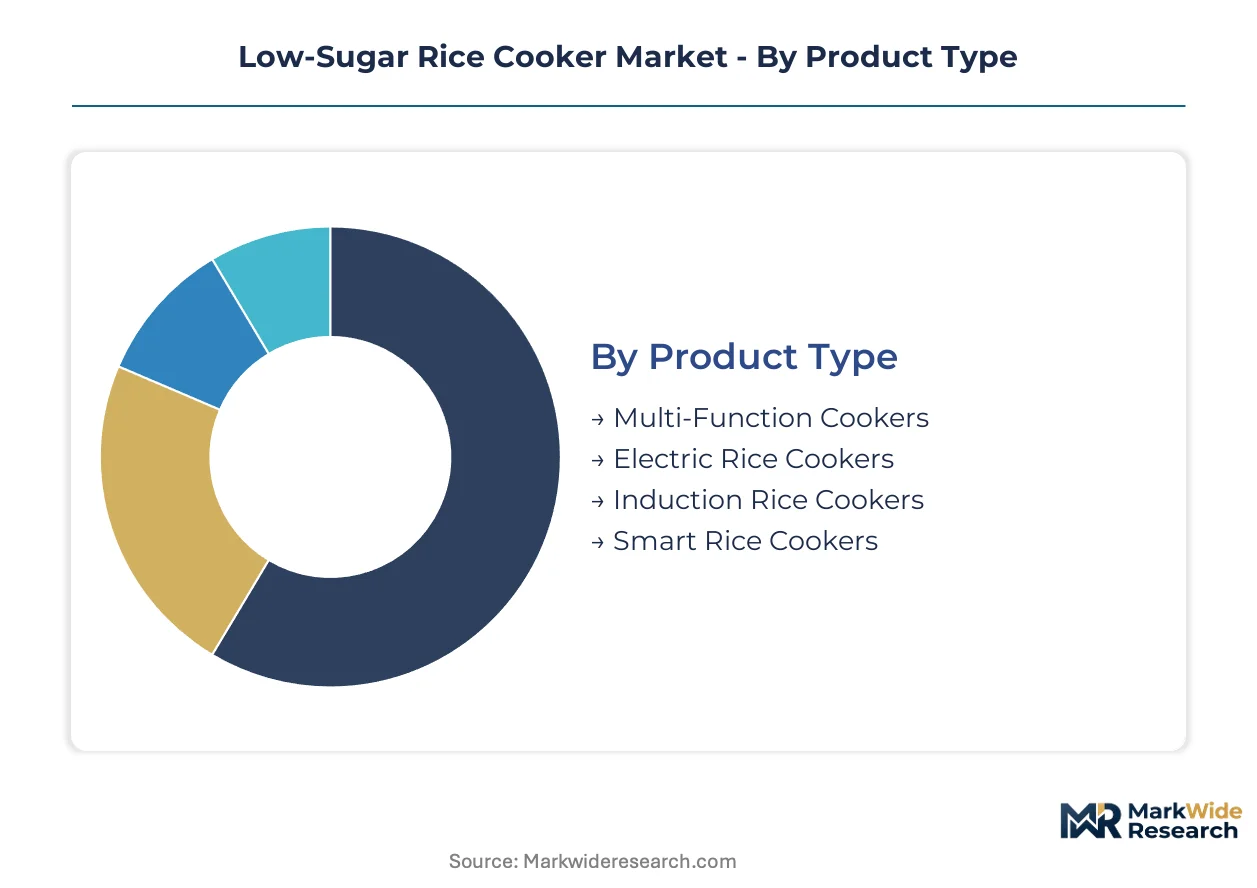
Segmentation in the low-sugar rice cooker market reveals how health-conscious households, commercial foodservice operators, and technology adopters drive divergent product requirements. Manufacturers calibrate feature sets, certification tiers, and channel strategies against these distinct demand profiles.
Product Type:
Product type segmentation traces the use-case spectrum from basic carbohydrate reduction to integrated smart-home health management.
- Multi-Function Cookers:These units bundle porridge, soup, slow-cook, and low-sugar rice modes into single appliances. Demand concentrates in Chinese urban households where countertop space constraints and meal variety preferences justify premium price points. The versatility driver offsets higher unit costs through consolidated appliance replacement.
- Smart Rice Cookers:Wi-Fi-enabled models with app-based glycemic tracking and recipe libraries are climbing the fastest among digitally native consumers in Seoul and Taipei metropolitan zones. Firmware integration with health-monitoring ecosystems distinguishes premium positioning.
- Electric Rice Cookers:Conventional heating-element designs retain the largest installed base across East Asian mass retail.
- Induction Rice Cookers:Electromagnetic heating with millisecond temperature precision supports advanced starch-separation algorithms.
Established volume favors electric rice cookers; emerging adoption favors smart rice cookers.
End User:
End user segmentation maps cost tier differentiation from mass-market home penetration to specialized institutional procurement.
- Home Kitchens:Individual households seeking diabetes-prevention tools or weight management support constitute the core demand pool. Replacement cycles in Japanese and Chinese cities accelerate as health-awareness campaigns elevate low-sugar cooking from niche to standard practice.
- Health-Focused Consumers:This segment prioritizes verified glycemic outcomes over price sensitivity, driving demand for NMPA-certified and METI-labeled precision models. Concentrated adoption appears in high-income districts of Shanghai, Tokyo, and Singapore where preventive healthcare spending displaces conventional appliance budgets.
- Restaurants:Commercial kitchens adopt low-sugar rice cookers to menu diabetic-friendly options without separate preparation infrastructure.
- Catering Services:Institutional food providers respond to government nutrition guidelines in South Korea and Japan with batch-capacity procurement.
Volume concentration sits with home kitchens; margin expansion sits with health-focused consumers.
Technology:
Technology segmentation reflects maturity gradients from proven fuzzy-logic controllers to emerging automated glycemic estimation.
- Fuzzy Logic:Microprocessor-controlled temperature curves adjust heating intensity based on rice variety and ambient conditions. This proven architecture dominates mid-tier manufacturing in Guangdong and Zhejiang clusters where supply chain scale minimizes component costs.
- Steam Cooking:Controlled steam-separation mechanisms drain dissolved starch during cooking cycles without pressure vessels. Demand clusters in Japanese households where texture preservation ranks equal to carbohydrate reduction in purchase decisions.
- Pressure Cooking:Vacuum-pressure algorithms enable higher starch extraction rates through elevated boiling temperatures.
- Automated Cooking:Sensor-driven systems with real-time starch-content estimation remain at pilot deployment stage.
Manufacturing scale favors fuzzy logic; patent activity favors steam cooking.
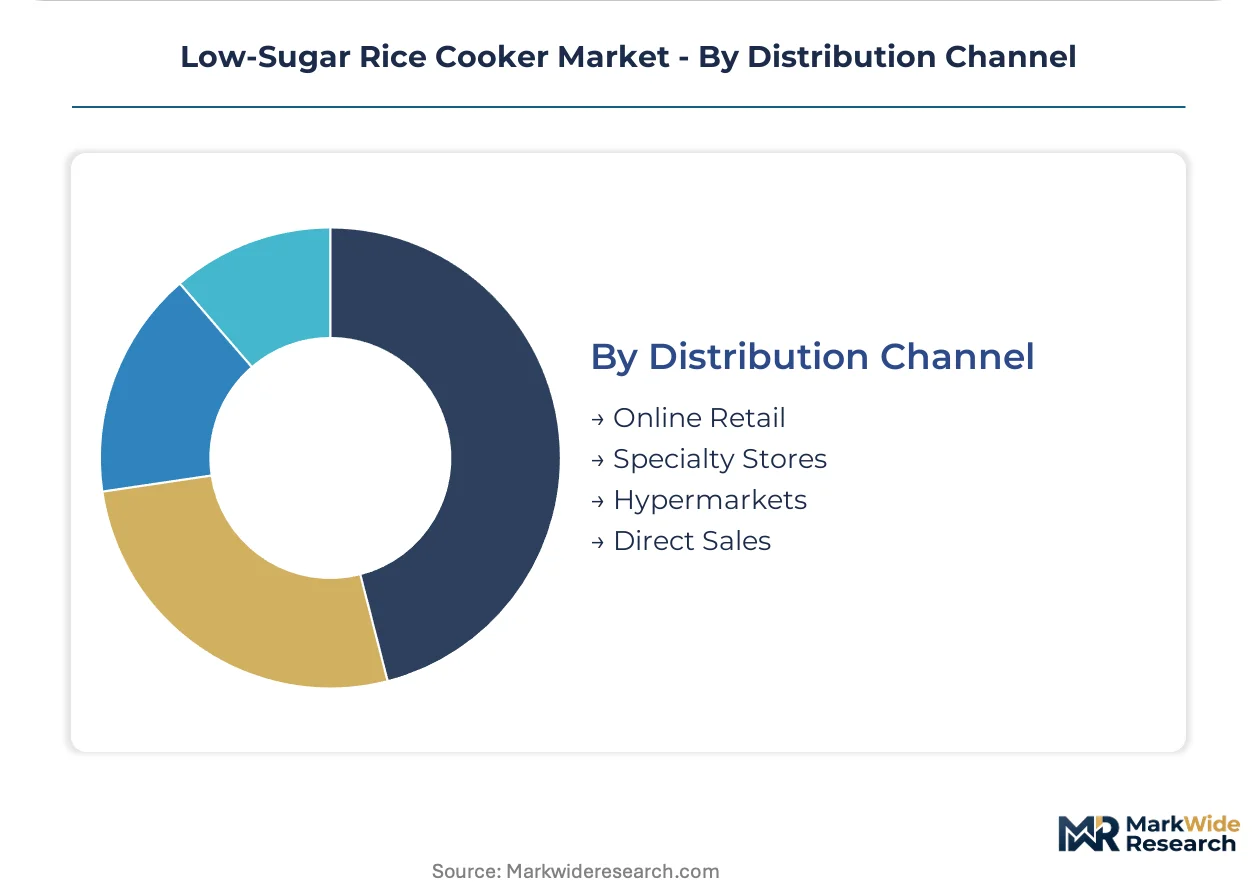
Distribution Channel:
Distribution channel segmentation tracks how purchase behavior fragments between digital-native discovery and tactile retail evaluation.
- Online Retail:E-commerce platforms capture the steepest expansion trajectory for connected models where specifications, certification documentation, and user reviews substitute for physical inspection. Direct-to-consumer channels in South Korea and Taiwan displace traditional appliance retail for Wi-Fi-enabled inventory.
- Specialty Stores:Kitchenware boutiques and health-appliance showrooms provide hands-on demonstration of steam-separation mechanics. Concentrated presence in Tokyo's Shinjuku and Osaka's Umeda districts supports premium brand positioning through trained sales consultation.
- Hypermarkets:Mass retail chains anchor volume throughput for economy and standard tier electric cookers across Southeast Asian urban centers.
- Direct Sales:Manufacturer-owned channels support warranty integration and subscription service attachments.
Volume throughput runs through hypermarkets; customer lifetime value runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-focused households in East Asian urban centers drive regional demand concentration, with diabetes-prevention awareness accelerating replacement cycles in cities where rice dominates dietary intake. Procurement patterns split between premium precision-engineered models in Japanese and Korean metros and cost-optimized mass-market units across Chinese and Southeast Asian retail channels.
China
Shanghai and Beijing households anchor volume demand for smart-connected low-sugar rice cookers with app-based glycemic tracking. SAMR enforcement of GB food-contact material standards filters factory gate access, accelerating modernization in Guangdong and Zhejiang manufacturing clusters where third-party laboratory testing has become mandatory for export-bound production.
Japan
Tokyo and Osaka metropolitan zones prioritize texture-preserving steam-separation engineering alongside carbohydrate reduction. METI mandatory energy-efficiency labeling shapes import eligibility and retail visibility, rewarding inverter-technology investment with tiered consumer-facing ratings that influence purchase decisions in high-income districts.
South Korea
Seoul's smartphone-native buyers displace traditional appliance retail through direct-to-consumer channels for Wi-Fi-enabled inventory. MFDS multi-stage electrical safety certification extends product launch windows, compressing effective market entry timelines for firmware-integrated models targeting health-monitoring ecosystem convergence.
India
Maharashtra and Karnataka urban centers present whitespace opportunity as government nutrition awareness campaigns elevate diabetic-prevention cooking. Localized voltage configurations and voltage-stabilized engineering address grid instability in Delhi-NCR and Mumbai metros where rising middle-class health expenditure outpaces dedicated appliance penetration.
Vietnam
Ho Chi Minh City and Hanoi households drive Southeast Asian adoption of multi-function cookers bundling low-sugar rice with porridge and soup modes. Regional warranty networks and localized voltage standards determine shelf access in mass retail channels where SUPOR's established presence creates channel gatekeeping for new entrants.
Low-Sugar Rice Cooker Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The structure fragments between mass-market volume leaders with retail shelf dominance and precision-engineering specialists commanding premium positioning through patented starch-separation algorithms. Three archetypes dominate: ecosystem-integrated smart-home platforms, steam-separation technology patent holders, and regional mass-retail channel controllers. Competitive moves concentrate on firmware differentiation for health-app connectivity and backward integration into semiconductor-grade temperature sensor supply.
Within the precision-engineering tier, Toshiba and Zojirushi occupy positions anchored by vacuum-pressure algorithm development, while Xiaomi exemplifies ecosystem-integrated cost engineering through smart-home platform penetration. SUPOR represents regional channel control through Southeast Asian mass-retail network density. Cuckoo Electronics and Tiger sit within Korean and Japanese domestic-market specialization archetypes respectively.
| Leading Market Players |
|---|
| Toshiba |
| Xiaomi |
| SUPOR |
| Philips |
| Panasonic |
| Zojirushi |
| Cuckoo Electronics |
| Midea |
| Tiger |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Ningbo freight corridor's container cost dynamics amplify pricing power for Guangdong-based manufacturers while compressing margins for Southeast Asian assemblers dependent on Chinese component inflows. This logistics geometry concentrates supply-side leverage among Zhejiang and Guangdong factory clusters, forcing downstream price differentiation between METI-certified premium exports and domestic-only economy tiers.
Pricing Analysis
Cost-plus contracts with nickel and chromium futures indexation dominate mid-tier induction cooker procurement. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-certified smart models from basic electric units and unbranded white-label inventory. Pricing pressure stems from stainless steel input volatility, particularly affecting 304/316 inner-pot grades. Mass-market Southeast Asian buyers exhibit highest price sensitivity, while Japanese health-focused consumers prioritize texture-preserving engineering over unit cost.
Supply Chain Analysis
Upstream feedstock for semiconductor-grade temperature sensors draws from Taiwan, South Korea, and Japan, while 304/316 stainless steel inner pots rest on Chinese and Indonesian nickel processing. Inner-pot coatings, fuzzy-logic microprocessors, and Wi-Fi modules constitute critical component dependencies. Single-source vulnerability concentrates in Taiwan-sourced sensor chips amid geopolitical friction. Distribution runs through hypermarket chains for economy tiers, direct-to-consumer platforms for connected models, and specialty kitchenware boutiques for premium steam-separation units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—specifically NMPA batch-testing mandates and METI efficiency labeling—creates asymmetric compliance burdens that filter subscale competitors.
For Market Incumbents: Build certification moats by accelerating NMPA laboratory partnerships and METI tier-jumping investments before cybersecurity mandates harden. Firmware engineering scarcity in Guangdong clusters threatens ecosystem-integrated positioning. Channel control through regional warranty network density anchors Southeast Asian shelf access against emerging Chinese cost engineers. For New Entrants and Emerging Players: Maharashtra and Karnataka urban centers present whitespace where government nutrition campaigns outpace dedicated low-sugar appliance penetration. Voltage-stabilized engineering for grid-unstable Indian metros offers the most penetrable entry vector. Direct-to-consumer launch through health-app partnerships bypasses SUPOR's mass-retail gatekeeping. For Investors and Strategic Acquirers: Patent-holding steam-separation specialists with METI/NMPA dual certification represent the optimal acquisition archetype for portfolio exposure to precision-health appliance convergence. Long-term viability hinges on IoT sensor convergence with glycemic-index databases creating subscription attach rates. Watch for MFDS timeline compression signals indicating South Korean market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Temperature Sensors | Captive supply of semiconductor-grade sensors reduces Taiwan-sourcing vulnerability for precision cookers. |
| Direct-to-Consumer Channel Launch | Seoul and Taipei smartphone-native buyers prefer app-managed workflows over hypermarket retail. |
| Dual Certification Investment | Simultaneous NMPA and METI compliance unlocks premium positioning in Chinese and Japanese metros. |
| Subscription Service Unbundling | Recurring recipe and glycemic-tracking revenue attaches to hardware purchases in connected segments. |
| Geographic Manufacturing Footprint Expansion | Localized voltage engineering for Indian and Vietnamese grids addresses whitespace penetration barriers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with appliance R&D directors, supply chain managers at Zhejiang manufacturing clusters, METI certification consultants, and South Korean health-app platform engineers; and secondary validation through SAMR GB standard filings, METI efficiency label registries, customs records for stainless steel component trade, and semiconductor import manifests. Bottom-up shipment estimates from Guangdong factory outputs triangulated against top-down household penetration models for Tokyo, Shanghai, and Seoul metropolitan zones.
Forecast inputs incorporated product type segmentation across multi-function, smart, electric, and induction categories; end-user calibration between home kitchens and health-focused consumers; and technology maturity gradients from fuzzy-logic controllers to automated glycemic estimation. CAGRs derived from replacement-cycle velocity in Japanese urban households, Chinese smart-home adoption curves, and Indian government nutrition campaign intensity. Nickel futures volatility and MFDS certification timeline data fed scenario-weighted projections across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ecosystem-integrated platform players or subsidy-heavy Indian market entrants would shift outcomes beyond modeled ranges. Cross-checking against NMPA batch-testing disclosure rates and METI tier-migration velocities is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Multi Cooker Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Culinary Torch Market
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Ice Cube Tray Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Commercial Bar Equipment Market