
 Teaseed Cake Market | 2026-2036
Teaseed Cake Market Size, Share, and Industry Trends Forecast 2026-2036
Teaseed Cake Market Outlook
Specialized oilseed processing technicians is redrawing competitive boundaries in teaseed cake production. Hunan Nutramax Inc. leverages its Hunan province base to anchor regional supply chains for camellia-derived feedstock. Xi'an Sgonek Biological Tech sustains R&D intensity in extraction protocols that preserve saponin content. GreenHerb Biological Tech dominates organic certification pathways, differentiating its portfolio from conventional processors.
Teaseed cake denotes the compressed residue remaining after mechanical or solvent extraction of oil from camellia seeds, typically containing residual saponins, proteins, and polysaccharides that render it suitable for animal feed formulations and organic fertilizer applications. The material serves as a protein supplement in aquaculture and livestock rations, particularly across subtropical farming systems where camellia cultivation clusters. Classic teaseed cake retains volume leadership due to established feed-milling infrastructure and lower unit economics, though organic teaseed cake commands premium positioning as regenerative agriculture protocols spread. Gluten-free and vegan variants occupy niche channels targeting specialty bakeries and catering services sensitive to allergen labeling requirements.
China's SAMR enforces GB standards for oilseed processing residues that dictate maximum aflatoxin thresholds and labeling disclosures, while Taiwan's central food regulator maintains parallel inspection regimes for cross-strait shipments. REACH compliance in Europe constrains saponin concentration limits for imported feed additives, redirecting some Asian volume toward domestic aquaculture applications. Stakeholders must monitor evolving saponin toxicity classifications and pivot formulation strategies before regulatory reclassifications disrupt established trade corridors.
Market Dynamics
China's updated GB standards for oilseed processing residues are tightening aflatoxin thresholds and labeling requirements, forcing processors to upgrade extraction infrastructure and redirect lower-grade output toward domestic aquaculture channels rather than export markets.
Growth Catalysts
- Regenerative agriculture protocols:European organic certification pathways are expanding premium positioning for saponin-rich teaseed cake in specialty livestock feed. Farmers in the Netherlands and Germany now specify organic cake in procurement tenders.
- Camellia cultivation expansion:Subtropical farming clusters in Hunan and Jiangxi provinces are scaling cold-press extraction capacity to meet aquaculture protein demand. Regional cooperatives are consolidating feedstock supply.
- REACH compliance adaptation:Asian processors are reformulating saponin concentrations to satisfy European feed additive thresholds, opening certified export corridors previously blocked by toxicity classification barriers.
Market Restraints
- Input cost volatility:Mechanical pressing equipment and solvent recovery systems face steel and energy price swings that compress processor margins during harvest season bottlenecks.
- Supply concentration risk:East Asian camellia feedstock dominates global volume, with Hunan province accounting for disproportionate extraction capacity that creates geographic vulnerability to climate disruption.
- Substitution threat:Soybean meal and rapeseed cake maintain entrenched positions in conventional feed-milling infrastructure, limiting teaseed cake penetration in price-sensitive livestock operations.
Strategic Opportunities
- Underpenetrated specialty bakery channel:Gluten-free and vegan variants targeting allergen-sensitive catering services in North American urban markets remain nascent with room for certified organic positioning.
- Emerging aquaculture application:Tilapia and shrimp farming operations in subtropical zones are testing saponin-enhanced feed formulations for parasite resistance, creating technical differentiation potential.
- Technology convergence:Cold-press extraction is merging with membrane filtration protocols to preserve protein integrity, enabling premium-grade output for high-value organic fertilizer markets.
Industry Challenges
- Specialized technician scarcity:Oilseed processing facilities require operators trained in solvent recovery and aflatoxin testing protocols that vocational programs in producing regions have not scaled to match capacity expansion.
- Certification timeline compression:Organic and REACH-compliant pathways demand 18-24 month validation cycles that misalign with seasonal harvest windows and working capital constraints.
- Legacy feed-milling integration:Established livestock operations run formulation software calibrated for soybean meal amino acid profiles, requiring technical support investment to recalibrate for teaseed cake protein-saponin ratios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teaseed Cake Market |
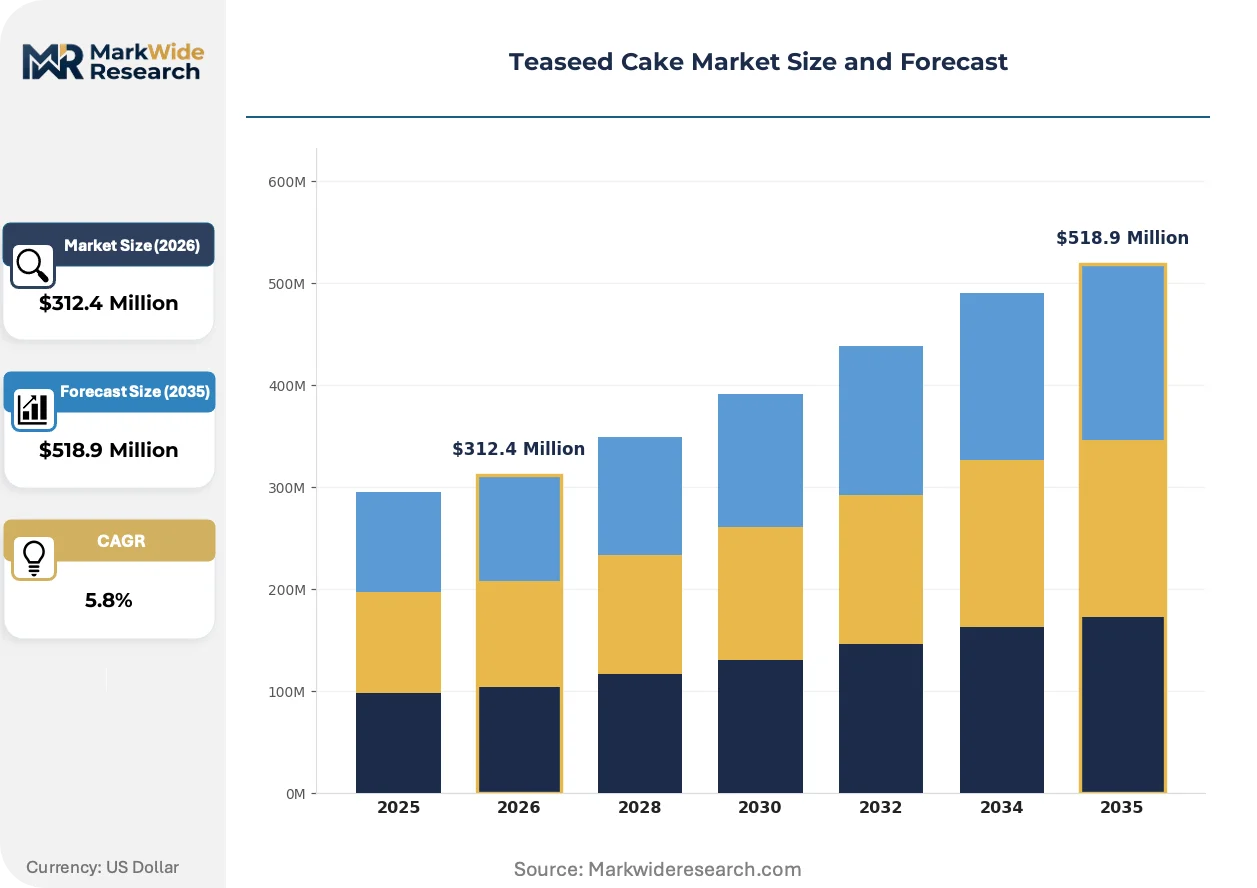
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Teaseed Cake, Gluten-Free Teaseed Cake, Vegan Teaseed Cake, Organic Teaseed Cake End User: Retail Consumers, Bakeries, Coffee Shops, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Food Stores, Food Service Packaging Type: Plastic Containers, Boxed Packaging, Eco-Friendly Wraps, Bulk Packaging |
| Companies Covered | Hunan Nutramax Inc., Xi’an Sgonek Biological Tech, GreenHerb Biological Tech, Naturalin Bio-Resources Co., GreenHerb Biotech, Anhui Huayin Camellia Oil Co., Ltd., Xian Pincredit Bio-Tech Co., Ltd., Taiwan Fu Kung Industrial, Gih Hwa Enterprise Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teaseed Cake Market Strategic Shifts
Extraction technology and certification protocols are converging to reshape competitive boundaries in teaseed cake processing. Market participants are racing to capture premium positioning through technical differentiation and compliance adaptation.
Cold-press extraction systems with integrated membrane filtration are miniaturizing. Mid-scale processors in Taiwan and Fujian province are adopting skid-mounted units that preserve heat-sensitive saponins previously degraded by solvent methods. This technology is miniaturizing capital requirements for organic certification, compressing the scale threshold for premium-grade output and enabling cooperative ownership models that bypass centralized extraction monopolies.
REACH saponin concentration limits are tightening enforcement across European feed additive imports. ECHA guidance documents issued in 2024 have reclassified certain saponin thresholds, forcing Asian exporters to reformulate or redirect volume toward domestic aquaculture applications. Taiwanese processors with existing EU registration dossiers are capturing displaced market share from competitors lacking pre-submitted toxicity data packages.
Certification-driven procurement is fragmenting buyer concentration in livestock feed channels. Large integrators in subtropical farming zones are unbundling organic and conventional teaseed cake into separate tender categories, displacing undifferentiated spot purchasing. This shift is most visible in China's Guangdong province, where provincial agricultural bureaus now mandate traceability documentation for subsidized feed programs.
Teaseed Cake Market Segmentation
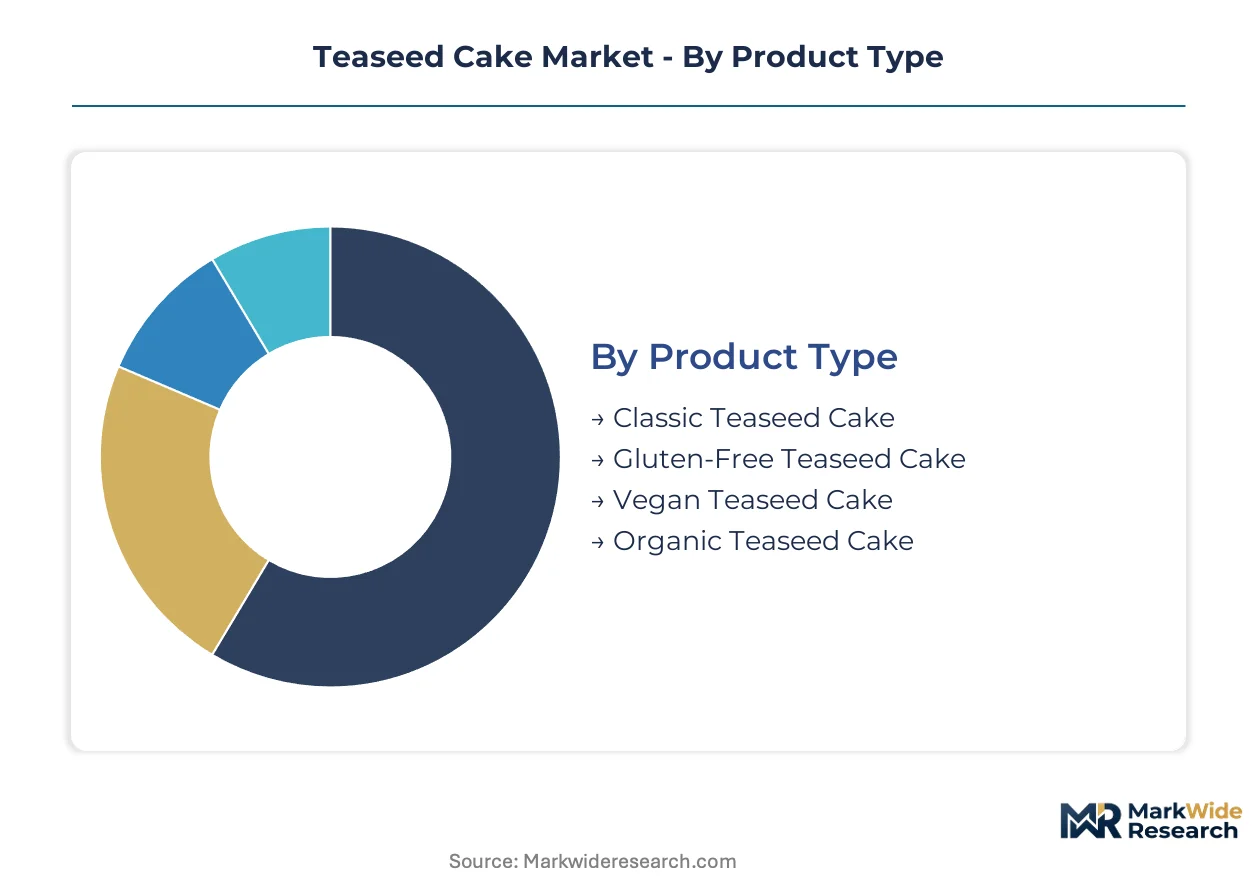
Teaseed cake processors segment their portfolios across four dimensions that determine pricing power and channel access. Product type and end-user targeting create the steepest margin differentials, while distribution and packaging configurations shape working capital intensity and geographic reach.
Product Type:
Margin pools concentrate in certified organic variants where regenerative agriculture protocols command procurement premiums, while classic formulations compete on feed-milling scale economics.
- Organic Teaseed Cake:Cold-press extraction preserves heat-sensitive saponins and proteins that satisfy European organic certification pathways. Dutch and German livestock integrators now specify organic cake in tender documentation, displacing conventional spot purchasing. Premium positioning reflects 18-24 month validation cycles and traceability infrastructure investments.
- Classic Teaseed Cake:Solvent-extracted residue retains volume leadership through established aquaculture feed infrastructure in subtropical farming systems. Hunan and Jiangxi province processors anchor regional supply chains with lower unit economics that compete against soybean meal and rapeseed cake in price-sensitive livestock operations.
- Gluten-Free Teaseed Cake:Specialty bakery channel in North American urban markets targets allergen-sensitive catering services with niche positioning.
- Vegan Teaseed Cake:Plant-based certification opens procurement pathways for institutional food service operators with dietary restriction protocols.
Classic teaseed cake holds installed capacity. Organic teaseed cake is rotating up the share rankings.
End User:
Application concentration tilts toward food service procurement where volume contracts and technical support requirements filter out undifferentiated suppliers.
- Catering Services:Large-scale event operators and institutional food service networks specify certified organic and allergen-free variants in procurement tenders. Technical support investment for formulation recalibration separates qualified suppliers from commodity traders.
- Bakeries:Specialty and artisanal baking operations in North American urban markets test gluten-free and vegan teaseed cake for texture and binding properties. Product development cycles align with seasonal demand peaks that strain working capital for smaller processors.
- Retail Consumers:Health-conscious households in East Asian markets drive organic variant demand through direct-to-consumer channels.
- Coffee Shops:Limited-service beverage and snack operators experiment with teaseed cake as a novel ingredient in premium baked goods.
Catering services concentrate procurement volume. Bakeries are climbing the fastest as specialty channel penetration deepens.
Distribution Channel:
Channel configuration determines margin capture, with direct food service relationships yielding superior returns compared to retail intermediation.
- Food Service:Direct supply relationships with large integrators and institutional operators bypass distributor markups while locking in volume commitments. Technical field support for feed formulation recalibration creates switching costs that stabilize supplier positions.
- Specialty Food Stores:Curated retail environments in urban markets premium-position organic and allergen-free variants for health-conscious consumers. Shelf placement fees and promotional spending compress net margins relative to direct channels.
- Online Retail:E-commerce platforms enable direct-to-consumer access for certified organic products with traceability documentation.
- Supermarkets:Mass retail distribution requires scale economies and promotional investment that favor established processors with cold-chain infrastructure.
Food service commands margin premiums. Online retail is gaining share fastest as digital procurement platforms mature.
Packaging Type:
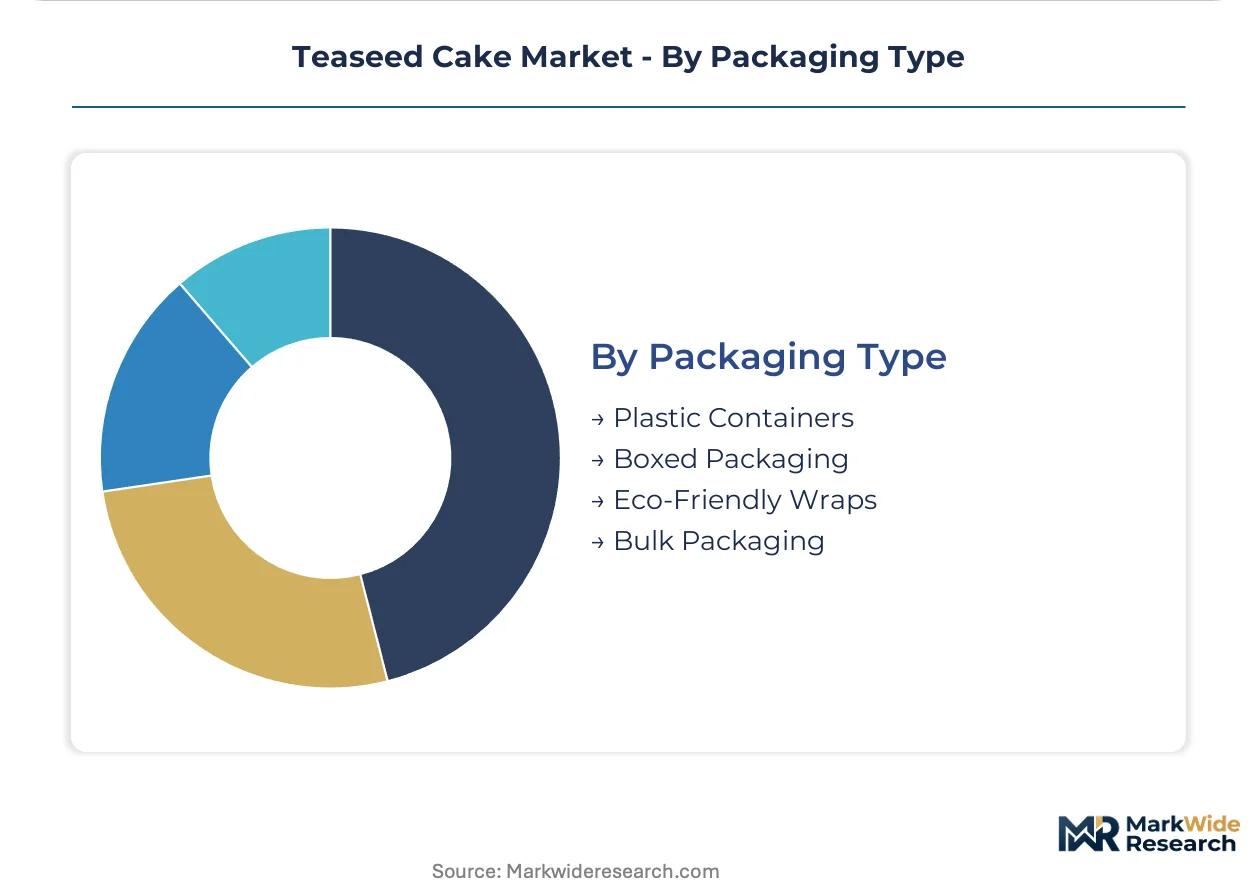
Packaging selection reflects customer scale and sustainability positioning, with bulk configurations dominating feed-milling applications.
- Bulk Packaging:Industrial totes and flexible intermediate bulk containers serve aquaculture and livestock feed-milling operations in subtropical farming zones. Lower per-unit packaging costs align with price-sensitive commodity procurement.
- Eco-Friendly Wraps:Compostable and recyclable materials satisfy European organic certification requirements and corporate sustainability mandates. Premium positioning in specialty retail channels offsets higher unit costs.
- Plastic Containers:Rigid packaging preserves product integrity for retail distribution with extended shelf-life requirements.
- Boxed Packaging:Corrugated configurations balance protection and cost for mid-scale food service and specialty retail shipments.
Bulk packaging anchors feed-milling supply. Eco-friendly wraps are expanding most quickly as certification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in European organic feed channels while Chinese processors compete on volume scale and extraction throughput. Taiwan's technical compliance infrastructure captures displaced EU-bound volumes from mainland competitors facing REACH reclassification delays. Subtropical cultivation clusters in East Asia supply raw feedstock, though regulatory divergence is fragmenting trade corridors.
China
Camellia cultivation expansion in Hunan and Jiangxi provinces drives feedstock supply growth for aquaculture protein demand. SAMR enforces updated GB standards for oilseed processing residues with tightened aflatoxin thresholds and mandatory labeling disclosures. Cold-press extraction clusters in Changsha are scaling capacity to meet domestic livestock feed procurement while redirecting lower-grade output from export channels.
Taiwan
Cross-strait shipment inspection regimes maintain parallel quality benchmarks that filter substandard consignments. The central food regulator operates pre-submitted toxicity data packages that accelerate EU registration dossier approvals. Kaohsiung-based processors with existing REACH compliance capture market share from mainland competitors lacking European feed additive certifications.
Germany
Livestock integrators in Lower Saxony and Bavaria now specify organic teaseed cake in procurement tenders with regenerative agriculture protocols. ECHA guidance documents issued in 2024 reclassified certain saponin thresholds, forcing reformulation of imported feed additives. Hamburg feed-milling operations are recalibrating formulation software to accommodate protein-saponin ratios distinct from soybean meal profiles.
Netherlands
Dutch organic certification pathways expand premium positioning for saponin-rich variants in specialty livestock feed channels. Provincial agricultural bureaus mandate traceability documentation for subsidized feed programs that unbundle organic and conventional categories. Rotterdam distribution hubs consolidate EU-bound volumes from Taiwanese processors with pre-cleared toxicity classifications.
United States
Specialty bakery channels in North American urban markets test gluten-free and vegan variants for allergen-sensitive catering services. FDA labeling requirements for oilseed-derived ingredients create compliance barriers that favor established importers with GRAS documentation. Pacific Northwest food service distributors experiment with direct procurement relationships that bypass traditional commodity trading structures.
Teaseed Cake Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with cold-press extraction specialists commanding premium positioning against solvent-based volume processors. The vendor base stratifies across three tiers: integrated camellia oil processors with captive feedstock supply, standalone extraction specialists with certification infrastructure, and regional commodity traders with undifferentiated spot-market positioning. Dominant competitive moves include backward integration into cultivation cooperatives and technology licensing agreements for membrane filtration protocols that preserve heat-sensitive saponins.
Within the integrated processor tier, Hunan Nutramax Inc. and Anhui Huayin Camellia Oil Co., Ltd. anchor regional supply chains through provincial cultivation bases. Xi'an Sgonek Biological Tech occupies a position among extraction specialists with R&D intensity in protocol development. GreenHerb Biological Tech exemplifies the certification-focused archetype with organic pathway dominance that differentiates from conventional processors.
| Leading Market Players |
|---|
| Hunan Nutramax Inc. |
| Xi'an Sgonek Biological Tech |
| GreenHerb Biological Tech |
| Naturalin Bio-Resources Co. |
| GreenHerb Biotech |
| Anhui Huayin Camellia Oil Co., Ltd. |
| Xian Pincredit Bio-Tech Co., Ltd. |
| Taiwan Fu Kung Industrial |
| Gih Hwa Enterprise Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day harvest-to-extraction lead times for camellia seed feedstock concentrate pricing power among Hunan province processors with cold-press infrastructure, while SAMR compliance timelines force working capital commitments that smaller solvent-based operators cannot sustain. This inventory compression at origin points locks in premium capture for certified organic tiers against commodity spot volatility.
Pricing Analysis
The configured-to-order premium for REACH-compliant organic teaseed cake runs 40-60% above classic solvent-extracted grades, with pricing stratifying across certification grade, volume scale, and geographic delivery cost. Cost compression in conventional tiers is intensifying because soybean meal substitution pressure from livestock integrators in Guangdong province limits spot-market liquidity. Small-scale aquaculture cooperatives in Jiangxi exhibit highest price sensitivity, while Dutch organic livestock integrators show lowest elasticity due to regenerative agriculture procurement mandates.
Supply Chain Analysis
Inventory accumulation peaks during October-November harvest windows, with feedstock supply drawing from China, Taiwan, and Vietnam cultivation clusters. Raw material dependencies center on camellia seed availability, mechanical pressing equipment, and solvent recovery chemicals. Single-source vulnerability concentrates in Hunan province extraction capacity, which feeds from domestic aquaculture demand and European organic feed channels. Distribution runs through regional feed-milling cooperatives in subtropical farming zones and Rotterdam consolidation hubs for EU-bound organic volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
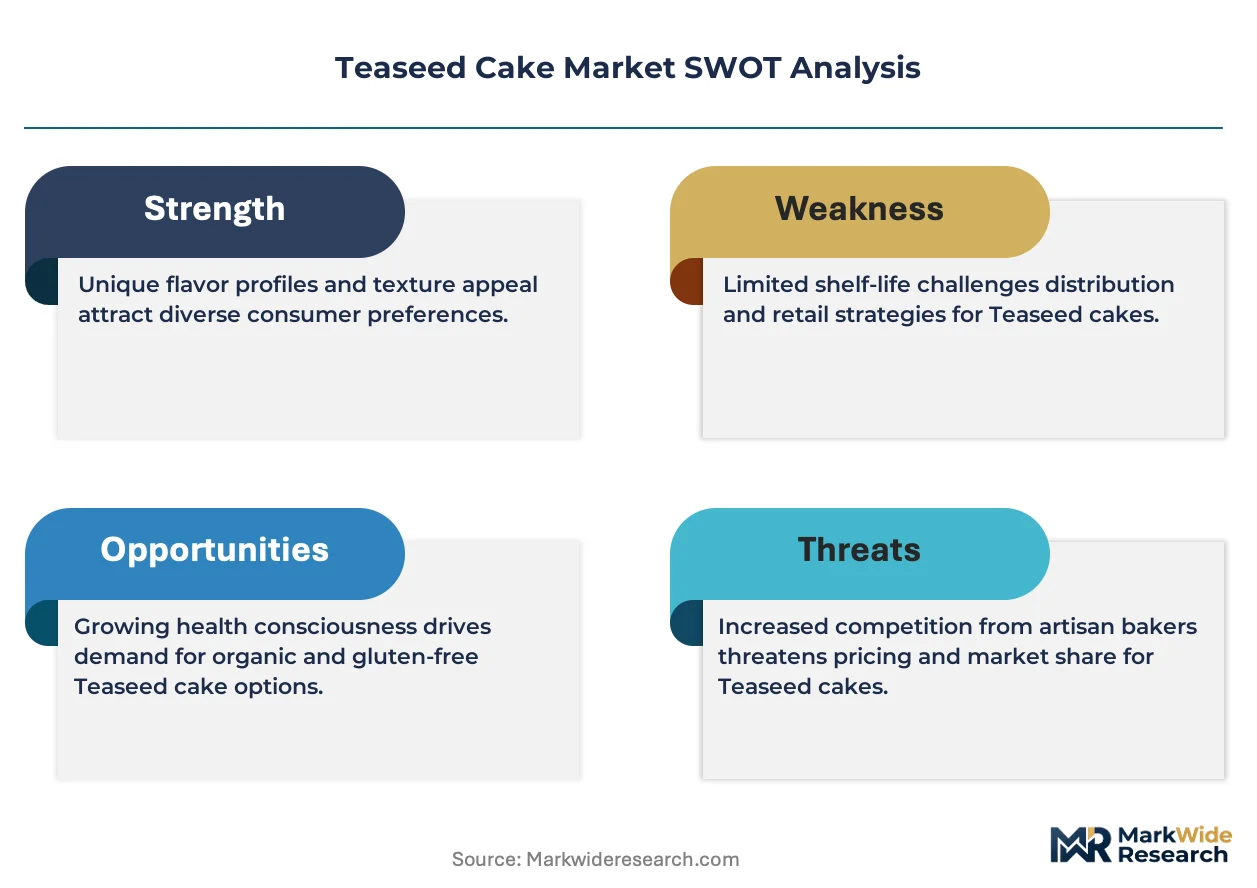
Specialized oilseed processing technicians trained in aflatoxin testing and solvent recovery protocols remain scarce relative to planned capacity expansion across Hunan and Jiangxi provinces, creating bottlenecks that constrain quality-grade output and certification timelines.
For Market Incumbents: Fortify upstream control over cultivation cooperatives in Changsha and Nanchang clusters to secure feedstock priority during harvest compression periods. Invest in membrane filtration R&D to preserve saponin integrity for REACH compliance, defending against Taiwanese processors with pre-cleared EU dossiers. Certification infrastructure expansion represents the critical lever for margin protection against commodity substitution. For New Entrants and Emerging Players: Differentiate on cold-press organic certification for North American specialty bakery channels, where gluten-free and vegan positioning remains underpenetrated relative to aquaculture saturation. Target Pacific Northwest food service distributors with direct procurement relationships that bypass legacy commodity trading structures. Lead with allergen-free technical documentation and formulation support services. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated camellia oil processors seeking to monetize captive teaseed cake residues as standalone feed divisions. Long-term viability hinges on organic certification pathway completion and European feed additive registration status. Monitor ECHA saponin threshold guidance revisions as the primary inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Cooperatives | Hunan and Jiangxi provincial clusters secure feedstock priority during seasonal harvest windows. |
| Membrane Filtration Technology Licensing | Taiwanese processors with EU registration capture share from mainland competitors lacking REACH compliance. |
| Organic Certification Pathway Investment | Eighteen-to-twenty-four month validation cycles align with Dutch and German regenerative agriculture procurement. |
| Direct Food Service Distribution Relationships | Pacific Northwest distributors bypass commodity trading structures for specialty bakery channel access. |
| Aquaculture Feed Formulation Partnerships | Tilapia and shrimp farming operations in subtropical zones test saponin-enhanced parasite resistance protocols. |
Study Parameters
Desk research of customs trade databases, SAMR regulatory filings, and ECHA guidance documents preceded structured interviews with oilseed processing facility managers, aquaculture feed formulators, European livestock procurement directors, and organic certification auditors. Primary fieldwork with Hunan province extraction operators and Taiwanese REACH compliance specialists combined with secondary validation from agricultural cooperative records. Bottom-up volume estimates triangulated against top-down market sizing across product type and end-user segments.
Variance decomposition across the projection horizon isolates volume, price, and mix effects by segmentation dimension including product grade tier, end-use application, distribution channel configuration, and regional regulatory cluster. CAGRs derive from logistic adoption curves fitted to historical penetration patterns and forward-looking procurement tender documentation. Industry-specific forecast inputs incorporate camellia cultivation yield projections and European organic livestock feed specification trends.
Material uncertainties — regulatory reclassification of saponin toxicity thresholds, climate disruption impacts on Hunan province harvests, and feed-milling software recalibration timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread and Baked Food Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Bakery Emulsions Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Frozen Bakery Products Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Fortified Bakery Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Low-Calorie Pie Market
Bakery Products
Ezekiel Bread Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Pizza Crust Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Healthy Biscuits Market
Bakery Products
Bakery Premixes Market