
 Pizza Crust Mix Market | 2026-2036
Pizza Crust Mix Market Size, Share, and Industry Trends Forecast 2026-2036
Pizza Crust Mix Market Analytics
Millwright and industrial baking technician shortages across North America is reorganizing how manufacturers scale output, forcing capital-light automation strategies. King Arthur Flour leverages its employee-owned structure to sustain above-average retention in milling operations. ADM competes through backward integration into wheat protein isolates, controlling input costs for gluten-free formulations. Bob's Red Mill anchors its position through stone-ground specialization, occupying the premium heritage segment.
Pizza crust mix comprises pre-formulated dry blends of wheat or alternative flours, leavening agents, and conditioning salts requiring hydration and fermentation before baking, typically specified by protein content between 10-14% for chew development and ash levels below 0.55% for color control. The blend serves commercial and home bakers seeking consistent dough performance without ingredient sourcing complexity. Gluten-free formulations now command disproportionate shelf space growth as celiac diagnoses and flexitarian diets expand the addressable base, though traditional wheat-based mixes still generate the largest absolute volume. Food service distribution channels are capturing margin pools through direct-store-delivery relationships with independent pizzerias, while online retail segments fastest from subscription and direct-to-consumer specialty brands.
The FDA enforces gluten-free labeling thresholds at 20 ppm, compelling reformulation investments and third-party certification costs that filter smaller blenders from retail distribution. The USDA's organic certification program and FSMA preventive controls rule jointly shape ingredient traceability requirements and facility audit protocols for interstate commerce. Stakeholders must monitor emerging state-level clean-label disclosure laws and assess whether European-style fermented flour designations will migrate into North American positioning strategies.
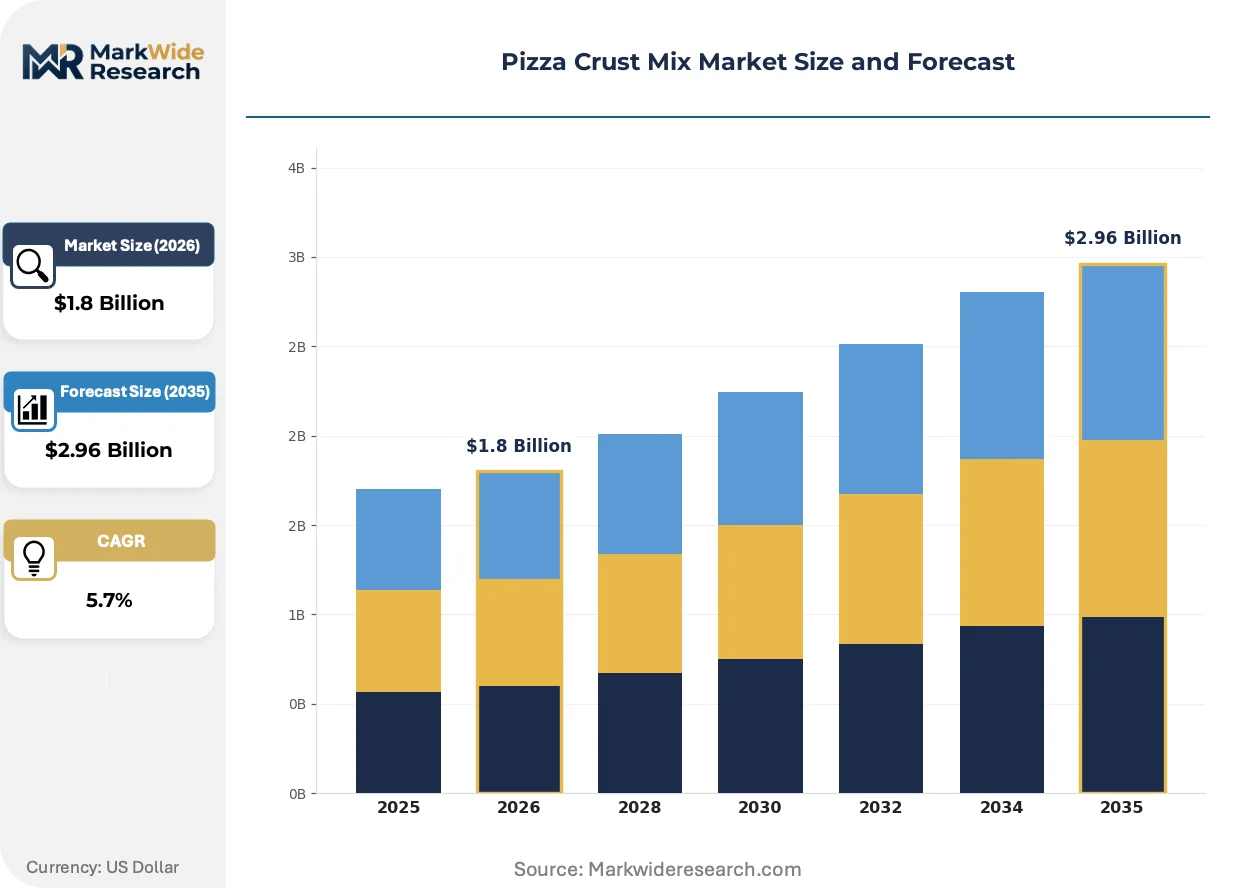
Market Dynamics
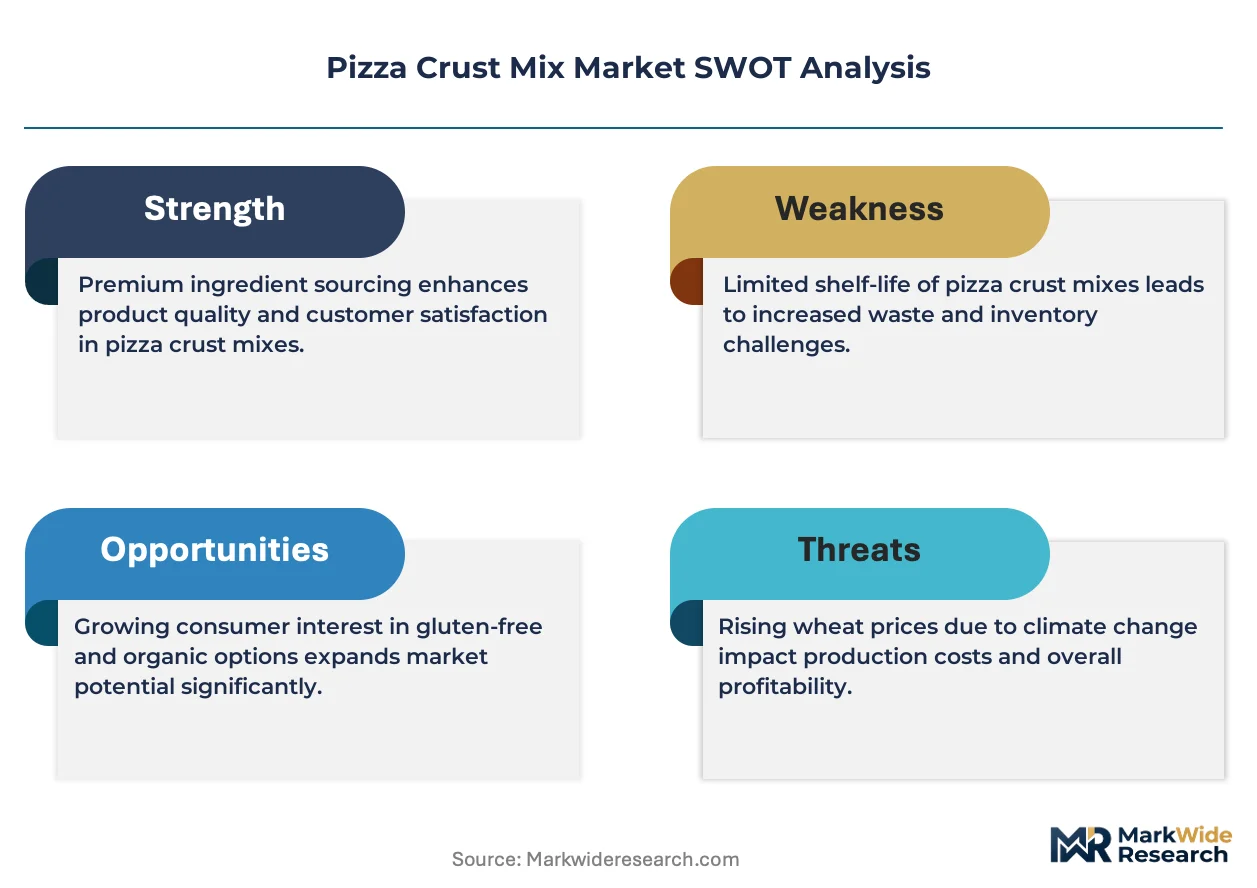
Quick-service restaurants expanding private-label pizza programs are compressing branded mix margins while FDA gluten-free labeling standards at 20 ppm force reformulation investments that filter smaller blenders from retail distribution.
Growth Catalysts
- Flexitarian diet expansion:Celiac diagnoses and wheat-avoidance behaviors widen the addressable base for alternative-flour formulations beyond traditional wheat-based blends.
- Direct-store-delivery consolidation:Food service distributors capturing margin pools through exclusive relationships with independent pizzerias in Italy's artisan bakery supply chain.
- FSMA preventive controls:The rule's ingredient traceability requirements favor blenders with established facility audit protocols for interstate commerce.
Market Restraints
- Protein isolate input volatility:Wheat gluten and alternative protein costs fluctuate with commodity grain markets, squeezing margin on premium-positioned gluten-free lines.
- Third-party certification burden:Gluten-free labeling thresholds impose testing costs that disproportionately burden sub-scale blenders lacking captive laboratory capacity.
- Millwright labor scarcity:Industrial baking technician shortages across production geographies limit output scaling regardless of capital availability.
Strategic Opportunities
- Subscription channel penetration:Direct-to-consumer specialty brands bypass retail slotting fees through online retail segments.
- Stone-ground heritage positioning:Premium milling differentiation commands shelf-space premiums in specialty grocery channels.
- European fermented flour designations:Clean-label disclosure laws in select states may migrate toward EU-style labeling that rewards extended fermentation protocols.
Industry Challenges
- Automation capex requirements:Capital-light strategies must reconcile with precision dosing and conditioning salt dispersion tolerances.
- Employee-owned retention models:Competing for operational talent against structures that sustain above-average milling operation tenure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pizza Crust Mix Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Whole Wheat, Traditional, Cauliflower Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Households, Restaurants, Catering Services, Bakeries Packaging Type: Bags, Boxes, Pouches, Bulk Containers |
| Companies Covered | Bob’s Red Mill, King Arthur Flour, Hodgson Mill, Martha White, Namaste Foods, ADM, Pillsbury, Krusteaz, Simple Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pizza Crust Mix Market Evolving Landscape
Formulation science and channel economics are diverging the competitive landscape into precision-automated commodity supply and artisan-positioned specialty blends.
Sourdough starter integration into dry mix formats is bifurcating the refrigerated dough aisle. Artisan pizzerias and home bakers seeking fermented flavor profiles without multi-day prep are driving adoption. The technology is compressing shelf-stable mix margins while enabling premium pricing for live-culture formulations.
REACH chemical registration requirements in Europe are reshaping conditioning salt and leavening agent sourcing for exporters. Industrial blenders reformulating for cross-border compliance face ingredient substitution costs. Gluten-free lines bound for EU markets absorb disproportionate regulatory overhead.
Independent pizzerias are consolidating procurement through cooperative buying groups that displace traditional broadline distributors. These aggregators negotiate direct mill relationships, compressing intermediary margins. The pattern concentrates in metropolitan clusters where operator density supports collective volume commitments.
Pizza Crust Mix Market Segmentation
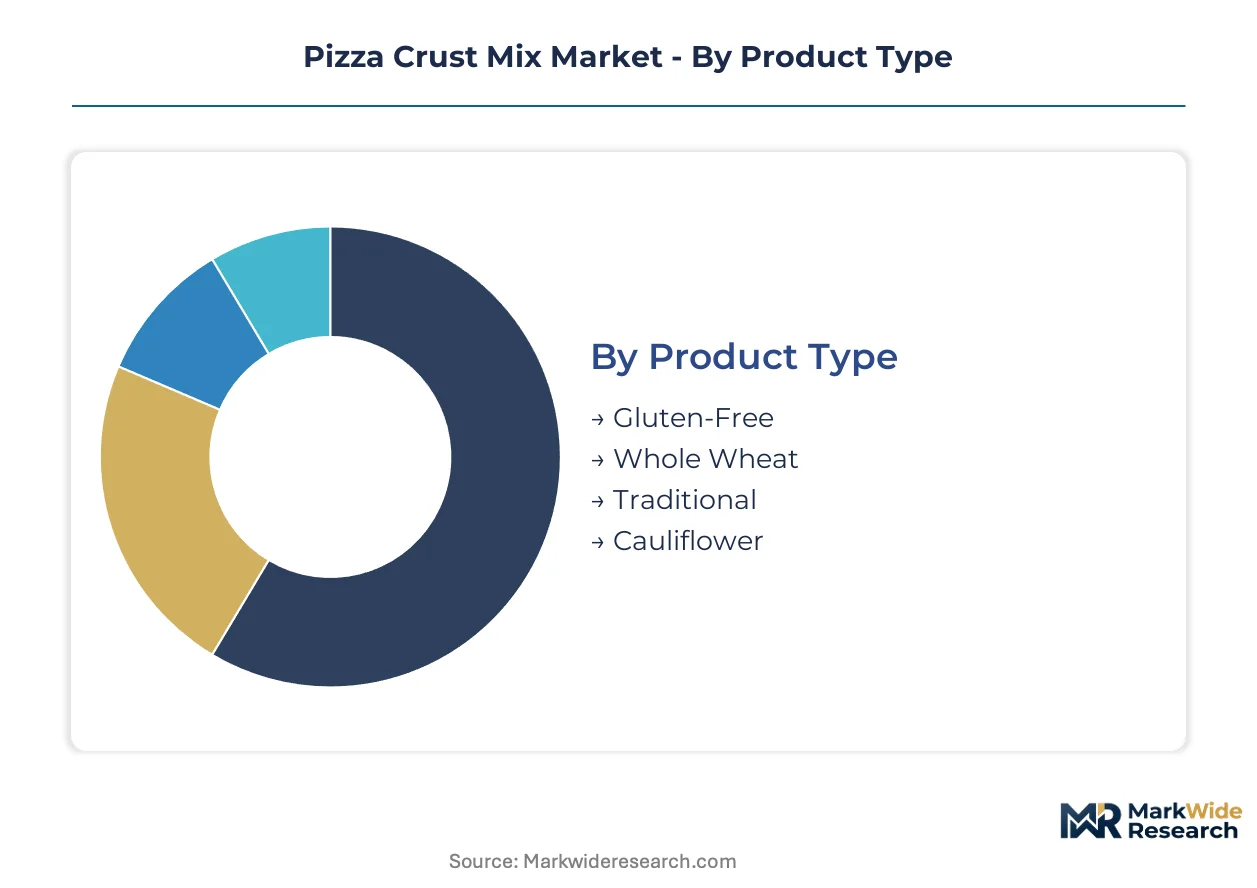
Segmentation in pizza crust mix reveals how FDA gluten-free thresholds and FSMA traceability rules concentrate margin across formulation types and channel structures. Manufacturers align R&D and certification investments against segments where regulatory compliance creates defendable positioning.
Product Type:
FDA's 20 ppm gluten-free labeling standard and USDA organic certification requirements impose divergent formulation costs and third-party testing burdens across product lines.
- Gluten-Free:Formulations rely on rice flour, tapioca starch, and xanthan gum binding systems to achieve dough elasticity without wheat protein. Demand concentrates in US households managing celiac diagnoses, where third-party certification commands shelf-space premiums despite per-unit production costs.
- Traditional:Wheat-based blends specify 10-14% protein content and sub-0.55% ash levels for consistent chew and color control. Italian artisan pizzerias in Naples and Rome anchor procurement volume, though North American quick-service restaurants are expanding private-label programs that compress branded margins.
- Whole Wheat:Higher bran content formulations target health-positioned retail shelves with elevated fiber claims and darker crust aesthetics.
- Cauliflower:Vegetable-base alternatives occupy flexitarian diet segments with lower carbohydrate positioning and refrigerated distribution requirements.
Traditional mixes handle the majority of throughput; gluten-free is expanding most quickly on share as diagnostic rates and wheat-avoidance behaviors widen the addressable base.
Distribution Channel:
Channel economics separate capital-light direct-to-consumer entrants from food service distributors investing in exclusive direct-store-delivery infrastructure.
- Food Service:Broadline and specialty distributors capture margin pools through exclusive relationships with independent pizzerias, cooperative buying groups, and quick-service restaurant chains. Consolidated procurement in metropolitan clusters supports collective volume commitments that displace traditional intermediaries.
- Online Retail:Subscription models and direct-to-consumer specialty brands bypass retail slotting fees, with fastest expansion in gluten-free and heritage-positioned stone-ground lines where brand story drives repeat purchase.
- Supermarkets:Mass retail placement demands scale certification and promotional funding that filters sub-scale blenders.
- Specialty Stores:Premium channel placement rewards organic certification and extended fermentation protocols with shelf-space premiums.
Food service channels handle the majority of throughput; online retail is climbing the fastest on share as subscription economics reduce customer acquisition costs for niche formulations.
End User:
User sophistication determines whether procurement prioritizes consistency and labor reduction or ingredient provenance and fermentation control.
- Restaurants:Independent pizzerias and quick-service chains specify protein content and conditioning salt dispersion for throughput reliability, with cooperative buying groups consolidating procurement to negotiate direct mill relationships.
- Households:Home bakers select convenience-oriented pouches and smaller-format bags where sourdough starter integration commands premium pricing for live-culture formulations without multi-day prep.
- Catering Services:Volume operators prioritize bulk packaging and hydration tolerance across variable equipment conditions.
- Bakeries:Artisan producers demand stone-ground heritage positioning and extended fermentation designations that align with clean-label disclosure trends.
Restaurants handle the majority of throughput; households are gaining share fastest as sourdough-integrated dry mixes compress refrigerated dough aisle economics.
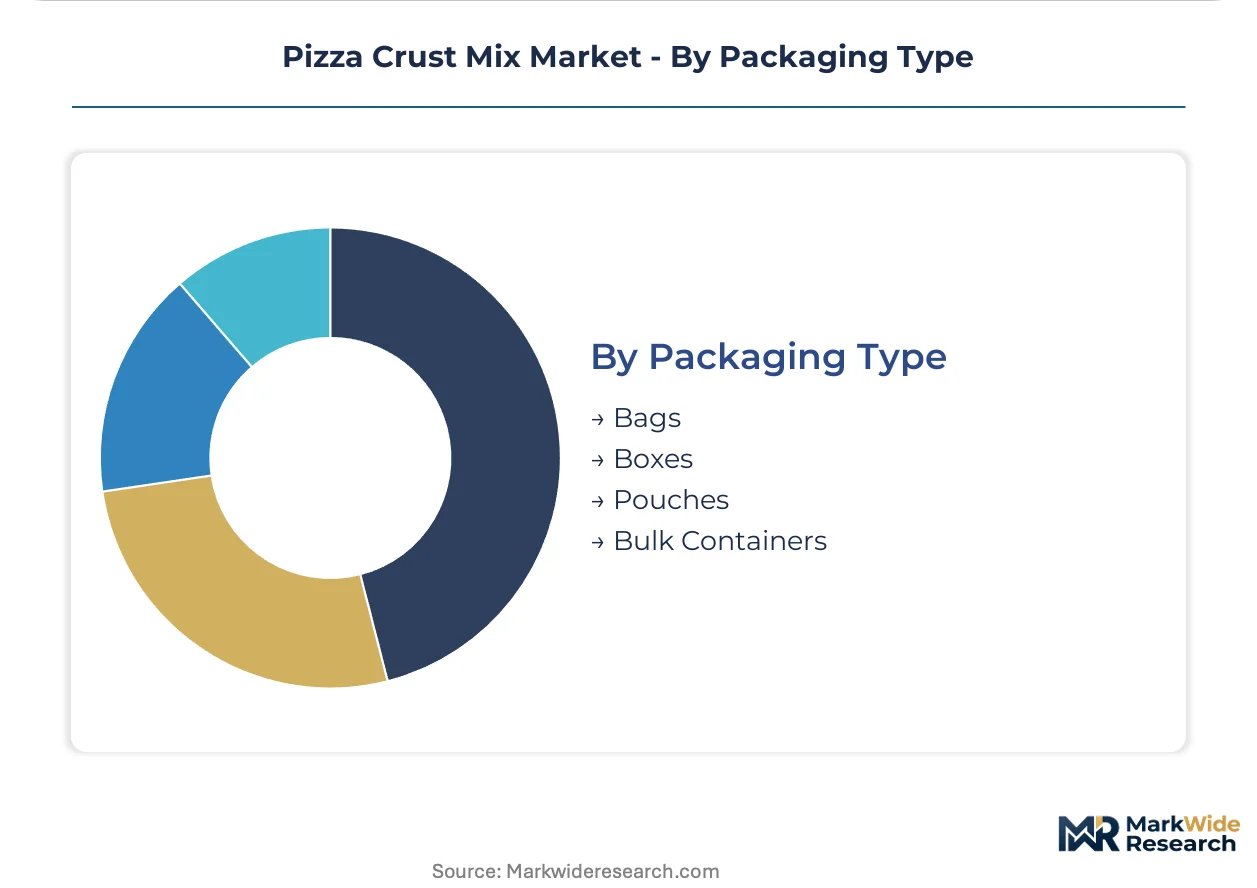
Packaging Type:
Packaging format aligns with channel handling requirements and end-user batch size, from single-serve convenience to food service bulk.
- Pouches:Flexible laminate structures dominate direct-to-consumer and specialty retail, where resealability and portion control support subscription economics and premium positioning.
- Bulk Containers:Food service and industrial bakery procurement favors tote and drum formats that minimize per-unit handling cost and align with FSMA lot traceability requirements for interstate commerce.
- Bags:Multi-wall paper and poly structures serve mainstream retail with established shelf presence and commodity price points.
- Boxes:Rigid packaging protects premium formulations in gift and specialty channels where presentation drives purchase.
Bulk containers handle the majority of throughput; pouches are gaining share fastest as direct-to-consumer subscription models reshape channel economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's gluten-free labeling standards at 20 ppm anchor the United States as the dominant geography, with regulatory compliance costs filtering smaller blenders from retail distribution and reshaping formulation investments across North American supply chains.
United States
Independent pizzerias in metropolitan clusters consolidate procurement through cooperative buying groups that negotiate direct mill relationships. The FDA's updated gluten-free thresholds compel third-party certification investments that disproportionately burden sub-scale blenders. King Arthur Flour leverages its employee-owned structure to sustain above-average retention in milling operations across Vermont and the Northeast.
Italy
Artisan pizzerias in Naples and Rome anchor procurement volume for traditional wheat-based blends specifying 10-14% protein content. The EU's REACH chemical registration requirements reshape conditioning salt sourcing for exporters bound for cross-border compliance. Emilia-Romagna's heritage milling clusters supply stone-ground specialization to premium bakery supply chains.
Germany
Industrial bakeries demand precision-automated commodity supply with FSMA-aligned traceability for interstate commerce into North American markets. ECHA's chemical safety protocols influence leavening agent formulation substitutions. Bavaria's milling infrastructure concentrates gluten-free line investments for EU export qualification.
Canada
Health Canada's food labeling regulations align with FDA thresholds, enabling streamlined cross-border formulation strategies for North American distribution. The CFIA's preventive control requirements favor blenders with established facility audit protocols. Ontario's food manufacturing corridor hosts specialty blenders targeting subscription channel penetration.
United Kingdom
Clean-label disclosure trends drive demand for extended fermentation protocols in specialty retail channels. The FSA's allergen labeling guidance shapes gluten-free positioning strategies. London's food service distributors capture margin pools through exclusive relationships with independent pizzeria operators.
Pizza Crust Mix Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the pizza crust mix landscape. The vendor base fragments between precision-automated commodity suppliers and heritage-positioned specialty blenders. Three archetypes dominate: employee-owned mills with retention advantages, backward-integrated agribusinesses controlling input costs, and direct-to-consumer subscription specialists bypassing retail slotting fees. Competitive moves concentrate on M&A for gluten-free certification capabilities and strategic partnerships with food service distributors for direct-store-delivery infrastructure.
Among heritage-positioned specialists, Bob's Red Mill anchors the premium stone-ground segment through employee-owned operational structure. King Arthur Flour exemplifies the retention-driven archetype with above-average milling operation tenure. ADM represents backward-integrated scale, controlling wheat protein isolate inputs for gluten-free formulation cost management.
| Leading Market Players |
|---|
| Bob's Red Mill |
| King Arthur Flour |
| Hodgson Mill |
| Martha White |
| Namaste Foods |
| ADM |
| Pillsbury |
| Krusteaz |
| Simple Mills |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between wheat protein suppliers and gluten-free blenders lock in both input access and cost visibility across volatile commodity cycles. These contracts insulate larger manufacturers from spot-market protein isolate fluctuations while smaller competitors absorb margin compression from unhedged exposure to FDA-mandated reformulation cycles.
Pricing Analysis
North American shelf prices for gluten-free formulations command substantial premiums over traditional wheat-based equivalents, driven by third-party certification costs and captive laboratory investments. Three-tier pricing structure across premium, standard, and economy levels separates stone-ground heritage positioning from commodity blends and private-label food service supply. Pricing pressure stems from quick-service restaurant chains expanding direct mill relationships that bypass branded mix intermediaries. Independent pizzerias show highest price sensitivity due to cooperative buying group consolidation, while artisan bakeries absorb premiums for provenance-verified ingredients.
Supply Chain Analysis
Inbound logistics costs from Emilia-Romagna milling clusters to North American distribution centers have tightened margins on European stone-ground imports amid container availability constraints on Mediterranean trade lanes. Supply concentrates in Italy's artisan bakery corridor, the US Great Plains wheat belt, and Canadian prairie milling infrastructure. Raw material dependencies center on hard red winter wheat, rice flour for gluten-free binding systems, and xanthan gum stabilizers. Single-source vulnerability in wheat protein isolate supply from backward-integrated agribusinesses threatens formulation cost stability. Distribution runs through food service broadline networks, direct-store-delivery relationships, and subscription-based direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial baking technician scarcity across production geographies constrains output scaling regardless of capital deployment, creating defendable positioning for operators with established training pipelines and retention infrastructure.
For Market Incumbents: Secure gluten-free certification capabilities through laboratory capacity expansion or strategic certification body partnerships before FDA enforcement intensifies. Defend margin pools by locking exclusive direct-store-delivery relationships with cooperative buying groups in metropolitan pizzeria clusters, preventing disintermediation by direct mill procurement. For New Entrants and Emerging Players: Differentiate on sourdough starter integration and live-culture fermentation protocols that command subscription pricing in household segments. Target online retail channels where brand storytelling bypasses retail slotting fees and slotting cost barriers filter incumbent dominance. Pursue heritage milling narratives anchored to specific geographic clusters with verifiable provenance claims. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription specialists with established gluten-free certification and retention metrics above category averages. Five-to-ten year viability favors blenders with backward-integrated protein isolate supply or employee-owned structures sustaining above-average milling tenure. Monitor FDA gluten-free labeling enforcement intensity as inflection signal for certification-capability valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Gluten-Free Certification Investment | FDA's 20 ppm threshold filters sub-scale competitors from retail distribution channels. |
| Direct-Store-Delivery Infrastructure | Exclusive relationships with independent pizzerias capture margin pools from broadline displacement. |
| Employee-Owned Structure Conversion | King Arthur Flour's retention model sustains above-average milling operation tenure against labor scarcity. |
| Backward Integration into Protein Isolates | ADM's wheat protein control insulates gluten-free formulation costs from commodity volatility. |
| Subscription Channel Penetration | Direct-to-consumer models bypass retail slotting fees in fastest-expanding online retail segment. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with milling operation managers, food service procurement directors, gluten-free certification laboratory heads, and artisan pizzeria operators; and secondary validation against FDA regulatory filings, USDA organic certification databases, FSMA facility audit records, and customs trade data on wheat protein isolate flows. Bottom-up volume estimates from segment-level production capacity triangulated against top-down category expenditure patterns.
Across the projection horizon, the analytical framework modeled formulation type segmentation by certification burden, distribution channel economics by margin capture structure, end-user sophistication by labor-reduction versus provenance priorities, and packaging format by subscription versus bulk handling requirements. CAGRs were derived from trend extrapolation of diagnostic rate expansion, flexitarian diet adoption curves, and channel shift velocities. Industry-specific inputs included millwright labor availability indices and gluten-free shelf-space allocation trends.
Decision-makers should treat outputs as directional under assumptions of sustained FDA enforcement intensity and stable commodity grain price regimes; material deviation would warrant model refresh. Forecasts embed assumptions about celiac diagnosis rates, quick-service restaurant private-label expansion velocity, and European REACH compliance migration patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Organic Bakery Products Market
Bakery Products
Lentil Bread Market
Bakery Products
Vegan Donuts Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Pizza Crust Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Gluten-Free Pizza Crust Market
Bakery Products
Bread and Baked Food Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
Global Cake Mix Market
Bakery Products
No-Fat Cake Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Banana Bread Market