
 Vegan Baking Mix Market | 2026-2036
Vegan Baking Mix Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Baking Mix Market Analytics
Aftermarket recipe customization revenue is narrowing as consumers shift toward ready-to-use solutions. King Arthur Baking leverages its heritage milling expertise to sustain premium positioning in specialty flours. Simple Mills anchors its portfolio through grain-free formulations that command shelf space in natural channels. Miss Jones Baking differentiates through organic certification and transparent sourcing claims that resonate with label-conscious buyers.
Vegan baking mix denotes a pre-formulated dry blend of plant-derived flours, leavening agents, and binding substitutes designed to produce baked goods without eggs, dairy, or honey, typically requiring only the addition of water or oil. These formulations rely on enzymatic or chemically-raised leavening systems and hydrocolloid stabilizers to replicate structural properties lost from omitted animal ingredients. Brownie mix and cookie mix occupy the deepest margin pools due to repeat purchase frequency and gifting occasions, while chickpea flour formulations represent the fastest-growing ingredient trajectory as protein-forward positioning gains traction among athletic and diabetic consumer segments. Pancake mix remains the most mature category with established breakfast rituals limiting premiumization headroom.
The USDA Organic seal and FDA food labeling requirements shape permissible health claims and ingredient disclosure depth for domestic manufacturers, while the EU Green Deal's Farm to Fork strategy pressures import-dependent brands to document sustainable sourcing across oat and almond supply chains. Stakeholders must monitor evolving positions on precision-fermented egg replacers, as regulatory classification of these novel ingredients will determine whether they qualify for clean-label positioning or trigger GMO-adjacent scrutiny.
Market Dynamics
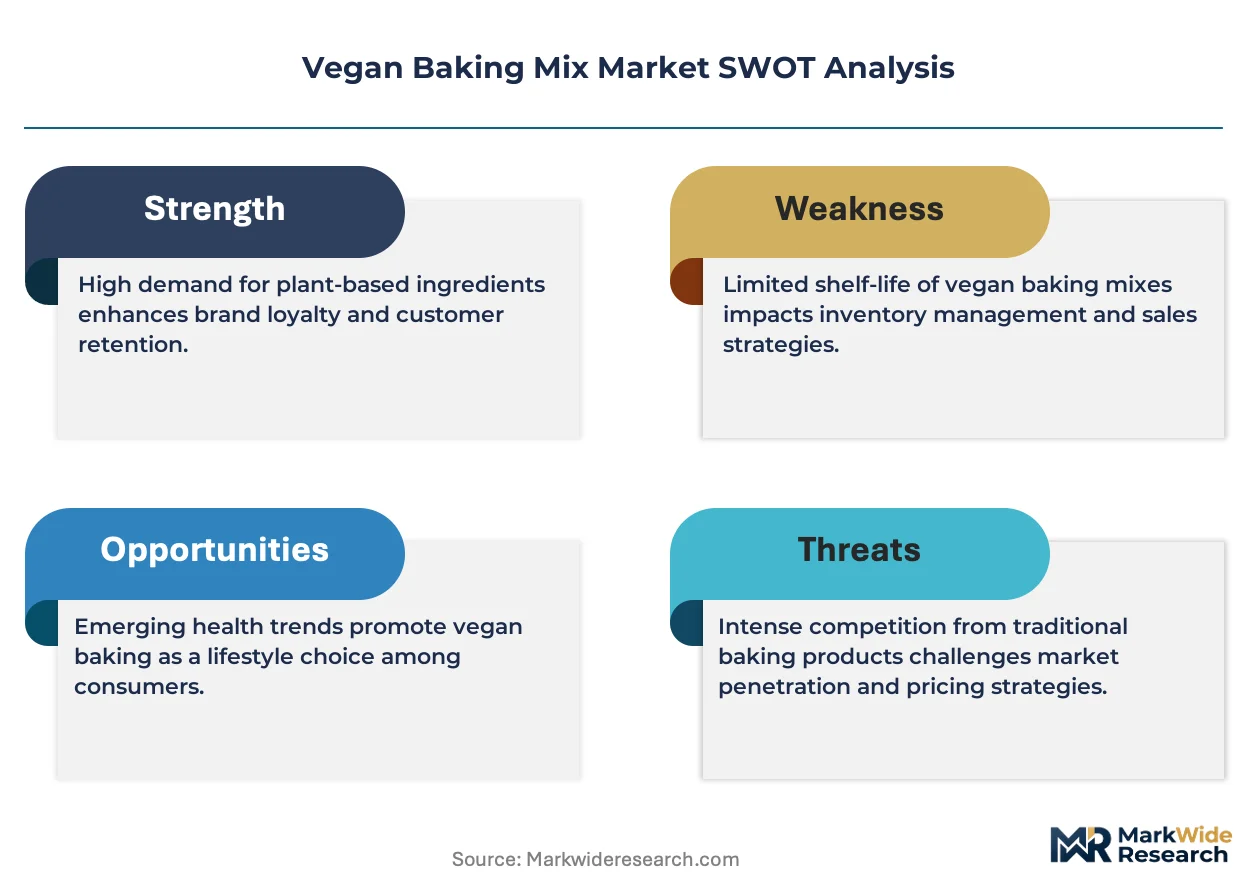
Clean-label certification mandates from the USDA and EU Green Deal are compressing formulation freedom while specialty cafes accelerate SKU proliferation, forcing suppliers to reconcile artisan positioning with industrial scale.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Mandatory sustainable sourcing documentation for oat and almond supply chains creates competitive moat for early-compliant brands in European export channels.
- Metropolitan health-conscious clusters:Concentrated demand in Los Angeles, New York, and London drives premium pricing acceptance and accelerates new flavor variant testing.
- Precision-fermented egg replacers:Novel enzymatic binding systems expand clean-label formulation options beyond traditional hydrocolloid stabilizers.
Market Restraints
- Almond flour input cost volatility:California drought cycles and water allocation disputes create margin compression for nut-forward formulations.
- Single-source hydrocolloid dependency:Guar gum concentration in Rajasthan, India exposes supply chains to monsoon-driven harvest variability.
- Clean-label definition fragmentation:Divergent USDA Organic, EU organic, and private retailer standards multiply certification costs without consumer clarity.
Strategic Opportunities
- Chickpea flour protein-forward positioning:Athletic and diabetic consumer segments in Germany and Australia show unmet demand for high-protein baking alternatives.
- Direct-to-bakery bulk dispensing:Specialty cafes in Portland and Austin are piloting zero-waste refill systems for high-volume brownie and cookie bases.
- Precision-fermentation regulatory clarity:FDA and EFSA classification timelines will determine whether novel egg replacers qualify for non-GMO claims.
Industry Challenges
- Food technologist specialization gap:Shortage of formulation chemists trained in plant-based rheology slows clean-label product development cycles.
- Multi-certification audit complexity:Simultaneous USDA Organic, Non-GMO Project, and B-Corp verification creates 18-24 month compliance timelines.
- Legacy equipment retrofit costs:Dedicated lines for allergen-free production require capital outlay that mid-tier co-manufacturers struggle to justify.
Report Scope
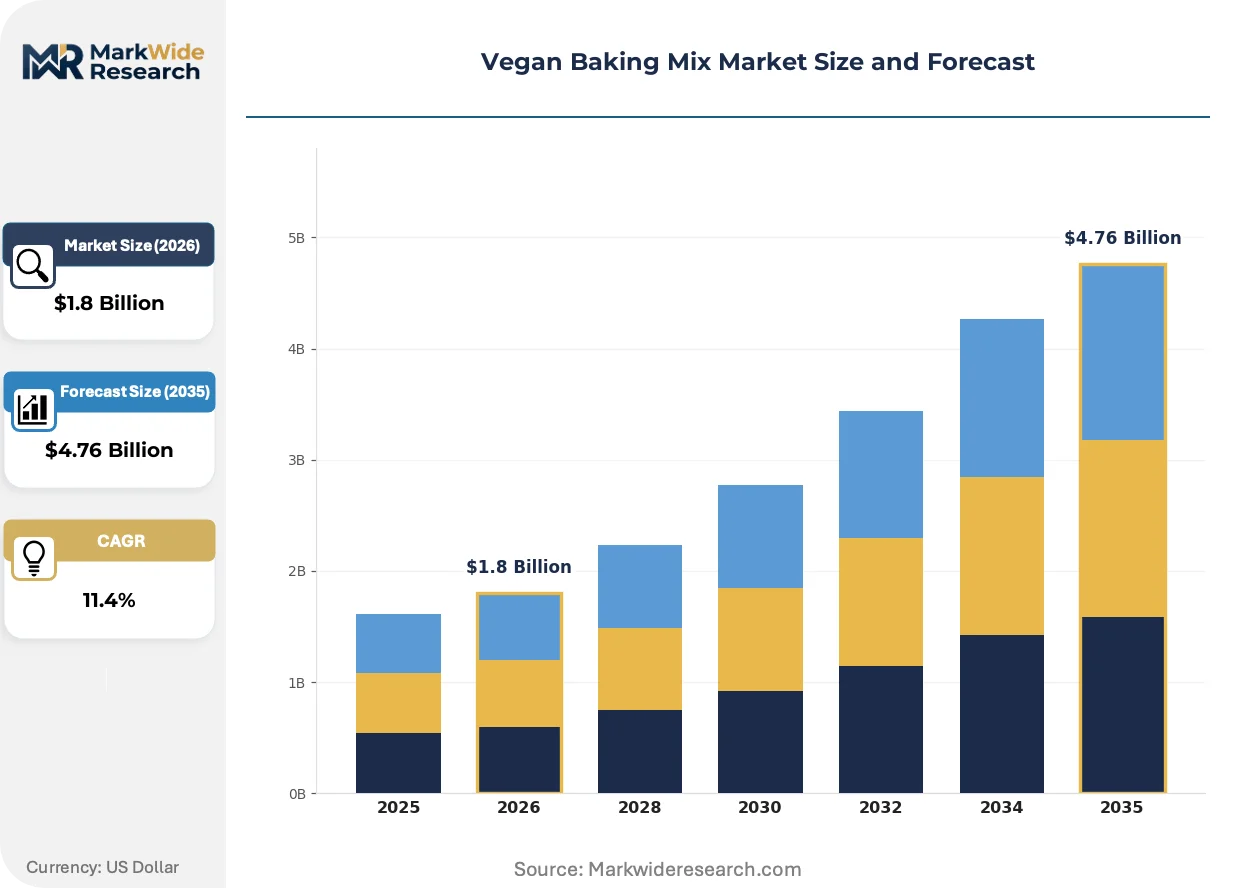
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Baking Mix Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brownie Mix, Pancake Mix, Cookie Mix, Muffin Mix Ingredient Type: Almond Flour, Coconut Flour, Oat Flour, Chickpea Flour End User: Households, Cafes, Restaurants, Bakeries Packaging Type: Bags, Boxes, Pouches, Jars |
| Companies Covered | Bob's Red Mill, Simple Mills, King Arthur Baking, Pamela's Products, Betty Crocker, Namaste Foods, Duncan Hines, Miss Jones Baking, Dr. Oetker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Baking Mix Market Evolving Landscape
Binding technology and regulatory classification of novel ingredients are the twin forces compressing competitive timelines, while channel experimentation in specialty retail redefines how consumers encounter vegan baking solutions.
Enzymatic egg replacers based on precision-fermented proteins are migrating from niche R&D pipelines into commercial formulations. Athletic nutrition brands and diabetic-focused bakeries are piloting these systems at pilot-scale volumes. The technology is migrating from experimental positioning toward mainstream clean-label acceptance, contingent on regulatory classification outcomes.
USDA Organic seal requirements and FDA food labeling standards are tightening permissible health claim language for domestic manufacturers. The industrial consequence is reduced marketing flexibility for "natural" and "wholesome" positioning. Brownie and cookie mix categories, which rely heavily on gifting and occasion-based messaging, are responding with deeper ingredient transparency rather than claim expansion.
Specialty cafes in Portland, Los Angeles, and London are unbundling after-sales recipe support in favor of ready-to-use solutions with minimal add-in requirements. This procurement compression eliminates a traditional revenue stream for mix suppliers while opening shelf-stable, long-tail distribution through natural channel retailers. The shift is most visible in breakfast-adjacent categories where time-constrained consumers dominate purchase decisions.
Vegan Baking Mix Market Segmentation
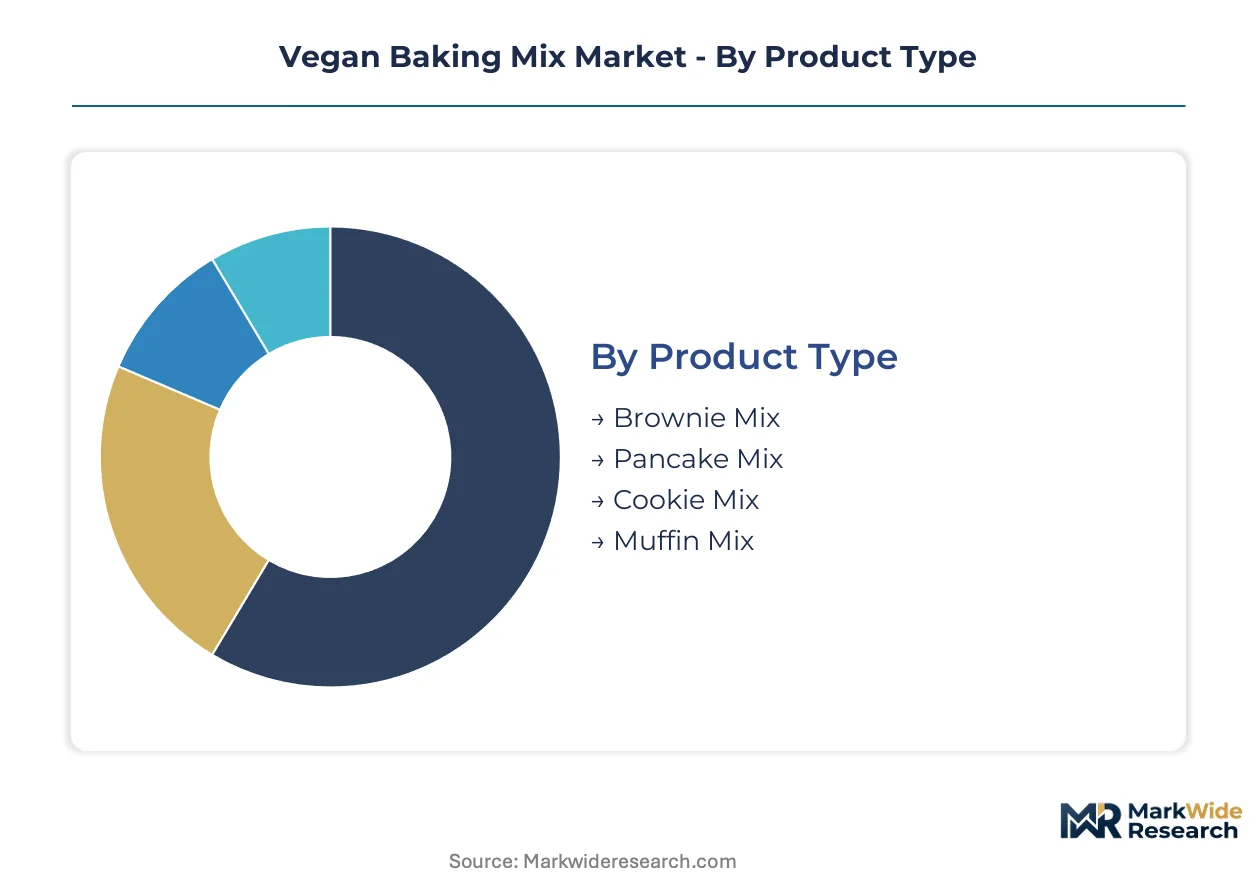
Segmentation in vegan baking mixes reveals how formulation choices, channel strategies, and packaging economics split addressable demand across distinct margin profiles. Each dimension carries specific regulatory and supply chain implications that shape supplier positioning.
Product Type:
Application use cases separate repeat-purchase staples from occasion-driven categories with distinct velocity and premiumization potential.
- Brownie Mix:Dense, fudgy formulations rely on cocoa butter and hydrocolloid stabilizers to replicate egg-bound structure. Demand clusters in metropolitan gift markets and specialty cafes in Los Angeles and New York where occasion-based premium pricing sustains margins.
- Cookie Mix:Versatile base formulations accommodate mix-in customization while maintaining shelf stability through modified starch systems. Household penetration in health-conscious clusters drives the highest repeat purchase frequency among all product types.
- Pancake Mix:The most mature breakfast ritual category with limited premiumization headroom due to entrenched preparation habits.
- Muffin Mix:Higher complexity formulations requiring precise leavening balance; bakery channel concentration in Portland and Austin pilot programs.
Brownie Mix holds installed capacity. Cookie Mix is rotating up the share rankings.
Ingredient Type:
Cost tiers and protein positioning separate commodity grain bases from specialty nut and legume formulations with distinct supply risk profiles.
- Chickpea Flour:High-protein, low-glycemic index positioning targets athletic nutrition and diabetic consumer segments in Germany and Australia. Supply expansion in Saskatchewan and Ethiopia is reducing price volatility versus nut-based alternatives.
- Almond Flour:Premium fat content and neutral flavor profile anchor keto and paleo-positioned mixes. California drought cycles and water allocation disputes create persistent input cost volatility that compresses margins for nut-forward formulations.
- Oat Flour:Clean-label familiarity and EU Green Deal-compliant sourcing documentation advantages for European export channels.
- Coconut Flour:High-fiber, low-carbohydrate positioning with hygroscopic handling requirements that limit co-manufacturer flexibility.
Almond Flour holds installed capacity. Chickpea Flour is climbing the fastest among ingredient alternatives.
End User:
Customer type determines formulation complexity, certification requirements, and procurement scale with fundamentally different service models.
- Households:Single-serve and small-format packaging with minimal add-in requirements dominates natural channel retail. Label-conscious buyers in London and New York metropolitan clusters drive organic certification premiums.
- Bakeries:Bulk dispensing systems and consistent batch scalability requirements; zero-waste refill pilots in Portland and Austin signal channel evolution toward sustainability-integrated procurement.
- Cafes:SKU proliferation pressure from specialty coffee chains accelerates flavor variant testing but compresses supplier margins through volume consolidation.
- Restaurants:Dessert menu integration with back-of-house simplicity requirements; limited from-scratch capability drives ready-to-use solution demand.
Households hold installed capacity. Bakeries is rotating up the share rankings.
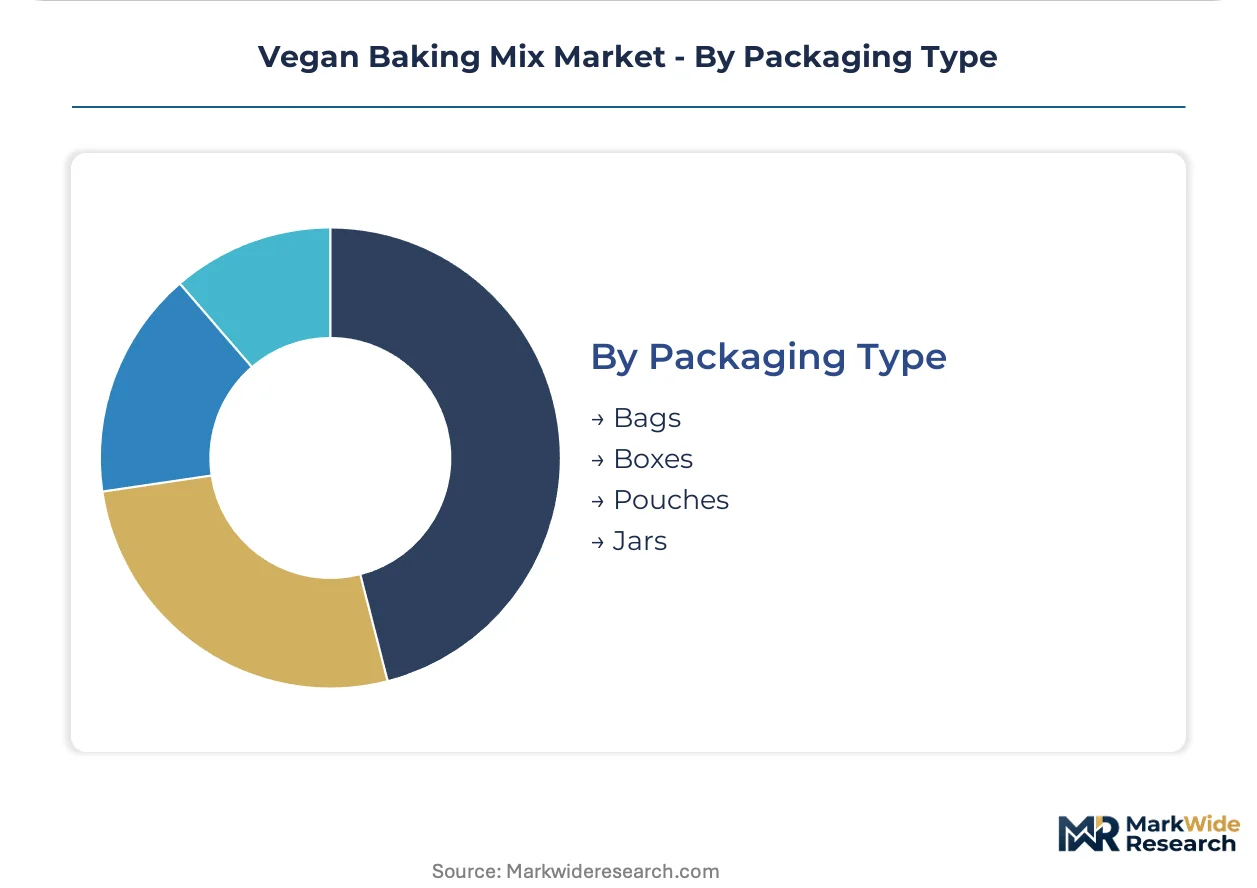
Packaging Type:
Volume economics and shelf-preservation technology separate commodity formats from premium presentation tiers with distinct material cost structures.
- Pouches:Flexible film barriers with reseal functionality command natural channel shelf space and reduce shipping cube versus rigid alternatives. Stand-up pouch adoption in Whole Foods and Sprouts regions accelerates format conversion from legacy boxes.
- Boxes:Structural rigidity protects fragile inclusions and supports premium gifting positioning; higher material costs pressure mid-tier brands.
- Bags:Lowest unit cost format with limited barrier properties; club channel and value-oriented retail concentration.
- Jars:Reusable premium positioning for specialty nut-flour formulations; glass weight and fragility limit e-commerce viability.
Boxes hold installed capacity. Pouches is expanding most quickly among packaging alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Metropolitan health-conscious clusters in the United States drive premium organic certification acceptance, while European buyers prioritize EU Green Deal-compliant sustainable sourcing documentation. Asian markets concentrate demand in protein-forward athletic nutrition segments.
United States
Specialty cafes in Los Angeles and New York accelerate SKU proliferation for brownie and cookie bases. FDA food labeling requirements and USDA Organic seal mandates shape permissible health claim language for domestic manufacturers. Portland and Austin pilot zero-waste bulk dispensing systems for bakery channel procurement.
Germany
Athletic and diabetic consumer segments show unmet demand for high-protein chickpea flour formulations. EFSA classification timelines for precision-fermented ingredients determine clean-label positioning eligibility. Berlin and Hamburg metropolitan clusters anchor European demand for transparent sourcing claims.
United Kingdom
London's natural channel retailers drive stand-up pouch adoption and premium gifting positioning for specialty nut-flour formulations. EU Green Deal Farm to Fork strategy pressures import-dependent brands to document sustainable oat and almond supply chains. Manchester and Bristol health-conscious households sustain repeat purchase frequency in cookie mix categories.
Australia
High-protein baking alternatives gain traction among athletic nutrition segments in Sydney and Melbourne. TGA regulatory frameworks influence novel ingredient approval timelines for enzymatic binding systems. Queensland and Western Australia supply chain expansion reduces chickpea flour price volatility versus nut-based alternatives.
Canada
Health Canada labeling standards align with FDA requirements for cross-border product harmonization. Toronto and Vancouver metropolitan clusters concentrate demand for grain-free and allergen-free formulations. Prairie provinces oat cultivation supports EU Green Deal-compliant sourcing documentation for European export channels.
Vegan Baking Mix Market Competitive Landscape
Capability concentration sits with heritage milling specialists and organic certification leaders; scale advantage sits with mass-market baking conglomerates. The vendor base stratifies across three tiers: premium artisan-positioned independents, mid-tier natural channel specialists, and commodity-scale CPG players. Strategic archetypes include clean-label certification specialists, protein-forward ingredient innovators, and private-label co-manufacturing platforms. Dominant competitive moves encompass portfolio diversification into grain-free formulations and backward integration into specialty flour milling.
Within the heritage milling tier, King Arthur Baking anchors premium positioning through specialty flour expertise. Simple Mills exemplifies grain-free formulation leadership that commands natural channel shelf space. Miss Jones Baking occupies a position within the organic certification specialist archetype, leveraging transparent sourcing claims to resonate with label-conscious buyers.
| Leading Market Players |
|---|
| Bob's Red Mill |
| Simple Mills |
| King Arthur Baking |
| Pamela's Products |
| Betty Crocker |
| Namaste Foods |
| Duncan Hines |
| Miss Jones Baking |
| Dr. Oetker |
| Others |
Value Network & Pricing Analysis
Portland-to-Los Angeles freight corridors carry oat and almond flour shipments where fuel surcharge volatility feeds directly into landed costs for specialty cafes, compressing margins for nut-forward formulations while amplifying price premiums for EU Green Deal-compliant documentation.
Pricing Analysis
Long-term offtake contracts dominate procurement between major mills and bakery chains, insulating volume buyers from spot-market swings in chickpea and almond flour. Three-tier pricing structure across premium organic-certified, standard clean-label, and economy conventional tiers separates King Arthur Baking heritage positioning from commodity private-label alternatives. Pricing pressure stems from California drought-driven almond input volatility, forcing reformulation toward oat and chickpea bases. Household buyers in metropolitan clusters show lowest price sensitivity, while club-channel bag formats compete on per-ounce economy.
Supply Chain Analysis
Upstream feedstock concentration in California almond orchards, Saskatchewan chickpea cultivation, and Canadian prairie oat operations creates geographic dependency for protein-forward and clean-label formulations. Guar gum hydrocolloids draw from Rajasthan monsoon harvests, while cocoa butter for brownie bases sources from West African cooperatives. Single-source hydrocolloid vulnerability exposes batch consistency to climate-driven harvest variability. Distribution runs through natural channel distributors to Whole Foods and Sprouts regions, with direct-to-bakery bulk dispensing pilots in Portland and Austin bypassing traditional retail markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty cafe procurement platforms are consolidating supplier relationships into interoperable sourcing ecosystems, compressing vendor counts while rewarding formulation partners with USDA Organic and EU Green Deal documentation capabilities.
For Market Incumbents: Insulate premium positioning through backward integration into specialty flour milling, capturing margin lost to volatile almond and oat spot markets. Expand certification investment across USDA Organic, Non-GMO Project, and B-Corp standards to deepen competitive moats against emerging private-label entrants. Prioritize capacity addition in Saskatchewan and Ethiopia chickpea sourcing to reduce nut-flour dependency.
For New Entrants and Emerging Players: Pursue white-space opportunities in direct-to-bakery bulk dispensing systems, where zero-waste refill pilots in Portland and Austin lack established supplier relationships. Target athletic nutrition segments in Germany and Australia with protein-forward chickpea formulations, as incumbent portfolios underweight diabetic and performance-positioned SKUs. Launch through natural channel distributors with transparent sourcing claims as the primary go-to-market angle.
For Investors and Strategic Acquirers: EFSA classification timelines for precision-fermented egg replacers reshape the acquisition landscape, determining which formulation platforms qualify for clean-label premiums versus GMO-adjacent discounting. Target mid-tier natural channel specialists with established co-manufacturer relationships and multi-certification audit completion, as compliance timelines stretch 18-24 months for new entrants. Watch FDA and EFSA novel ingredient rulings as the signal for portfolio revaluation in enzymatic binding technology.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Milling | Captures margin compression from California almond drought cycles and volatile oat inputs. |
| Multi-Certification Compliance Investment | USDA Organic, Non-GMO Project, and B-Corp verification creates 18-24 month barriers for competitors. |
| Direct-to-Bakery Bulk Dispensing Launch | Zero-waste refill pilots in Portland and Austin bypass retail markup while locking in cafe procurement. |
| Precision-Fermentation Formulation Partnership | Early positioning on enzymatic egg replacers contingent on EFSA clean-label classification outcomes. |
| EU Green Deal Sourcing Documentation | Farm to Fork compliance enables premium European export channel access for oat and almond supply chains. |
Research Methodology
A spread of perspectives from R&D formulation chemists, natural channel category buyers, specialty cafe procurement directors, and co-manufacturer operations managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with supply chain stakeholders and secondary validation through FDA food labeling guidance, USDA Organic certification databases, EU Green Deal Farm to Fork strategy documents, and customs trade records for oat and almond flour imports. Bottom-up SKU velocity estimates from natural channel retail audits triangulated against top-down market sizing from ingredient supplier shipment data.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions spanning product type, ingredient base, end-user channel, and packaging format. CAGRs derived from historical velocity trends in brownie and cookie mix categories, adjusted for clean-label certification penetration rates and precision-fermentation regulatory approval timelines. Forecast inputs incorporated metropolitan health-conscious cluster expansion patterns and specialty cafe SKU proliferation rates.
Macroeconomic conditions sit as an overlay; deviation in freight fuel costs, California water allocation rulings, and Rajasthan monsoon patterns would shift the trajectory. Forecasts reflect documented assumptions about regulatory classification timelines and clean-label definition convergence. Cross-checking against EU import documentation requirements and natural channel retail audit benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Biscuit Mixes Market
Bakery Products
Flour Mixes Market
Bakery Products
Specula Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Instant Cake Gel Market
Bakery Products
Wedding Cakes Market
Bakery Products
Bakery Cases Market
Bakery Products
Pastry Dough Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Bakery Mixes Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Pizza Crust Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Bread Slicer Blades Market