
 Baking Molds and Trays Market | 2026-2036
Baking Molds and Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Baking Molds and Trays Market Outlook
LFGB food-contact certification is rotating supplier eligibility across European distribution channels, forcing mold makers to recalibrate polymer formulations and metal coatings. Nordic Ware leverages its Minnesota-based aluminum die-casting capacity to sustain North American retail shelf dominance. Silikomart competes through Italian-designed platinum silicone platforms that anchor European pastry chef loyalty. Guardini S.p.A. specializes in rolled-steel tart molds with PFOA-free coatings, occupying mid-tier European household segments.
Baking molds and trays comprise formed cooking vessels engineered from aluminum alloys, stainless steel, borosilicate glass, or platinum-cured silicone, with wall thicknesses typically ranging from 0.8 mm to 2.5 mm depending on thermal conductivity requirements and intended bake cycle duration. These tools provide controlled heat distribution, structural shape retention, and clean release for dough-based and batter-based food preparation across commercial and residential kitchens. Aluminum baking sheets lead volume throughput due to thermal efficiency and cost scalability, while silicone cupcake molds represent the fastest-expanding material segment among home bakers seeking flexible storage and dishwasher compatibility. Steel loaf pans command premium positioning in professional chef channels where durability under repeated thermal cycling determines procurement decisions.
FDA food-contact substance regulations govern silicone and coating chemistry for US-bound products, while EU Framework Regulation EC 1935/2004 and Germany's LFGB set parallel compliance thresholds for European market access. BIS certification requirements in India and China's GB standards for food-contact metals further fragment qualification burdens, compelling exporters to maintain multiple material certification portfolios. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across jurisdictions, as coating chemistry transitions will reshape supplier cost structures and product line viability within the next certification cycle.
Market Dynamics
Material certification cascades from Germany's LFGB and the EU's Framework Regulation EC 1935/2004 are forcing simultaneous reformulation of silicone polymers, aluminum coatings, and steel surface treatments across supplier portfolios.
Growth Catalysts
- EU food-contact compliance tightening:Germany's LFGB certification requirements are expanding addressable market for platinum-cured silicone and PFOA-free coated metal formats as non-compliant suppliers exit distribution channels.
- Artisan bakery expansion:Western European craft bakeries are scaling silicone mold procurement to meet pastry chef demand for flexible, precision-release tooling in high-mix production environments.
- Home baking persistence:Residential kitchen investment in dishwasher-compatible, space-efficient bakeware continues elevating silicone cupcake and muffin formats above traditional rigid alternatives.
Market Restraints
- Aluminum alloy cost volatility:Primary aluminum price fluctuations and energy-intensive smelting economics compress margin structures for die-cast sheet and formed pan manufacturers.
- Coating chemistry transition costs:Per- and polyfluoroalkyl substance restrictions across multiple jurisdictions force expensive R&D pivots away from legacy non-stick formulations before amortization cycles complete.
- Certification portfolio fragmentation:Exporters must maintain parallel FDA, LFGB, BIS, and GB standard compliance, multiplying testing burdens and extending product launch timelines.
Strategic Opportunities
- India BIS certification alignment:Early movers securing Bureau of Indian Standards food-contact approvals capture share in underpenetrated commercial bakery and hospitality procurement channels.
- Platinum silicone-steel hybrid platforms:Convergence of flexible silicone forms with rigid steel structural frames addresses professional chef demands for durability combined with intricate shape release.
- Direct-to-pastry-chef digital channels:Bypassing traditional hospitality distribution, specialized mold makers are building e-commerce platforms targeting certified product education and reorder convenience.
Industry Challenges
- Multi-jurisdiction certification timelines:Sequential FDA, EU, and Asian market approvals extend product commercialization cycles by 18-24 months, straining working capital and first-mover advantage windows.
- Polymer formulation talent scarcity:Food-grade silicone chemistry expertise concentrates among Italian and German technical specialists, limiting supplier scaling in emerging manufacturing geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baking Molds and Trays Market |
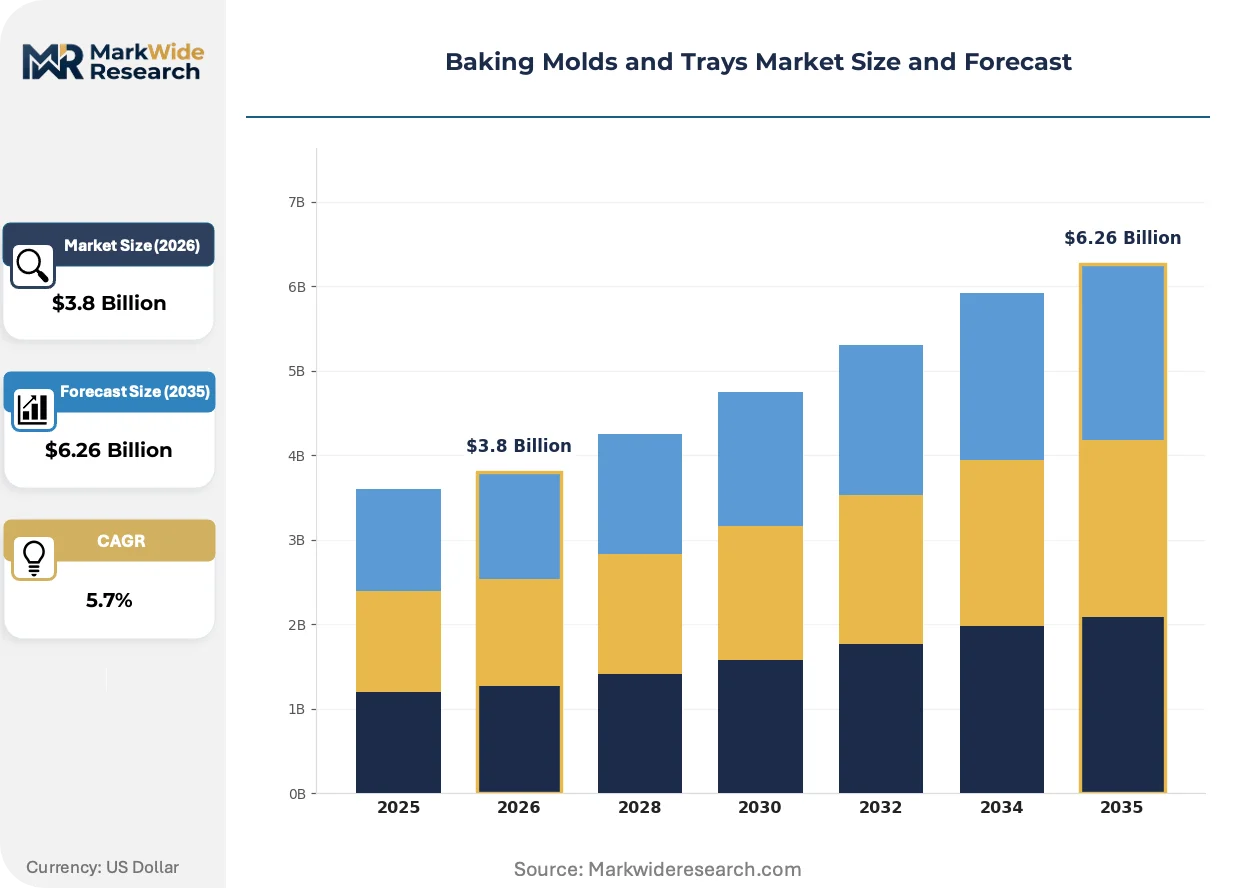
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cupcake Molds, Loaf Pans, Baking Sheets, Tart Pans Material: Silicone, Aluminum, Steel, Glass Size: Mini, Medium, Large, Extra Large End User: Home Bakers, Professional Chefs, Bakeries, Restaurants |
| Companies Covered | Nordic Ware, Wilton Brands LLC, USA Pan, Fat Daddio's, Silikomart, Guardini S.p.A., Pavoni Italia, Hans Brunner GmbH, Le Creuset, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baking Molds and Trays Market Strategic Shifts
Active material science advancement and regulatory chemistry restrictions are compressing legacy coating technologies while elevating certified alternatives. Supplier R&D investment now concentrates on thermal performance optimization and cross-border compliance automation.
Platinum-cured silicone formulations with enhanced thermal stability and mechanical resilience are decomposing traditional aluminum dominance in intricate pastry applications. Artisan bakeries in France and Italy are adopting these platforms for complex entremet and petit gateau production. The technology is decomposing price premiums historically commanded by machined aluminum molds in specialty formats.
REACH restrictions on per- and polyfluoroalkyl substances are accelerating coating chemistry transitions across European supplier bases. Industrial consequence includes forced obsolescence of established non-stick formulations and urgent substitution with ceramic and sol-gel alternatives. Professional kitchen procurement in Germany and France is most affected, with buyers now requiring explicit PFAS-free documentation in supplier qualification.
Certification-driven purchasing behavior is restructuring hospitality procurement relationships. Pastry chefs and commercial bakery operators are consolidating supplier relationships around vendors holding simultaneous FDA, LFGB, and BIS credentials, displacing fragmented multi-source strategies. This concentration is most visible in Nordic and Benelux markets where food safety auditing intensity exceeds Southern European norms.
Baking Molds and Trays Market Segmentation
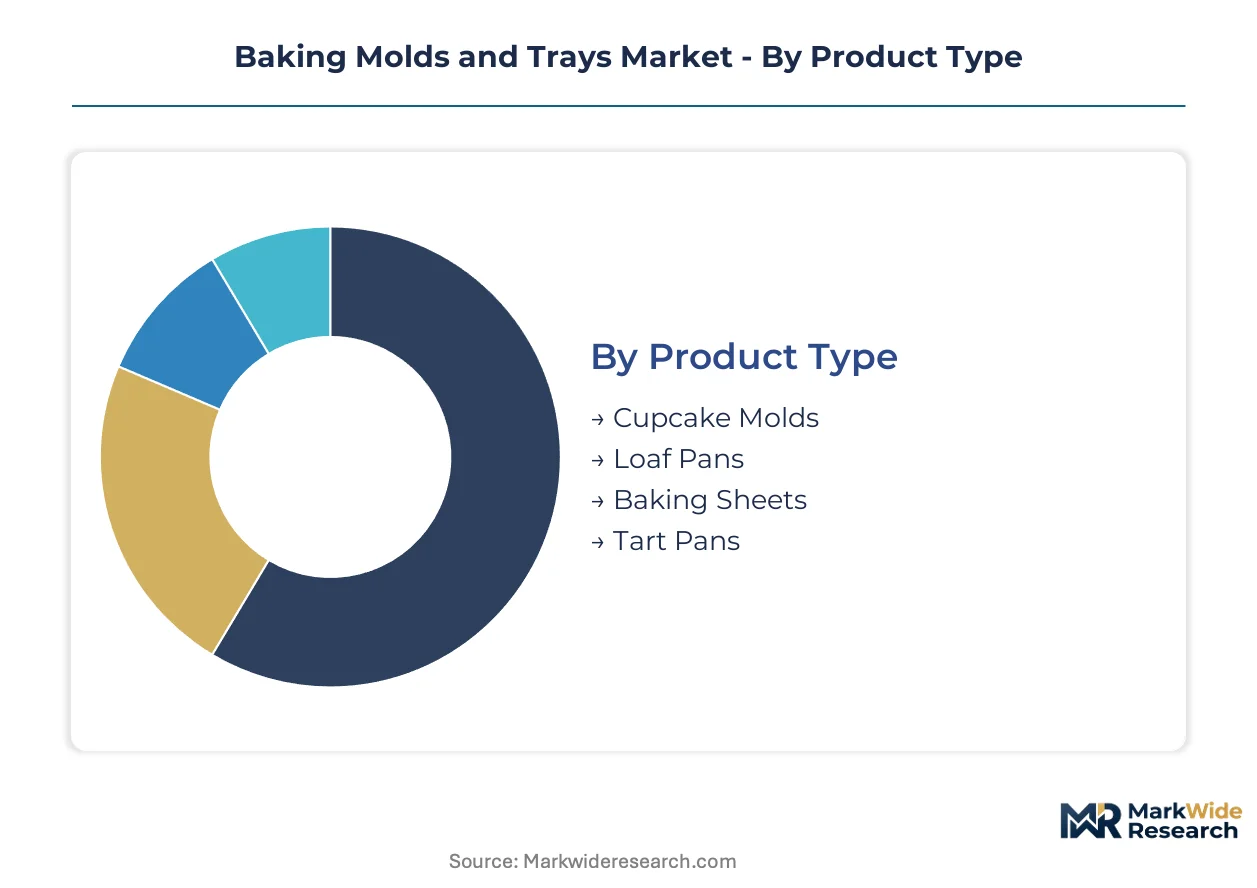
Segmentation in baking molds and trays determines procurement channel access, certification requirements, and margin structures. Professional channels demand material traceability and thermal performance documentation that residential retail channels rarely enforce.
Product Type:
Channel distribution varies sharply by product format, with commercial hospitality suppliers dominating tart pan and loaf pan flows while mass retail captures cupcake mold and baking sheet volumes.
- Baking Sheets:Flat rectangular aluminum or steel platforms with raised edges, typically 0.8-1.2 mm thickness for even heat distribution. Demand concentrates in US restaurant chains and European commercial bakeries where throughput efficiency and NSF certification drive replacement cycles.
- Cupcake Molds:Multi-cavity silicone or metal forms engineered for uniform batter distribution and clean release. Home bakers in Germany and France are shifting procurement toward platinum-cured silicone formats that collapse for drawer storage and withstand dishwasher cycling.
- Loaf Pans:Rectangular vessels with standardized bread dimensions, constructed from aluminized steel or cast aluminum for structural rigidity under repeated thermal shock.
- Tart Pans:Shallow fluted rings with removable bottoms, predominantly rolled steel with ceramic coatings for precise pastry edge definition.
By volume, baking sheets lead. By growth pace, cupcake molds are expanding most quickly.
Material:
Cost tier stratification separates premium platinum silicone and heavy-gauge steel from commodity aluminum and entry glass, with certification grade often overriding base material economics in professional procurement.
- Aluminum:Die-cast or stamped sheet alloys offering superior thermal conductivity at moderate weight. Commercial bakery procurement in Italy and Spain favors certified aluminum for high-volume production lines where energy efficiency amortizes equipment investment.
- Silicone:Platinum-cured elastomer formulations with thermal stability to 230°C, delivering flexible demolding and nested storage. Pastry chefs in France and artisan bakers across Belgium are displacing rigid molds for entremet and petit gateau applications requiring intricate geometry release.
- Steel:Rolled carbon or stainless formats with PFOA-free ceramic coatings, commanding durability premiums in professional channels.
- Glass:Borosilicate compositions offering visual bake monitoring and chemical inertness, constrained by thermal shock sensitivity and weight.
Steel commands the highest unit margins. Silicone demonstrates the steepest expansion trajectory.
Size:
Application context dictates size selection, with commercial throughput requirements favoring large formats and precision pastry work driving mini segment innovation.
- Large:Standard commercial dimensions optimized for full-sheet ovens and high-volume production. Restaurant chains in the US and contract bakeries in Germany specify large-format aluminum sheets for operational efficiency.
- Mini:Individual-portion molds for tasting menus, catering, and artisan retail. Pastry chefs in Paris and Milan are scaling mini silicone formats for petit gateau and entremet lines where presentation granularity commands price premiums.
- Medium:Residential kitchen standards matching conventional oven dimensions and household batch sizes.
- Extra Large:Industrial bakery specifications for tunnel ovens and automated production lines.
Large formats dominate commercial procurement volumes. Mini formats are gaining share fastest in specialty channels.
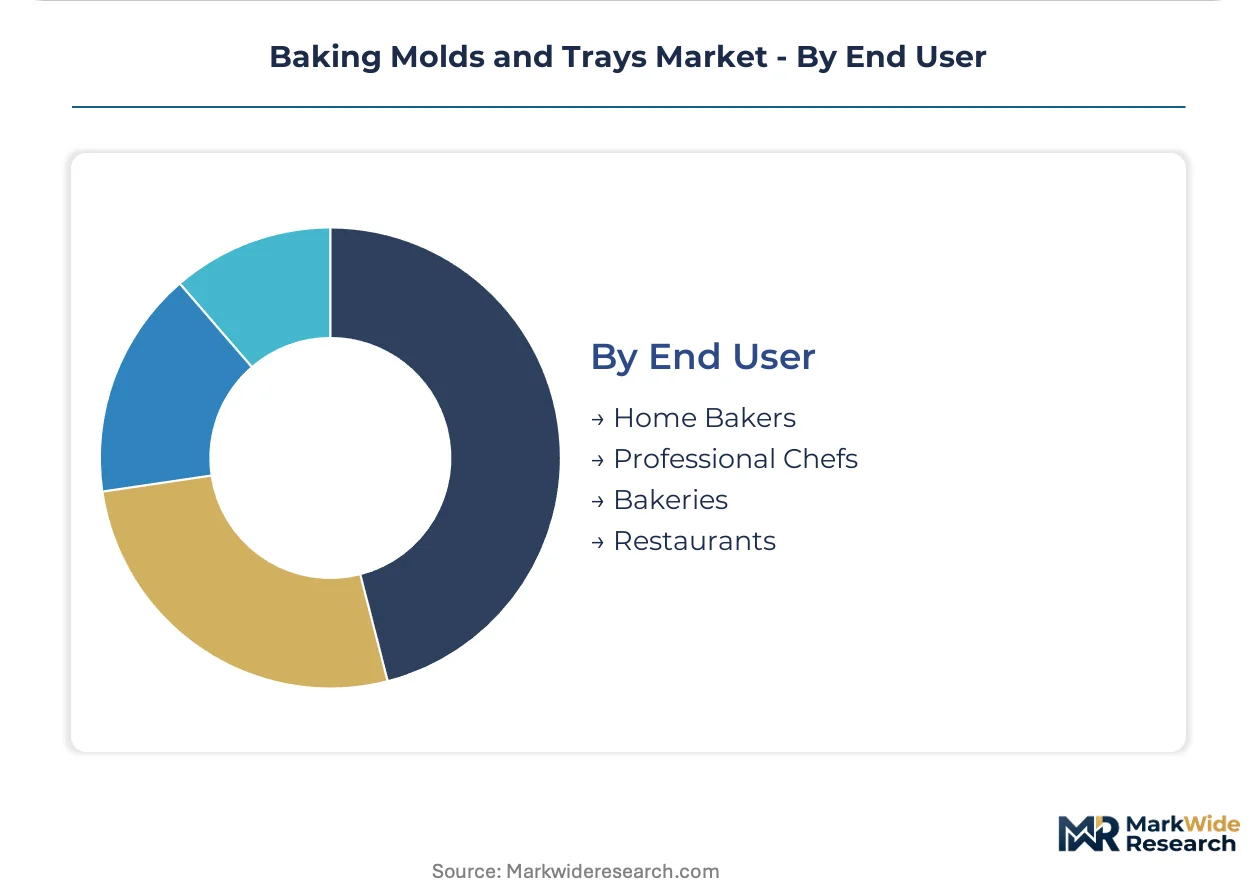
End User:
Customer type determines certification stringency, with professional segments requiring LFGB, FDA, or BIS documentation that home channels rarely demand.
- Professional Chefs:Individual pastry artisans and executive bakers specifying certified platinum silicone and PFOA-free steel with explicit thermal cycling warranties. Procurement concentrates through specialized hospitality distributors in France, Italy, and Germany.
- Home Bakers:Residential consumers prioritizing dishwasher compatibility, collapsible storage, and retail accessibility. German and French households are elevating silicone cupcake and muffin mold adoption above traditional rigid alternatives.
- Bakeries:Commercial production facilities requiring volume pricing, consistent supply, and equipment compatibility across multiple oven formats.
- Restaurants:Foodservice operations balancing durability requirements with kitchen space constraints and multi-purpose utility.
Bakeries generate the highest absolute volume. Professional chefs are expanding procurement fastest as artisan segment growth accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's aluminum die-casting supply chain, channeling raw material flows into Nordic Ware's North American distribution network while connecting European mold makers to Asian silicone polymer sources.
Germany
Artisan bakeries in Munich and Berlin are scaling platinum-cured silicone procurement for entremet production. LFGB certification requirements under Germany's Food and Feed Code are disqualifying non-compliant suppliers from hospitality distribution channels. The Baden-Württemberg industrial corridor hosts specialized coating applicators serving Stuttgart-area metal fabricators.
France
Parisian pastry chefs are consolidating supplier relationships around vendors holding simultaneous FDA and LFGB credentials. ANSM food-contact material oversight is tightening documentation requirements for imported silicone platforms. The Lyon-Rhône manufacturing cluster anchors rolled-steel tart mold production for European retail channels.
United States
Commercial bakery chains in the Midwest are specifying NSF-certified aluminum baking sheets for high-throughput production lines. FDA food-contact substance regulations govern silicone chemistry for domestic-bound products. Minnesota's Twin Cities metro concentrates die-casting capacity serving North American mass retail distribution.
Italy
Artisan producers in Milan and Bologna are displacing rigid aluminum molds with platinum silicone formats for petit gateau applications. EU Framework Regulation EC 1935/2004 compliance is becoming a baseline qualification for hospitality procurement. The Emilia-Romagna tooling district supplies precision-machined mold components to French and German integrators.
India
Commercial bakeries in Mumbai and Bangalore are expanding procurement of BIS-certified bakeware as hospitality sector investment accelerates. Bureau of Indian Standards food-contact approvals are becoming mandatory for imported silicone and metal formats. The Maharashtra industrial corridor is attracting mold makers seeking early-mover positioning in underpenetrated procurement channels.
Baking Molds and Trays Market Competitive Environment
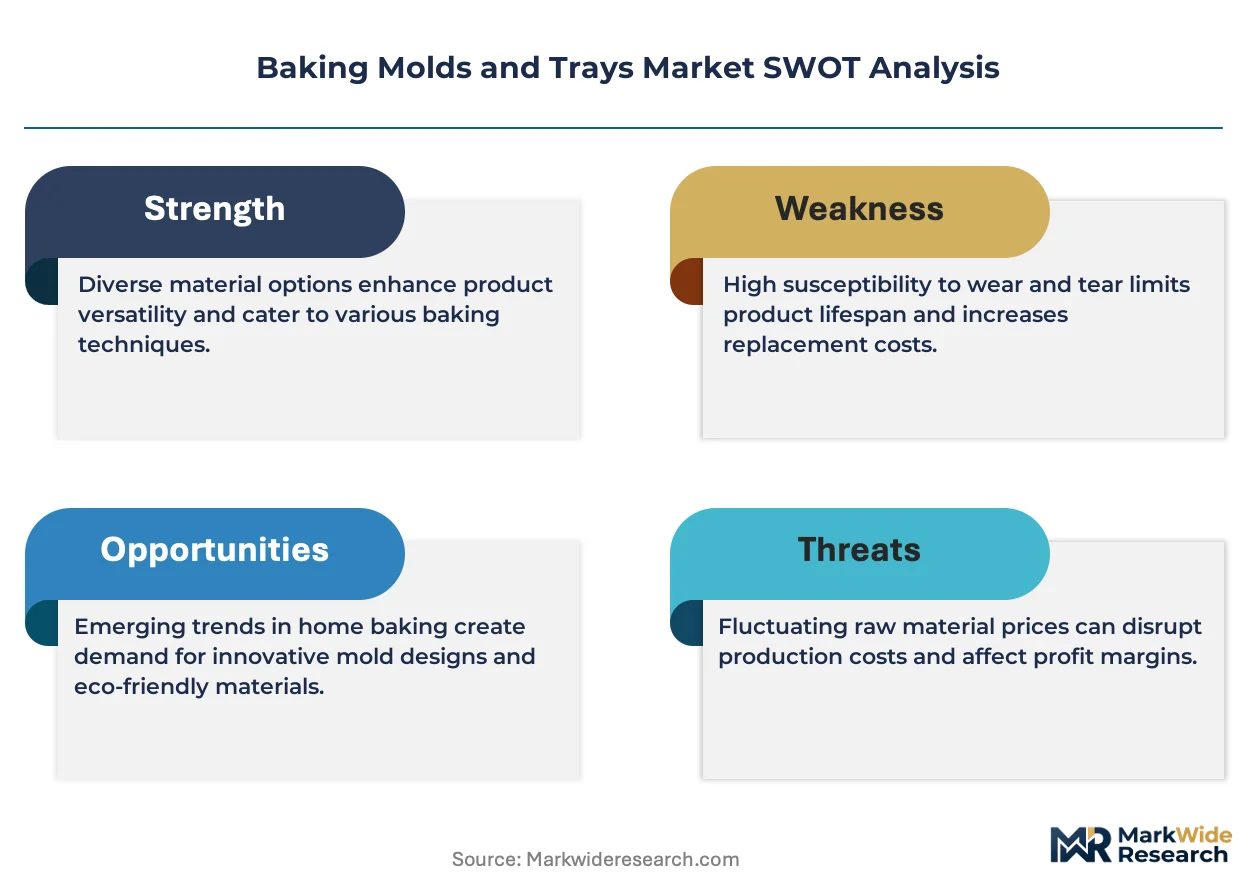
Listed leaders compete with private specialists across certification portfolio breadth, with public company disclosure requirements creating transparency advantages in regulatory compliance documentation while family-owned fabricators retain agility in artisan channel relationships. The vendor base stratifies across three tiers: multinational kitchenware conglomerates with diversified appliance portfolios, specialized bakeware houses concentrating on thermal performance engineering, and regional metal stampers serving private-label retail contracts. Dominant competitive moves include geographic certification expansion to capture emerging market access and material formulation partnerships with polymer suppliers to accelerate PFAS-free coating transitions.
Among European specialists, Silikomart and Guardini S.p.A. exemplify the certification-intensive tier where Italian design heritage converges with LFGB compliance engineering, while Nordic Ware anchors the North American scale-driven segment through Minnesota-based aluminum capacity. These three occupy positions reflecting divergent strategic bets: platinum silicone platform specialization, mid-tier rolled-steel household positioning, and mass-market die-cast dominance respectively.
| Leading Market Players |
|---|
| Nordic Ware |
| Wilton Brands LLC |
| USA Pan |
| Fat Daddio's |
| Silikomart |
| Guardini S.p.A. |
| Pavoni Italia |
| Hans Brunner GmbH |
| Le Creuset |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between German aluminum die-casters and Nordic mass retail distributors lock in multi-year price visibility while securing dedicated capacity for NSF-certified baking sheet production. These arrangements insulate volume buyers from primary aluminum volatility while committing suppliers to LFGB compliance maintenance across coating reformulation cycles.
Pricing Analysis
Certification grade (LFGB/FDA/BIS-tier) creates the primary spread between commodity aluminum formats and platinum-cured silicone premiums. Three-tier pricing structure across certified professional, compliant household, and uncertified entry levels reflects testing burden amortization and liability coverage costs. Pricing pressure stems from coating chemistry transitions as REACH restrictions force premature R&D write-offs. Commercial bakeries exhibit lowest price sensitivity, prioritizing thermal cycling warranties over unit cost.
Supply Chain Analysis
Port of Hamburg throughput constraints periodically disrupt aluminum alloy flows from German smelters to Minnesota die-casting facilities. Raw material sourcing draws from Chinese silicone polymer producers, Italian platinum catalyst suppliers, and domestic steel rolling mills. Single-source vulnerability concentrates in platinum-cured elastomer formulations where Italian technical specialists dominate. Distribution runs through hospitality procurement distributors in France and Germany, mass retail chains in North America, and emerging direct-to-chef digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification jurisdictions creates specialist niches as multi-standard compliance burdens disqualify generalist suppliers from professional channels.
For Market Incumbents: Shield market position by accelerating backward integration into platinum catalyst supply partnerships, reducing exposure to Italian polymer chemistry bottlenecks. Prioritize simultaneous FDA-LFGB-BIS certification maintenance to consolidate hospitality procurement relationships before coating transition costs peak.
For New Entrants and Emerging Players: Differentiate on BIS-first positioning in Indian commercial bakery channels where early certification capture yields procurement lock-in. Target Maharashtra and Karnataka hospitality clusters through localized compliance documentation and regional distributor partnerships.
For Investors and Strategic Acquirers: Food-grade silicone chemistry specialists with existing LFGB credentials represent the most defensible acquisition profile as coating reformulation demands intensify. Monitor REACH enforcement acceleration in Germany and France as the signal for certification-premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Expansion | Simultaneous LFGB, FDA, and BIS approvals unlock hospitality procurement consolidation in Nordic and Benelux markets. |
| Platinum Silicone Polymer Partnership | Italian catalyst supplier alliances secure formulation expertise scarcity and accelerate PFAS-free coating transitions. |
| Direct-to-Chef Digital Platform Launch | Bypassing traditional hospitality distributors captures reorder convenience premiums from Paris and Milan pastry artisans. |
| Hybrid Silicone-Steel Platform Development | Converging flexible forms with rigid frames addresses professional durability demands while enabling intricate release geometry. |
| India BIS Early-Mover Positioning | Maharashtra and Karnataka commercial bakery channel capture precedes mandatory certification enforcement expansion. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with commercial bakery procurement managers, pastry chef equipment specifiers, hospitality distributor category buyers, and aluminum die-casting plant engineers. Secondary validation drew from EU Framework Regulation EC 1935/2004 compliance filings, Bureau of Indian Standards certification registries, FDA food-contact substance notifications, and customs trade flow data. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Across the analysis window, projections model volume and value trajectories through segmentation by material chemistry, end-user certification requirements, product format thermal performance, and regional regulatory cluster. CAGRs derive from historical elasticity patterns applied to aluminum price scenarios and silicone adoption S-curves. Forecast inputs include artisan bakery expansion rates in Western Europe and coating chemistry transition timelines under REACH restrictions.
Material uncertainties — primary aluminum price volatility, per- and polyfluoroalkyl substance ban acceleration, and certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and polymer formulation talent availability. Practitioners should keep alternative scenarios live as EU Green Deal chemical restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread Market
Bakery Products
Baking Mix, Base and Concentrate Market
Bakery Products
Low Fat Bread Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Sweet Biscuits Market
Bakery Products
North America Sweet Biscuits Market
Bakery Products
Oman Frozen Bakery Products Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Pancakes Market
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Bakery Premixes Market
Bakery Products
Bread and Baked Food Market
Bakery Products
No-Fat Cake Market