
 Low Fat Oatmeal Cookies Market | 2026-2036
Low Fat Oatmeal Cookies Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Oatmeal Cookies Market Analytics
Aftermarket recipe licensing is rewriting how legacy food manufacturers monetize their intellectual property in the low-fat oatmeal cookie space. General Mills leverages its decades-old formulation archives to sustain competitive moats against private-label encroachment. Nestlé anchors its position through proprietary oat-milling partnerships that secure premium supply streams. Mondelez International differentiates via controlled glycemic index certifications that command shelf-space premiums in health-focused retail channels.
Low fat oatmeal cookies are baked goods containing no more than three grams of fat per serving, typically achieved through apple sauce or fruit puree fat replacement and steam-injection baking processes that preserve moisture without butter or shortening. Their primary commercial purpose is to deliver fiber-rich snacking options to consumers managing caloric intake or cardiovascular risk profiles. The ingredient source dimension shows organic and non-GMO subcategories capturing expanding margin pools as certification costs decline and consumer willingness-to-pay holds firm. Distribution through health food stores and specialty shops concentrates the highest per-unit margins, while online retail channels compete most aggressively on subscription-driven volume.
FDA nutrition labeling requirements and the USDA organic certification framework shape formulation transparency and market access thresholds for domestic manufacturers. The EU Green Deal's Farm-to-Fork strategy and EFSA health claim verification processes create parallel compliance obligations for exporters targeting European retail networks. Stakeholders must monitor evolving soluble fiber health claim approvals and oat supply chain sustainability audits as the primary determinants of long-term pricing power and geographic expansion feasibility.
Market Dynamics
Clean-label reformulations using soluble oat fiber and reduced saturated fat blends are compressing traditional formulation cycles, forcing manufacturers to rebuild R&D pipelines around ingredient transparency rather than cost engineering alone.
Growth Catalysts
- Corporate wellness program procurement:Health-conscious millennials enrolled in employer-sponsored nutrition initiatives now constitute the fastest-expanding buyer segment for portion-controlled, fiber-enriched snacks.
- FDA nutrition labeling updates:Revised serving-size definitions and added-sugar disclosure mandates are accelerating product reformulation investments among domestic manufacturers seeking shelf-space retention.
- Steam-injection baking:This moisture-preservation technology eliminates butter dependency while maintaining chew texture, enabling fat-content compliance without sensory trade-offs.
Market Restraints
- Oat supply concentration:Premium milling-grade oat procurement depends heavily on North American and Nordic growing regions, exposing margins to weather-driven harvest volatility and freight cost spikes.
- Organic certification cost barriers:USDA organic and Non-GMO Project verification expenses create fixed-cost burdens that disadvantage smaller regional bakeries against scaled competitors.
- Sugar-alcohol substitution limits:Polyol-based fat replacements trigger digestive tolerance thresholds that cap inclusion rates, constraining formulation flexibility for ultra-low-fat targets.
Strategic Opportunities
- Subscription-direct distribution:Online retail channels competing on recurring delivery models offer margin recovery potential bypassing slotting-fee-intensive conventional grocery.
- EFSA health claim pathway:Soluble fiber cardiovascular benefit approvals under EU verification processes would unlock premium positioning in European retail networks.
- Functional ingredient convergence:Probiotic and adaptogenic additive integration targets stress-management positioning within workplace snacking occasions.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists skilled in natural emulsifier systems and enzymatic texturizing command premium compensation, constraining mid-tier manufacturer hiring pipelines.
- Legacy equipment retrofit requirements:Steam-injection oven installation and humidity-control system upgrades demand capital deployment that strains already-thin bakery operating margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Oatmeal Cookies Market |
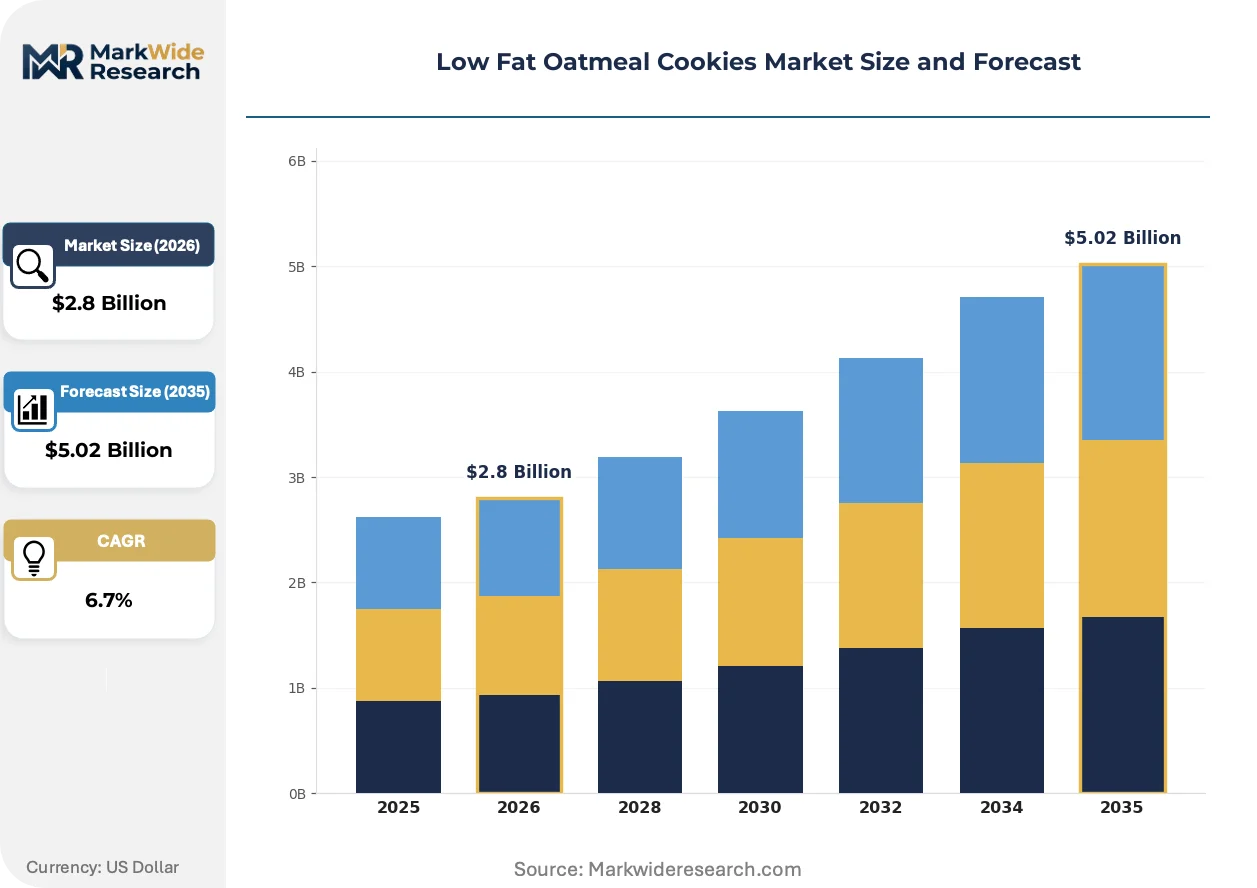
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Baked, Crunchy, Chewy, Gourmet Ingredient Source: Organic, Non-GMO, Conventional, Gluten-Free Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Consumer Type: Health Conscious, Diabetic, Fitness Enthusiasts, Families |
| Companies Covered | General Mills, Nestlé, Conagra Brands, Mondelez International, PepsiCo, Kellogg Company, Kraft Heinz, Hain Celestial Group, Bob's Red Mill Natural Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Oatmeal Cookies Market Evolving Landscape
Reformulation science and procurement transparency are compressing product development timelines while fragmenting competitive advantage sources across ingredient sourcing, manufacturing process, and distribution model simultaneously.
Enzymatic oat processing is collapsing the functional gap between conventional and premium oat fiber ingredients. Mid-tier manufacturers are adopting cellulase and xylanase treatments to achieve beta-glucan concentration levels previously requiring proprietary milling partnerships. This enzymatic democratization is collapsing the historical barrier between mass-market and specialty positioning, forcing premium brands to differentiate through certification stacking rather than ingredient exclusivity.
EU Green Deal Farm-to-Fork sustainability audits are reshaping export compliance burdens. The strategy's mandatory supply-chain traceability requirements impose documentation costs that disproportionately affect smaller US exporters lacking integrated ERP systems. European retail buyers are responding by consolidating vendor relationships toward vertically integrated suppliers capable of batch-level carbon footprint reporting.
Health food store buyers are consolidating assortment decisions around controlled glycemic index certifications. This channel-level preference compression is displacing conventional low-fat claims as the primary shelf-space determinant, favoring manufacturers with third-party metabolic response testing capabilities. The shift is most visible in California and Pacific Northwest metropolitan markets where functional snacking literacy runs highest among core demographics.
Low Fat Oatmeal Cookies Market Segmentation
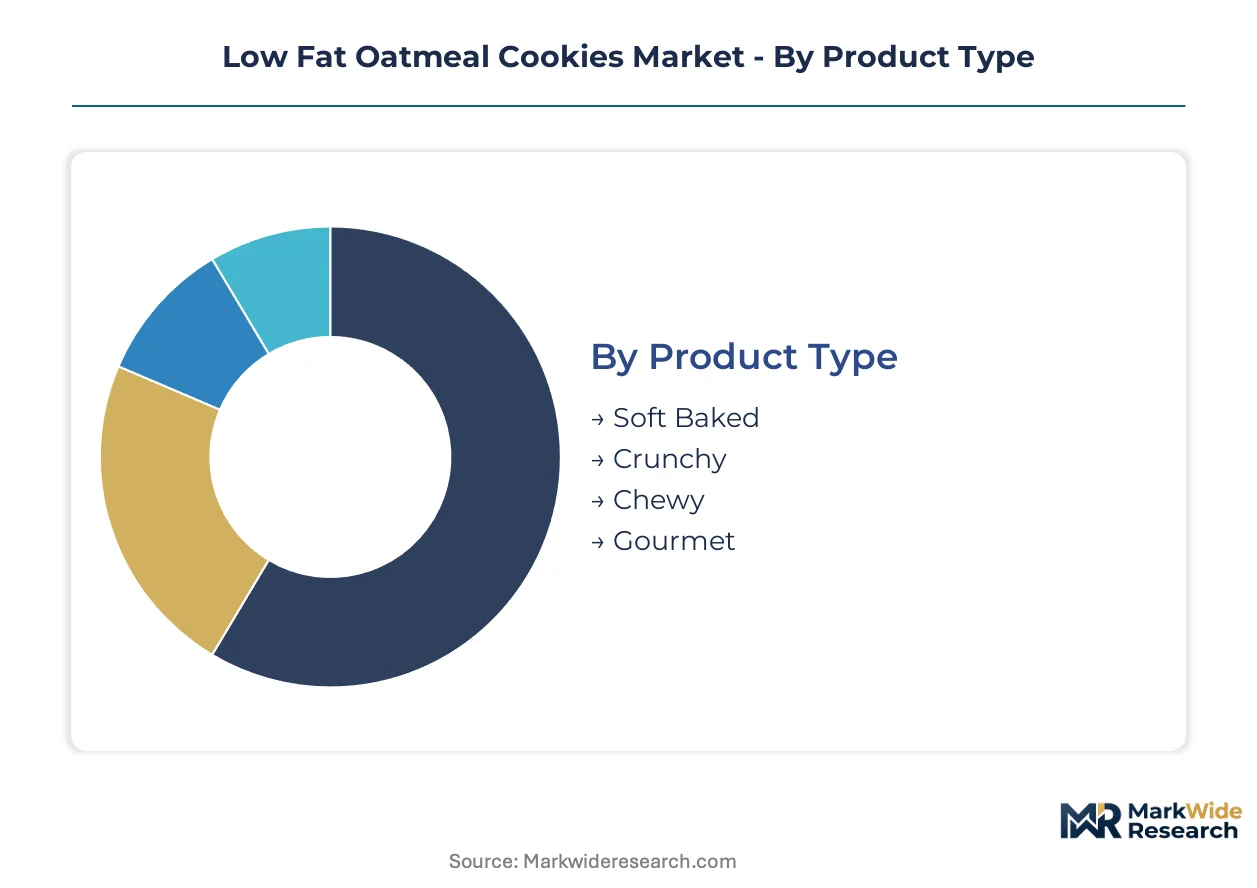
Segmentation in the low-fat oatmeal cookie market reveals how texture preferences, certification premiums, and channel economics fragment purchasing behavior across distinct consumer missions. Manufacturers must align formulation investments with the specific functional and emotional drivers governing each slice of demand.
Product Type:
Texture and moisture profile divide consumer loyalty into four distinct eating occasions, each demanding specialized production parameters and shelf-life engineering.
- Soft Baked:Higher moisture retention through modified starch systems and controlled water activity targets the comfort-snacking segment seeking indulgence without caloric penalty. Corporate wellness program procurement in the United States concentrates here due to portion-controlled packaging compatibility and perceived freshness cues.
- Crunchy:Extended low-temperature drying cycles achieve brittle fracture mechanics preferred by tea and coffee accompaniment occasions. European retail buyers under EFSA labeling frameworks favor this format for its clean ingredient transparency and extended ambient stability.
- Chewy:Intermediate moisture bands balance resilience with tenderness, capturing family pantry stocking missions.
- Gourmet:Premium inclusions and artisan positioning command specialty channel margins.
Soft baked commands the established base. The steepest expansion runs through crunchy formats aligned with European export compliance.
Ingredient Source:
Certification tier functions as a price-quality signal that stratifies manufacturing cost structures and retail placement simultaneously.
- Organic:USDA certification and EU organic logo compliance require segregated supply chains and third-party audit documentation, doubling ingredient procurement costs against conventional benchmarks. Health food stores in California and Pacific Northwest metropolitan markets absorb these premiums through consumer willingness-to-pay for pesticide-residue avoidance.
- Non-GMO:Non-GMO Project verification provides entry-level transparency for mass-market retailers seeking clean-label credibility without full organic conversion. Supermarket private-label programs in the United States leverage this tier for margin recovery against branded competition.
- Conventional:Standard oat supply chains serve price-sensitive volume channels.
- Gluten-Free:Dedicated facility requirements and oat purity protocol compliance target celiac and sensitivity-diagnosed segments.
Conventional maintains volume dominance. Organic certification is climbing the fastest as EU Green Deal sustainability audits elevate traceability requirements.
Distribution Channel:
Channel selection determines margin architecture, with slotting fees and subscription mechanics creating divergent profitability profiles across the route-to-market matrix.
- Online Retail:Direct-to-consumer subscription models bypass wholesale markups and capture first-party consumption data for reformulation targeting. Fitness enthusiasts seeking macro-nutrient customization drive recurring revenue density in this channel.
- Supermarkets:Mass-market penetration depends on trade promotion spending and planogram positioning against entrenched cookie category leaders.
- Health Food Stores:Controlled glycemic index certification and staff education requirements concentrate premium pricing power.
- Specialty Shops:Curated assortment and local sourcing narratives serve gift and discovery-oriented purchasing missions.
Supermarkets anchor current volume. Online retail is expanding most quickly as subscription mechanics reshape household pantry replenishment patterns.
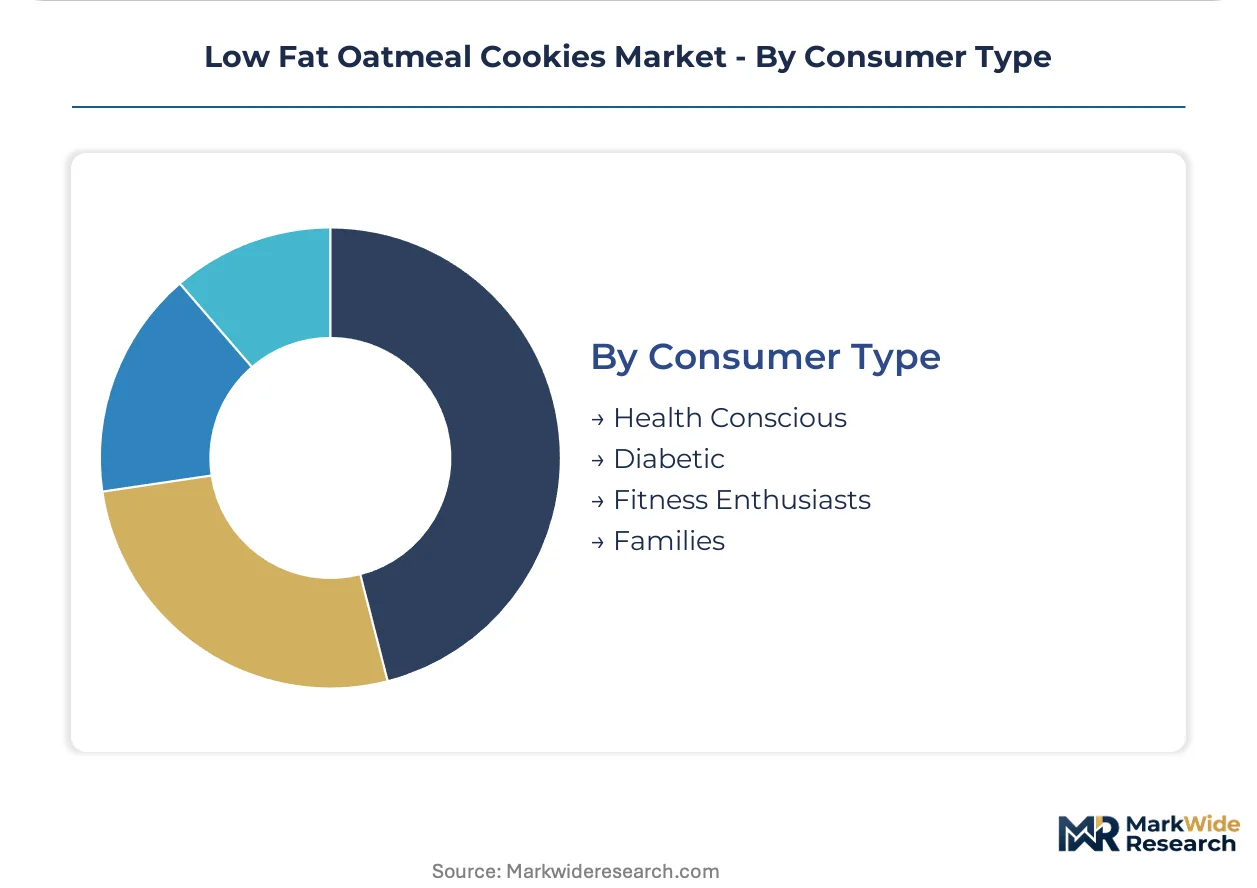
Consumer Type:
Health motivation intensity segments buyers along a spectrum from preventive wellness to clinical dietary management, each demanding distinct nutritional communication strategies.
- Health Conscious:General wellness positioning emphasizing fiber content and reduced saturated fat appeals to preventive lifestyle adopters. Millennials in employer-sponsored nutrition initiatives represent the core expansion demographic for this segment.
- Diabetic:Glycemic response testing and carbohydrate disclosure precision targets insulin-managed consumers seeking predictable glucose impact.
- Fitness Enthusiasts:Macro-tracking compatibility and protein fortification options align with body composition goals.
- Families:Child-friendly portioning and allergen management priorities govern household purchasing decisions.
Health conscious buyers command the established base. The diabetic segment is gaining share fastest as FDA added-sugar disclosure mandates elevate metabolic awareness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between North American functional-snacking adoption and European regulatory-premium positioning, with Asian markets still developing category awareness around low-fat baked goods.
United States
Corporate wellness program procurement drives volume concentration among health-conscious millennials seeking portion-controlled fiber options. FDA nutrition labeling updates on added-sugar disclosure and revised serving sizes accelerate reformulation investments by domestic manufacturers. Minneapolis-St. Paul anchors production gravity for major branded portfolios, while California's Pacific Coast metropolitan markets concentrate highest per-unit premiums for organic-certified lines.
Germany
Clean-label literacy among consumers elevates demand for EFSA-verified health claims on soluble fiber cardiovascular benefits. EU Green Deal Farm-to-Fork sustainability audits impose traceability documentation costs that reshape supplier consolidation toward vertically integrated oat millers. Bavaria's food processing clusters around Munich host specialized bakery equipment manufacturers advancing steam-injection baking technology for fat-content compliance.
United Kingdom
Glycemic index awareness penetrates retail buyer decisions faster than continental Europe, displacing conventional low-fat claims with metabolic response certifications. Competition and Markets Authority scrutiny of environmental claims pressures substantiation standards for carbon footprint labeling. London's health food retail corridor and Manchester's specialty distribution hubs concentrate premium assortment curation for functional snacking missions.
Canada
Health Canada front-of-package nutrition symbol regulations accelerate category innovation toward reduced saturated fat thresholds. Cross-border supply chain integration with US milling operations exposes Prairie oat-growing regions to freight cost volatility and harvest quality fluctuations. Toronto-Waterloo corridor and Vancouver metropolitan area concentrate direct-to-consumer subscription channel development for fitness-oriented buyer segments.
France
ANSM and DGCCRF enforcement of nutritional claim substantiation elevates barrier-to-entry for imported low-fat baked goods without third-party testing documentation. Traditional patisserie culture creates hybrid demand for gourmet-positioned oatmeal cookies with artisan credentialing. Île-de-France retail networks and Lyon's food manufacturing basin concentrate reformulation R&D partnerships between bakery specialists and enzyme technology providers.
Low Fat Oatmeal Cookies Market Competitive Landscape
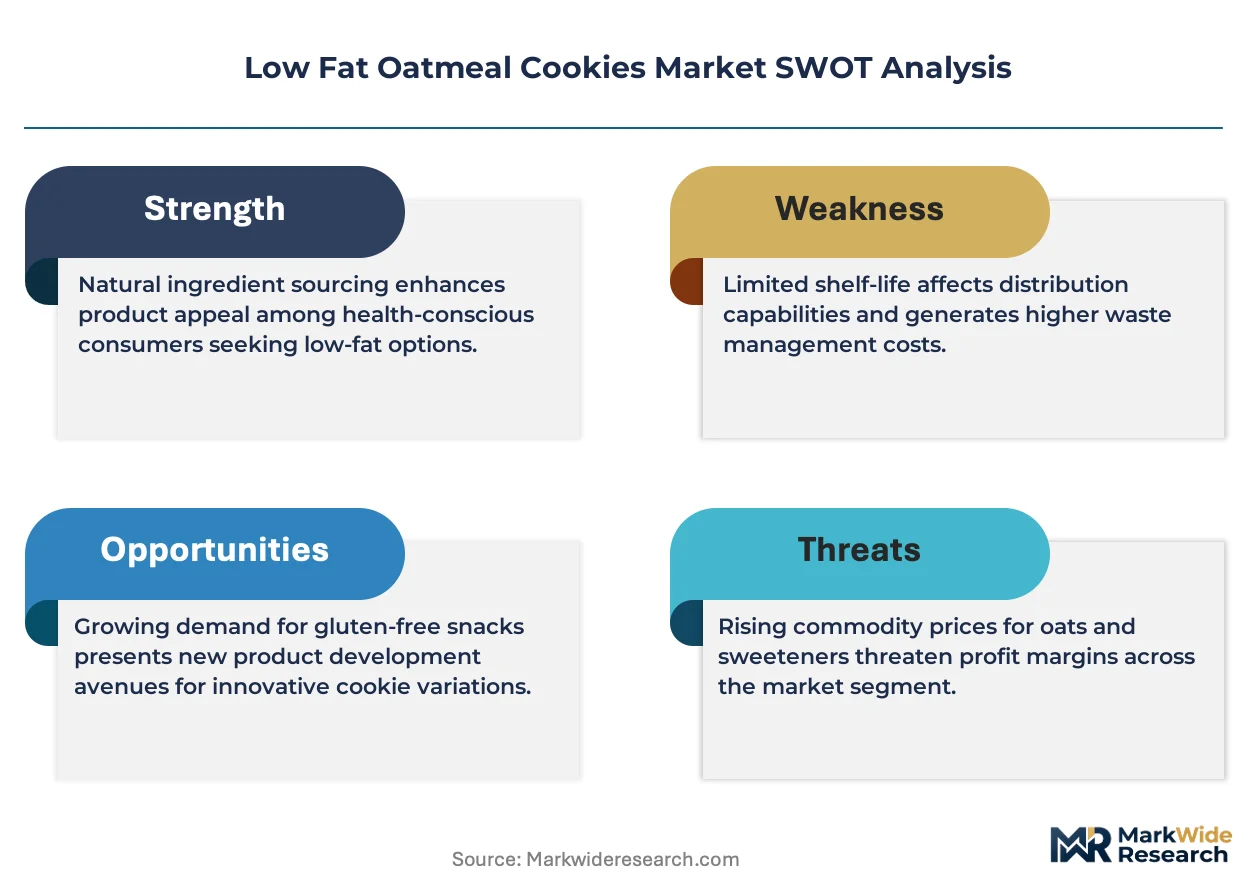
Capability concentration sits with legacy branded manufacturers possessing proprietary formulation archives; scale advantage sits with diversified food conglomerates with cross-category procurement leverage. The market structure tiers across three distinct competitive archetypes: multinational CPG portfolios with integrated oat supply chains, regional clean-label specialists with certification stacking expertise, and private-label programs leveraging enzymatic democratization of premium fiber ingredients. Dominant competitive moves include strategic partnerships with milling operations for supply security and portfolio diversification into adjacent functional snacking categories.
Within the multinational CPG tier, General Mills and Nestlé exemplify divergent defensive strategies against private-label encroachment, with the former leveraging decades-old formulation archives and the latter anchoring position through proprietary oat-milling partnerships. Mondelez International occupies a distinct premium-channel position through controlled glycemic index certifications that command shelf-space premiums in health-focused retail networks. These three companies represent the primary competitive anchors shaping category innovation pacing and certification investment thresholds across North American and European markets.
| Leading Market Players |
|---|
| General Mills |
| Nestlé |
| Conagra Brands |
| Mondelez International |
| PepsiCo |
| Kellogg Company |
| Kraft Heinz |
| Hain Celestial Group |
| Bob's Red Mill Natural Foods |
| Others |
Value Network & Pricing Analysis
Minneapolis-St. Paul milling clusters anchor North American oat processing capacity, with their throughput dynamics directly transmitting into downstream pricing power for premium fiber ingredients. FDA nutrition labeling updates and EU Green Deal traceability mandates are compressing margin structures for manufacturers lacking captive supply arrangements or long-term offtake coverage.
Pricing Analysis
Long-term offtake contracts between major branded portfolios and proprietary oat-milling partnerships dominate upstream procurement, insulating volume buyers from spot-market volatility in milling-grade oats. Three-tier pricing structure across organic-certified, non-GMO verified, and conventional supply tiers reflects certification cost pass-through and consumer willingness-to-pay stratification. Cost compression in the conventional tier is intensifying as enzymatic processing democratizes beta-glucan concentration previously requiring premium partnerships. Corporate wellness program procurement demonstrates lowest price sensitivity, while mass-market supermarket channels compete most aggressively on per-unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized bakery equipment manufacturers advancing steam-injection oven technology, particularly around Munich and Bavaria's food processing clusters. Premium milling-grade oat procurement draws from North American Prairie regions and Nordic growing areas, with dependency on weather-driven harvest quality and freight cost fluctuations. Single-source vulnerability concentrates in proprietary oat-milling partnerships that lock competitors out of premium beta-glucan supply streams. Distribution runs through health food stores and specialty shops for highest-margin tiers, while online retail subscription models bypass wholesale markups for direct margin recovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is materializing through subscription-direct distribution ecosystems that capture recurring revenue and first-party consumption data for reformulation targeting. Interoperability between enrollment-based corporate wellness procurement and personalized nutrition platforms is reshaping buyer access patterns.
For Market Incumbents: Build formulation archive moats by licensing decades-old recipe IP to private-label manufacturers seeking rapid clean-label credibility. Deepen backward integration into oat-milling operations to secure premium beta-glucan supply streams against enzymatic democratization threats. Invest in controlled glycemic index certification capabilities to defend shelf-space premiums in health-focused retail channels as conventional low-fat claims lose differentiation power. For New Entrants and Emerging Players: Establish a beachhead in the diabetic consumer segment through glycemic response testing documentation that meets FDA added-sugar disclosure precision requirements. Target direct-to-consumer subscription channels for fitness enthusiast segments seeking macro-nutrient customization, where recurring revenue density offsets customer acquisition costs. Leverage enzymatic oat processing partnerships to achieve premium fiber concentration without proprietary milling investments. For Investors and Strategic Acquirers: Long-term, this sits as a certification-stacking consolidation play because organic, non-GMO, and glycemic index verification costs are concentrating advantage with scaled players capable of absorbing fixed compliance burdens. Acquisition targets should demonstrate integrated ERP systems for EU Green Deal traceability documentation and batch-level carbon footprint reporting. Watch EFSA soluble fiber cardiovascular health claim approvals as the signal for premium positioning feasibility in European retail networks.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Oat-Milling Partnership | Secures premium beta-glucan supply streams against enzymatic processing democratization. |
| Controlled Glycemic Index Certification | Commands shelf-space premiums in California and Pacific Northwest health food retail corridors. |
| Subscription-Direct Distribution Launch | Captures recurring revenue density from fitness enthusiasts seeking macro-customization. |
| Clean-Label Reformulation Investment | Accelerates R&D pipelines around FDA nutrition labeling transparency requirements. |
| EU Green Deal Traceability Compliance | Enables batch-level carbon footprint reporting for European retail buyer consolidation. |
Research Methodology
Cross-validation between primary interviews with category buyers, formulation chemists, and corporate wellness program procurement officers anchors the qualitative findings against secondary validation from FDA labeling guidance documents, USDA organic certification databases, and Nielsen retail audit data. Bottom-up triangulation across ingredient sourcing cost structures and top-down assessment of branded portfolio revenue disclosures calibrate market sizing estimates. EFSA health claim verification records and EU Farm-to-Fork strategy implementation reports provide European regulatory context.
Calibration against historical CAGRs from adjacent functional snacking categories and elasticity modeling across price-tier transitions inform the projection framework throughout the forecast period. Segmentation dimensions modeled include product texture format, certification tier, distribution channel economics, and consumer health motivation intensity. CAGRs derive from regression analysis against corporate wellness program enrollment trajectories and soluble fiber health claim approval timelines. Steam-injection baking technology adoption curves and enzymatic processing penetration rates serve as industry-specific forecast inputs.
Sensitivities concentrate around oat harvest volatility in Prairie and Nordic growing regions, EFSA health claim approval delays, and corporate wellness program budget reallocations. Forecasts reflect documented assumptions regarding certification cost trajectories and subscription channel retention benchmarks. Cross-checking against IRI/Circana retail velocity data and customs records for oat ingredient trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bakery Cases Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Wedding Cakes Market
Bakery Products
Bakery Premixes Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Bread and Baked Food Market
Bakery Products
US Retail Packaged Bread Market
Bakery Products
Baked Foods Market
Bakery Products
Bakery Fats Market
Bakery Products
North America Fortified Bakery Products Market
Bakery Products
Latin America Frozen Bakery Market