
 Cookie Pucks Market | 2026-2036
Cookie Pucks Market Size, Share, and Industry Trends Forecast 2026-2036
Cookie Pucks Market Outlook
Recurring frozen dough subscription programs is shifting how commercial bakeries manage inventory cycles and forecast weekly throughput. Dawn Foods leverages its North American distribution network to anchor supply contracts with regional bakery chains. CSM Bakery Solutions differentiates through technical service teams that reformulate base doughs for regional humidity conditions. Nestlé competes by extending its retail frozen dessert logistics infrastructure into foodservice cookie puck fulfillment.
Cookie pucks are pre-portioned, frozen or chilled disks of cookie dough, typically ranging from 1.5 to 3 ounces in unit weight, designed for direct-to-oven baking without thawing or scaling. Manufacturers form these units through extrusion or rotary molding, then blast-freeze them to preserve leavening integrity and inhibit pathogen proliferation across extended distribution chains. Frozen product type dominates current volume owing to its compatibility with foodservice batch workflows and extended holding periods, while gluten-free variants occupy the fastest-expanding margin pool as allergen-free ingredient premiums sustain higher price points. Chocolate chip flavor profile leads absolute consumption across institutional channels, though peanut butter formulations attract concentrated demand from K-12 nutrition programs seeking protein-forward dessert options.
The FDA's Food Safety Modernization Act mandates preventive controls and supply chain verification for ready-to-bake frozen dough, compelling processors to validate kill-step equivalency in customer ovens. USDA organic certification and Non-GMO Project verification now function as gatekeeping credentials for placement in premium retail and contract foodservice channels. Stakeholders must monitor how state-level extended producer responsibility legislation for food packaging reshapes material specifications for individually wrapped pucks before committing to multi-year equipment investments.
Market Dynamics
Frozen dough subscription programs are compressing inventory cycles for commercial bakeries while the FDA's Food Safety Modernization Act traceability rules force serialized lot tracking investments across the supply chain.
Growth Catalysts
- FSMA Section 204:The FDA's enhanced traceability mandates drive processors to adopt blockchain-enabled serialization, expanding demand for integrated dough management systems in United States foodservice chains.
- Quick-service restaurant centralization:National procurement agreements through distributors like Sysco and US Foods standardize frozen dough specifications across multi-unit operators, consolidating vendor relationships.
- Blast-freezing technology:Cryogenic tunnel systems preserve leavening integrity during extended distribution, enabling cross-country fulfillment without quality degradation for regional bakery chains.
Market Restraints
- Butter and egg input volatility:Commodity dairy and egg price swings compress margin predictability for processors locked into annual foodservice contracts with fixed pricing terms.
- Midwest production concentration:Frozen dough manufacturing clusters heavily in Wisconsin, Illinois, and Minnesota, creating weather-related supply disruption exposure and logistics bottlenecks during peak winter demand.
- Convection oven kill-step variability:Inconsistent heat distribution across customer equipment complicates pathogen validation protocols, limiting expansion into smaller independent bakeries without technical service support.
Strategic Opportunities
- K-12 nutrition programs:Protein-forward peanut butter formulations attract concentrated institutional demand as USDA school meal pattern requirements emphasize nutrient density in dessert components.
- Gluten-free certification premiums:Non-GMO Project verification and certified gluten-free labeling unlock placement in premium retail channels and contract healthcare foodservice, sustaining higher price points per puck.
- Direct-to-oven automation:Robotic depanning and loading systems converging with frozen dough formats enable labor reduction in high-volume commercial bakeries seeking throughput optimization.
Industry Challenges
- Preventive controls qualified individual shortage:FSMA-mandated PCQI certification requirements outpace training program capacity, creating compliance bottlenecks for mid-sized processors expanding production lines.
- Extended producer responsibility packaging mandates:State-level legislation in California, Oregon, and Washington forces rapid material specification shifts for individually wrapped pucks before equipment depreciation cycles complete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cookie Pucks Market |
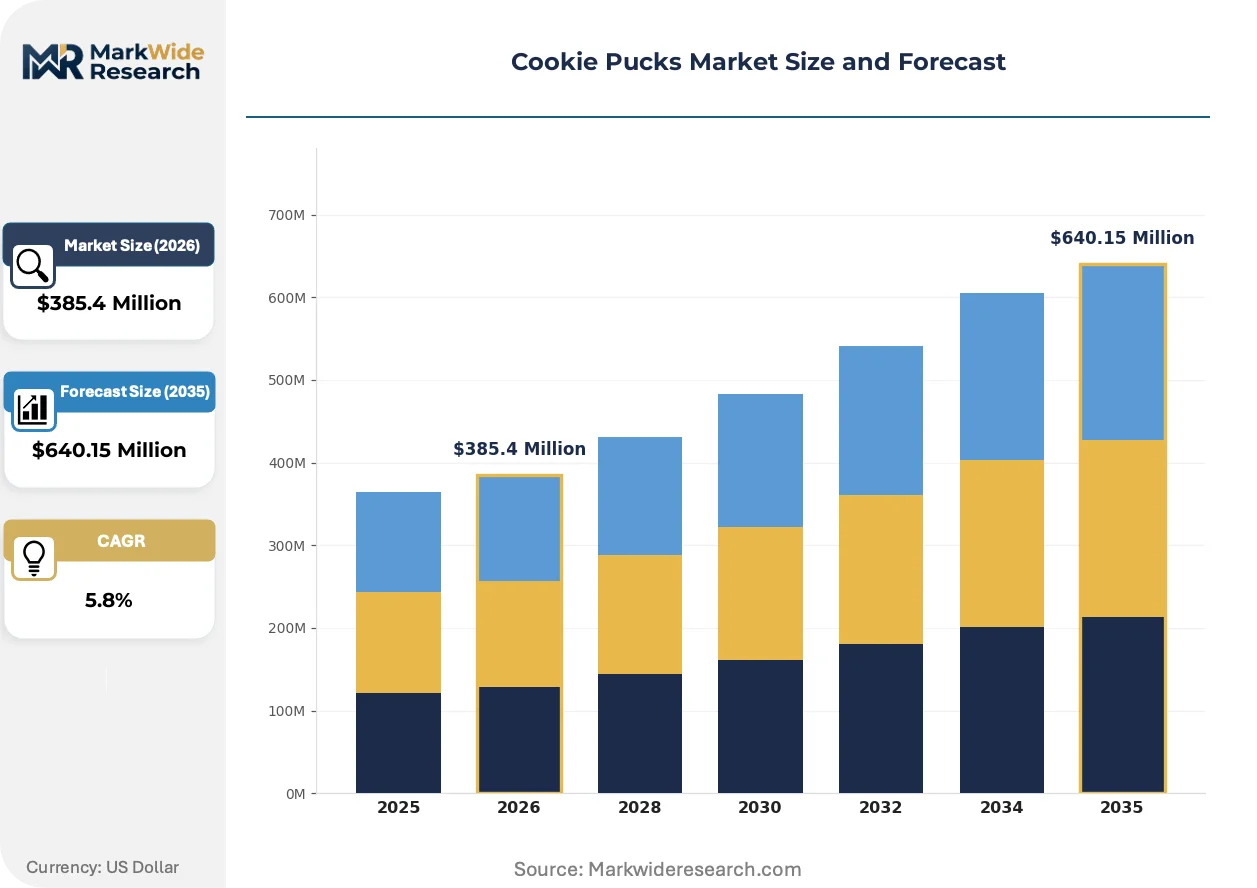
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilled, Frozen, Shelf-Stable, Gluten-Free Flavor Profile: Chocolate Chip, Oatmeal Raisin, Peanut Butter, Double Chocolate Target Audience: Children, Adults, Health-Conscious Consumers, Vegan Shoppers Packaging Type: Individual Packs, Bulk Boxes, Eco-Friendly Bags, Resealable Containers |
| Companies Covered | Dawn Foods, CSM Bakery Solutions, General Mills, Nestlé, Conagra Brands, Grupo Bimbo, Brakers Ltd., Sweet Street Desserts, Rubicon Bakers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cookie Pucks Market Strategic Shifts
Automation and regulatory serialization are compressing operational timelines while reformulation science opens new allergen-free positioning corridors for premium market tiers.
Cryogenic individual quick freezing is rewriting throughput economics for high-volume processors. Commercial bakeries operating 24-hour production schedules adopt IQF tunnel systems to eliminate thaw-to-bake lag time. The technology is rewriting batch size flexibility, enabling same-day flavor changeovers that were previously uneconomical.
The FDA's Food Safety Modernization Act Section 204 traceability rule mandates granular lot tracking from ingredient receipt through finished goods distribution. Processors must validate kill-step equivalency documentation across customer oven configurations. Quick-service chains with national footprints face the steepest compliance costs as they retrofit legacy procurement systems.
Subscription-based frozen dough replenishment is consolidating procurement authority within centralized bakery commissaries. Regional bakery chains replace spot purchasing with scheduled delivery programs that synchronize weekly throughput forecasts with distributor inventory. This pattern concentrates most visibly in the United States, where foodservice procurement teams negotiate multi-year supply agreements through group purchasing organizations.
Cookie Pucks Market Segmentation
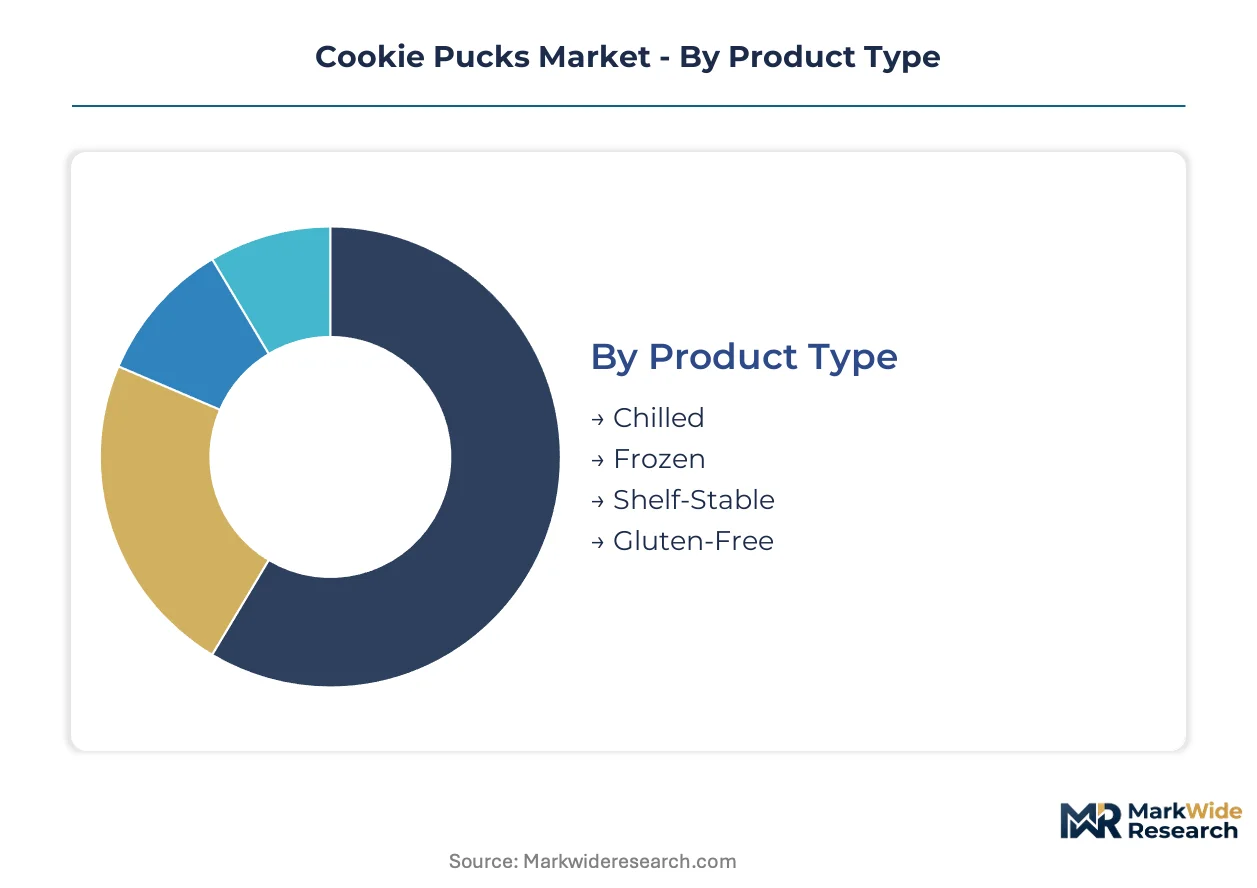
Cookie puck segmentation reveals how processors balance operational standardization against the customization demands of distinct channels. Each dimension carries procurement implications that reshape vendor selection criteria and contract structures across foodservice and retail.
Product Type:
The customization-vs-standardization spectrum spans from commodity frozen formats to precision-engineered allergen-free variants requiring dedicated production lines.
- Frozen:Blast-frozen units between 1.5 and 3 ounces dominate foodservice throughput. Quick-service restaurants in the United States centralize procurement through Sysco and US Foods for direct-to-oven workflows without thaw stages.
- Gluten-Free:Certified formulations command ingredient premiums and dedicated facility segregation. Healthcare foodservice contracts and premium retail placement in California and Oregon sustain higher price points through Non-GMO Project verification.
- Chilled:Shorter shelf life limits distribution radius to regional bakery commissaries within 500 miles of production.
- Shelf-Stable:Retort packaging extends holding periods for emergency feeding programs and military procurement.
Leading the category by volume: Frozen. Growing fastest: Gluten-Free.
Flavor Profile:
Cost tier stratification separates institutional commodity contracts from premium positioning through ingredient provenance and formulation complexity.
- Chocolate Chip:The baseline formulation across K-12 nutrition programs and quick-service dessert menus. USDA school meal pattern compliance and consistent cocoa supply chains anchor volume procurement in the United States.
- Peanut Butter:Protein-forward positioning captures institutional demand as USDA emphasizes nutrient density. Wisconsin and Illinois production clusters serve Midwest school districts with validated kill-step documentation.
- Oatmeal Raisin:Whole-grain credentials appeal to healthcare foodservice seeking fiber-forward dessert options.
- Double Chocolate:Premium cocoa butter content targets specialty coffee chains and boutique bakery channels.
Dominating procurement contracts: Chocolate Chip. Expanding most quickly: Peanut Butter.
Target Audience:
Application focus determines formulation priorities from clean-label ingredient decks to fortified nutrient profiles.
- Health-Conscious Consumers:Reduced-sugar and whole-grain formulations drive reformulation investment. FDA Nutrition Facts panel updates and front-of-package labeling requirements in California shape ingredient declarations.
- Children:Portion-controlled 1.5-ounce units align with USDA Child and Adult Care Food Program serving specifications.
- Adults:Indulgence positioning through premium inclusions and artisan flavor profiles.
- Vegan Shoppers:Plant-based fat systems and egg replacers require separate processing equipment and allergen cleaning protocols.
Commanding formulation R&D spend: Health-Conscious Consumers. Gaining share fastest: Vegan Shoppers.
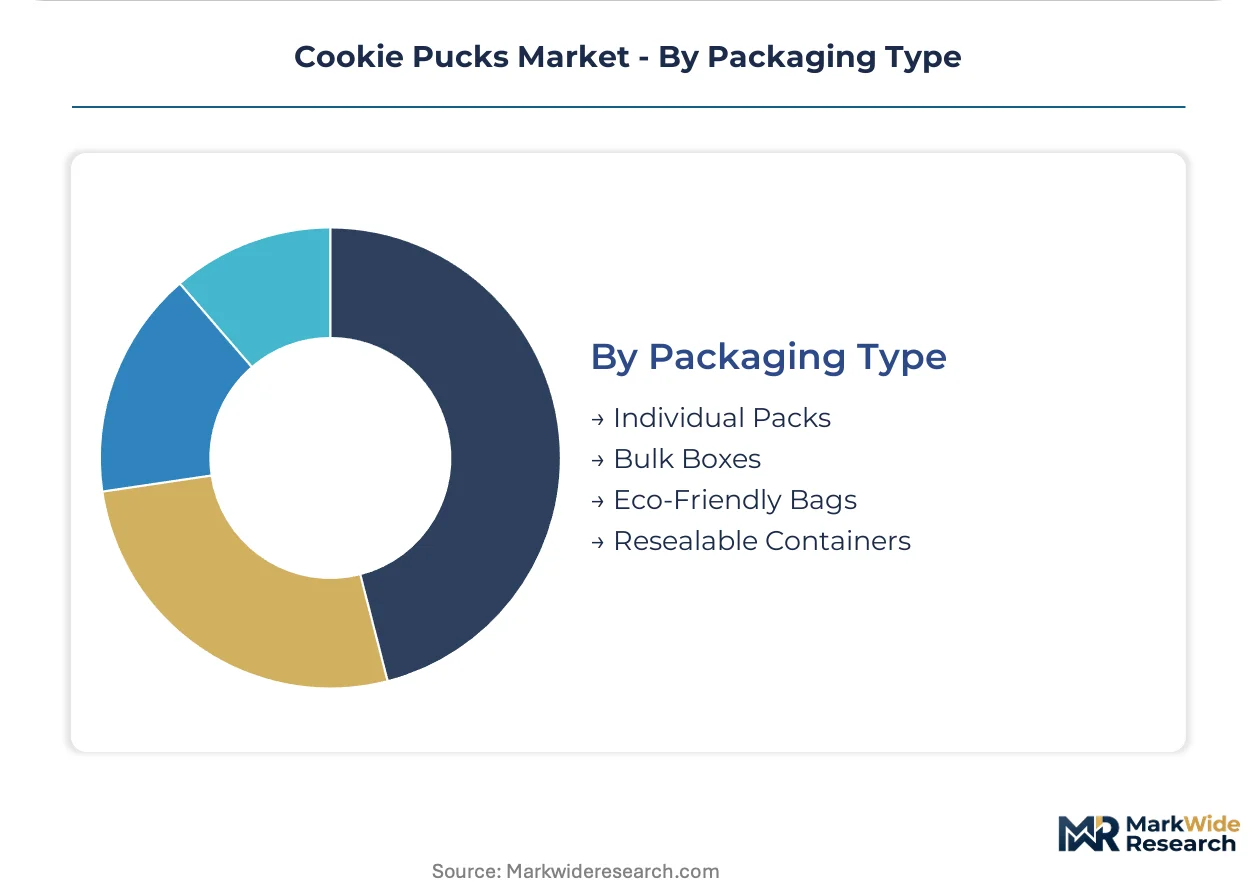
Packaging Type:
Customer type segmentation separates high-velocity foodservice operations from retail channels demanding extended shelf presence and sustainability credentials.
- Bulk Boxes:50-pound corrugated cases serve commercial bakeries with automated depanning systems. National distribution agreements through US Foods and Sysco standardize case counts for pallet optimization.
- Eco-Friendly Bags:Compostable films and reduced-plastic structures respond to California, Oregon, and Washington extended producer responsibility mandates.
- Individual Packs:Single-serve portions target convenience retail and vending channels.
- Resealable Containers:Multi-serve formats for club store placement and home freezer storage.
Anchoring foodservice procurement: Bulk Boxes. Facing steepest specification pressure: Eco-Friendly Bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest production clusters in Wisconsin and Illinois generate frozen dough supply, while consumption concentrates in coastal foodservice corridors and institutional procurement networks across distinct national markets.
United States
Quick-service restaurant chains centralize procurement through Sysco and US Foods distribution agreements. The FDA's Food Safety Modernization Act Section 204 mandates blockchain-enabled traceability from ingredient receipt through finished goods. Wisconsin and Illinois manufacturing hubs serve national foodservice accounts with validated kill-step documentation for direct-to-oven workflows.
Germany
Commercial bakery automation drives demand for precision-portioned frozen dough units compatible with robotic loading systems. The EU Green Deal packaging requirements accelerate compostable film adoption for individually wrapped pucks. Bavaria-based equipment manufacturers supply cryogenic tunnel freezing systems to processors across Central Europe.
Canada
Healthcare foodservice contracts in Ontario and Quebec prioritize certified gluten-free formulations for patient dietary programs. Health Canada allergen labeling regulations enforce strict facility segregation protocols for allergen-free production lines. Toronto-area distribution centers coordinate cross-border fulfillment to US institutional accounts.
United Kingdom
Premium coffee chains and boutique bakery channels demand artisan flavor profiles with provenance credentials. The Food Standards Agency enforces enhanced traceability for ready-to-bake frozen dough imports post-Brexit. Greater London commissaries consolidate procurement authority through scheduled replenishment programs replacing spot purchasing.
France
Specialty dessert channels in Île-de-France emphasize premium cocoa butter content and regional ingredient sourcing. ECHA REACH regulations govern emulsifier and preservative approvals in frozen dough formulations. Lyon-based technical service teams reformulate base doughs for humidity conditions across Mediterranean and Atlantic climate zones.
Cookie Pucks Market Competitive Environment
Top-tier vendors anchor national distribution networks, while mid-tier specialists compete through technical service differentiation and regional formulation expertise. The market structure reflects consolidation around multi-unit foodservice procurement authority, with fragmentation persisting in artisan and allergen-free niches. Strategic archetypes include integrated ingredient-to-dough processors, pure-play frozen dough specialists, and diversified food manufacturers extending dessert logistics infrastructure. Dominant competitive moves encompass backward integration into captive ingredient supply and geographic expansion through distributor partnership tiers.
Among North American-based processors, Dawn Foods, CSM Bakery Solutions, and Nestlé occupy positions reflecting distinct strategic vectors. Dawn Foods exemplifies the distribution-anchored archetype through supply contract relationships with regional bakery chains. CSM Bakery Solutions represents the technical-service-differentiated model with reformulation capabilities for environmental conditions. Nestlé sits within the diversified-manufacturer tier, extending retail frozen dessert logistics infrastructure into foodservice fulfillment channels.
| Leading Market Players |
|---|
| Dawn Foods |
| CSM Bakery Solutions |
| General Mills |
| Nestlé |
| Conagra Brands |
| Grupo Bimbo |
| Brakers Ltd. |
| Sweet Street Desserts |
| Rubicon Bakers |
| Others |
Value Chain & Pricing Dynamics
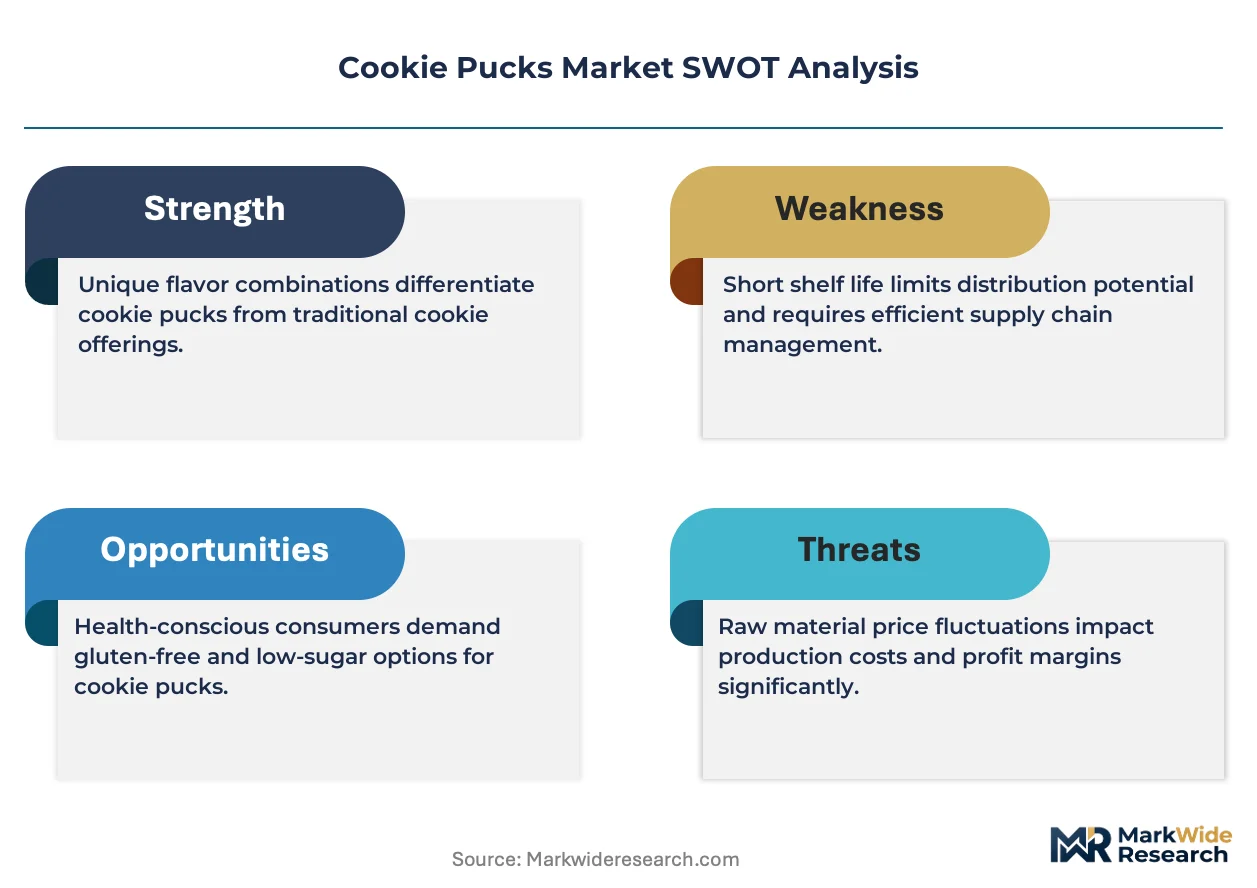
Butter and egg commodity volatility cascades through frozen dough pricing tiers, compressing margins for processors locked into annual foodservice contracts while rewarding operators with backward integration into captive dairy supply. This input-cost architecture stratifies the market into premium allergen-free tiers, standard frozen formats, and economy private-label channels.
Pricing Analysis
Margin tightening in standard frozen tiers reflects butter futures volatility and fixed-price annual contracts with quick-service chains. Three-tier pricing structure across premium certified-gluten-free, standard foodservice, and economy private-label levels separates buyers by certification investment and volume scale. Price differentiation hinges on Non-GMO Project verification and dedicated facility segregation for allergen-free production. Cost-down pressure on economy tiers accelerates because retail private-label buyers demand parity with branded unit economics.
Supply Chain Analysis
Dairy supply rests on Wisconsin, Illinois, and Minnesota production clusters where butter and egg processing concentrates. Frozen dough manufacturing draws from regionally sourced creamery butter, cage-free egg pools, and specialty wheat flour milled in the upper Midwest. Single-source vulnerability emerges from weather-related disruption exposure across these northern-tier states during peak winter demand periods. Distribution runs through Sysco and US Foods national networks for foodservice accounts, with direct regional bakery commissary replenishment for chilled formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cookie pucks market sits at a technology-transition inflection where cryogenic individual quick freezing displaces legacy blast-freezing workflows, rewriting throughput economics and batch flexibility for commercial bakeries.
For Market Incumbents: Anticipate margin compression from commodity dairy volatility by securing multi-year butter supply agreements with upper Midwest creameries. Incumbent processors must accelerate blockchain-enabled lot tracking investments ahead of FDA Food Safety Modernization Act Section 204 enforcement deadlines to defend national foodservice contract positions against technical-service-specialist competitors. For New Entrants and Emerging Players: Capture white-space opportunity in certified gluten-free production for healthcare foodservice contracts in California and Oregon, where extended producer responsibility packaging mandates and Non-GMO Project verification create dual certification barriers. New entrants should pursue direct-to-oven automation partnerships with commercial bakery equipment manufacturers as the primary go-to-market channel. For Investors and Strategic Acquirers: FDA Section 204 compliance investment announcements from multi-unit quick-service chains are the leading indicator that traceability-capable processors will command acquisition premiums. The five-to-ten-year viability window favors mid-tier frozen dough specialists with existing PCQI-certified production lines and regional distributor relationships as consolidation targets. Watch for state-level extended producer responsibility legislation passage as the signal triggering rapid packaging specification shifts and equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic IQF Technology Deployment | Rewrites batch economics for 24-hour commercial bakery operations seeking flavor-changeover flexibility. |
| Blockchain Traceability Integration | Validates kill-step documentation across customer oven configurations for FDA FSMA Section 204 compliance. |
| Backward Integration into Dairy Supply | Secures captive butter and egg inputs against commodity volatility compressing fixed-contract margins. |
| Gluten-Free Facility Segregation | Unlocks healthcare foodservice placement and premium retail channels through Non-GMO Project verification. |
| Subscription-Based Replenishment Programs | Consolidates procurement authority within centralized bakery commissaries replacing spot purchasing patterns. |
Study Parameters
USDA commodity price databases, FDA FSMA guidance documents, and foodservice distributor procurement records formed the secondary backbone, cross-referenced with primary interviews across frozen dough plant managers, quick-service chain procurement directors, commercial bakery operations heads, and regional distributor category managers. Bottom-up unit volume estimates triangulated against top-down foodservice spending allocation models.
Top-down market sizing anchored in national foodservice procurement patterns segmented by product type, flavor profile, target audience, and packaging format across the projection horizon. CAGRs derived from trend extrapolation of frozen dough subscription program adoption rates and cryogenic freezing technology penetration curves, with gluten-free certification premiums and K-12 nutrition program contract volumes as industry-specific demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to butter commodity volatility, state-level packaging mandate timing, and PCQI training program capacity constraints. A small set of named triggers—including FDA enforcement action dates and extended producer responsibility legislation passage—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Salad Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Instant Ramen Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
Canned Food Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Dried Honey Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Europe Ready-To-Eat Food Market