
 Europe Sweet Biscuits Market | 2026-2036
Europe Sweet Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sweet Biscuits Market Foresight
Single-serve and multipack bundling is repositioning how European households buy sweet biscuits, shifting volume from bulk pantry stock toward impulse and lunchbox formats. Mondelez International leverages its continental manufacturing scale to dominate this configuration tier. Lotus Bakeries NV anchors its growth in premium branded multipacks across Benelux and France. Bahlsen GmbH & Co. KG competes through heritage-positioned seasonal bundling that sustains price premiums in German retail.
Europe sweet biscuits comprise wheat-flour-based baked goods containing added sugars, fats, and flavoring agents, typically achieving moisture content below five percent through controlled baking to ensure shelf stability and crisp texture; their primary commercial purpose is packaged snack consumption across retail and foodservice channels. Chocolate cookies command the largest revenue pool due to ingredient cost pass-through and brand loyalty, while cream-filled biscuits generate higher per-unit margins through indulgence positioning. Online retail represents the fastest-growing distribution channel as fulfillment networks improve ambient-grocery logistics and subscription models gain traction among repeat buyers.
EFSA front-of-pack nutrition labeling requirements and EU Green Deal packaging regulations are reshaping formulation and material choices, pushing manufacturers toward reduced-sugar recipes and recyclable mono-material wrappers. REACH compliance on food-contact substances adds testing burdens that favor larger producers with dedicated regulatory affairs capacity. Stakeholders must monitor how EUDR deforestation due diligence rules affect palm oil and cocoa sourcing costs across their supplier bases.
Market Dynamics
EU Green Deal packaging mandates and EFSA front-of-pack nutrition labeling rules are compressing formulation flexibility while forcing simultaneous capital deployment into sustainable packaging lines and recipe reformulation labs.
Growth Catalysts
- EFSA Nutri-Score alignment:Manufacturers accelerating reduced-sugar recipe development capture shelf space in French and Belgian retail banners where front-of-pack scoring influences placement.
- Portion-controlled formats:Lunchbox-oriented multipacks penetrate German and UK household purchasing cycles, converting bulk pantry buyers into higher-frequency snack purchasers.
- Mono-material flexible films:Polypropylene-based recyclable wrappers replace multi-layer laminates, satisfying EU Green Deal recyclability targets without compromising moisture barriers.
Market Restraints
- Cocoa butter price volatility:West African supply concentration and EUDR due diligence requirements inflate chocolate cookie input costs unpredictably.
- REACH food-contact testing burdens:Migration testing for new packaging chemistries extends product launch timelines by 8-14 months for mid-tier producers lacking dedicated regulatory affairs teams.
- Fresh bakery substitution:In-store bakery cookie counters at German and UK grocery chains capture impulse occasions previously reserved for packaged biscuits.
Strategic Opportunities
- Polish and Romanian modern trade expansion:Discount retail format growth in Warsaw and Bucharest creates first-mover advantage for private-label biscuit suppliers with localized flavor portfolios.
- Subscription ambient-grocery models:D2C replenishment platforms bypass traditional wholesale markups, capturing repeat purchase data from UK and Netherlands urban households.
- EUDR-compliant cocoa sourcing:Early certification investments secure supply chain preferencing as deforestation due diligence rules tighten traceability requirements.
Industry Challenges
- Reformulation R&D talent scarcity:Sugar reduction expertise combining bakery science with clean-label ingredient functionality concentrates at a handful of continental research institutes.
- Legacy oven energy retrofit costs:Converting thermal baking lines to hybrid electric-gas configurations demands capital outlays that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sweet Biscuits Market |
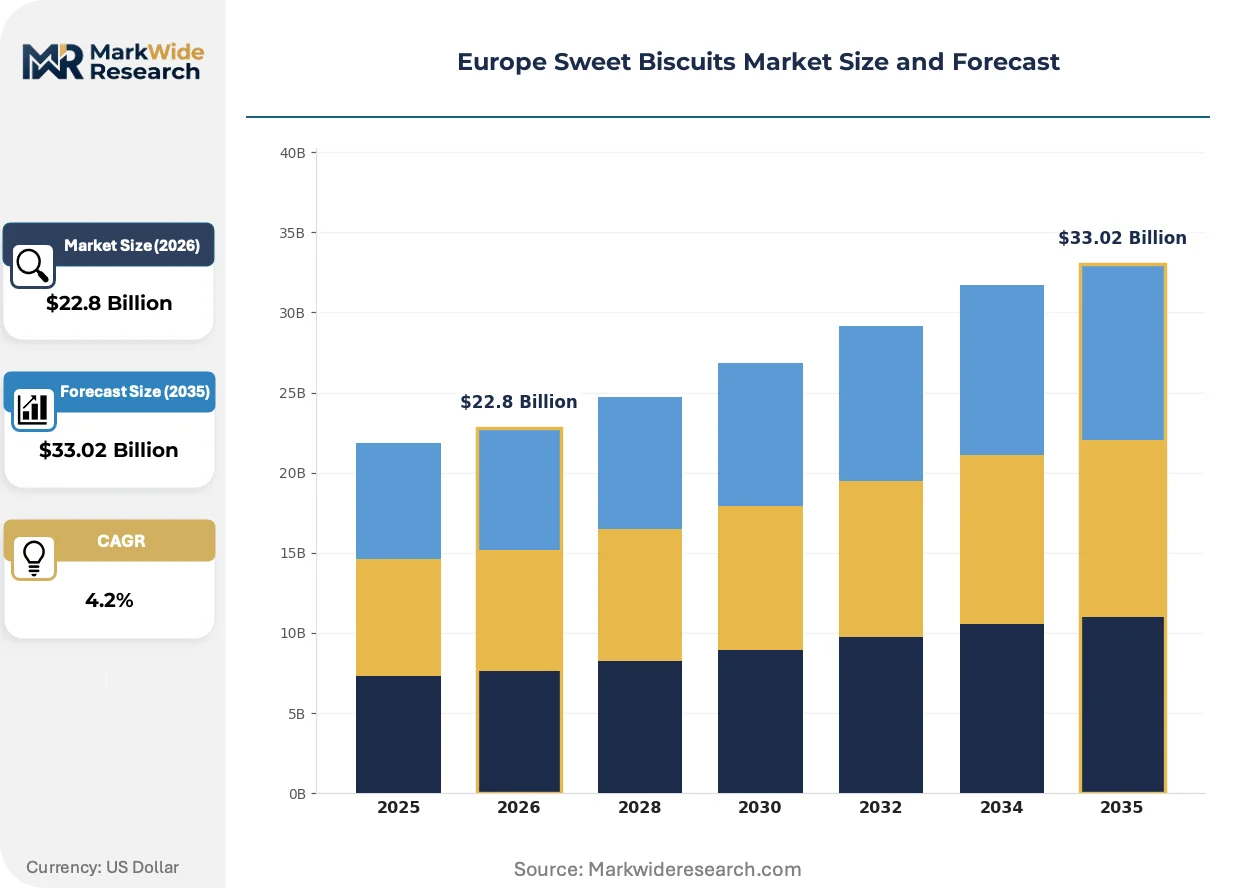
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $33.02 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Cookies, Cream-Filled Biscuits, Shortbread, Digestive Biscuits Packaging Type: Box, Wrapper, Tray, Bag Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Customer Type: Retail Consumers, HoReCa, Wholesalers, Distributors |
| Companies Covered | Lotus Bakeries NV, Bahlsen GmbH & Co. KG, Nestle SA, Pladis, Walkers Shortbread Ltd, Mondelez International, Burton's Biscuits Company, Kellanova, United Biscuits, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sweet Biscuits Market Shifts & Advancements
Reformulation chemistry and packaging material science are converging to resolve the tension between shelf-life performance and sustainability compliance, reshaping how European manufacturers allocate R&D resources.
Enzymatic sugar reduction technology is expanding into mainstream production lines. Dutch and Belgian producers deploy amylase and invertase systems to maintain Maillard browning and texture in 30% reduced-sugar recipes. This enzymatic approach is expanding into private-label manufacturing, compressing the cost gap between premium health-positioned and standard formulations.
EU Green Deal packaging regulations now mandate recyclable mono-material structures by 2030. Flexible packaging converters accelerate polypropylene and polyethylene film development to replace aluminum-oxide barrier layers. Biscuit categories with shorter shelf-life requirements, including seasonal specialties, are converting first due to less demanding moisture protection needs.
Digital shelf-edge integration is altering retail negotiation dynamics. Major UK and German grocers now require suppliers to fund electronic price-tag infrastructure in exchange for promotional placement. This shifts margin extraction toward data-rich category captains capable of real-time promotional elasticity modeling, disadvantaging smaller heritage brands with limited analytics investment.
Europe Sweet Biscuits Market Segmentation
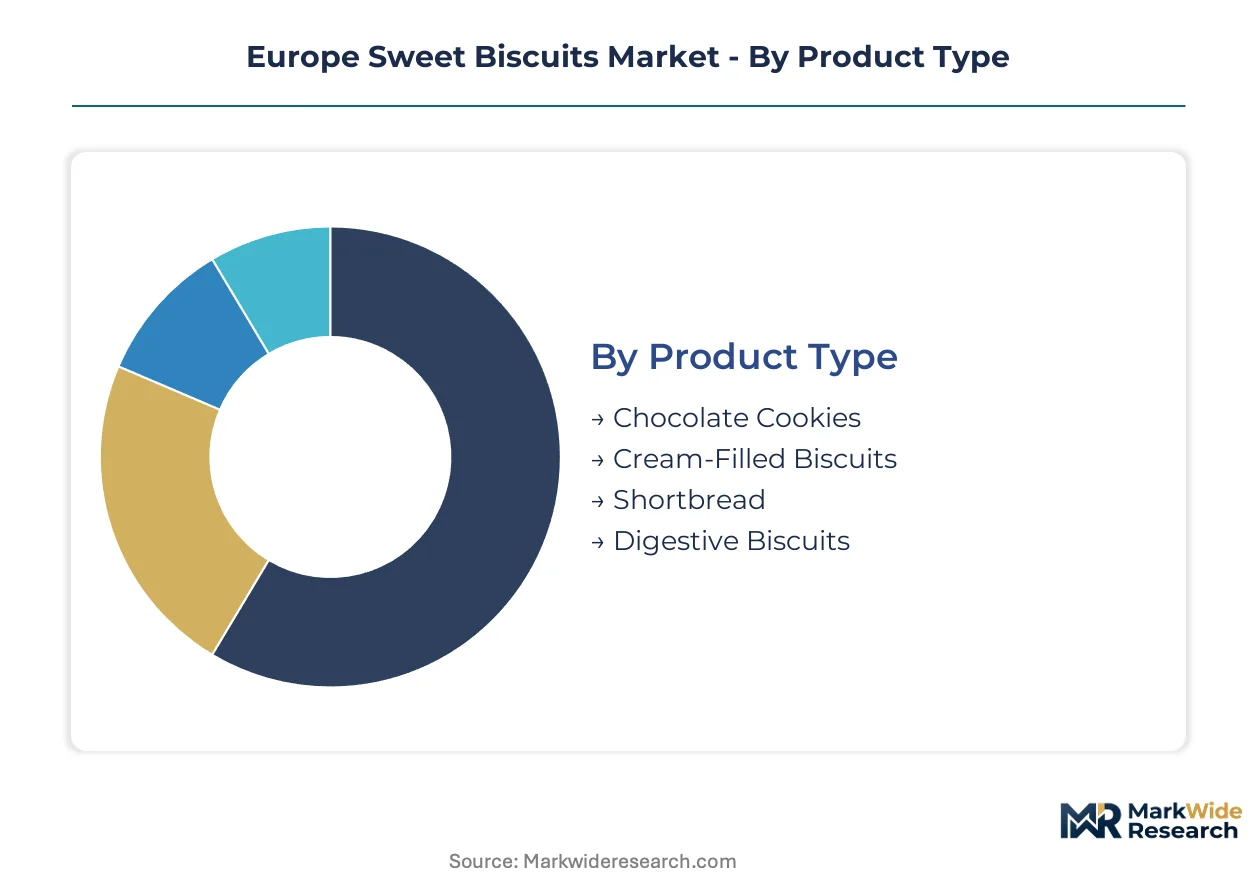
Sweet biscuit manufacturers configure production lines around moisture sensitivity and impulse-purchase mechanics. Segmentation choices determine capital allocation between continuous baking systems and seasonal changeover flexibility.
Product Type:
Standardization dominates commodity segments while premium tiers demand recipe customization and ingredient provenance documentation.
- Chocolate Cookies:Cocoa butter and chocolate mass formulations achieve moisture content below four percent through extended baking cycles. German and UK retail banners concentrate volume here, though cocoa price volatility under EUDR compliance rules compresses margin predictability.
- Cream-Filled Biscuits:Sandwich construction with fat-based fillings requires controlled humidity environments post-baking to prevent moisture migration. French and Belgian consumers sustain per-unit premiums through indulgence positioning and portion-controlled multipack formats.
- Shortbread:High butter-ratio recipes command heritage pricing in Scottish and Irish retail channels.
- Digestive Biscuits:Wholemeal wheat bases with reduced-sugar positioning align with EFSA Nutri-Score preferences in health-oriented retail banners.
Most installed capacity flows through Chocolate Cookies. Expansion is steepest in Cream-Filled Biscuits.
Packaging Type:
Cost tier separation maps directly to shelf-life requirements and retail channel mechanics.
- Wrapper:Flexible mono-material films now replace multi-layer laminates under EU Green Deal mandates. Polypropylene barriers satisfy recyclability targets while maintaining moisture protection for standard shelf-life products.
- Box:Rigid paperboard structures support gift-oriented and seasonal premium positioning. UK and German grocers demand box formats for promotional display placement during Q4 purchasing cycles.
- Tray:Thermoformed PET or PP containers protect fragile cream-filled constructions through distribution.
- Bag:Pillow pouches serve bulk pantry stock formats with lower unit economics.
Wrapper formats absorb the majority of production line investment. Box formats are climbing the fastest as premiumization accelerates.
Distribution Channel:
Customer acquisition cost and replenishment frequency determine channel prioritization.
- Supermarkets:Category captain negotiations dominate shelf placement. Real-time promotional elasticity modeling now determines margin extraction capability.
- Online Retail:Ambient-grocery logistics improvements and subscription replenishment models capture repeat purchase data. Netherlands and UK urban households drive adoption here.
- Convenience Stores:Impulse-oriented single-serve and small multipack formats penetrate lunchbox and travel occasions.
- Specialty Shops:Curated heritage and artisan positioning sustains price premiums in Benelux and French urban centers.
Supermarkets retain the largest volume throughput. Online Retail is expanding most quickly as fulfillment networks mature.
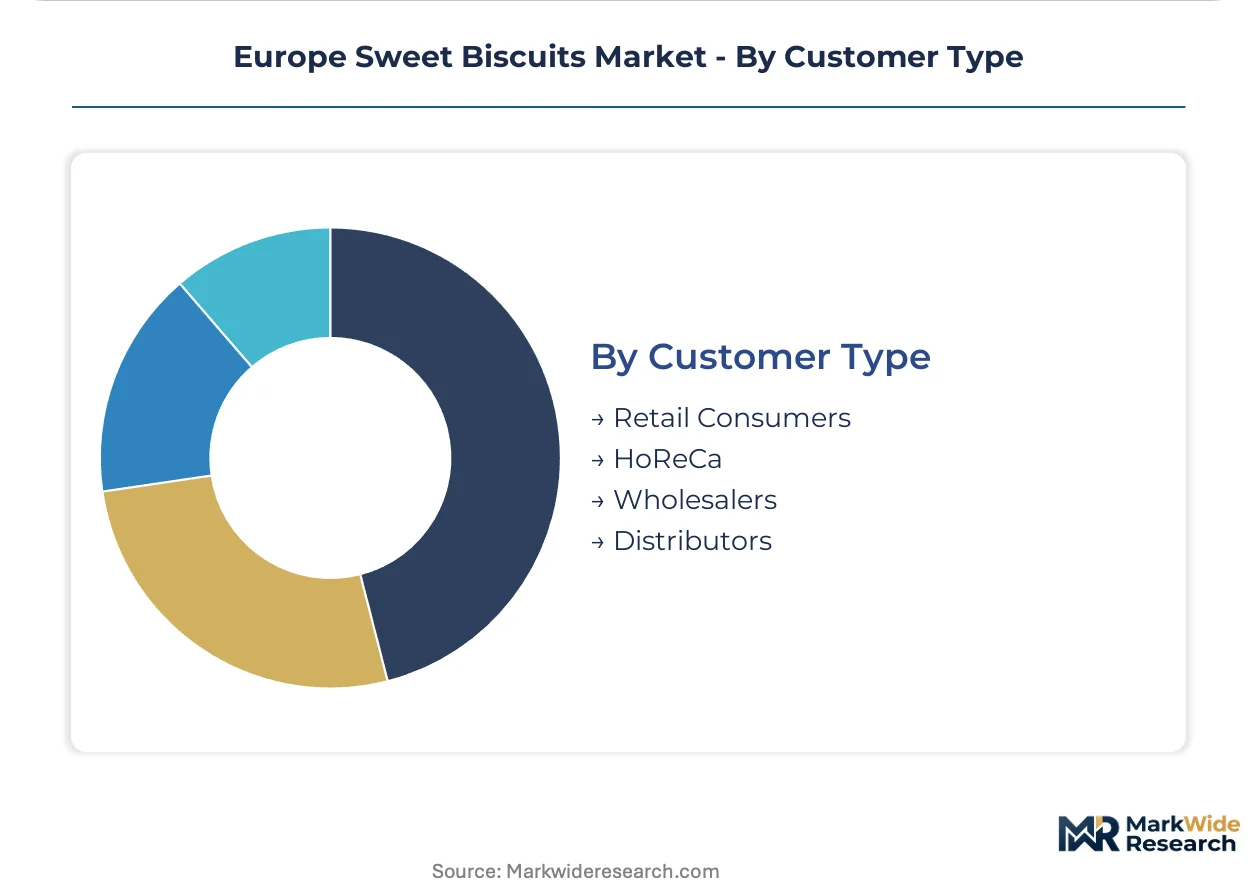
Customer Type:
Volume scale and margin structure diverge sharply across procurement behaviors.
- Retail Consumers:End-user purchasing decisions concentrate in German, French, and UK household segments. Portion-controlled format preferences are displacing bulk pantry stock.
- HoReCa:Hotels, restaurants, and cafes demand individually wrapped portions with extended ambient stability for minibar and breakfast service applications.
- Wholesalers:Cash-and-carry formats serve independent convenience retail across Poland and Romania.
- Distributors:Consolidated procurement for regional retail banners concentrates negotiating power in fewer intermediaries.
Retail Consumers anchor volume demand. HoReCa represents the steepest expansion trajectory as foodservice recovery continues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweet biscuit manufacturing in Europe traces its industrial lineage to nineteenth-century British and Scottish bakeries, where mechanized production first standardized shortbread and digestive recipes for mass distribution. Continental expansion followed through Belgian chocolate-cookie specialists and German butter-biscuit artisans, establishing the regional production geography that persists today.
Germany
Heritage-positioned seasonal bundling and portion-controlled lunchbox formats drive household purchasing cycles in German retail. EFSA Nutri-Score alignment requirements accelerate reduced-sugar recipe development among domestic producers. The Lower Saxony corridor hosts concentrated biscuit manufacturing capacity, where thermal baking line retrofits are converting to hybrid electric-gas configurations under EU Green Deal energy mandates.
United Kingdom
Chocolate cookies and digestive biscuits anchor volume demand through supermarket category captain negotiations and promotional elasticity modeling. UK grocers now mandate supplier funding for electronic price-tag infrastructure in exchange for shelf placement. The Scottish Highlands sustain shortbread heritage pricing through provenance documentation and gift-oriented box formats during Q4 purchasing cycles.
France
Cream-filled biscuits generate per-unit premiums through indulgence positioning in French and Belgian retail banners where front-of-pack scoring influences placement. EUDR deforestation due diligence rules inflate cocoa butter input costs for chocolate cookie formulations. The Île-de-France region concentrates premium branded multipack distribution networks serving Benelux export channels.
Netherlands
Subscription ambient-grocery models and D2C replenishment platforms capture repeat purchase data from urban households, driving fastest-growing online retail adoption. REACH food-contact testing burdens for new packaging chemistries extend product launch timelines for mid-tier producers lacking dedicated regulatory affairs teams. The Randstad logistics cluster enables same-day fulfillment networks for mono-material flexible film packaging conversions.
Poland
Discount retail format growth in Warsaw creates first-mover advantage for private-label biscuit suppliers with localized flavor portfolios. Cash-and-carry wholesale formats serve independent convenience retail across emerging modern trade channels. The country's central European position attracts regional distribution hub investments from continental manufacturers seeking EUDR-compliant cocoa sourcing diversification.
Europe Sweet Biscuits Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and regulatory compliance capacity. The market exhibits tiered concentration where multinational scale operators command supermarket category captain status while heritage specialists defend niche price positioning through provenance storytelling. Three archetypes dominate: continental-scale diversified snack conglomerates, regional heritage brands with seasonal bundling expertise, and private-label manufacturers serving discount retail expansion. Competitive dynamics center on enzymatic reformulation R&D acquisition and mono-material packaging line deployment ahead of 2030 EU Green Deal mandates.
Among heritage-anchored specialists, Lotus Bakeries NV and Bahlsen GmbH & Co. KG exemplify premium-tier positioning through regional brand equity and controlled distribution depth. Mondelez International occupies the scale-driven archetype, representing continental manufacturing footprint and category captain negotiation leverage across multiple European retail banners. These three entities illustrate the strategic divergence between provenance-based margin defense and volume-scale operational efficiency that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Lotus Bakeries NV |
| Bahlsen GmbH & Co. KG |
| Nestle SA |
| Pladis |
| Walkers Shortbread Ltd |
| Mondelez International |
| Burton's Biscuits Company |
| Kellanova |
| United Biscuits |
| Others |
Supply & Pricing Matrix
EU Green Deal packaging mandates gate both qualified supply and premium-tier pricing access, as mono-material film certification and enzymatic reformulation capabilities concentrate among producers with dedicated regulatory affairs capacity. Manufacturers lacking these qualifications face margin compression in standard tiers while certified suppliers extract shelf-placement premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage-positioned seasonal bundling from private-label discount formats and commodity pantry stock. Price differentiation rests on EFSA Nutri-Score alignment and mono-material packaging certification. Cost compression in standard tiers is intensifying because EUDR due diligence inflates cocoa butter input costs. Discount retail banners in Poland and Romania exhibit highest price sensitivity, while Benelux specialty shops sustain lowest.
Supply Chain Analysis
Single-source vulnerability sits with West African cocoa butter suppliers facing EUDR traceability requirements. Raw material flows draw from Côte d'Ivoire and Ghana for cocoa mass, Germany and Belgium for wheat flour milling, and the Netherlands for enzymatic ingredient processing. Regulatory restriction risk dominates as REACH food-contact testing extends launch timelines. Distribution runs through consolidated retail banner procurement with category captain negotiations determining shelf access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe sweet biscuits functions as a stable compounder anchored by recurring household replenishment cycles and portion-controlled format premiumization. Snack-oriented consumption patterns sustain volume predictability across economic cycles.
For Market Incumbents: To counter fresh bakery substitution at German and UK grocery chains, accelerate thermal oven retrofit completion in the Lower Saxony corridor and deepen enzymatic sugar reduction R&D partnerships with Dutch and Belgian research institutes. Mono-material flexible film line deployment ahead of 2030 mandates secures category captain status.
For New Entrants and Emerging Players: Capture discount retail expansion in Warsaw and Bucharest through localized flavor portfolios tailored to Polish and Romanian palates. Private-label manufacturing for emerging modern trade channels offers lowest competitive density. D2C subscription models in Netherlands urban households bypass wholesale markup structures.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier heritage brands with seasonal bundling expertise but limited analytics investment for digital shelf-edge integration. Long-term viability frames around EUDR-compliant cocoa sourcing infrastructure and reformulation talent retention. Watch for EFSA front-of-pack scoring expansion beyond France and Belgium as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Reformulation Investment | Amylase and invertase systems enable 30% sugar reduction while maintaining Maillard browning for EFSA Nutri-Score alignment. |
| Mono-Material Packaging Conversion | Polypropylene barrier films satisfy EU Green Deal recyclability targets without compromising moisture protection for standard shelf-life products. |
| Direct-to-Consumer Launch | Subscription replenishment platforms capture repeat purchase data from Netherlands and UK urban households while bypassing wholesale markups. |
| Regional Distribution Hub Establishment | Poland's central European position enables EUDR-compliant cocoa sourcing diversification and Warsaw-Bucharest discount retail coverage. |
| Sustainability Repositioning | EUDR deforestation due diligence certification secures supply chain preferencing as traceability rules tighten across West African cocoa origins. |
Research Methodology
Direct dialogue with category buyers at German and UK retail banners, brand managers at heritage and multinational producers, supply planners managing cocoa butter procurement, and regulatory affairs leads navigating EFSA and REACH compliance grounds this analysis. Secondary validation draws from EFSA guidance documents, EU Green Deal regulatory texts, customs records of cocoa and wheat flour trade flows, and Nielsen retail audit data across European markets. Bottom-up production capacity modeling and top-down household expenditure triangulation ensure cross-verified outputs.
Bottom-up volume builds aggregate from individual country consumption patterns, product type production line capacities, and channel throughput estimates across the projection horizon. Segmentation dimensions span product type, packaging format, distribution channel, and customer procurement behavior. CAGRs derive from trend-line extrapolation of portion-controlled format adoption, online retail penetration curves, and regulatory compliance cost pass-through assumptions. Enzymatic reformulation adoption rates and mono-material packaging conversion timelines serve as industry-specific forecast inputs.
Cocoa butter price volatility, EUDR enforcement timing variations, and fresh bakery counter expansion velocity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about regulatory implementation schedules and consumer format preference evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Flatbread Market
Bakery Products
Fondant Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Marzipan Market
Bakery Products
Latin America Frozen Bakery Market
Bakery Products
Gluten-Free Pizza Crust Market
Bakery Products
North America Par Baked Bread Market
Bakery Products
Low Calorie Cake Market
Bakery Products
Muffins Market
Bakery Products
United States Cookies Market
Bakery Products
Low-Calorie Toast Market
Bakery Products
Cream Cheese Frosting Market
Bakery Products
Soft Biscuit Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Bread Dough Improver Market