
 Low-Calorie Toast Market | 2026-2036
Low-Calorie Toast Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Toast Market Foresight
Whole grain specification upgrades is redrawing competitive boundaries in low-calorie toast. Flowers Foods leverages its southeastern US manufacturing footprint to sustain regional freshness leadership. Grupo Bimbo anchors Latin American supply chains while extending North American whole grain portfolios. Silver Hills Bakery specializes in organic sprouted grain processes that differentiate its premium positioning against mass-market alternatives.
Low-calorie toast denotes sliced bread products formulated with reduced caloric density per serving, typically achieved through modified flour blends, fiber enrichment, or controlled portion sizing below standard bread equivalents. Manufacturers achieve caloric reduction via enzyme-treated starches, resistant wheat starches, or alternative binders that maintain structural integrity at lower carbohydrate loads. The gluten-free segment leads absolute growth as celiac and non-celiac gluten-sensitive populations expand diagnostic recognition. Online retailers represent the fastest-growing distribution channel, capturing margin pools previously held by conventional supermarkets through subscription and direct-to-consumer health positioning.
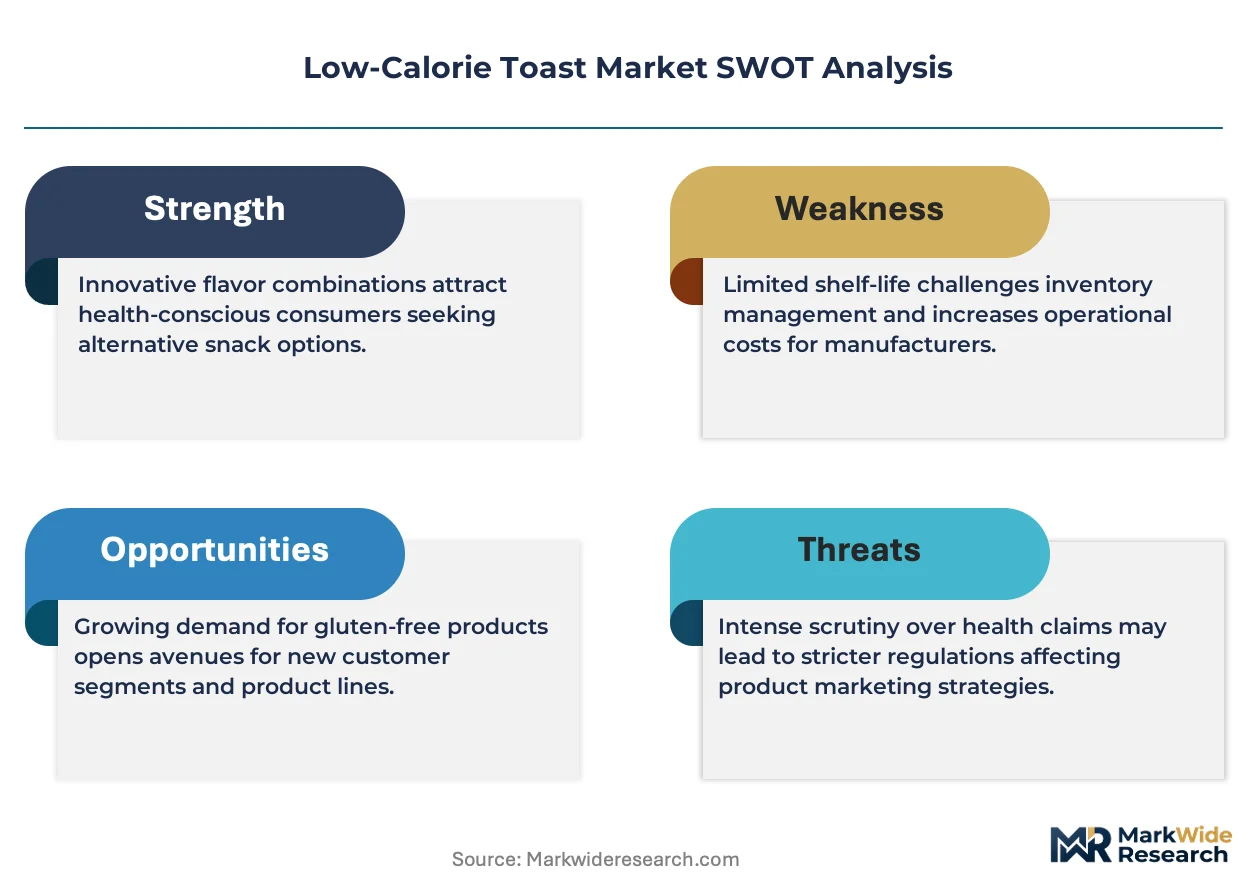
FDA nutrition labeling requirements and the USDA organic certification framework govern product claims and ingredient transparency in the United States, while EFSA health claim regulations constrain how European producers market caloric reduction benefits. These standards compel reformulation investments and restrict unsubstantiated wellness messaging. Stakeholders must monitor evolving glycemic index disclosure requirements and emerging front-of-pack labeling schemes that will reshape consumer decision architecture and retail placement economics.
Market Dynamics
Enzyme-treated starch technology is decomposing traditional flour economics by enabling caloric reduction without structural compromise, forcing reformulation investments across mid-tier bakeries that previously relied on conventional wheat processing.
Growth Catalysts
- FDA Nutrition Labeling Requirements:Transparent caloric disclosure mandates compel manufacturers to develop verifiably reduced-calorie formulations, accelerating clean-label innovation in US retail channels.
- Fitness Segment Demand:Body composition-focused consumers in weight management programs prioritize portion-controlled whole grain toast with measurable macronutrient profiles.
- Resistant Wheat Starch Processing:Industrial enzyme applications enable 30-40% carbohydrate reduction while maintaining loaf volume, expanding formulation possibilities for commercial bakeries.
Market Restraints
- Input Cost Volatility:Specialty enzyme and resistant starch suppliers concentrate in North American and European chemical processing corridors, exposing margins to energy-driven price swings.
- Technical Limitation:Gluten-free formulations face structural integrity ceilings at sub-80-calorie slice thresholds, constraining product development in the fastest-growing allergen segment.
- Substitution Threat:Refrigerated protein-rich alternatives and savory egg-based breakfast formats capture morning meal occasions from traditional toast categories.
Strategic Opportunities
- Direct-to-Consumer Subscription:Online retailers capture recurring revenue through personalized nutrition bundles, bypassing supermarket slotting fees and building first-party data assets.
- EFSA Health Claim Pathways:Validated glycemic index reduction claims open premium positioning in European markets where nutritional marketing faces strict evidentiary standards.
- Sprouted Grain Convergence:Combining enzymatic processing with controlled germination unlocks bioactive compound retention alongside caloric reduction, targeting functional food positioning.
Industry Challenges
- Formulation Talent Scarcity:Food science professionals with dual expertise in enzyme systems and sensory optimization command premium compensation, constraining mid-market R&D expansion.
- Multi-Jurisdiction Certification Timelines:Simultaneous USDA organic, FDA-compliant, and EU health claim validations extend product launch cycles by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Toast Market |
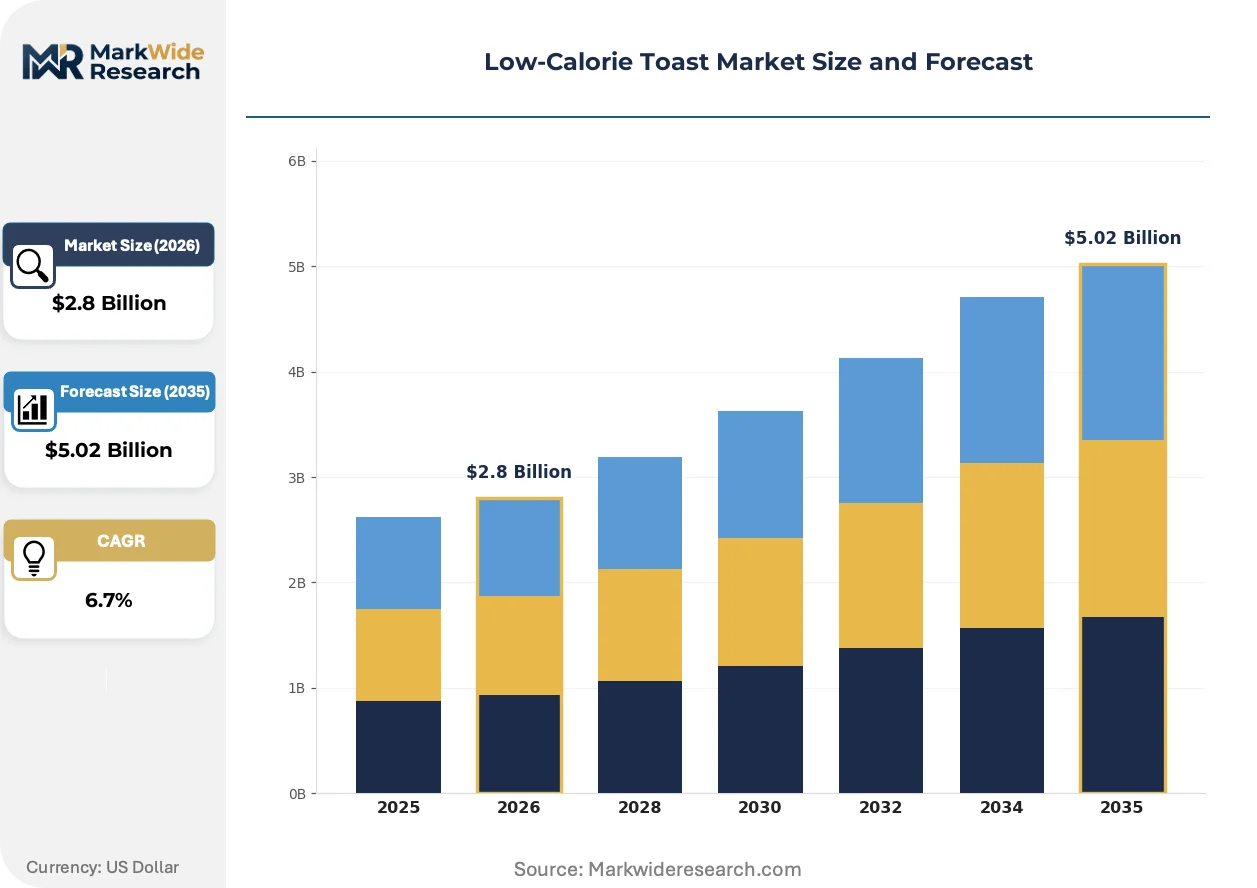
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, Gluten-Free, Seed-Based, Flavored End User: Health-Conscious Consumers, Fitness Enthusiasts, Diabetics, Weight Watchers Packaging Type: Bags, Boxes, Individually Wrapped, Bulk Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores |
| Companies Covered | Flowers Foods, Grupo Bimbo, Nature's Own, Silver Hills Bakery, Bimbo Bakeries USA, Franz Bakery, Aryzta, Angelic Bakehouse, ThinSlim Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Toast Market Shifts & Advancements
Reformulation science is actively displacing portion-reduction as the primary caloric control mechanism, with structural innovations enabling full-slice satisfaction at reduced energy density. This shift reconfigures manufacturing capital allocation and raw material sourcing strategies.
Enzymatic starch modification is decomposing the traditional trade-off between caloric reduction and mouthfeel quality. Food technologists deploy amyloglucosidase and pullulanase treatments to create resistant starch matrices that retain moisture and elasticity. Health-conscious households in Germany and Japan adopt these products at accelerating rates. The technology is compressing market share for legacy "thin-slice" approaches that sacrificed consumer satisfaction for label claims.
EU Green Deal nutritional profiling schemes are reshaping front-of-pack communication standards. The Nutri-Score algorithm penalizes energy density and refined carbohydrate content, incentivizing manufacturers to reformulate for favorable color-coded ratings. German and French retailers now require minimum profile thresholds for premium shelf placement. Bakery brands are responding with accelerated fiber fortification and alternative binder integration.
Subscription-based replenishment models are capturing pantry-stocking occasions from conventional grocery channels. Digital-native consumers in US metropolitan markets favor auto-delivery of specialized sprouted and gluten-free varieties with predictable consumption cycles. Direct relationships enable real-time flavor preference data collection. This pattern concentrates most visibly in California and New York urban corridors where delivery density supports unit economics.
Low-Calorie Toast Market Segmentation
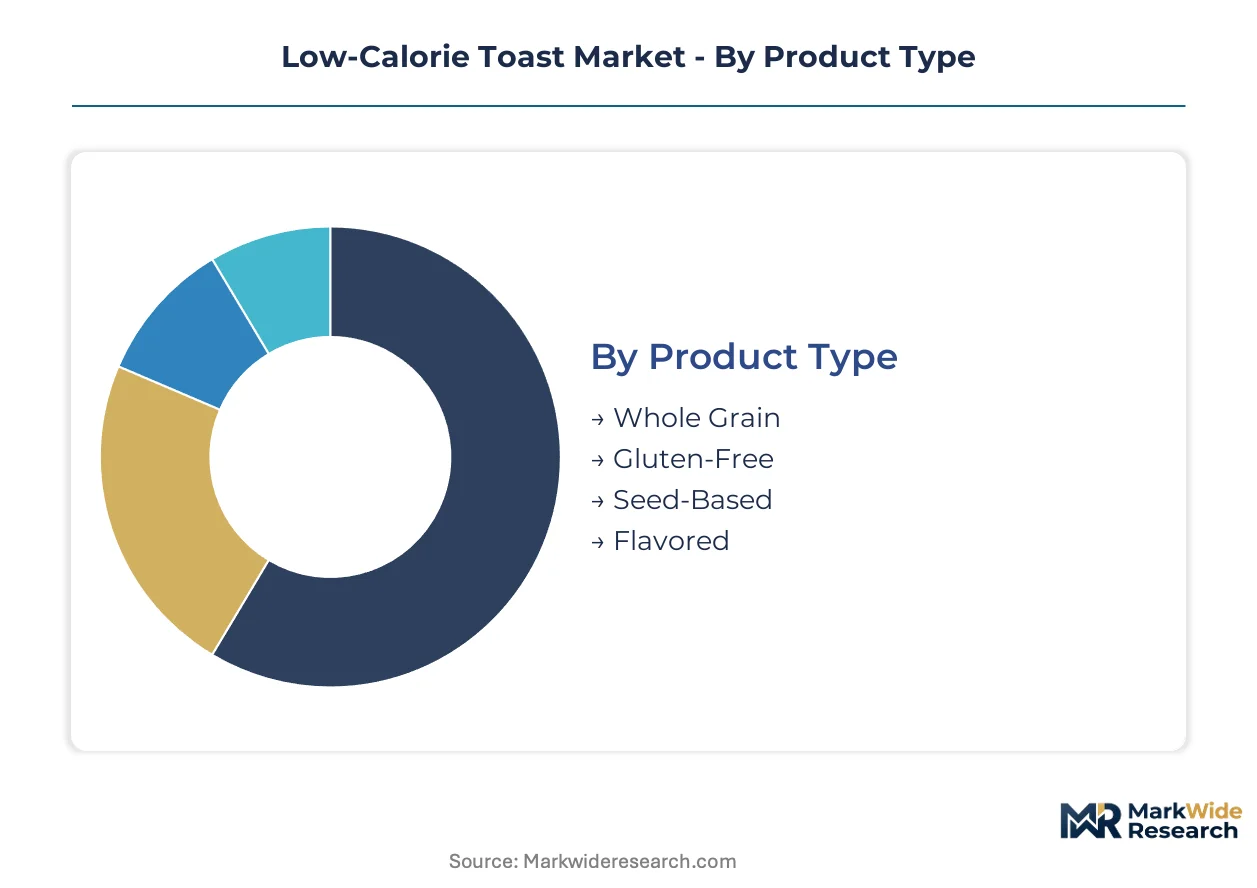
Segmentation in low-calorie toast reveals how formulation choices, consumption occasions, and purchase channels intersect to create distinct margin profiles. Manufacturers calibrate ingredient investments and packaging formats against the channel economics and nutritional priorities of each buyer cohort.
Product Type:
Supermarkets favor whole grain and flavored varieties for mainstream shelf placement, while health food stores and online retailers concentrate gluten-free and seed-based SKUs with premium positioning and specialized merchandising.
- Whole Grain:Formulations incorporate intact bran and germ layers with enzyme-modified starches to reduce caloric density while preserving fiber content. German retailers stock these varieties most heavily, driven by Nutri-Score labeling incentives that reward fiber density and penalize refined carbohydrate content.
- Gluten-Free:Rice flour, tapioca starch, and hydrocolloid binders replace wheat proteins to serve celiac and non-celiac gluten-sensitive populations. United States demand concentrates through Amazon and Thrive Market subscriptions where diagnostic recognition of gluten sensitivity continues expanding.
- Seed-Based:Chia, flax, and sunflower inclusions boost omega-3 and protein content for functional food positioning.
- Flavored:Cinnamon, vanilla, and savory herb infusions target breakfast and snacking occasions with sensory differentiation.
By volume, whole grain leads. By growth pace, gluten-free is ahead.
End User:
Cost tier stratification separates medical necessity buyers from lifestyle purchasers, with diabetics and weight watchers accepting higher per-slice costs for glycemic-controlled formulations while fitness enthusiasts prioritize macronutrient transparency.
- Health-Conscious Consumers:Households seeking general wellness improvement favor clean-label whole grain products with minimal processing claims. Japanese metropolitan markets show strongest adoption, where aging demographics prioritize preventive nutrition and front-of-pack calorie disclosure is mandatory.
- Fitness Enthusiasts:Body composition-focused buyers demand precise macronutrient labeling and portion-controlled packaging for meal prep integration. United States gym-adjacent retail and direct-to-consumer channels capture this cohort through subscription bundles paired with protein supplements.
- Diabetics:Glycemic index certification drives purchase decisions for blood glucose management.
- Weight Watchers:Calorie-point systems and portion accountability shape brand selection and slice-count preferences.
Health-conscious consumers generate the largest revenue base. Fitness enthusiasts are climbing the fastest.
Packaging Type:
Margin structure varies sharply by format, with individually wrapped slices commanding manufacturing premiums that offset higher per-unit costs through extended shelf stability and foodservice applicability.
- Bags:Standard multi-sleeve polypropylene packaging dominates retail velocity for family-size purchases. German and United States supermarkets rely on this format for everyday low-calorie toast placement, where unit economics favor high-throughput production lines.
- Individually Wrapped:Single-slice foil or film packaging enables precise portion control and extended ambient stability for foodservice and travel occasions. Japanese convenience stores and United States hotel breakfast programs drive adoption of this premium format.
- Boxes:Carton-based secondary packaging supports premium brand storytelling and gift-market positioning.
- Bulk:Unsliced loaf or unpackaged formats serve commercial foodservice and bakery commissary operations.
Bags dominate unit movement. Individually wrapped formats are gaining share fastest.
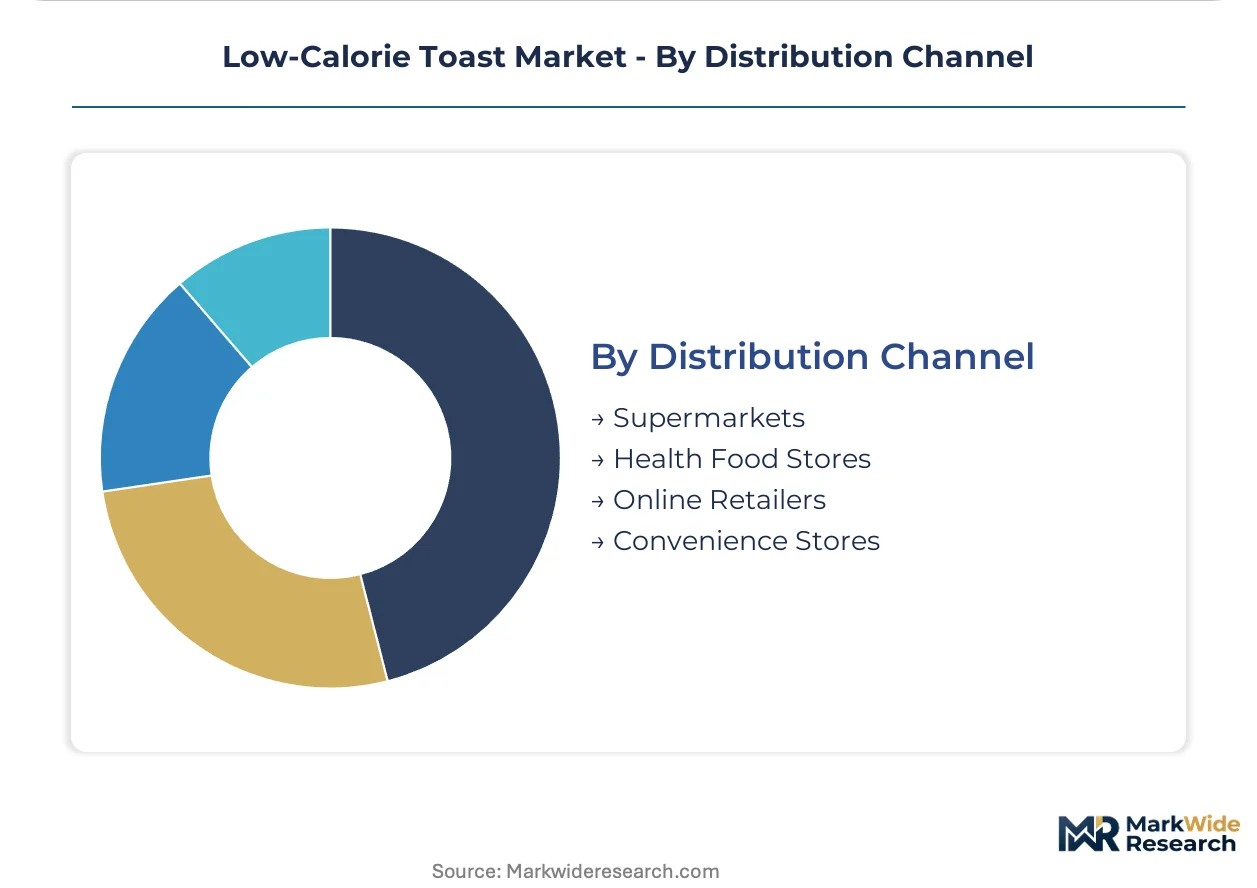
Distribution Channel:
Geographic concentration of channel development creates divergent growth trajectories, with online infrastructure maturity in coastal United States cities enabling subscription models that inland markets cannot yet support.
- Supermarkets:Conventional grocery chains maintain volume leadership through established bakery aisle placement and promotional slotting programs. United States retailers like Kroger and Albertsons anchor whole grain and flavored variety distribution, though shelf space for low-calorie SKUs competes with conventional bread price promotions.
- Online Retailers:Amazon, Thrive Market, and brand-direct subscriptions capture recurring pantry replenishment with personalized nutrition bundles. California and New York urban corridors show highest penetration, where delivery density supports unit economics and consumer data collection enables flavor innovation.
- Health Food Stores:Specialized retailers like Whole Foods and Sprouts curate premium gluten-free and organic sprouted selections with educated staff recommendation.
- Convenience Stores:Grab-and-go breakfast occasions drive individually wrapped low-calorie toast placement in urban Japan and selective United States metro markets.
Supermarkets lead absolute volume. Online retailers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty enzyme production for resistant starch processing clusters in the United States and Germany, while consumer adoption concentrates in aging metropolitan markets with established health food retail infrastructure. Regulatory divergence between FDA disclosure mandates and EFSA health claim frameworks creates formulation complexity for multinational brands. Japanese convenience retail and German Nutri-Score labeling represent distinct demand-pull mechanisms reshaping regional product specifications.
United States
Fitness enthusiasts and weight management program participants drive demand for portion-controlled whole grain varieties with precise macronutrient labeling. FDA nutrition labeling requirements mandate transparent caloric disclosure, compelling manufacturers to invest in verifiable formulation technologies. California and New York urban corridors anchor subscription-based direct-to-consumer growth, where delivery density supports personalized nutrition bundle economics.
Germany
Health-conscious households prioritize fiber-dense whole grain products that optimize Nutri-Score color-coded ratings for shelf placement. EU Green Deal nutritional profiling schemes penalize energy density and refined carbohydrate content, accelerating reformulation toward favorable front-of-pack scores. Retailers in Berlin and Munich now enforce minimum profile thresholds for premium bakery aisle positioning.
Japan
Aging demographics in metropolitan Tokyo and Osaka prioritize preventive nutrition and mandatory front-of-pack calorie disclosure. METI standards govern functional food claims, constraining how manufacturers market glycemic-controlled formulations. Convenience stores in Kanto and Kansai regions drive individually wrapped low-calorie toast adoption for grab-and-go breakfast occasions.
Canada
Health Canada regulations on nutritional claims and organic certification shape product development for cross-border North American distribution. Consumers in Toronto and Vancouver metropolitan areas show accelerating adoption of gluten-free varieties through specialized health food retail channels. Prairie grain processing infrastructure supports regional sourcing of enzyme-modified starch inputs.
United Kingdom
Post-regulatory divergence from EU frameworks creates distinct labeling requirements managed by the Food Standards Agency. London and Southeast England concentrate demand for premium sprouted grain and seed-based varieties through subscription and specialty retail channels. Mid-sized regional bakeries compete against multinational brands by emphasizing local provenance and clean-label positioning.
Low-Calorie Toast Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with enzyme formulation specialists commanding premium positioning while scale manufacturers optimize throughput economics. The market structure segments into three tiers: multinational baked goods conglomerates with continental distribution networks, mid-sized regional specialists leveraging proximity freshness, and niche organic sprouted grain artisans targeting subscription channels. Dominant competitive moves include portfolio diversification into gluten-free and functional positioning, plus strategic partnerships with enzyme technology suppliers to secure resistant starch processing capabilities.
Among North American baked goods manufacturers, Flowers Foods and Bimbo Bakeries USA exemplify scale-driven regional distribution archetypes, while Silver Hills Bakery occupies a position within the organic sprouted grain specialist tier. These three entities represent distinct strategic postures: continental network coverage, manufacturing footprint optimization, and premium ingredient differentiation respectively.
| Leading Market Players |
|---|
| Flowers Foods |
| Grupo Bimbo |
| Nature's Own |
| Silver Hills Bakery |
| Bimbo Bakeries USA |
| Franz Bakery |
| Aryzta |
| Angelic Bakehouse |
| ThinSlim Foods |
| Others |
Supply & Pricing Matrix
Ninety-day enzyme inventory cycles in North American chemical processing corridors concentrate pricing power among resistant starch suppliers, while FDA disclosure mandates force manufacturers to absorb certification premiums or pass them to health-conscious consumers. This lead-time structure rewards vertically integrated bakeries with captive enzyme sourcing and squeezes mid-tier competitors dependent on spot-market specialty inputs.
Pricing Analysis
FDA nutrition labeling requirements dictate the pricing tier structure across the low-calorie toast market, separating premium certified-organic SKUs from conventional reduced-calorie alternatives. Three-tier pricing stratifies across premium sprouted-grain, standard whole-grain, and economy thin-slice formulations, with certification grade and fiber content as primary differentiation drivers. Cost compression in the economy tier intensifies because commodity wheat flour contracts face energy-driven volatility. Health-conscious consumers in Japan and Germany show least price sensitivity, while budget buyers in US inland markets resist per-slice premiums above conventional bread benchmarks.
Supply Chain Analysis
Ninety-day enzyme inventory cycles expose manufacturers to input cost volatility when energy prices spike in German and US chemical processing hubs. Resistant wheat starch supply concentrates in the United States, Germany, and Canada, with amyloglucosidase and pullulanase enzymes drawing from North American biotech fermentation capacity. Single-source vulnerability in specialty hydrocolloid binders for gluten-free formulations threatens production continuity. Distribution runs through supermarket bakery aisles in Germany and the United States, with online subscription channels capturing margin pools in California and New York urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in subscription-based direct-to-consumer channels, where diagnostic recognition of gluten sensitivity and fitness-program adoption create addressable micro-segments underserved by mass-market bakery distribution.
For Market Incumbents: Compound defensive moats through backward integration into enzyme-modified starch production and accelerated USDA organic certification timelines. Refrigerated protein-rich breakfast alternatives threaten morning toast occasions, demanding portfolio diversification into functional positioning. Channel control through exclusive supermarket bakery aisle placement in Kroger and Albertsons networks preserves volume leadership against digital-native entrants. For New Entrants and Emerging Players: Differentiate on sprouted-grain bioactive compound retention combined with glycemic index certification for diabetic and weight-management segments. White-space concentrates in individually wrapped formats for Japanese convenience stores and US hotel breakfast programs. Direct-to-consumer subscription bundles paired with protein supplements offer the most penetrable go-to-market angle for fitness enthusiasts in coastal US metropolitan markets. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational baked goods conglomerates seeking to divest non-core regional brands with underutilized organic certification infrastructure. Long-term viability hinges on formulation talent retention and enzyme technology licensing access. Watch EFSA health claim validation timelines as inflection indicator for European premium positioning viability.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Captures recurring revenue from California and New York fitness enthusiasts while building first-party preference data. |
| Backward Integration into Enzyme Processing | Secures resistant starch supply continuity against energy-driven price swings in North American chemical corridors. |
| EFSA Health Claim Validation Investment | Unlocks premium positioning in German and French markets where Nutri-Score thresholds govern shelf placement. |
| Gluten-Free Structural Integrity R&D | Overcomes sub-80-calorie formulation ceilings constraining product development in the fastest-growing allergen segment. |
| Individually Wrapped Format Expansion | Targets Japanese convenience store channels and US foodservice accounts with extended ambient stability requirements. |
Research Methodology
Operator-level perspectives from bakery R&D directors, supermarket category buyers, enzyme technology suppliers, and health food store procurement managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through FDA labeling guidance documents, USDA organic certification databases, EFSA health claim registers, and Nielsen retail audit data. Bottom-up volume triangulation across product type, end user, packaging format, and distribution channel dimensions converged with top-down market sizing.
Sensitivity analysis tested forecast robustness across enzyme input cost scenarios and regulatory timeline variations over the projection horizon. Segmentation modeling incorporated product type, end user archetype, packaging configuration, and distribution channel dimensions alongside geographic regulatory cluster differentiation. CAGRs derived from weighted average growth contributions across these segments, with formulation technology adoption curves and subscription channel penetration rates as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of caloric disclosure mandates or accelerated EU Green Deal nutritional profiling implementation would require recalibration. Forecasts reflect assumptions regarding enzyme technology maturation and gluten-free structural innovation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Healthy Biscuits Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Waffle Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Middle East and Africa Bakery Products Market
Bakery Products
Baking Mixes Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Pancake Mixes Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
United States Cookies Market
Bakery Products
Global Wafer Biscuits Market