
 South America Ice Cream Market | 2026-2036
South America Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
South America Ice Cream Market Analytics
Buyer concentration among South American supermarket operators is shifting as regional chains consolidate procurement and expand private-label ice cream programs. Grupo Nutresa leverages its Andean manufacturing footprint to supply multiple retail banners across Colombia and Ecuador. Unilever PLC sustains brand equity through premium positioning in Brazil's urban centers, while Arcor S.A.I.C. dominates Argentina's interior provinces through deep distribution networks.
Ice cream denotes a frozen dairy or water-based dessert typically containing milk fat, sugars, and stabilizers, aerated through continuous freezing to achieve overrun levels between 80% and 120%. The product serves commercial refreshment and at-home indulgence segments across tropical and temperate climates. Artisan and gelato categories command margin premiums in metropolitan food service channels, while family-size tubs anchor volume through supermarket distribution. Soft serve competes aggressively in convenience-store and quick-service formats, where throughput economics favor lower-unit-price, higher-frequency purchase patterns.
ANVISA governs dairy-derived product standards and additive approvals in Brazil, while Argentina's national food safety authority enforces parallel compositional rules that complicate cross-border formulation standardization. Mercosur technical regulations on dairy trade create both harmonization pressure and residual national exemptions that fragment compliance costs. Stakeholders must monitor evolving front-of-package warning label mandates and their downstream effects on premium positioning and reformulation investments.
Market Dynamics
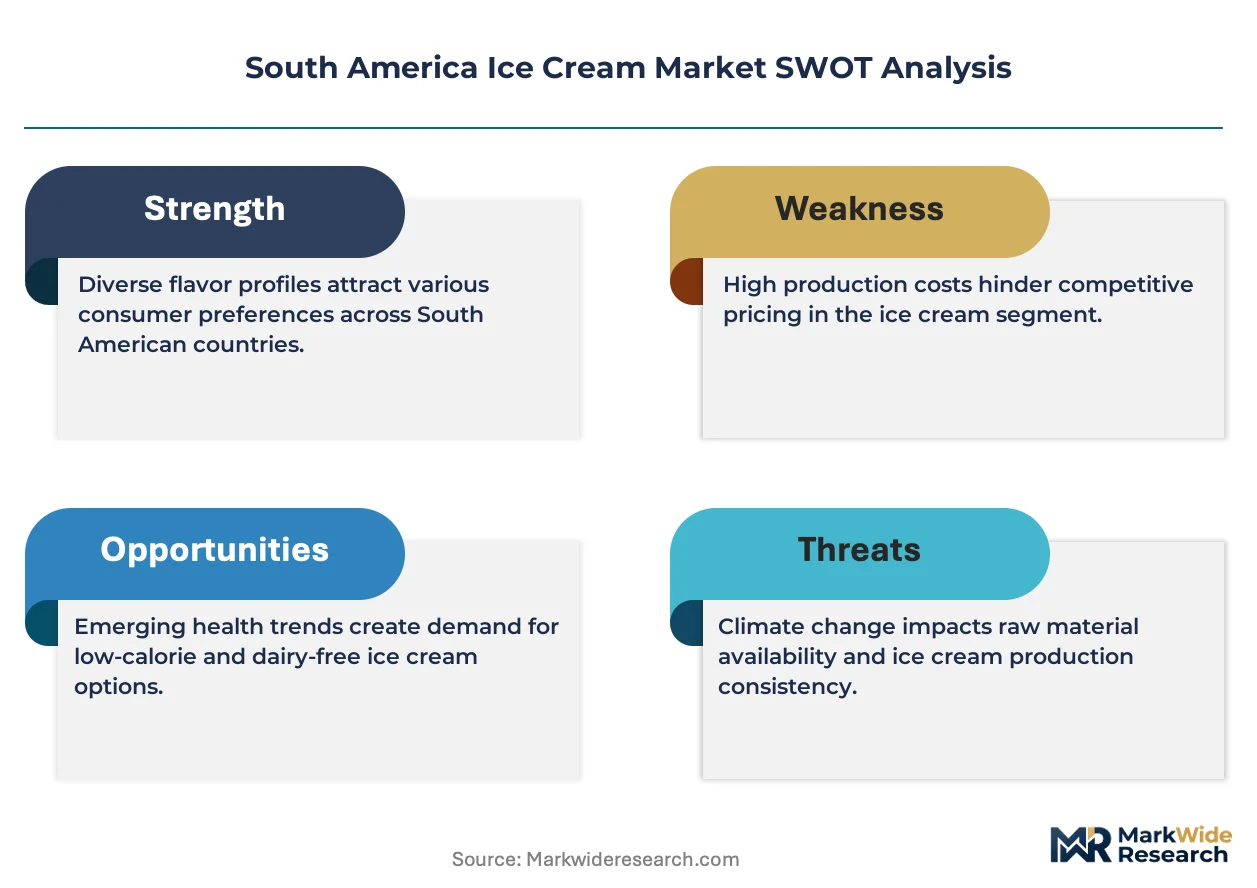
Supermarket chains across Brazil and Argentina are consolidating procurement through expanded private-label freezer allocations, reshaping manufacturer relationships and margin structures throughout the South American ice cream supply chain.
Growth Catalysts
- ANVISA labeling harmonization:Brazil's updated front-of-package warning standards are accelerating reformulation investments that favor clean-label portfolios across Mercosur trade zones.
- Cold-chain infrastructure expansion:Refrigerated logistics networks in Colombia's Andean corridor are unlocking at-home consumption growth previously constrained by distribution gaps.
- Urban density concentration:São Paulo's metropolitan consumer base sustains per-capita consumption rates that justify premium product line investments by regional manufacturers.
Market Restraints
- Dairy input cost volatility:Milk powder and butterfat price swings tied to Argentine agricultural cycles compress margin predictability for formulation-dependent producers.
- Cross-border regulatory friction:Residual national exemptions within Mercosur technical regulations fragment compliance costs between Brazilian ANVISA standards and Argentina's parallel food safety authority requirements.
- Energy-intensive freezing:Grid reliability constraints in Ecuador's highland regions limit continuous freezing throughput economics for industrial-scale production.
Strategic Opportunities
- Ecuador's underpenetrated Andean corridor:Grupo Nutresa's existing manufacturing footprint positions suppliers to capture volume growth in provinces beyond Quito's immediate catchment.
- Quick-service soft-serve expansion:Convenience-store channel penetration in Chile's Santiago metropolitan area favors lower-unit-price, higher-frequency purchase patterns over traditional tub formats.
- Gelato artisan convergence:Metropolitan food service channels in Buenos Aires are absorbing European-style production equipment to command margin premiums through experiential positioning.
Industry Challenges
- Refrigeration technician scarcity:Specialized cold-chain maintenance skills are concentrating in Brazil's southeastern corridor, leaving interior provinces vulnerable to equipment downtime.
- Front-of-package compliance timelines:ANVISA's phased warning label implementation is forcing simultaneous portfolio management across legacy and reformulated product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Ice Cream Market |
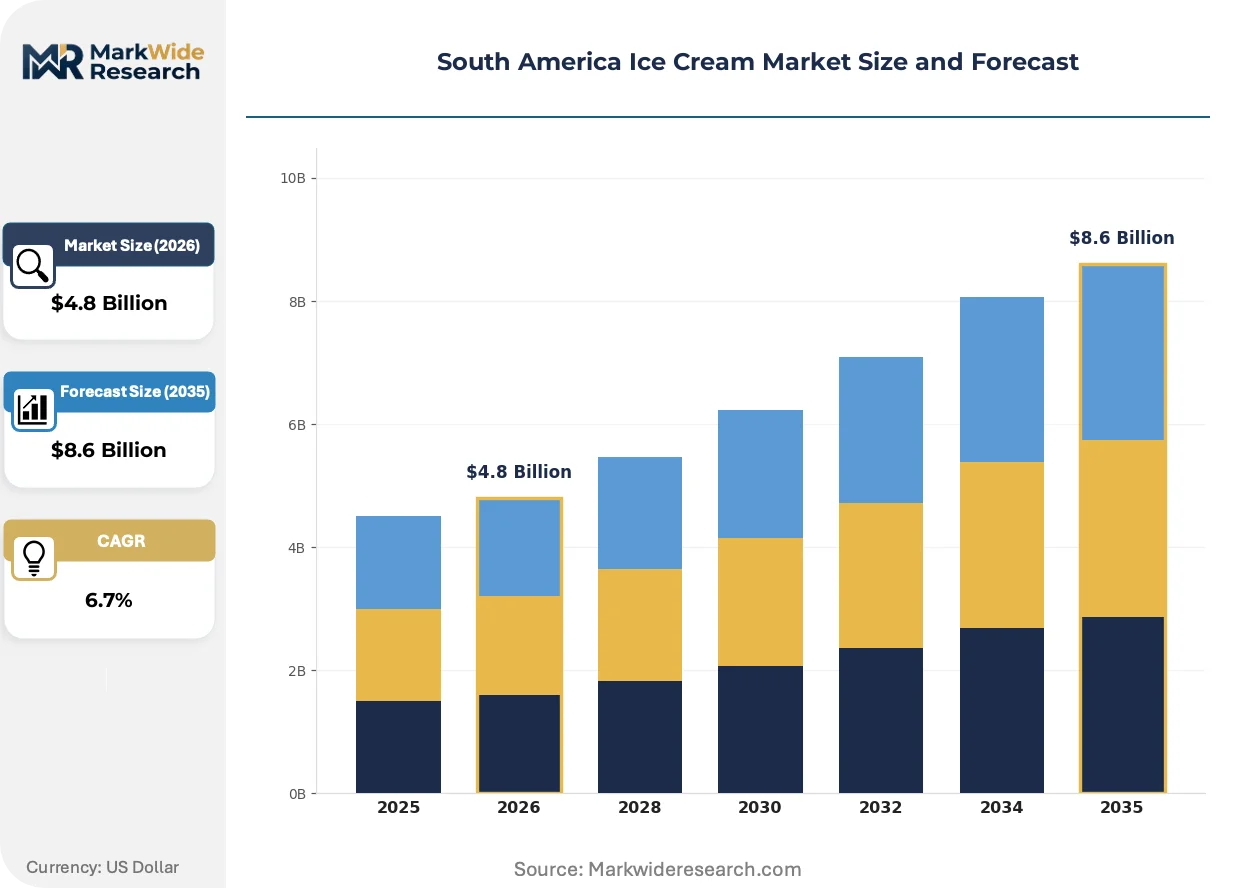
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artisan, Soft Serve, Gelato, Sorbet Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Flavor Profile: Chocolate, Vanilla, Strawberry, Mango Serving Size: Single Scoop, Double Scoop, Family Size, Tubs |
| Companies Covered | Helacor S.A., Grupo Nutresa, Unilever PLC, Froneri Lux Topco S.À R.L., Sorvetes Jundiá Indústria E Comércio LTDA, Nestlé S.A., Colombina S.A., Chiquinho Sorvetes, Arcor S.A.I.C., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Ice Cream Market Evolving Landscape
Reformulation investments and channel restructuring are converging to reshape competitive positioning across South America's ice cream value chain, with regulatory pressure and urban consumption patterns driving material allocation decisions.
Continuous freezing technology with precision overrun control is electrifying production economics for mid-scale manufacturers. Brazilian industrial processors in São Paulo's manufacturing belt are adopting these systems to compress batch-to-batch variation and reduce energy intensity per liter. The technology is electrifying capacity utilization rates in facilities serving both private-label supermarket contracts and branded food service channels.
Mercosur's ongoing dairy trade harmonization efforts are creating formulation standardization pressure across member states. Brazil's ANVISA and Argentina's national food safety authority maintain parallel additive approval lists that complicate cross-border product line rationalization. Premium positioning strategies are most affected, as manufacturers must either maintain separate SKUs or accept lowest-common-denominator ingredient restrictions.
At-home consumption consolidation through supermarket freezer expansion is displacing traditional corner-store impulse purchasing in Brazil's urban centers. São Paulo's supermarket operators are reallocating floor space toward family-size tubs and multi-pack formats, compressing single-serve novelty exposure. This rotation is most visible in the southeastern corridor, where cold-chain reliability supports extended stockholding periods that favor planned rather than impulse purchase behavior.
South America Ice Cream Market Segmentation
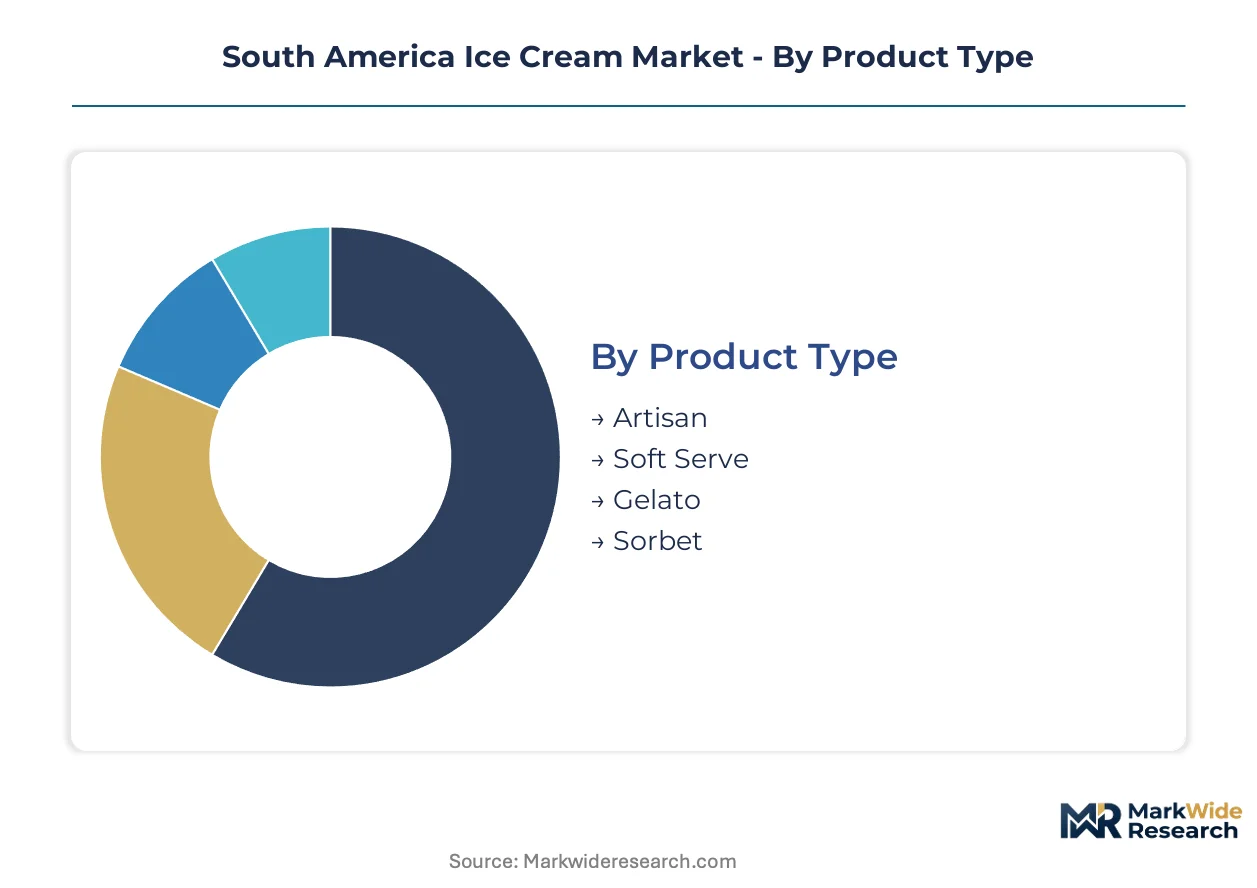
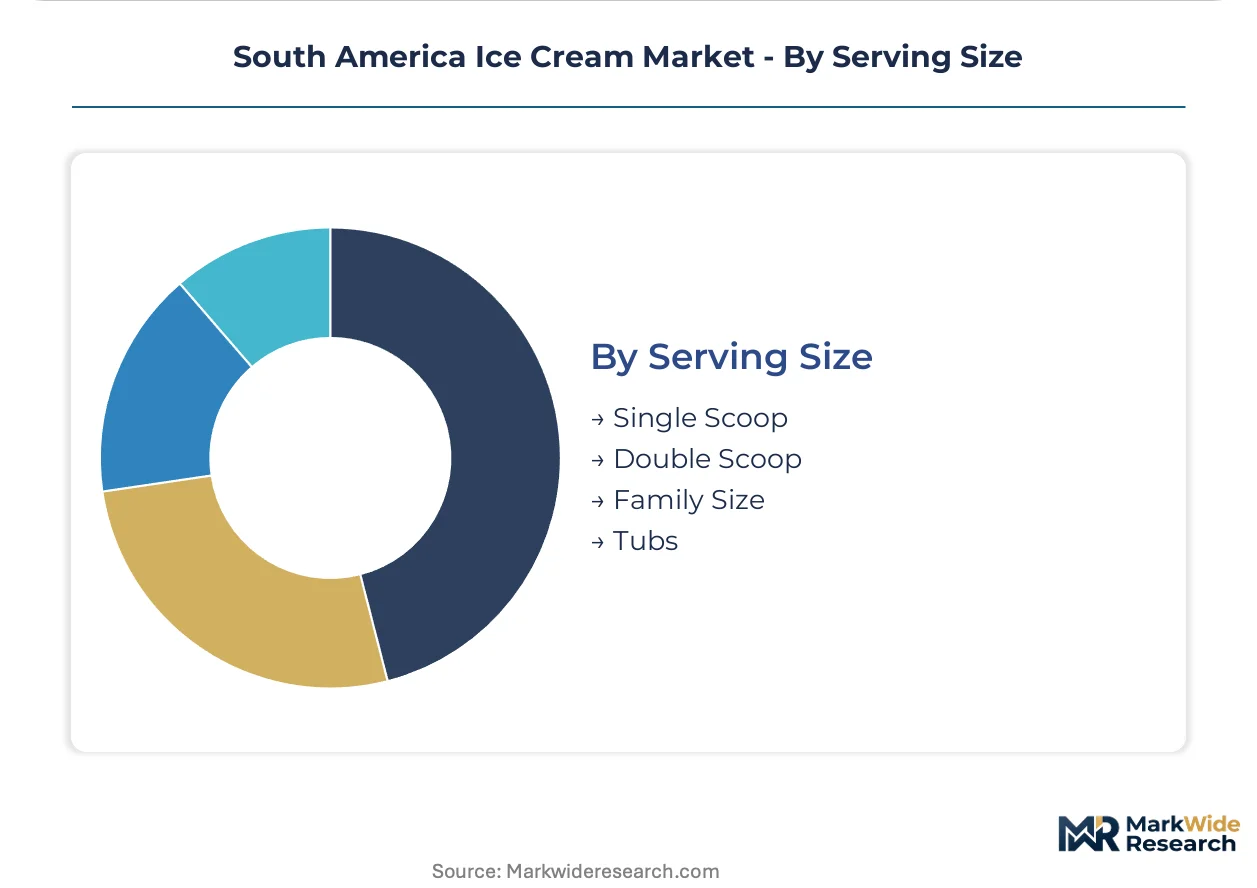
Ice cream segmentation across South America reflects divergent consumption contexts: metropolitan food service channels favor experiential artisan formats, while supermarket expansion concentrates volume in family-size packaged goods. Manufacturers must configure production lines for both premium margin capture and high-throughput private-label supply.
Product Type:
Customization intensity varies sharply across this spectrum, from standardized soft-serve systems to highly variable artisan production.
- Artisan:Small-batch production with premium ingredient sourcing and elevated butterfat content distinguishes this segment. São Paulo's metropolitan food service corridor absorbs the highest regional concentration, driven by consumer willingness to pay experiential premiums in dense urban dining clusters.
- Soft Serve:Continuous freezing systems deliver 80-120% overrun through precise aeration control. Quick-service penetration in Chile's Santiago metropolitan area favors this format's throughput economics and lower unit-price positioning for high-frequency purchase patterns.
- Gelato:Lower overrun and denser texture command margin premiums through European-style positioning in Buenos Aires food service channels.
- Sorbet:Water-based formulations without dairy fat serve lactose-intolerant demand and tropical climate refreshment needs in Colombia's Andean corridor.
Most installed capacity flows through Soft Serve. Expansion is steepest in Artisan.
Distribution Channel:
Channel economics separate planned stock-up purchases from impulse-driven single-serve transactions across South America's evolving retail landscape.
- Supermarkets:Refrigerated logistics networks and extended stockholding periods enable family-size tub concentration. Brazil's southeastern corridor operators are reallocating freezer floor space toward multi-pack formats, compressing single-serve novelty exposure.
- Convenience Stores:Impulse velocity and limited freezer footprint favor high-margin novelty items and soft-serve machines. Argentina's interior provinces retain stronger traditional corner-store penetration than Brazil's urban centers.
- Online Retail:Cold-chain reliability constraints limit penetration to metropolitan zones with dedicated frozen fulfillment infrastructure.
- Food Service:Gelato and artisan categories anchor this channel through experiential positioning and premium pricing in metropolitan dining clusters.
Volume concentrates in Supermarkets. Margin expansion runs fastest through Food Service.
Flavor Profile:
Regional taste preferences and ingredient sourcing economics create distinct formulation priorities across Mercosur markets.
- Chocolate:Cocoa butter and powder input costs tie this segment to volatile commodity markets, with premium positioning requiring single-origin sourcing claims.
- Vanilla:Standardization potential is highest here, supporting private-label production scale across Brazilian supermarket banners.
- Strawberry:Seasonal fruit sourcing constraints complicate year-round supply consistency for regional manufacturers.
- Mango:Tropical climate alignment drives strongest demand concentration in Colombia and Ecuador, with local fruit processing integration reducing import dependency.
Vanilla commands the broadest installed base. Mango is climbing the fastest.
Serving Size:
Packaging economics and consumption occasion segmentation separate immediate consumption from at-home inventory building.
- Single Scoop:Food service portion control and impulse pricing dominate this format, with equipment-dependent throughput in convenience and quick-service channels.
- Double Scoop:Premium positioning in artisan and gelato contexts supports higher per-transaction revenue in metropolitan food service.
- Family Size:Multi-portion packaging aligns with Brazilian supermarket expansion and at-home consumption consolidation in São Paulo's urban density.
- Tubs:Industrial-scale production and private-label supply concentration favor this format for volume manufacturing economics.
Tubs absorb most production line capacity. Family Size is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized refrigeration technicians concentrate in Brazil's southeastern corridor, leaving interior provinces vulnerable to equipment downtime that constrains production scale-up. Cold-chain reliability gaps fragment market development across the continent's mountainous and remote zones. Urban density clusters in specific metropolitan corridors anchor per-capita consumption premiums.
Brazil
São Paulo's metropolitan consumer base sustains the highest regional per-capita ice cream consumption rates, justifying premium product line investments by manufacturers. ANVISA's updated front-of-package warning label standards are accelerating reformulation investments toward clean-label portfolios. The southeastern manufacturing belt around São Paulo is adopting continuous freezing systems with precision overrun control to compress batch-to-batch variation.
Argentina
Deep distribution networks penetrate Argentina's interior provinces where traditional corner-store impulse purchasing retains stronger penetration than in Brazil's urban centers. The national food safety authority enforces compositional rules that complicate cross-border formulation standardization with Brazil. Buenos Aires metropolitan food service channels are absorbing European-style gelato production equipment to command margin premiums.
Colombia
Refrigerated logistics networks in Colombia's Andean corridor are unlocking at-home consumption growth previously constrained by distribution gaps. Local fruit processing integration for mango formulations reduces import dependency in tropical climate refreshment segments. Grupo Nutresa leverages its Andean manufacturing footprint to supply multiple retail banners across provinces beyond Quito's immediate catchment.
Chile
Quick-service soft-serve expansion in Santiago's metropolitan area favors lower-unit-price, higher-frequency purchase patterns over traditional tub formats. Convenience-store channel penetration concentrates volume throughput in equipment-dependent formats. Grid reliability constraints in highland regions limit continuous freezing throughput economics for industrial-scale production.
Ecuador
Underpenetrated Andean provinces beyond Quito present volume growth opportunities for suppliers with existing manufacturing footprints. Cold-chain infrastructure investments remain uneven across elevation zones, fragmenting at-home consumption development. Energy-intensive freezing operations face grid reliability constraints that limit continuous production scale.
South America Ice Cream Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South America's ice cream value chain, creating tiered competitive dynamics. The market structure consolidates around multinational packaged goods groups with regional manufacturing footprints and domestic specialists with deep distribution networks. Three strategic archetypes dominate: diversified food conglomerates with ice cream as a portfolio segment, regional dairy processors with captive cold-chain assets, and artisan specialists serving metropolitan food service channels. Competitive moves concentrate on private-label contract manufacturing expansion and cold-chain infrastructure partnerships with retail banners.
Among regional conglomerates, Grupo Nutresa and Arcor S.A.I.C. exemplify the diversified food group archetype with multi-category manufacturing footprints spanning Andean and Southern Cone markets. Unilever PLC occupies a position representing multinational packaged goods specialists competing through premium brand equity in dense urban corridors. These three companies anchor the competitive landscape by demonstrating alternative scale pathways: regional manufacturing consolidation, domestic distribution depth, and global brand leverage.
| Leading Market Players |
|---|
| Helacor S.A. |
| Grupo Nutresa |
| Unilever PLC |
| Froneri Lux Topco S.À R.L. |
| Sorvetes Jundiá Indústria E Comércio LTDA |
| Nestlé S.A. |
| Colombina S.A. |
| Chiquinho Sorvetes |
| Arcor S.A.I.C. |
| Others |
Value Network & Pricing Analysis
Milk powder and butterfat input costs cascade through South American ice cream manufacturing into three distinct pricing tiers, with Argentine dairy price volatility compressing margins for formulation-dependent producers while Brazilian supermarket chains extract volume discounts through consolidated procurement.
Pricing Analysis
Packaged goods compete against food service dispensing on fundamentally different pricing logics. Three-tier pricing structure across premium, standard, and economy levels separates artisan gelato positioning from private-label tub economics, with brand equity and butterfat content driving differentiation. Cost compression in economy tiers is intensifying because Argentine agricultural cycles destabilize dairy input costs. Convenience-store operators show highest price sensitivity, while metropolitan food service channels absorb premium markups for experiential positioning.
Supply Chain Analysis
Dual-sourcing requirements from Brazilian supermarket chains mandate multi-supplier qualification for private-label contracts, fragmenting manufacturing relationships. Supply concentrates in Brazil, Argentina, and Colombia for dairy base and tropical fruit processing. Raw material dependencies center on milk powder, cocoa butter, and regional mango pulp. Single-source vulnerability runs through Argentine butterfat suppliers exposed to climatic yield variation. Distribution runs through refrigerated logistics networks anchored in São Paulo's southeastern corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South America's ice cream market offers margin-expansion pathways through continuous freezing technology adoption and premium-tier portfolio shifts toward artisan and gelato categories.
For Market Incumbents: Extend cold-chain infrastructure partnerships into Ecuador's underpenetrated Andean provinces before competitor manufacturing footprints solidify. Defend against Grupo Nutresa's regional consolidation by locking multi-year private-label contracts with Brazilian supermarket banners. Prioritize ANVISA-compliant reformulation investments to maintain shelf access as front-of-package warning mandates phase in.
For New Entrants and Emerging Players: Precision overrun control systems offer entry into mid-scale manufacturing previously dominated by legacy batch equipment. White-space targets include Santiago's quick-service soft-serve channel and Buenos Aires gelato equipment supply. Penetrate through equipment-leasing models that lower capital barriers for artisan food service operators.
For Investors and Strategic Acquirers: Consolidation pressure builds where cold-chain technician scarcity constrains production scale-up in interior provinces. Five-to-ten-year viability favors regional dairy processors with captive freezer distribution assets. Target acquisition archetype: Andean corridor manufacturers with established fruit processing integration. Watch ANVISA enforcement consistency as inflection indicator for reformulation cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Refrigerated logistics alliances with Colombian Andean distributors unlock at-home consumption growth beyond Quito. |
| Premium Tier Introduction | European-style gelato equipment deployment in Buenos Aires commands margin premiums through experiential positioning. |
| Private-Label Contract Expansion | Multi-year supply agreements with Brazilian supermarket banners secure volume throughput against regional competitors. |
| Reformulation Investment | ANVISA-compliant clean-label portfolios maintain retail access as front-of-package warning mandates accelerate. |
| Manufacturing Footprint Extension | Andean corridor production capacity captures Ecuador volume growth outside existing competitor catchment zones. |
Research Methodology
Multiple input streams — executive interviews with dairy processing plant managers, category buyer discussions at Brazilian supermarket chains, and secondary validation through customs records and ANVISA regulatory filings — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged supply planners at regional manufacturers, cold-chain logistics operators, and food service channel distributors. Secondary sources included Mercosur trade harmonization documents, dairy commodity price databases, and retail audit data from Nielsen and Circana.
Historical consumption patterns were cross-referenced against panel input from industry stakeholders to construct projections across the analysis window. Segmentation dimensions modeled include product type, distribution channel, flavor profile, and serving size, with regional regulatory clusters and urban density tiers as cross-cutting variables. CAGRs were derived from volume trajectory analysis incorporating dairy input cost cycles and supermarket freezer space allocation trends.
The model holds under stable Mercosur trade harmonization and continued cold-chain infrastructure investment; deviation in Argentine agricultural yield volatility or ANVISA enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Europe Sourdough Market
Bakery Products
Bakery Flavors Market
Bakery Products
Bakery Improvers Market
Bakery Products
Dough Whitener Market
Bakery Products
Bakery Mixes Market
Bakery Products
Pastries Market
Bakery Products
Cake Base Discs Market
Bakery Products
India Cake Market
Bakery Products
Vegan Certified Cake Mixes Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
Cake Concentrate Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Dough Conveyor Market
Bakery Products
Pancakes Market
Bakery Products
United States Bread Market
Bakery Products
Bake Stable Pastry Fillings Market