
 Sugar-Free Biscuits and Cookies Market | 2026-2036
Sugar-Free Biscuits and Cookies Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar-Free Biscuits and Cookies Market Analytics
E-commerce grocery platforms are reshaping how sugar-free biscuits and cookies reach health-conscious households, bypassing traditional retail gatekeepers with direct-to-pantry subscription models. Mondelēz International leverages its global snack logistics network to sustain shelf presence across multiple continents. Nestlé anchors its portfolio with specialized diabetic-friendly lines developed through intensive R&D programs. Quest Nutrition differentiates through protein-enriched cookie formulations targeting fitness-oriented consumers.
Sugar-free biscuits and cookies denote baked goods manufactured without sucrose or high-fructose corn syrup, typically employing polyols, steviol glycosides, or monk fruit extracts to achieve sweetness while maintaining structural integrity through modified starch and fiber systems. These products serve clinical nutrition needs for diabetics and glycemic-controlled diets while expanding into mainstream wellness snacking. The cookies segment leads volume due to familiar consumption rituals and flavor adaptability, though bars command premium positioning through protein fortification and portable format convenience. Online retail channels capture the fastest expansion trajectory as algorithm-driven personalization matches specialty ingredient preferences to niche consumer cohorts.
The FDA's Nutrition Facts panel mandates transparent added-sugar disclosure, compelling manufacturers to reformulate or risk consumer rejection at point of purchase. EFSA's health claim evaluations for sugar substitutes create regulatory gatekeeping that determines which sweetener technologies achieve European market authorization. Stakeholders must monitor evolving WHO guidance on non-sugar sweeteners, as pending systematic reviews could recast consumer trust and reshape permissible ingredient palettes across formulations.
Market Dynamics
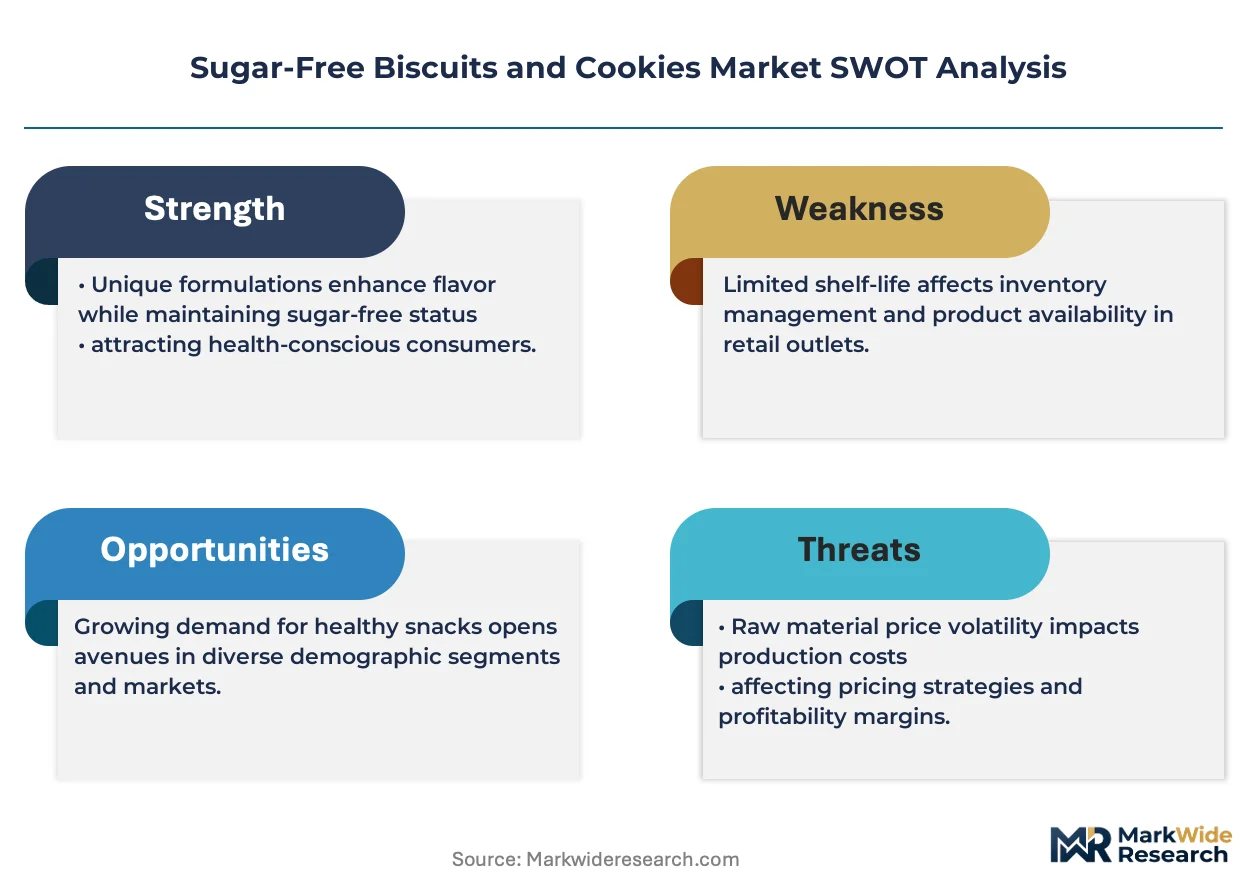
Reformulation pressure from transparent sugar-disclosure mandates is collapsing legacy sweetener architectures, forcing manufacturers to rebuild recipes around steviol glycosides and monk fruit extracts while maintaining the structural integrity that consumers expect from traditional biscuits.
Growth Catalysts
- FDA Nutrition Facts Overhaul:Mandatory added-sugar line-item disclosure compels manufacturers to eliminate sucrose from formulations or face point-of-purchase rejection by health-conscious shoppers scanning labels in retail pharmacy and grocery channels.
- Urban Health-Food Retail Corridors:Concentrated demand clusters in California, Maharashtra, and Bavaria concentrate purchasing power and validate premium positioning for specialty sugar-free assortments in high-foot-traffic locations.
- Diabetic Diet Normalization:Glycemic-controlled eating patterns expand beyond clinical necessity into mainstream wellness snacking, enlarging the addressable consumer base for functional baked goods.
Market Restraints
- Polyol Cost Volatility:Erythritol and maltitol supply chains exhibit price instability tied to corn-derived feedstock fluctuations, compressing margin buffers for mid-tier manufacturers dependent on bulk sweetener contracts.
- EFSA Authorization Gatekeeping:Health claim evaluations for novel sweetener technologies create multi-year regulatory friction, delaying European market entry for monk fruit extract formulations already cleared in North American jurisdictions.
- Texture Engineering Limitations:Modified starch and fiber systems required to replace sugar's structural properties introduce formulation complexity that extends R&D cycles and raises technical failure rates in scaled production.
Strategic Opportunities
- Direct-to-Pantry Subscription Models:E-commerce grocery platforms bypass traditional retail gatekeepers, enabling algorithm-driven personalization that matches specialty ingredient preferences to niche consumer cohorts with precision impossible in brick-and-mortar.
- Protein-Fortified Cookie Convergence:Fitness-oriented consumers seeking macronutrient-dense snacking create white space for hybrid products combining sugar-free positioning with elevated protein content in portable formats.
- German Retail Pharmacy Expansion:Shelf-space allocation for sugar-free biscuit assortments in Apotheke and dm-drogerie markt chains signals channel authorization that manufacturers can replicate across similar health-focused retail formats.
Industry Challenges
- Flavor Chemist Talent Scarcity:Reformulation expertise bridging bakery science and sweetener technology commands premium compensation, constraining capacity expansion for mid-market producers seeking to enter the category.
- Clean-Label Certification Timelines:Third-party non-GMO and organic verification processes extend product launch schedules by 8-14 months, delaying revenue recognition against fixed R&D investments.
- Legacy Equipment Retrofit Costs:Existing production lines optimized for sucrose-based dough rheology require capital-intensive modification to handle hygroscopic polyol systems without moisture-control failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar-Free Biscuits and Cookies Market |
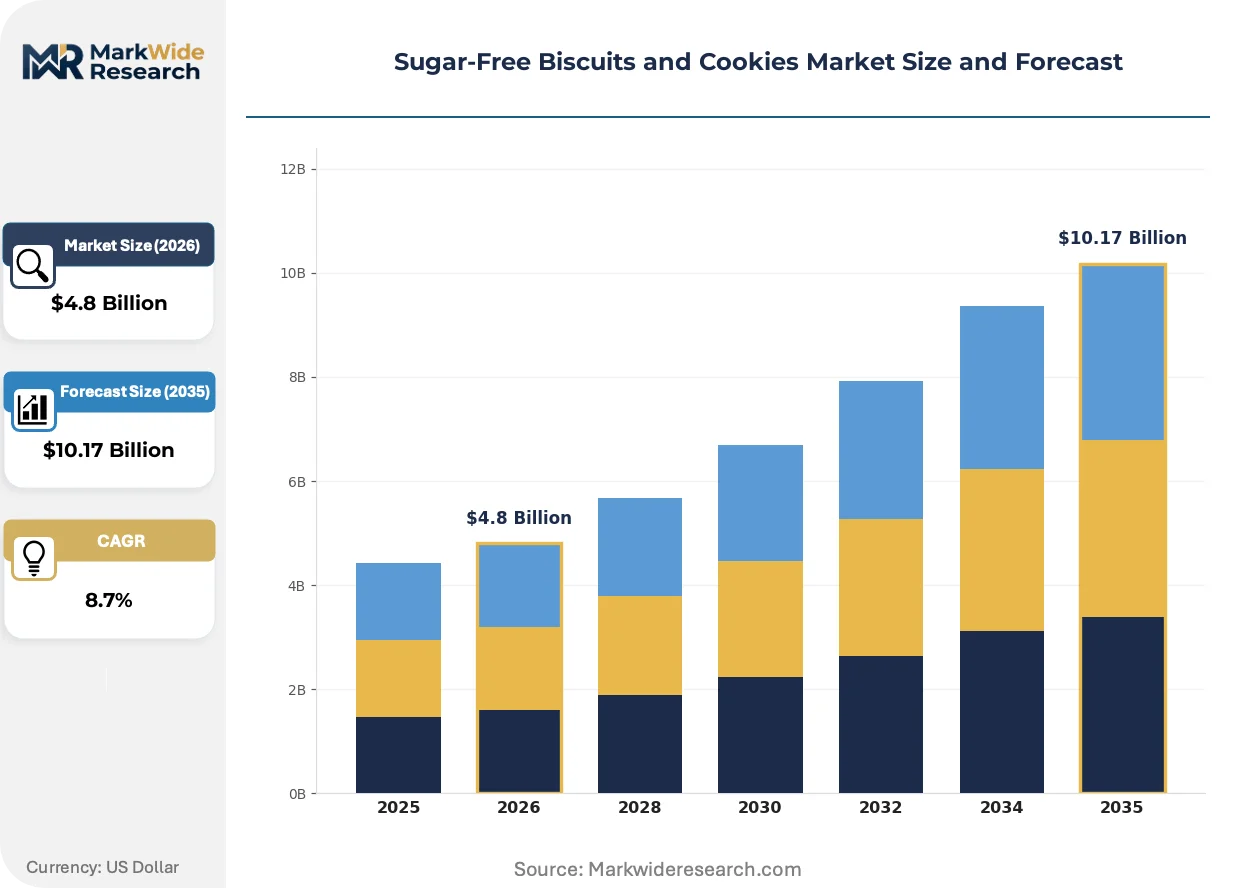
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookies, Biscuits, Bars, Crackers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Convenience Stores Ingredients: Almond Flour, Coconut Sugar, Stevia, Monk Fruit End User: Health-Conscious Consumers, Diabetics, Weight Watchers, Children |
| Companies Covered | Galletas Gullon, Aunt Gussie's Cookies & Crackers, Mondelēz International, Quest Nutrition, Lenny & Larry's, Nestlé, Voortman Bakery, The Ferrero Group, Burton's Biscuit Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar-Free Biscuits and Cookies Market Evolving Landscape
Reformulation science is advancing faster than consumer education, creating a gap between technical capability and market comprehension that early movers exploit through transparent ingredient storytelling.
Monk fruit extract is collapsing the technical barrier between sugar-free positioning and acceptable taste profiles in premium cookie segments. Artisanal bakeries and specialty manufacturers are adopting this technology at accelerating pace as extraction costs decline. The structural consequence is compression of the quality-premium formerly commanded by stevia-only formulations.
EFSA's systematic re-evaluation of non-sugar sweetener health claims is reshaping permissible ingredient palettes across European formulations. Manufacturers are pre-emptively diversifying sweetener portfolios to avoid single-point-of-failure regulatory exposure. The biscuit segment faces the highest reformulation urgency given its dependence on bulk sweetener volumes.
Algorithm-curated subscription boxes are displacing aisle-based discovery for specialty dietary products. Health-conscious households in California and Bavaria are abandoning traditional grocery browsing for personalized pantry replenishment matched to metabolic profiles. This behavioral shift concentrates purchasing power with platform owners and fragments brand loyalty.
Sugar-Free Biscuits and Cookies Market Segmentation
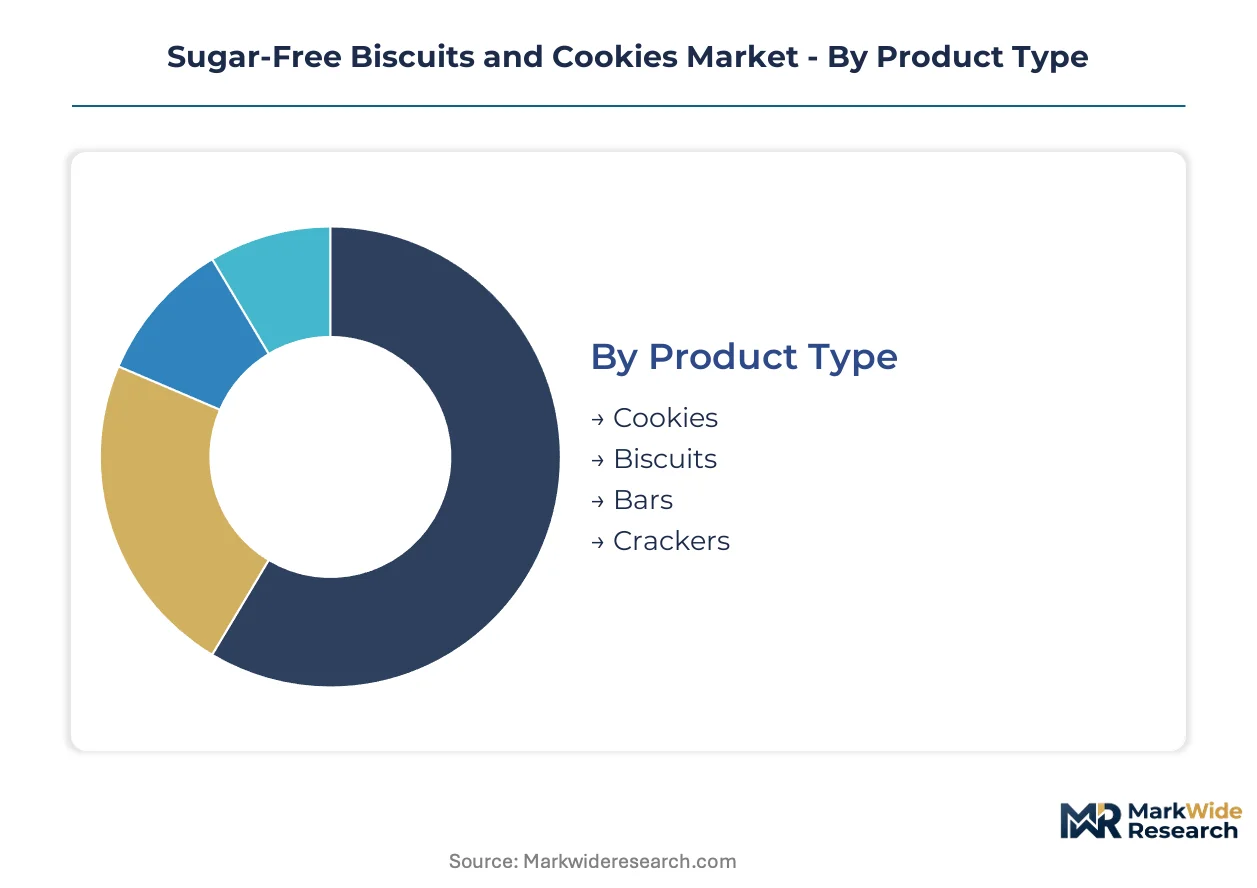
Sugar-free biscuits and cookies segment along four distinct axes that determine formulation priorities, channel strategy, and pricing architecture. Product type dictates manufacturing complexity and margin structure. Distribution channel governs consumer touchpoints and brand discovery mechanics. Ingredient selection shapes regulatory compliance and clean-label positioning. End-user targeting calibrates functional claims and packaging formats.
Product Type:
Mature formats anchor volume while emerging configurations capture premium positioning through functional fortification.
- Cookies:Classic drop and molded formats employ modified starch and fiber systems to replicate sucrose's structural binding. California health-food retail corridors concentrate demand for premium assortments as diabetic diet normalization broadens the consumer base beyond clinical necessity.
- Biscuits:Layered and shortbread varieties require precise polyol crystallization control to achieve flaky texture without sugar's glass-forming properties. German Apotheke and dm-drogerie markt chains allocate expanding shelf space, validating channel authorization for functional baked goods in pharmacy retail formats.
- Bars:Portable formats integrate protein fortification with sugar-free positioning to serve fitness-oriented snacking occasions.
- Crackers:Savory applications leverage minimal sweetness requirements, reducing reformulation complexity for clean-label cracker lines.
Cookies retain volume leadership; bars hold the steepest expansion curve.
Distribution Channel:
Channel selection determines margin capture and consumer relationship depth across the purchase journey.
- Online Retail:Algorithm-driven personalization matches specialty ingredient preferences to niche metabolic profiles. Direct-to-pantry subscription models in California and Bavaria bypass traditional retail gatekeepers, fragmenting brand loyalty while concentrating purchasing power with platform owners.
- Supermarkets:Mass-market penetration requires FDA Nutrition Facts compliance for transparent added-sugar disclosure at point of purchase.
- Specialty Stores:Curated assortments command premium pricing through educated staff and ingredient transparency.
- Convenience Stores:Impulse-oriented formats favor single-serve packaging with immediate consumption cues.
Supermarkets maintain volume dominance; online retail climbs the fastest.
Ingredients:
Cost tier stratification separates commodity polyols from premium botanical extracts in formulation economics.
- Almond Flour:Nut-based flours provide structural integrity and protein content while eliminating grain allergens. Clean-label certification timelines for non-GMO verification extend product launch schedules, delaying revenue recognition against fixed R&D investments.
- Monk Fruit:Mogroside extracts collapse the technical barrier between sugar-free positioning and acceptable taste profiles. EFSA authorization gatekeeping creates multi-year regulatory friction, delaying European market entry for formulations already cleared in North American jurisdictions.
- Stevia:Steviol glycosides face compression of quality-premium as monk fruit adoption accelerates in premium segments.
- Coconut Sugar:Lower-glycemic alternatives occupy mid-tier positioning between conventional sweeteners and zero-calorie extracts.
Stevia retains formulation ubiquity; monk fruit gains share fastest.
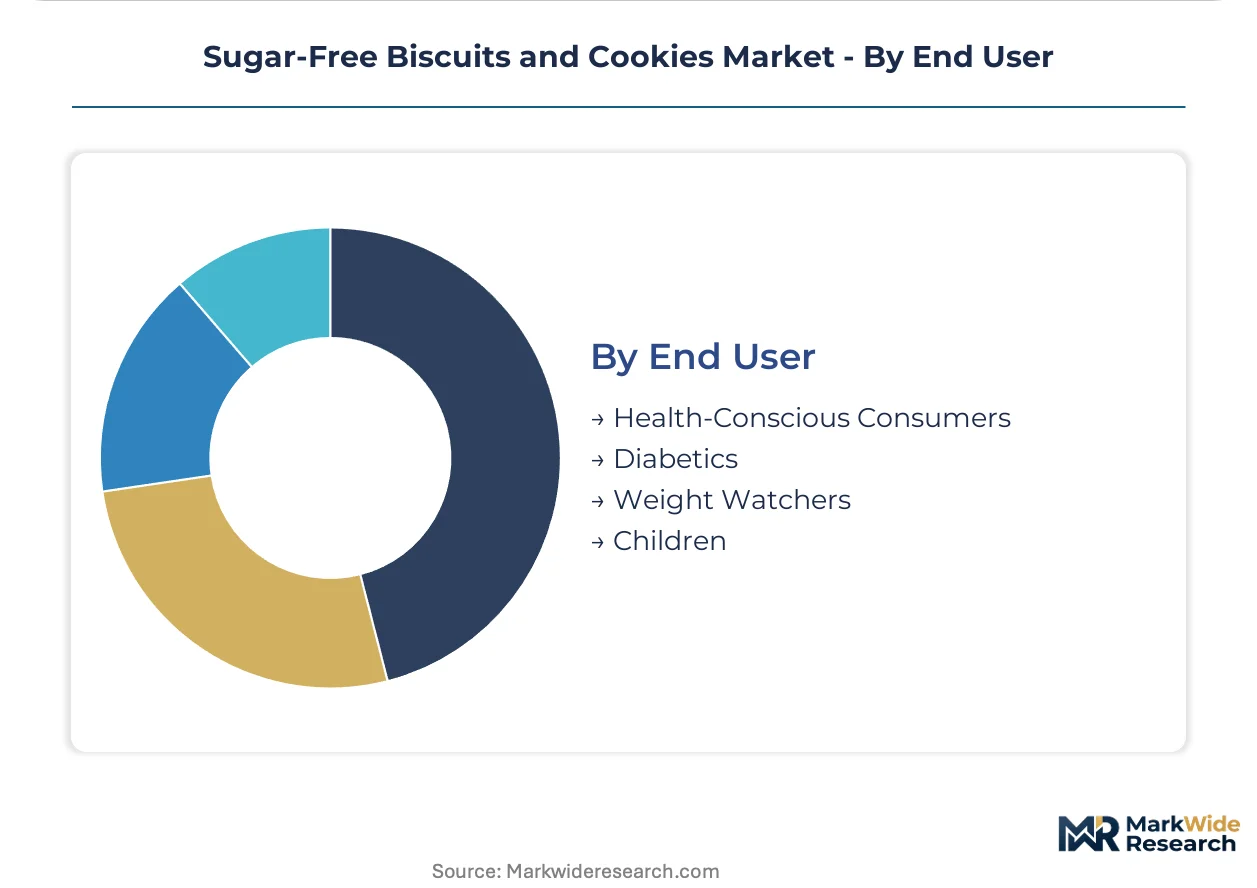
End User:
Customer type segments by metabolic need intensity and purchase motivation clarity.
- Diabetics:Clinical necessity drives consistent repurchase and price inelasticity for verified low-glycemic formulations. Maharashtra urban corridors concentrate purchasing power as glycemic-controlled eating patterns expand beyond medical prescription into lifestyle choice.
- Health-Conscious Consumers:Wellness-oriented households prioritize clean-label ingredient transparency over strict metabolic metrics. WHO guidance on non-sugar sweeteners shapes consumer trust, requiring manufacturers to monitor pending systematic reviews that could recast permissible ingredient palettes.
- Weight Watchers:Calorie-conscious segments favor portion-controlled packaging with macronutrient disclosure.
- Children:Pediatric formulations face heightened scrutiny for sweetener safety profiles and dental health claims.
Diabetics anchor revenue stability; health-conscious consumers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium shelf space in German pharmacy chains commands pricing power that mass-market US supermarkets cannot replicate, while Maharashtra's urban corridors concentrate emerging demand from glycemic-conscious households. This asymmetry shapes manufacturer channel prioritization and margin capture across developed and developing markets.
United States
FDA Nutrition Facts labeling mandates for added-sugar disclosure drive reformulation urgency among domestic manufacturers. California health-food retail corridors concentrate purchasing power for premium assortments, while retail pharmacy chains expand shelf space for diabetic-friendly lines. Quest Nutrition and Mondelēz International leverage established distribution networks to sustain presence across these high-foot-traffic channels.
Germany
Apotheke and dm-drogerie markt chains validate channel authorization for functional baked goods through expanding shelf-space allocation. EFSA health claim evaluations for novel sweeteners create regulatory friction that delays monk fruit extract formulations already cleared elsewhere. Bavaria's urban health-food retail corridors concentrate demand clusters that validate premium positioning for specialty assortments.
India
Maharashtra's urban corridors anchor emerging demand as glycemic-controlled eating patterns expand beyond clinical prescription into lifestyle choice. FSSAI regulatory frameworks govern permissible sweetener technologies and labeling requirements for sugar-free positioning. Mumbai and Pune retail clusters concentrate purchasing power among health-conscious households seeking clean-label alternatives.
United Kingdom
Boots pharmacy chains and premium grocery formats drive channel segmentation between clinical nutrition and wellness snacking. EFSA-aligned regulatory evaluations shape permissible ingredient palettes for European market entry. London and Southeast England health-food retail corridors concentrate demand for premium cookie assortments employing stevia and polyol systems.
Japan
PMDA and MHLW regulatory frameworks establish stringent safety profiles for non-sugar sweeteners in functional foods. METI industrial policy supports R&D investment in reformulation technologies for aging-population dietary needs. Tokyo-Osaka metropolitan corridors concentrate demand for portion-controlled, low-glycemic snacking formats.
Sugar-Free Biscuits and Cookies Market Competitive Landscape
Global snack conglomerates and specialized nutrition brands split the market between mass-market penetration and niche functional positioning. Consolidation pressure intensifies as reformulation costs favor scale economies in sweetener procurement and R&D capacity. Three archetypes dominate: multinational CPG platforms with cross-category logistics networks, protein-focused nutrition specialists, and regional bakery heritage brands. Competitive moves concentrate on portfolio diversification into diabetic-friendly lines and strategic partnerships with e-commerce grocery platforms.
Within the multinational platform tier, Mondelēz International and Nestlé exemplify scale-driven archetypes leveraging global distribution infrastructure. Quest Nutrition occupies a specialist position representing the protein-fortified nutrition segment. Among European heritage brands, Galletas Gullon and Burton's Biscuit Company anchor regional manufacturing expertise. These named entities illustrate strategic positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Galletas Gullon |
| Aunt Gussie's Cookies & Crackers |
| Mondelēz International |
| Quest Nutrition |
| Lenny & Larry's |
| Nestlé |
| Voortman Bakery |
| The Ferrero Group |
| Burton's Biscuit Company |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp freight corridors govern polyol distribution economics, compressing margin buffers for manufacturers dependent on erythritol and maltitol feedstocks while amplifying price differentiation between bulk commodity formulations and certified clean-label premium tiers.
Pricing Analysis
The customization-premium spread separates algorithm-curated subscription assortments from mass-market supermarket placements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and ingredient transparency intensity. Cost compression in mid-tier stevia formulations is intensifying because monk fruit extract adoption accelerates in premium segments. Health-conscious households in California and Bavaria show lowest price sensitivity; weight-management segments in emerging urban corridors exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between China and North America dominates monk fruit extract procurement risk for manufacturers building European market entry strategies. Raw material dependencies center on corn-derived erythritol, Chinese mogroside extracts, and modified starch systems from Thailand and India. Single-source vulnerability concentrates in steviol glycoside extraction capacity. Distribution runs through e-commerce grocery platforms, retail pharmacy chains, and health-food specialty corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-pantry subscription platforms are collapsing traditional retail gatekeeper economics, creating platform-economics inflection where algorithm-driven personalization interoperability determines brand survival.
For Market Incumbents: Harden supply chain resilience through backward integration into polyol production or captive supply agreements with Thai and Indian modified starch processors. Consolidate R&D capacity around monk fruit-stevia hybrid formulations before EFSA authorization gates clear. Channel control through German Apotheke shelf-space expansion represents the critical defensive lever against e-commerce platform disintermediation. For New Entrants and Emerging Players: Pursue protein-fortified cookie white space in fitness-oriented subscription channels where Quest Nutrition's positioning leaves formulation differentiation opportunities. Maharashtra urban corridors offer the most penetrable geography given glycemic-controlled diet normalization and limited incumbent saturation. Go-to-market execution should anchor on algorithm-matched metabolic profile curation. For Investors and Strategic Acquirers: Regional bakery heritage brands with established clean-label certification infrastructure represent the priority acquisition archetype for platform roll-up strategies. Long-term viability over the coming decade hinges on reformulation agility as WHO guidance on non-sugar sweeteners evolves. The signal to watch is EFSA's systematic re-evaluation timeline for monk fruit health claims.| Strategic Initiative | Industry Significance |
|---|---|
| Monk Fruit Formulation Diversification | Pre-emptive EFSA authorization hedging protects European market entry optionality against regulatory friction. |
| Direct-to-Pantry Subscription Launch | Algorithm-driven personalization matches specialty ingredient preferences to niche metabolic profiles. |
| German Retail Pharmacy Expansion | Apotheke and dm-drogerie markt shelf-space allocation validates functional baked goods channel authorization. |
| Protein-Fortified Cookie Line Extension | Hybrid sugar-free and elevated protein positioning captures fitness-oriented snacking occasions. |
| Clean-Label Certification Investment | Non-GMO and organic verification accelerates premium tier access despite 8-14 month timeline delays. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at retail pharmacy chains, supply planners, and formulation R&D directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA Nutrition Facts filings, EFSA health claim evaluation databases, Nielsen retail audit data, and customs import records. Bottom-up volume modeling and top-down value triangulation cross-verified segment-level outputs.
Scenario-bracketing framed projections across the analysis window through sensitivity testing of regulatory authorization timelines and sweetener cost volatility. Segmentation dimensions modeled include product type, distribution channel, ingredient technology tier, and end-user metabolic need intensity. CAGRs derived from fitted growth curves incorporating diabetic diet normalization rates and e-commerce penetration trajectories. Monk fruit extraction cost decline curves and polyol feedstock price elasticity shaped input assumptions.
Sensitivities concentrate around EFSA authorization delays, WHO guidance revisions on non-sugar sweeteners, and polyol supply chain disruptions. Forecasts reflect documented assumptions subject to revision from regulatory, technological, or macroeconomic shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Cereal Flakes Market
Packaged Foods
North America Pasta Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Tortilla Market
Packaged Foods
Dried Honey Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Dried Soup Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Burritos Market