
 Specialty Bakery Market | 2026-2036
Specialty Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Bakery Market Intelligence
Market Context
Buyer concentration across the foodservice channel is rebalancing as independent cafés and regional restaurant groups fragment procurement previously dominated by national chains. Yamazaki Baking leverages its integrated distribution network across Asian markets to sustain volume leadership in artisan bread lines. Grupo Bimbo anchors North American supply through extensive in-house production of gluten-free and specialty formulations. Associated British Foods competes across European retail and foodservice segments with differentiated premium pastry portfolios.
Technical Definition and Segment Structure
Specialty bakery encompasses baked goods distinguished by premium ingredients, artisan production methods, or targeted dietary specifications such as gluten-free certification, clean-label formulations, and extended fermentation processes, serving both direct consumption and foodservice preparation needs. Artisan breads and gluten-free bread command the strongest margin pools as consumers prioritize provenance and allergen safety in purchasing decisions. Pastries and cakes represent the fastest-growing product type segment, driven by café channel expansion and occasion-based consumption patterns across retail bakeries and catering services. Distribution through online stores and specialty stores captures disproportionate growth as direct-to-consumer and curated retail formats reshape how buyers access premium bakery products.
Regulatory Framework
The FDA governs allergen labeling and GRAS ingredient standards in the United States, while the EU Green Deal and EFSA frameworks drive reformulation toward sustainable sourcing and reduced environmental impact across European production. These regulatory pressures elevate compliance costs but simultaneously create market access advantages for manufacturers with certified clean-label and organic supply chains. Stakeholders must monitor evolving transatlantic regulatory divergence on novel ingredients and carbon accounting methodologies to anticipate competitive repositioning requirements.
Market Dynamics
Clean-label mandates from the FDA and EFSA are forcing simultaneous reformulation across gluten-free, organic, and extended-fermentation product lines, compressing development timelines while opening certified supply chains to premium positioning.
Growth Catalysts
- EU Green Deal carbon accounting:Manufacturers with verified low-carbon wheat sourcing and renewable energy integration in production facilities gain preferential shelf placement in European retail channels.
- Café channel expansion:Urban foodservice operators in the United States are tripling artisan bread SKUs as grab-and-go breakfast occasions migrate from fast-casual chains to independent coffeehouses.
- Sourdough fermentation science:Advances in controlled long-fermentation protocols reduce additive dependencies while delivering the flavor complexity consumers associate with traditional European methods.
Market Restraints
- Specialty flour supply concentration:North American organic wheat milling capacity concentrates among three regional processors, creating input bottlenecks during harvest volatility.
- Almond and coconut flour cost volatility:Gluten-free formulations depend on nut and tropical commodity markets exposed to climate-driven price swings and shipping disruption.
- Extended certification timelines:USDA Organic and Non-GMO Project verification processes stretch 14-18 months, freezing product pipelines for mid-tier manufacturers without pre-qualified supply chains.
Strategic Opportunities
- Direct-to-consumer subscription baking:Curated monthly bread boxes bypass retail slotting fees while capturing lifetime value through recurring revenue models.
- Frozen par-baked artisan distribution:Foodservice operators seek thaw-and-finish solutions that deliver fresh-baked quality without skilled labor at point of sale.
- Upcycled ingredient formulations:Spent grain from craft breweries and fruit pulp from juice processing create differentiated sustainability narratives with input cost advantages.
Industry Challenges
- Artisan baker skill scarcity:Master bread certification programs graduate fewer than 400 candidates annually in the United States against foodservice demand for thousands of production leads.
- Legacy equipment retrofit costs:Transitioning conventional lines to allergen-segregated clean-label production requires six-figure capital outlays for enclosed systems and validated cleaning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Bakery Market |
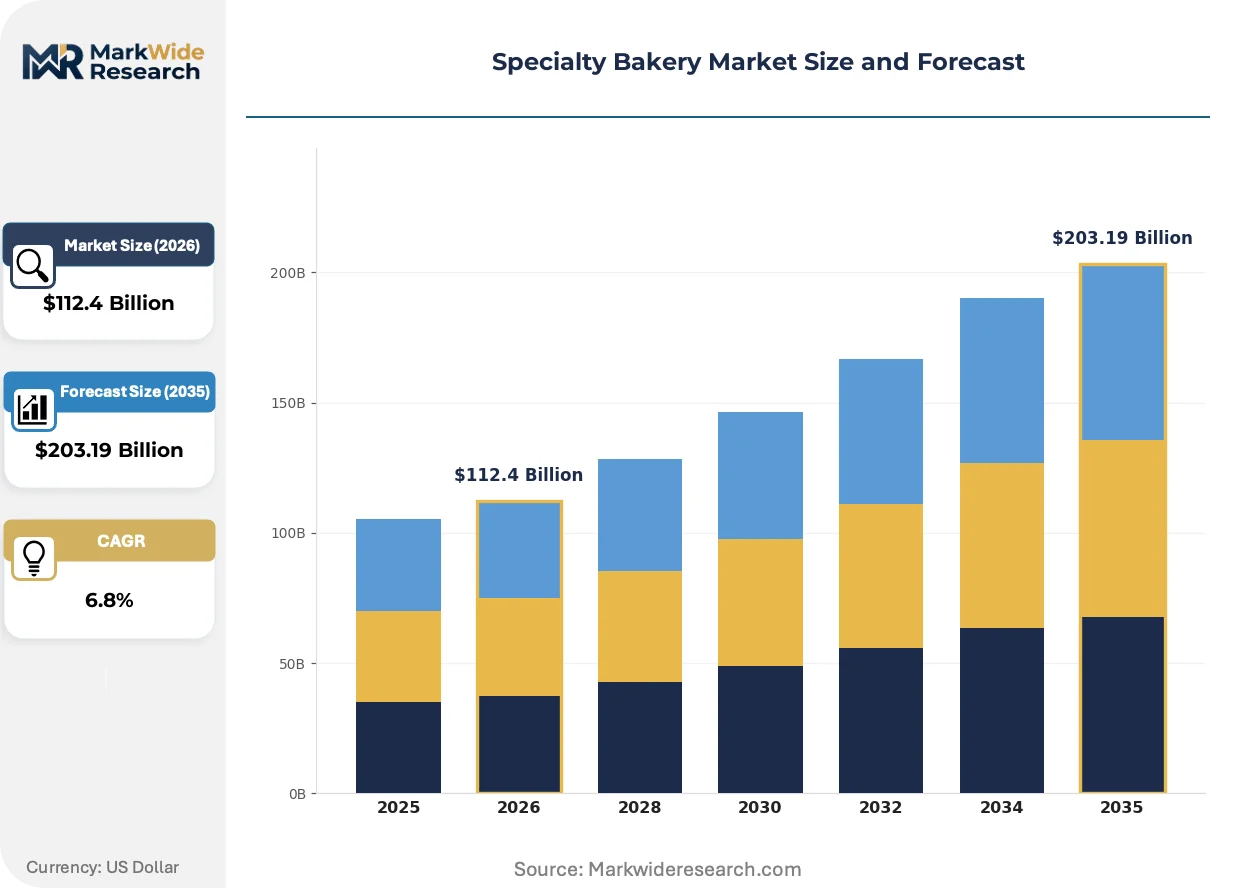
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free Bread, Artisan Breads, Pastries, Cakes End User: Restaurants, Cafés, Retail Bakeries, Catering Services Packaging Type: Bags, Boxes, Trays, Wraps Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Foodservice |
| Companies Covered | Yamazaki Baking, Mondelez International, Grupo Bimbo, Associated British Foods, General Mills, Aryzta, Lantmannen Unibake, Rich Products Corporation, Flowers Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Bakery Market Strategic Shifts & Innovations
Precision fermentation and enzyme engineering are collapsing the trade-off between artisan production timelines and industrial scale, enabling mass-market access to previously niche texture and flavor profiles.
Sourdough starter DNA sequencing and predictive microbiome management is rewriting quality consistency across distributed production networks. Regional bakery chains in Germany and California deploy these tools to replicate flagship product characteristics across franchise locations without centralized commissary dependency. The technology is compressing the artisan-versus-scale dichotomy that previously segmented the market.
EFSA's 2023 updated guidance on novel food enzymes and the FDA's impending rulemaking on fermented ingredient labeling are tightening substantiation requirements for "natural" and "traditional" marketing claims. European manufacturers face reformulation costs for enzyme-assisted sourdough acceleration. North American brands are preemptively building clinical dossiers to defend positioning ahead of enforcement.
Café operators are unbundling pastry procurement from coffee supply agreements, creating standalone RFP processes for artisan bakery categories. This disintermediation fragments volumes previously captured by broadline distributors and opens direct relationships between regional bakeries and multi-unit foodservice accounts. The pattern is most visible in metropolitan markets across the United States and United Kingdom where independent coffeehouse density exceeds chain penetration.
Specialty Bakery Market Segmentation
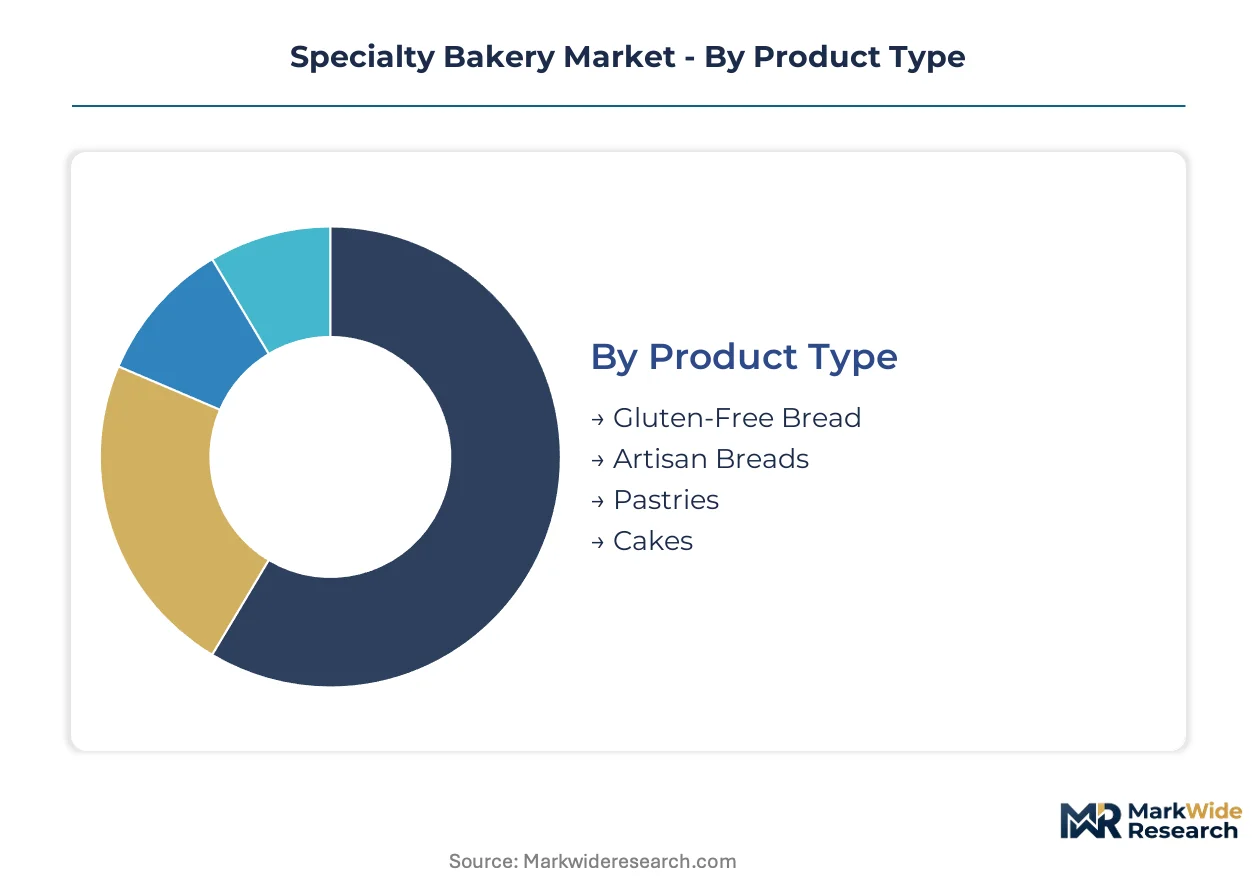
Specialty bakery segmentation reflects divergent paths between mass-market accessibility and premium exclusivity. Each category captures distinct value pools shaped by formulation complexity, service intensity, and channel control requirements.
Product Type:
Customization intensity varies sharply across this category, from standardized gluten-free formulations to highly variable artisan outputs dependent on baker skill and regional ingredient sourcing.
- Artisan Breads:Extended fermentation protocols and heritage grain varieties define specifications. Demand concentrates in United States urban café clusters where sourdough and levain varieties command premium positioning against commodity alternatives.
- Gluten-Free Bread:Rice, tapioca, and almond flour bases require segregated production facilities. European retail channels drive volume as EFSA labeling mandates and coeliac certification programs expand accessible shelf space.
- Pastries:Laminated doughs and filled varieties dominate morning occasion consumption.
- Cakes:Celebration and everyday dessert segments split between scratch bakery and frozen finish-at-home formats.
Mature deployment sits with Artisan Breads. Newer deployment is concentrated in Gluten-Free Bread.
End User:
Volume concentration versus margin capture defines the cost tier structure across this category, with institutional foodservice at one pole and curated retail at the other.
- Cafés:Grab-and-go pastry and breakfast bread occasions drive daily replenishment cycles. United States metropolitan markets exhibit the steepest expansion trajectory as independent coffeehouse density overtakes chain penetration in cities including Portland, Austin, and Denver.
- Restaurants:Bread service and dessert program procurement varies by cuisine type and service level. Fine-dining accounts in France and Italy specify protected-origin flour and traditional method certification.
- Retail Bakeries:Direct consumer relationships enable full-margin capture on custom occasion orders.
- Catering Services:Event-based volume spikes require flexible production scheduling and transport-stable packaging.
Volume leadership rests with Restaurants. Margin expansion concentrates in Cafés.
Packaging Type:
Application requirements span preservation, presentation, and operational efficiency needs across fresh, frozen, and ambient distribution scenarios.
- Bags:Breathable paper and compostable film structures maintain crust integrity for artisan loaves. European supermarket channels in Germany and the Netherlands mandate single-use plastic reduction, accelerating kraft and cellulose adoption.
- Boxes:Rigid structures protect decorated cakes and delicate pastries through last-mile delivery. United Kingdom online bakery subscriptions specify crush-resistant corrugated with moisture barriers.
- Trays:Display-ready formats serve foodservice and retail deli cases.
- Wraps:Cling and parchment variants support foodservice prep and consumer reheating.
Regulatory pressure is reshaping Bags. E-commerce growth is accelerating Boxes.
Distribution Channel:
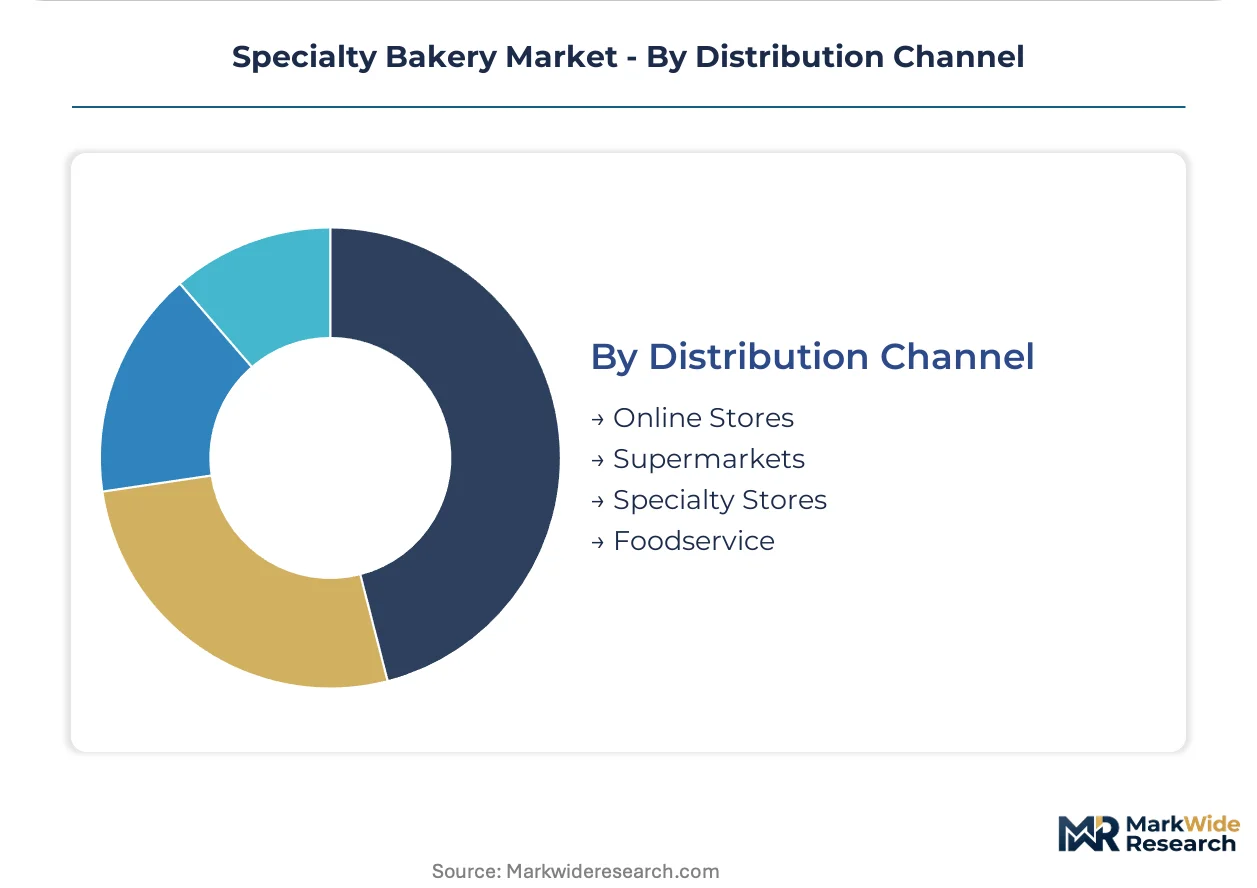
Customer type fragmentation—mass consumer versus curated buyer versus institutional procurement—determines channel strategy and margin architecture.
- Specialty Stores:Curated assortment and knowledgeable staff support premium positioning. Japanese department store food halls and United States natural grocery chains emphasize local bakery provenance and visible production.
- Online Stores:Subscription and direct-to-consumer models bypass retail slotting fees. Frozen par-baked and ambient-stable formats enable United States nationwide shipping from regional production hubs.
- Supermarkets:Central bakery and third-party supplier programs compete on price and placement.
- Foodservice:Broadline distributor and direct bakery relationships serve multi-unit operators.
Established infrastructure dominates Supermarkets. Disproportionate growth concentrates in Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban café density in the United States concentrates specialty bakery procurement more than any other single geography, though regulatory divergence between FDA and EFSA frameworks creates distinct competitive conditions across Atlantic markets.
United States
Independent coffeehouse expansion in Portland, Austin, and Denver drives artisan bread SKU proliferation as grab-and-go breakfast occasions shift from fast-casual chains. FDA allergen labeling mandates and GRAS ingredient standards elevate compliance costs for gluten-free formulations. Brooklyn and San Francisco anchor sourdough innovation clusters where precision fermentation startups partner with regional distributors.
Germany
Heritage grain revival and extended fermentation protocols sustain consumer willingness to pay premium prices for certified traditional methods. EU Green Deal carbon accounting requirements favor bakeries with verified renewable energy integration and regional wheat sourcing. Munich and Berlin host the densest concentration of craft bakery incubators testing enzyme-assisted sourdough acceleration.
Japan
Department store food halls and convenience store premium lines expand accessible distribution for artisan pastries and soft European-style breads. METI standards on food additive disclosure and plastic packaging reduction reshape formulation and presentation requirements. Tokyo's Shibuya and Osaka's Umeda districts concentrate concept bakery flagships targeting younger demographics.
United Kingdom
Online subscription bakery models and direct-to-consumer shipping of frozen par-baked goods capture margin previously lost to retail slotting fees. EFSA novel food enzyme guidance and impending fermented ingredient labeling rules tighten substantiation for "natural" marketing claims. London's Borough Market and Bristol's independent retail clusters sustain provenance-focused purchasing patterns.
France
Protected-origin flour specifications in fine-dining procurement preserve traditional method premiums against industrial competition. REACH and EU Green Deal frameworks drive reformulation toward sustainable sourcing and reduced environmental impact in laminated dough production. Lyon and Bordeaux anchor regional bakery chains deploying DNA sequencing for starter consistency across franchise locations.
Specialty Bakery Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription and frozen par-baked distribution channels previously inaccessible to smaller scale. The vendor base arranges across three tiers: integrated multinationals with captive milling and distribution, regional specialists commanding local provenance premiums, and technology-enabled startups collapsing artisan-scale quality into industrial throughput. Two dominant competitive moves define current positioning: backward integration into specialty flour milling to secure input cost stability, and strategic partnerships with café chains to displace broadline distributor relationships.
Within the integrated multinational tier, Yamazaki Baking and Grupo Bimbo exemplify divergent geographic anchoring strategies. Yamazaki's Asia-Pacific distribution density represents the network-effects archetype where commissary proximity enables daily replenishment cycles. Grupo Bimbo's North American production footprint occupies the scale-certification position, leveraging in-house gluten-free and clean-label capacity to meet FDA and retail chain audit requirements. Associated British Foods sits within the European retail-foodservice hybrid archetype, spanning premium pastry portfolios across EFSA-regulated markets without dominant single-channel dependence.
| Leading Market Players |
|---|
| Yamazaki Baking |
| Mondelez International |
| Grupo Bimbo |
| Associated British Foods |
| General Mills |
| Aryzta |
| Lantmannen Unibake |
| Rich Products Corporation |
| Flowers Foods |
| Others |
Cost & Logistics Intelligence
EU Green Deal carbon accounting requirements gate qualified supply access and premium-tier pricing power across European specialty bakery channels. Manufacturers lacking verified low-carbon wheat sourcing or renewable energy integration face exclusion from preferential shelf placement, compressing margins in conventional tiers while certified players capture price premiums.
Pricing Analysis
Volume leadership in commodity gluten-free bread contrasts with margin concentration in artisan sourdough lines where heritage grain certification commands substantial premiums. Three-tier pricing structure across premium, standard, and economy levels separates clean-label organic formulations from conventional alternatives, with FDA allergen compliance costs driving price differentiation between certified and uncertified production. Pricing pressure stems from almond and coconut flour cost volatility in gluten-free segments, squeezing mid-tier manufacturers without backward integration into specialty milling. Foodservice operators exhibit lowest price sensitivity for frozen par-baked artisan solutions, while retail supermarket channels drive hardest negotiation on standardized SKUs.
Supply Chain Analysis
Domestic-content mandates in EU member states and emerging local-sourcing preferences across United States metropolitan markets are reshaping procurement patterns toward regional wheat origination. North American organic wheat milling concentrates among three regional processors, while European heritage grain revival draws from France, Germany, and Italy. Gluten-free formulations depend on rice from Southeast Asia, almond flour from California, and tapioca from Thailand, exposing margins to climate-driven commodity swings. Single-source vulnerability in specialty flour supply creates bottleneck risk during harvest volatility. Distribution runs through broadline foodservice distributors, direct bakery relationships with café chains, and emerging direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty bakery operates as a supply-constrained market where master baker certification programs graduate fewer than four hundred candidates annually against foodservice demand for thousands of production leads, propping pricing power for qualified operators.
For Market Incumbents: Cement supply security through backward integration into specialty flour milling, capturing input cost stability against harvest volatility and almond flour price swings. Prioritize enzyme-assisted sourdough acceleration R&D to defend positioning against precision fermentation startups collapsing artisan-scale quality into industrial throughput. Lock in multi-year direct supply agreements with expanding independent café chains before broadline distributors renegotiate consolidated contracts.
For New Entrants and Emerging Players: Direct-to-consumer subscription baking offers the most penetrable white-space route, bypassing retail slotting fees while capturing lifetime value through recurring revenue models. Target frozen par-baked artisan distribution to foodservice operators seeking thaw-and-finish solutions without skilled labor investment. Leverage upcycled ingredient formulations from craft brewery spent grain and juice processing fruit pulp to differentiate on sustainability narratives with input cost advantages.
For Investors and Strategic Acquirers: FDA rulemaking completion on fermented ingredient labeling is the leading indicator that enforcement action will consolidate marketing claim substantiation requirements, favoring players with pre-built clinical dossiers. The five-to-ten year viability window favors acquisition of regional specialists commanding local provenance premiums with certified clean-label supply chains and established direct café relationships. Monitor EFSA novel food enzyme guidance implementation pace as signal for European reformulation cost burdens that will separate capitalized from under-resourced competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Milling | Captures input cost stability against North American organic wheat supply concentration and harvest volatility. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fees while building recurring revenue through curated monthly bread box models. |
| Frozen Par-Baked Distribution Expansion | Addresses foodservice labor scarcity with thaw-and-finish solutions for fresh-baked quality at point of sale. |
| Upcycled Ingredient Formulation Development | Creates sustainability differentiation and input cost advantages from brewery spent grain and juice pulp streams. |
| Precision Fermentation Partnership | Collapses artisan-versus-scale dichotomy through enzyme engineering enabling mass-market texture complexity. |
Research Approach
Independent corroboration across primary interviews with artisan bakery owners, foodservice procurement directors, specialty flour mill operators, and clean-label certification consultants underwrites the qualitative findings in this study. Secondary validation draws from FDA GRAS ingredient filings, EFSA novel food enzyme guidance documents, EU Green Deal implementation frameworks, and trade data on organic wheat and almond flour imports. Bottom-up demand modeling from café channel SKU proliferation and top-down supply assessment from milling capacity expansion plans were triangulated to ensure consistency.
Rate-of-change decomposition across the projection horizon separates volume growth in gluten-free formulations from value expansion in artisan premium tiers. The analytical framework models product type, end user channel, packaging format, and distribution channel segmentation alongside fermentation protocol complexity as an industry-specific dimension. CAGRs were derived from trend extrapolation adjusted for regulatory implementation timelines and café channel penetration saturation curves. Forecast inputs include master baker graduation rates, specialty flour processing capacity buildout, and EFSA enforcement probability on fermented ingredient labeling.
The model holds under stable regulatory implementation schedules and continued independent café channel expansion; deviation in FDA rulemaking acceleration or almond crop failure severity would shift volume and value trajectories. Forecasts reflect documented assumptions on certification timeline durations and carbon accounting verification adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Packaged Bread Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Organic Bread Flour Market
Bakery Products
Yeastless Dough Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
United States Bread Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Pastry Dough Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Laminated Dough Market
Bakery Products
Cookies Market