
 Construction Glass Market | 2026-2036
Construction Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Glass Market Intelligence
The gap between conventional float glass and electrochromic smart glazing is narrowing as building codes tighten thermal performance thresholds. Cardinal Glass Industries leverages its vertically integrated fabrication network to dominate high-performance coated products across North American commercial projects. Guardian Glass anchors its position through captive float lines and sputter-coating technology leadership, while Pilkington NSG Group competes on geographic breadth across European and Asian specification markets.
Construction glass comprises silica-based flat glass processed through float, tempering, laminating, or insulating techniques to achieve specified mechanical strength, thermal transmittance (U-value), and solar heat gain coefficients for architectural envelopes. Its primary purpose is to admit daylight while controlling heat transfer, acoustic transmission, and structural loads in building skins. Float glass still occupies the largest volume share but carries thin margins, whereas laminated glass leads value pools as safety and hurricane-code specifications harden across coastal US and Gulf state markets. Insulated glass units are displacing single-pane installations in retrofit-driven European building stock, with facade applications commanding the highest specification intensity per square meter.
The US Department of Energy's building energy codes and EPA ENERGY STAR certification for commercial structures directly shape low-emissivity and triple-glazing demand curves. China's MIIT enforces GB 50189 standards that mandate maximum window-to-wall ratios and thermal performance tiers for public buildings. India's BIS certification for safety glass and the Bureau of Energy Efficiency's ECBC codes are tightening compliance thresholds for new construction. Stakeholders must monitor how carbon-border adjustments and embodied-carbon disclosure rules recalibrate sourcing economics for imported float and processed glass.
Market Dynamics
Building energy codes across major economies are compressing thermal performance thresholds faster than legacy float glass can deliver, forcing a wholesale specification shift toward laminated and coated high-performance products.
Growth Catalysts
- LEED certification thresholds:High-rise commercial towers in the Middle East are expanding glass curtain wall ratios to meet US Green Building Council standards, pulling premium facade specifications into new construction pipelines.
- GB 50189 mandates:China's MIIT-enforced standards for energy-efficient building envelopes are accelerating laminated and insulated glass specifications across new residential developments.
- Smart Cities Mission:Rapid urbanization in India is pulling premium facade glass into metro corridor projects as municipal authorities prioritize modernized infrastructure.
Market Restraints
- Silica sand supply concentration:High-purity silica deposits cluster in limited geographies, exposing float glass producers to input cost volatility and geographic supply risk.
- Natural gas price exposure:Melting furnaces consume substantial energy, making production economics vulnerable to regional utility pricing fluctuations.
- Flat glass margin compression:Commodity float products face thin profitability as capacity expansion outpaces specification-grade demand growth.
Strategic Opportunities
- Electrochromic smart glazing convergence:The performance gap between conventional coated glass and dynamic tinting technologies is narrowing, opening retrofit and new-build specification channels.
- Triple-glazing penetration in European retrofits:Insulated glass units are displacing single-pane installations in aging building stock, with facade applications commanding highest specification intensity.
- Carbon-border adjustment readiness:Embodied-carbon disclosure rules are recalibrating sourcing economics, rewarding regional fabrication networks with lower transport emissions profiles.
Industry Challenges
- Sputter-coating technician scarcity:Advanced low-emissivity deposition requires specialized vacuum technology expertise that outpaces vocational training pipeline output.
- Multi-certification compliance timelines:Products must simultaneously satisfy BIS safety standards, Bureau of Energy Efficiency ECBC codes, and project-specific hurricane-impact ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Glass Market |
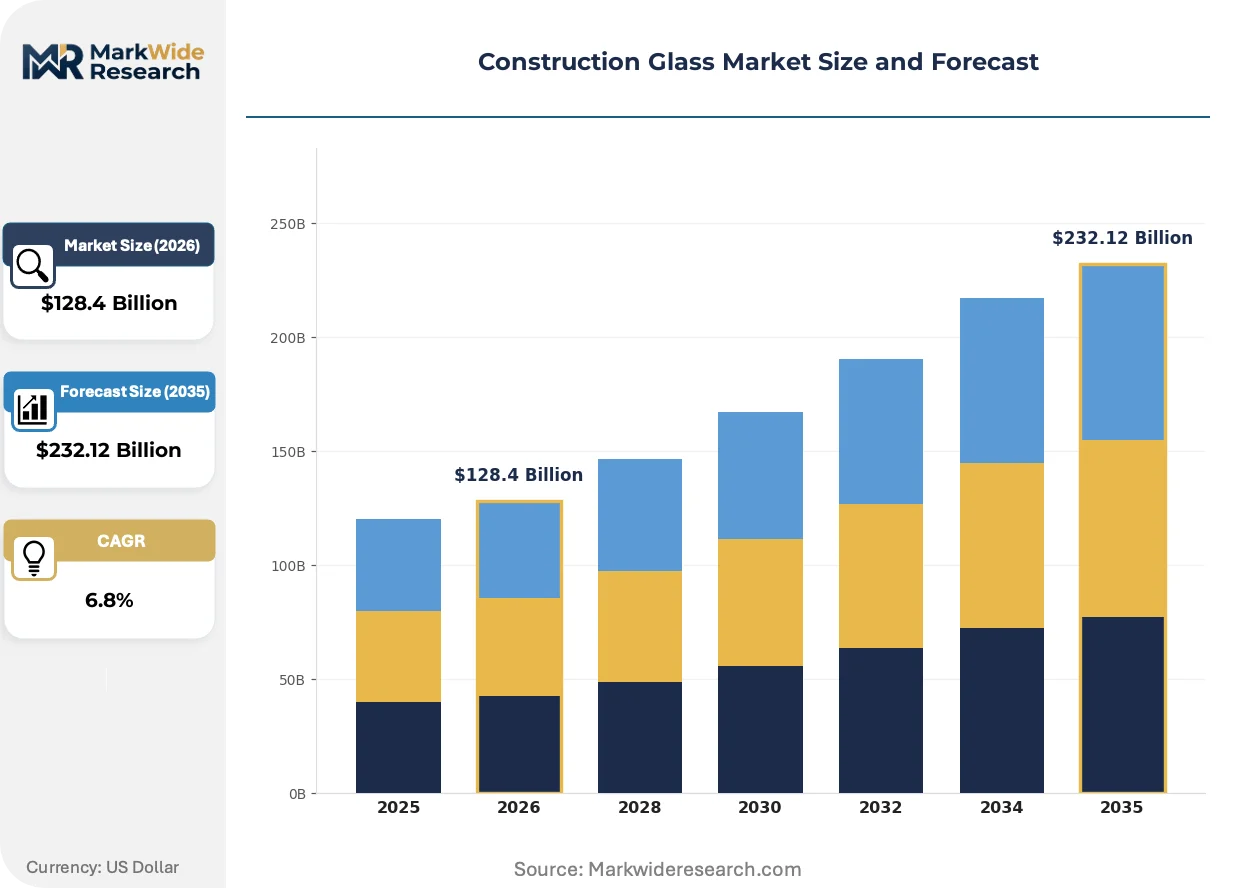
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $232.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Glass, Tempered Glass, Laminated Glass, Insulated Glass Application: Commercial Buildings, Residential Buildings, Curtain Walls, Facades End User: Contractors, Architects, Developers, Fabricators Distribution Channel: Wholesale, Retail, Direct Sales, Online Sales |
| Companies Covered | Oldcastle BuildingEnvelope, Cardinal Glass Industries, Vitro Architectural Glass, SAGE Electrochromics, General Glass International, Guardian Glass, Pilkington NSG Group, Trulite Glass & Aluminum Solutions, Viracon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Glass Market Strategic Shifts & Innovations
Digital specification tools and dynamic glazing technologies are compressing traditional procurement cycles while regulatory tightening forces simultaneous performance upgrades across thermal, safety, and embodied-carbon dimensions.
Electrochromic glazing is digitizing daylight and heat management in commercial envelopes. Large-scale office developers in North America are specifying these systems for atrium and curtain wall applications to eliminate external shading hardware. The technology is digitizing how building operators manage solar heat gain, collapsing energy loads previously addressed through mechanical systems.
China's updated GB standards for energy-efficient building envelopes are mandating maximum window-to-wall ratios and thermal performance tiers for public buildings. MIIT enforcement is accelerating laminated and insulated glass specifications across new residential developments. Developers are responding by consolidating procurement around certified suppliers capable of multi-performance documentation.
Specification decisions are consolidating around embodied-carbon disclosure requirements as project finance increasingly ties to ESG metrics. General contractors are unbundling traditional glass supply agreements to source certified low-carbon products separately from installation services. This pattern is most visible in European commercial retrofits where regulatory pressure combines with green bond financing conditions.
Construction Glass Market Segmentation
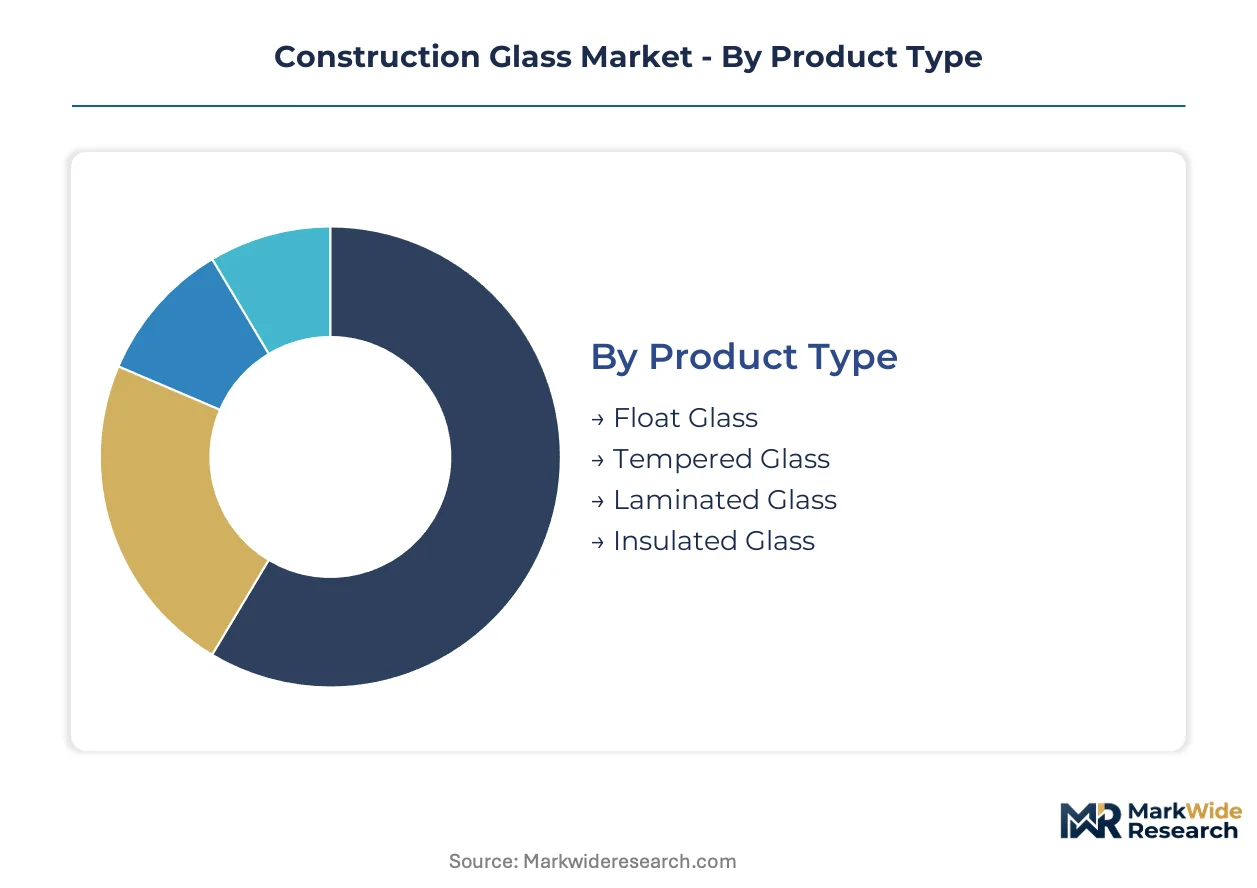
Construction glass segmentation reveals how specification intensity varies across product maturity, application criticality, and procurement channel economics. Distinct margin profiles and compliance requirements shape competitive positioning within each category.
Product Type:
Mature commodity products dominate volume flows while emerging high-performance categories capture specification premiums and code-driven substitution.
- Float Glass:Soda-lime silica formed through the Pilkington float process delivers the base substrate for downstream processing. Demand concentrates in emerging market residential construction where cost sensitivity overrides thermal performance thresholds. MIIT enforcement of GB 50189 standards is compressing its specification share in Chinese public buildings.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies to deliver post-breakage retention and acoustic damping. Hurricane-code jurisdictions across Florida and Gulf Coast states mandate its use in commercial envelopes, pulling premium specifications from safety-conscious developers.
- Tempered Glass:Thermal or chemical strengthening quadruples mechanical resistance for structural glazing applications.
- Insulated Glass:Sealed dual or triple-pane units with inert gas fills and low-emissivity coatings achieve U-values below 1.0 W/m²K.
Float glass retains volume leadership; laminated glass holds the steepest expansion curve.
Application:
Specification intensity escalates with envelope complexity and regulatory exposure, creating tiered procurement patterns across building types.
- Curtain Walls:Non-structural aluminum-framed glazing systems spanning multiple stories demand integrated thermal breaks, pressure-equalized rainscreens, and unitized fabrication. LEED certification thresholds in Dubai and Riyadh commercial towers are expanding glass-to-wall ratios beyond 70%, concentrating premium demand in Middle Eastern high-rise developments.
- Facades:Building-integrated systems combining structural performance with aesthetic intent command the highest engineering intensity per square meter. European retrofit programs targeting 2050 carbon neutrality are displacing single-pane legacy stock with triple-glazed facades in Frankfurt, Milan, and Barcelona commercial districts.
- Commercial Buildings:Office, retail, and hospitality structures with centralized procurement and professional specification teams.
- Residential Buildings:Single and multi-family housing with fragmented buyer decision-making and code-minimum compliance focus.
Curtain walls command specification premiums; facades are climbing fastest on retrofit-driven volume.
End User:
Technical authority and risk allocation determine which stakeholder controls glass specification decisions across project phases.
- Architects:Design-phase specification holders translate envelope performance targets into material selections. India's Smart Cities Mission metro corridor projects in Mumbai and Bangalore concentrate architect-driven premium glazing demand through design-build contracts.
- Developers:Pro forma-driven decision-makers balance first cost against energy modeling outcomes and green bond eligibility. Carbon-border adjustment readiness is recalibrating their sourcing economics toward regional fabrication networks with documented embodied-carbon profiles.
- Contractors:Construction-phase implementers executing specified designs with procurement flexibility on commodity substitutions.
- Fabricators:Value-add processors cutting, coating, tempering, and assembling raw glass into finished systems.
Architects retain specification authority; developers are gaining fastest on ESG-linked financing pressure.
Distribution Channel:
Channel selection tracks project scale, specification complexity, and the buyer's technical capability to assess product conformance.
- Direct Sales:Manufacturer-to-contractor relationships for large commercial projects with custom coating specifications and just-in-time delivery requirements. North American office developers specifying electrochromic atrium systems bypass intermediaries to secure application engineering support.
- Wholesale:Regional distributors stocking standard thicknesses and coatings for construction supply houses serving mid-market contractors.
- Retail:Big-box and specialty outlets reaching residential replacement and small commercial repair segments.
- Online Sales:Digital platforms emerging for standardized cut-to-size tempered and laminated products with documented certifications.
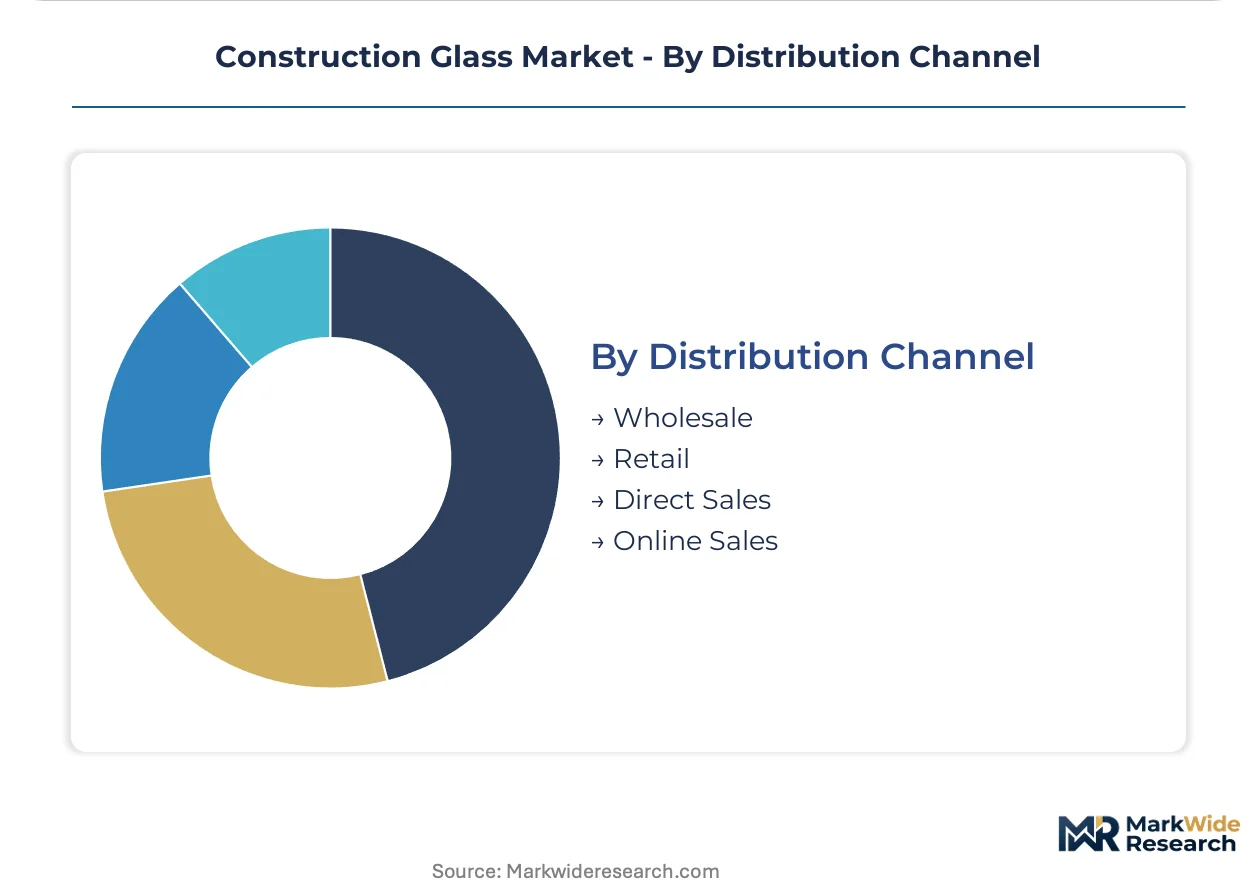
Direct sales capture premium project value; wholesale channels maintain broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports processed float and coated glass to Middle Eastern high-rise developers while Germany supplies precision fabrication equipment to upgrade Asian manufacturing lines. This trade corridor shapes regional competitive positioning.
United States
Hurricane-code mandates across Florida and Gulf Coast states pull laminated glass specifications into commercial envelopes. EPA ENERGY STAR certification for commercial structures shapes low-emissivity demand curves. Miami and Houston construction clusters concentrate premium facade procurement for LEED-targeted towers.
China
MIIT enforcement of GB 50189 standards accelerates insulated glass specifications across new residential developments. The country's dual carbon goals tighten embodied-carbon disclosure requirements for public buildings. Yangtze River Delta fabricators consolidate procurement around certified suppliers capable of multi-performance documentation.
Germany
European retrofit programs targeting carbon neutrality displace single-pane legacy stock with triple-glazed facades. EU Green Deal building renovation wave regulations compress thermal performance thresholds faster than legacy products deliver. Frankfurt and Munich commercial districts command highest specification intensity per square meter.
India
The Smart Cities Mission pulls premium facade glass into metro corridor projects across Mumbai and Bangalore. BIS certification for safety glass and Bureau of Energy Efficiency ECBC codes tighten compliance thresholds for new construction. Delhi-NCR and Hyderabad clusters concentrate architect-driven glazing demand through design-build contracts.
United Arab Emirates
High-rise commercial towers in Dubai and Riyadh expand glass curtain wall ratios to meet LEED certification thresholds. MOHAP building safety standards intersect with US Green Building Council performance benchmarks. Dubai Design District fabrication hubs serve Gulf state developers prioritizing modernized infrastructure.
Construction Glass Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated float-to-fabrication networks and specialized coating technology holders. Three archetypes dominate: captive float line operators with in-house sputter-coating capacity, regional fabrication specialists serving code-specific safety markets, and electrochromic technology developers targeting premium commercial retrofits. Competitive moves concentrate on strategic partnerships for smart glazing distribution and geographic expansion into carbon-border-adjustment-ready regional networks.
Among North American integrated manufacturers, Cardinal Glass Industries and Guardian Glass exemplify the captive production archetype, while Pilkington NSG Group occupies a position spanning European and Asian specification markets. SAGE Electrochromics represents the dynamic glazing specialization tier, anchoring technology convergence between conventional coated products and digitized daylight management systems.
| Leading Market Players |
|---|
| Oldcastle BuildingEnvelope |
| Cardinal Glass Industries |
| Vitro Architectural Glass |
| SAGE Electrochromics |
| General Glass International |
| Guardian Glass |
| Pilkington NSG Group |
| Trulite Glass & Aluminum Solutions |
| Viracon |
| Others |
Cost & Logistics Intelligence
Float glass overcapacity in China's Yangtze River Delta is compressing regional utilization rates below 75%, forcing domestic producers to dump processed glass into Middle Eastern markets and erode pricing discipline across laminated and coated product tiers.
Pricing Analysis
The technology-generation pricing gap between conventional float substrates and electrochromic smart glazing systems is narrowing as sputter-coating scale economies improve. Pricing stratifies across premium, standard, and economy tiers based on thermal performance certification grade and volume scale commitments. Cost compression in commodity float is intensifying because capacity expansion outpaces specification-grade demand growth. Residential developers in India exhibit highest price sensitivity, while LEED-targeted commercial tower developers in Dubai demonstrate lowest sensitivity due to green bond financing conditions.
Supply Chain Analysis
Tariff exposure between China and Gulf Cooperation Council states dominates supply chain risk calculations for processed glass exporters. High-purity silica sand concentrates in Australia, China, and Egypt, while natural gas feedstock for melting furnaces draws from Qatar, Russia, and US shale basins. Single-source vulnerability in low-emissivity coating equipment from German precision manufacturers threatens Asian fabrication expansion timelines. Distribution runs through regional wholesale networks serving mid-market contractors, with direct manufacturer-to-contractor channels capturing large commercial projects requiring just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction glass is entering a cyclical recovery phase as building code enforcement tightens thermal performance thresholds and retrofit-driven replacement cycles accelerate across European and North American building stock.
For Market Incumbents: Insulate margin position by deepening captive float-to-coating integration and securing multi-year offtake agreements with certified low-carbon suppliers ahead of carbon-border adjustment implementation. Electrochromic technology developers represent an emerging entrant threat to conventional coated glass specifications in premium commercial retrofits. Prioritize sputter-coating technician training pipelines to address vacuum technology expertise scarcity.
For New Entrants and Emerging Players: Build out regional fabrication capacity in carbon-border-adjustment-ready networks serving European commercial retrofit demand, where embodied-carbon disclosure rules recalibrate sourcing economics. India's Smart Cities Mission metro corridor projects offer the most penetrable geography for architect-driven premium glazing specifications. Pursue design-build contract partnerships with municipal authorities to bypass entrenched wholesale distribution channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrochromic technology developers with long-term service contracts for dynamic glazing system maintenance. Long-term viability centers on acquisition targets with demonstrated multi-certification compliance capabilities spanning BIS safety standards, Bureau of Energy Efficiency ECBC codes, and project-specific hurricane-impact ratings. Monitor carbon-border adjustment implementation timelines as the critical inflection signal for regional fabrication network valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Sand Supply | Captive high-purity feedstock secures margin protection against Australian and Egyptian deposit volatility. |
| Electrochromic Technology Licensing | SAGE Electrochromics partnerships digitize daylight management for North American atrium specifications. |
| Regional Fabrication Network Expansion | Carbon-border-adjustment-ready EU facilities capture green bond-financed commercial retrofit demand. |
| Multi-Certification Compliance Investment | Simultaneous BIS, ECBC, and hurricane-code documentation opens Indian and Gulf Coast specification channels. |
| Sputter-Coating Technician Training Pipeline | Vacuum technology expertise development addresses critical scarcity constraining low-emissivity capacity expansion. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with glass fabrication plant managers, commercial construction procurement leads, architectural specification directors, and low-emissivity coating equipment engineers; and secondary validation against customs trade databases, USGBC LEED project registries, MIIT GB standards enforcement records, and SEC 10-K filings from publicly traded building materials companies. Bottom-up project pipeline tracking across 12 countries triangulated against top-down regional construction spend estimates.
Forecast inputs considered product type segmentation across float, laminated, tempered, and insulated glass categories; application intensity across curtain wall, facade, commercial, and residential building types; and end-user specification authority patterns among architects, developers, contractors, and fabricators. CAGRs were derived from regression analysis of historical specification shifts against building code tightening trajectories, incorporating natural gas price volatility and silica sand supply concentration as industry-specific forecast inputs across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed float producers or accelerated electrochromic technology cost reduction would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Qatar Facade Market
Building Materials
Drywall Joint Tape Market
Building Materials
Steel Slag Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Composite Decking and Railing Market
Building Materials
Facade Gasket Market
Building Materials
Mass Timber Construction Market
Building Materials
Refractory Cement Market
Building Materials
Qatar Cement Market
Building Materials
Malaysia Architectural Coatings Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Global Builders Joinery and Carpentry of Wood Market