
 Malaysia Architectural Coatings Market | 2026-2036
Malaysia Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Architectural Coatings Market Foresight
Modular tinting and on-site color-matching systems is hardening as the default procurement pattern for mid-scale contractors. Nippon Paint Holdings leverages integrated tinting networks to secure specification loyalty among retail dealers. Jotun anchors premium project bids through marine-grade technology transfer into decorative exterior lines. Smart Asia Chemical competes on volume throughput for public housing tenders.
Architectural coatings are liquid or powder film-forming materials applied to building substrates for protection, decoration, or both, typically comprising binders, pigments, solvents or water carriers, and functional additives at film builds of 25–150 microns dry thickness. Water-based emulsions now dominate interior residential applications due to faster recoat intervals and lower odor profiles, while solvent-based alkyds retain structural share in exterior metal protection where humidity resistance is paramount. Nanotechnology-enhanced formulations command premium positioning in commercial facades requiring self-cleaning or anti-microbial performance.
Malaysia's Department of Standards administers MS 133 for emulsion paints and MS 134 for gloss enamel, with SIRIM QAS International conducting third-party certification for eco-labeling claims under the national Green Label program. The Ministry of Housing and Local Government ties affordable housing material approvals to VOC content thresholds, channeling procurement toward compliant suppliers. Stakeholders must monitor enforcement tightening on formaldehyde and heavy metal limits, as these standards will determine which formulation portfolios retain eligibility for government-backed construction programs.
Market Dynamics
Malaysia's Department of Standards is compressing formulation flexibility through MS 133 and MS 134 enforcement, forcing manufacturers to reconstitute product portfolios around low-VOC binders while maintaining humidity-resistant performance thresholds demanded by coastal construction clusters.
Growth Catalysts
- Selangor-Johor residential pipeline:High-rise and mixed-use developments across the Klang Valley corridor are pulling water-based interior emulsions into specification sheets at accelerating volumes.
- MS 133 compliance pathway:The national emulsion paint standard is channeling procurement toward certified suppliers eligible for Ministry of Housing and Local Government affordable housing programs.
- Nano-additive penetration:Self-cleaning and anti-microbial surface technologies are opening premium positioning in commercial facade maintenance contracts.
Market Restraints
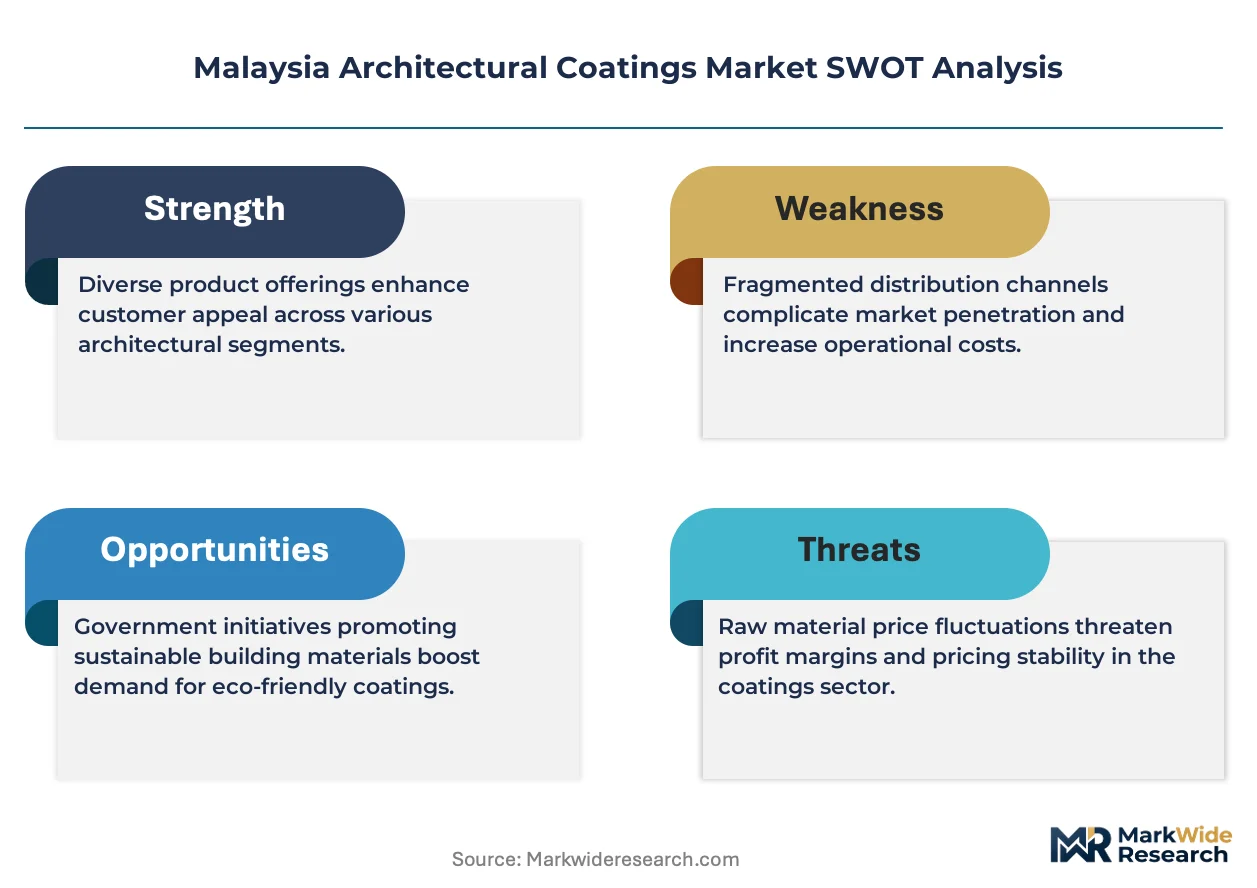
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin buffers for mid-scale formulators serving public housing tenders.
- Solvent-based alkyd dependency:Exterior metal protection specifications in Penang and Malacca retain structural share for humidity-resistant solvent carriers, complicating full portfolio transition.
- SIRIM QAS certification lag:Third-party eco-label verification timelines extend product launch cycles by four to six months.
Strategic Opportunities
- Johor Bahru-Singapore corridor:Cross-border logistics infrastructure supports export-oriented production scale for Indonesian and Thai project markets.
- Modular tinting networks:On-site color-matching systems are creating specification loyalty among mid-scale contractors previously served by generic bulk supply.
- Green Label procurement mandates:Government-backed construction programs are tightening VOC thresholds, advantaging early-compliant formulation portfolios.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in low-VOC binder chemistry remains concentrated among senior technical staff at established manufacturers.
- Legacy solvent inventory stranding:Distributors face working capital pressure from alkyd stockpiles as water-based specifications accelerate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Architectural Coatings Market |
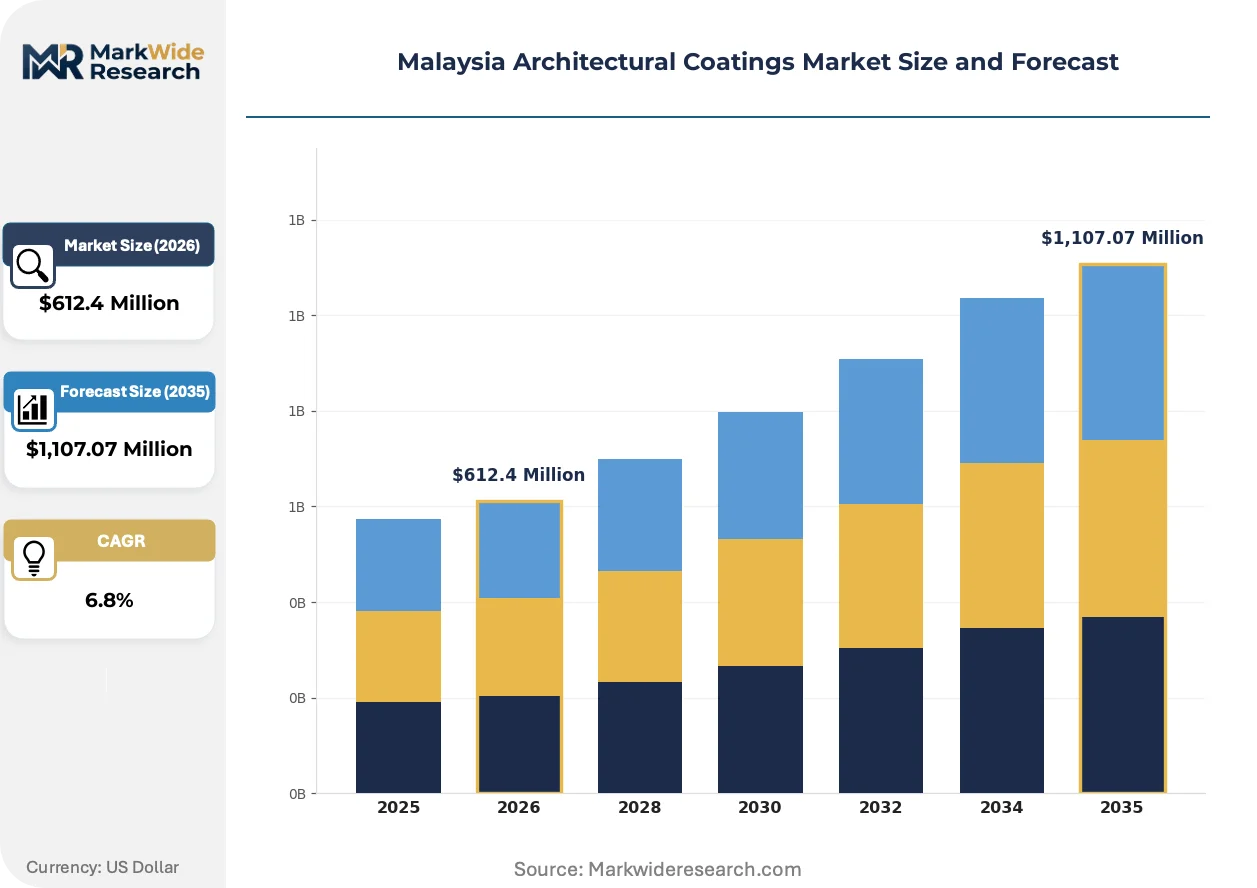
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Powder Coatings, UV-Cured End User: Residential, Commercial, Institutional, Industrial Application: Interior, Exterior, Protective, Decorative Technology: Nanotechnology, Eco-Friendly, High-Performance, Conventional |
| Companies Covered | Nippon Paint Holdings, PPG Industries, Jotun, Smart Asia Chemical, SKK (Malaysia) Sdn Bhd, Akzo Nobel, TOA Paint Public Company Limited, Smart Paint Manufacturing, Kansai Paint, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Architectural Coatings Market Shifts & Advancements
Water-based emulsion technologies are compressing the competitive set around rapid-recoat performance and odor-minimized interior applications, while regulatory pressure on formaldehyde and heavy metal content is narrowing eligible supplier pools.
Photocatalytic titanium dioxide surface treatments are absorbing specification share in commercial facade maintenance contracts across Kuala Lumpur and Petaling Jaya. Property management firms are specifying nano-enhanced coatings for high-traffic atriums and healthcare-adjacent mixed-use developments. The technology is absorbing premium positioning previously held by conventional silicone-modified acrylics.
Malaysia's Department of Standards is tightening enforcement on MS 134 gloss enamel specifications, with draft amendments targeting stricter heavy metal limits. Formulators are pre-emptively reformulating alkyd lines to retain SIRIM QAS certification eligibility. Metal protection applications in coastal Johor and Sabah face the steepest compliance recalibration.
Mid-scale contractors are consolidating purchase orders around integrated tinting service providers, displacing fragmented bulk-paint procurement. Retail dealer networks with on-site color-matching capabilities are capturing specification loyalty previously distributed across generic distributors. The pattern concentrates in Selangor's secondary township developments where finish consistency commands premium pricing.
Malaysia Architectural Coatings Market Segmentation
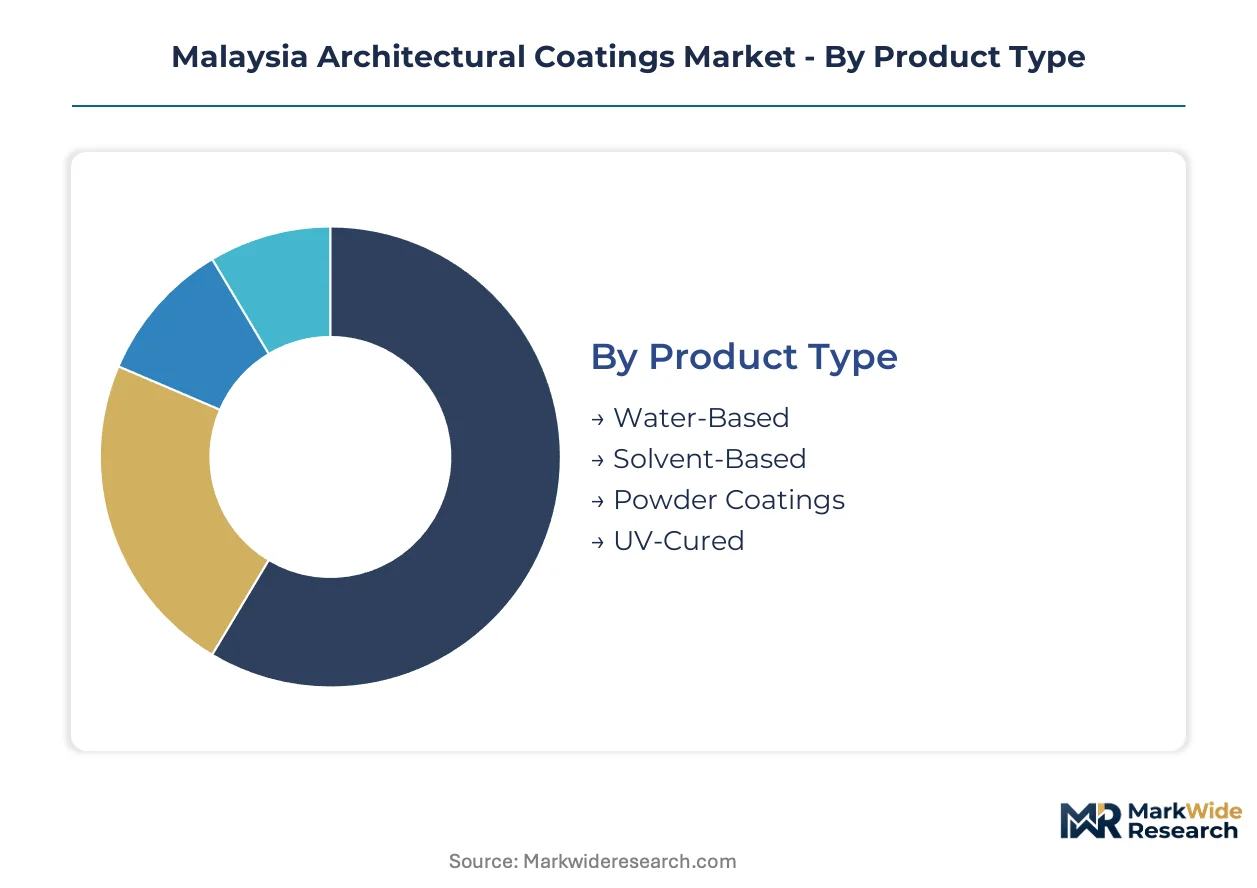
Architectural coatings in Malaysia fragment across formulation chemistry, end-use requirements, and performance specifications. Each segmentation axis reveals distinct procurement patterns, regulatory exposure, and margin structures that determine supplier positioning across Selangor's high-rise corridors and Johor's coastal industrial zones.
Product Type:
Formulation chemistry separates buyers by compliance burden, application speed, and substrate compatibility.
- Water-Based:Acrylic and vinyl-acrylic emulsions carry 30-50% lower VOC content than solvent alternatives, aligning with MS 133 certification requirements for Ministry of Housing affordable housing programs. Demand concentrates in Klang Valley residential towers where rapid recoat intervals and minimal odor disruption command specification priority.
- Solvent-Based:Alkyd and polyurethane formulations retain structural share in exterior metal protection across Penang and Malacca, where humidity resistance and adhesion to weathered substrates outweigh water-based performance limitations. Coastal industrial facilities in Johor specify solvent carriers for structural steel maintenance cycles.
- Powder Coatings:Thermoset epoxy-polyester hybrids serve factory-applied architectural metalwork with zero VOC emissions and superior chip resistance.
- UV-Cured:Acrylic oligomer systems penetrate niche wood finishing and specialty flooring applications requiring instant cure and high film build.
Water-based leads volumes today; nanotechnology-enhanced water systems are gaining share fastest.
End User:
Project scale and procurement authority determine specification control and pricing leverage.
- Residential:High-rise developers across Selangor and Johor dominate volume absorption, with master developers mandating MS 133-compliant emulsions across entire township portfolios. Finish consistency requirements drive consolidation around integrated tinting service providers.
- Commercial:Mixed-use developers in Kuala Lumpur and Petaling Jaya specify photocatalytic and anti-microbial facade treatments for premium positioning. Property management firms absorb lifecycle cost calculations that justify 40-60% formulation premiums.
- Institutional:Government hospitals and schools channel procurement through Bumiputera vendor mandates with SIRIM QAS certification prerequisites.
- Industrial:Manufacturing facilities in Port Klang and Pasir Gudang prioritize protective coating systems for corrosion prevention in chemical exposure environments.
Residential commands absolute volume; commercial applications show steepest expansion trajectory.
Application:
Exposure conditions and aesthetic requirements split the market between climate resilience and interior finish refinement.
- Interior:Water-based emulsions with low-odor profiles and rapid recoat capability dominate Selangor residential towers. Contractors specify scrub-resistant acrylics for high-traffic common areas in mixed-use developments.
- Exterior:Elastomeric acrylics and silicone-modified systems serve tropical monsoon exposure across coastal Johor and Sabah. UV degradation resistance and fungal resistance determine specification survival.
- Protective:Epoxy and polyurethane systems protect structural steel in industrial zones and marine-adjacent infrastructure.
- Decorative:Texture coatings and metallic effects differentiate premium residential and hospitality projects in Kuala Lumpur's luxury segment.
Interior applications absorb majority volume; exterior nanotechnology treatments are expanding most quickly.
Technology:
Performance tier and environmental positioning separate commodity supply from premium specification capture.
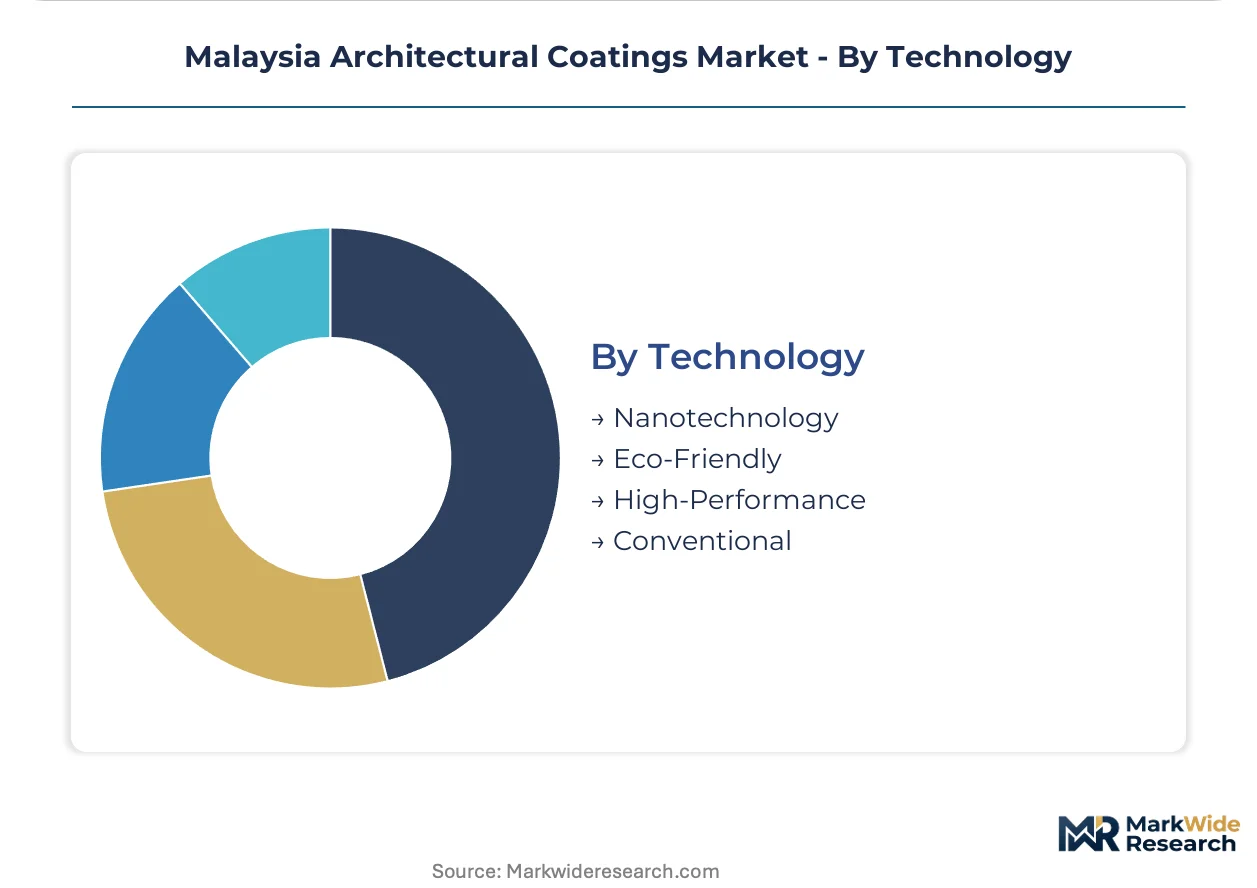
- Nanotechnology:Photocatalytic titanium dioxide and silver-ion antimicrobial additives command 50-80% price premiums in commercial facade and healthcare-adjacent applications. Self-cleaning functionality reduces maintenance labor costs for property management firms in Kuala Lumpur's central business district.
- Eco-Friendly:Low-VOC and zero-formaldehyde formulations align with Green Label procurement mandates and Ministry of Housing material approvals. SIRIM QAS certification creates eligibility barriers for non-compliant competitors.
- High-Performance:Fluoropolymer and polysiloxane systems serve extreme durability requirements in coastal and industrial exposure zones.
- Conventional:Standard acrylic and alkyd formulations retain cost-driven public housing and maintenance repaint segments.
Conventional technology leads installed base; eco-friendly formulations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's architectural coatings industry traces its modern scale to post-independence industrialization programs of the 1960s and 1970s, when import substitution policies nurtured domestic paint manufacturing around Port Klang and the Klang Valley. Federal infrastructure spending and township development schemes subsequently concentrated production capacity in Selangor and Johor.
Selangor
High-rise residential towers across Petaling Jaya and Subang Jaya absorb the majority of water-based interior emulsion volumes. The Ministry of Housing and Local Government ties affordable housing material approvals to MS 133 compliance, channeling procurement toward certified suppliers. Klang Valley master developers mandate integrated tinting systems across entire township portfolios to ensure finish consistency.
Johor
Coastal industrial facilities and cross-border logistics infrastructure support export-oriented production scale for Indonesian and Thai project markets. The Department of Standards enforces humidity-resistant performance thresholds through MS 134 gloss enamel specifications. Iskandar Malaysia's special economic zone status attracts manufacturing investment serving Singapore-linked construction demand.
Penang
Heritage conservation requirements and humid tropical exposure sustain structural demand for solvent-based alkyd formulations in exterior metal protection. The state's manufacturing base generates protective coating requirements for semiconductor fabrication facilities and port infrastructure. George Town's UNESCO buffer zone imposes aesthetic guidelines that favor traditional finish specifications.
Sabah
Marine-adjacent infrastructure and coastal industrial zones drive specifications for UV degradation-resistant and fungal-resistant exterior systems. Federal development allocations under the Malaysia Plan channel public housing construction toward compliant low-VOC suppliers. Kota Kinabalu's expanding mixed-use developments absorb premium nano-enhanced facade treatments.
Malacca
Tourism-driven hospitality construction and heritage restoration projects create segmented demand across decorative texture coatings and conventional maintenance repaint. The state's industrial corridor along the Strait of Malacca requires protective systems for chemical exposure environments. Historic city center conservation guidelines influence procurement patterns toward approved color palettes and finish standards.
Malaysia Architectural Coatings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and specification control, with SIRIM QAS certification creating eligibility barriers that separate compliant portfolios from generic supply. The vendor base concentrates around integrated tinting networks and marine-grade technology transfer capabilities. Three archetypes dominate: multinational coating specialists with regional R&D facilities, domestic volume producers serving public housing tenders, and integrated chemical groups with captive resin supply. Competitive dynamics center on formulation chemist recruitment and backward integration into water-based binder production.
Within the multinational specialist tier, Nippon Paint Holdings and Jotun occupy positions defined by specification loyalty mechanisms and technology transfer capabilities. Nippon Paint Holdings exemplifies integrated tinting network dominance, while Jotun represents marine-grade expertise migration into decorative exterior lines. Smart Asia Chemical sits within the domestic volume-producer archetype, competing on throughput scale for government-backed construction programs. These three companies anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Nippon Paint Holdings |
| PPG Industries |
| Jotun |
| Smart Asia Chemical |
| SKK (Malaysia) Sdn Bhd |
| Akzo Nobel |
| TOA Paint Public Company Limited |
| Smart Paint Manufacturing |
| Kansai Paint |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap formulators across Selangor and Johor anchor production capacity, translating generational cost discipline into pricing stability that resists volatile titanium dioxide feedstock swings. Their consolidated ownership structures enable long-term supply contracts with Port Klang resin distributors, insulating margin buffers against spot-market pigment pressure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SIRIM QAS-certified nano-enhanced formulations from generic bulk supply. Price differentiation hinges on certification grade and volume scale, with government-backed affordable housing tenders compressing mid-tier margins. Pricing pressure stems from titanium dioxide cost volatility, which squeezes formulators serving public housing programs. Economy-tier buyers exhibit highest price sensitivity, while commercial facade developers absorbing lifecycle cost calculations show lowest.
Supply Chain Analysis
Freight cost differentials between Klang Valley distribution hubs and Johor Bahru export corridors influence plant location decisions for Indonesian and Thai market access. Supply concentrates in Malaysia, China, and Thailand, with binder chemistry and titanium dioxide pigment as critical inputs. Single-source vulnerability in specialty resin feedstocks poses structural risk. Distribution runs through integrated tinting networks that displace fragmented bulk-paint procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's architectural coatings market functions as a stable compounder, with Ministry of Housing procurement mandates delivering predictable volume pipelines across electoral cycles.
For Market Incumbents: Extend integrated tinting network coverage into secondary township developments across Selangor's periphery, capturing specification loyalty from mid-scale contractors consolidating purchase orders. Deepen backward integration into water-based acrylic binder production to offset titanium dioxide cost volatility. MS 133 enforcement tightening represents the primary regulatory threat requiring pre-emptive reformulation investment. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer lowest-friction entry into the modular tinting segment, bypassing entrenched dealer networks. Target Johor Bahru-Singapore corridor cross-border logistics for export-oriented production scale. White-space concentrates in nano-enhanced facade treatments for commercial mixed-use developments, where property management firms prioritize lifecycle cost over upfront price. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic volume producers with captive public housing tender relationships and SIRIM QAS certification eligibility. Long-term viability frames around formulation chemist scarcity concentration and Green Label procurement mandate expansion. Watch Department of Standards draft amendments on heavy metal limits as inflection signal for compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Resin Production | Captive binder supply insulates margin buffers against titanium dioxide feedstock volatility. |
| Integrated Tinting Network Expansion | On-site color-matching capabilities lock specification loyalty among consolidating mid-scale contractors. |
| SIRIM QAS Certification Investment | Eco-label eligibility secures Ministry of Housing affordable housing program procurement access. |
| Nano-Additive Formulation Development | Photocatalytic titanium dioxide commands premium positioning in Kuala Lumpur commercial facade contracts. |
| Johor Bahru Export Corridor Capacity Buildout | Cross-border logistics infrastructure captures Indonesian and Thai construction project demand. |
Research Methodology
Coverage spans Selangor, Johor, Penang, Sabah, and Malacca, with primary inputs from each regional production cluster. The approach combines interviews with plant managers, procurement leads at master developers, distribution channel partners, and technical R&D directors with secondary validation through Department of Standards filings, SIRIM QAS certification databases, customs trade data, and Ministry of Housing procurement records. Bottom-up volume builds and top-down market sizing triangulate to produce segment-level outputs.
Granularity extends to formulation chemistry, end-use application, performance technology tier, and regional production hub across the projection horizon. The analytical framework models water-based emulsion penetration rates, nano-additive adoption curves, and solvent-based alkyd displacement patterns. CAGRs derive from regression analysis against construction completion data and regulatory compliance timelines. Forecast inputs include titanium dioxide price indices and Green Label procurement mandate expansion scenarios.
The model assumes a particular technology adoption path; alternative pathways for photocatalytic nano-enhanced systems would alter the outlook if cost curves flatten faster than projected. Forecasts reflect assumptions on MS 133 enforcement intensity and formaldehyde limit tightening schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
North America Architectural Coatings Market
Building Materials
Cement Market
Building Materials
Engineered Stone Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Dry Mix Mortar Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Dutch Brick Market
Building Materials
United Kingdom White Cement Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Sprayed Concrete Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
Block Paving Market
Building Materials
India Concealed Cistern Market
Building Materials
West Africa Cement Market
Building Materials
Recycled Construction Aggregates Market