
 Drywall Joint Tape Market | 2026-2036
Drywall Joint Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Drywall Joint Tape Market Insights
Premium-grade fiberglass mesh specifications is unwinding across commercial drywall specifications as architects specify higher crack-resistance ratings. Saint-Gobain leverages its mineral wool and glass fiber upstream capabilities to control raw material quality for tape substrates. USG Corporation anchors North American distribution through dedicated contractor supply channels. Strait-Flex specializes in composite corner bead and tape hybrid systems that reduce labor steps on large jobsites.
Drywall joint tape consists of paper, fiberglass, or synthetic mesh strips applied over seams between gypsum board panels to prevent cracking and create smooth finished surfaces, typically measuring two inches in width and designed to bond with joint compound through mechanical embedding or adhesive backing. The product serves the essential function of reinforcing gypsum panel joints against structural movement and thermal expansion in interior wall assemblies. Fiberglass mesh tape commands expanding share in residential construction applications where self-adhesive technology reduces skilled labor hours, while paper tape retains dominance among traditional contractors in renovation projects where multi-coat finishing remains standard practice. Alkali-resistant formulations are gaining specification in commercial construction where cement board substrates and synthetic stucco systems require corrosion-stable reinforcement.
EPA regulations on volatile organic compound emissions from construction materials shape adhesive formulation requirements for self-adhesive tape variants, while OSHA workplace exposure standards influence manufacturer investment in dust-suppression coatings for mesh products. ASTM C475 and C474 standards govern tensile strength and joint treatment performance, creating compliance barriers for imported generic products. Stakeholders must monitor evolving building code adoption of Level 5 finish specifications across municipalities, as this finish class demands superior tape performance under critical lighting conditions.
Market Dynamics
Residential construction velocity in the American Sun Belt is compressing installation timelines, forcing contractors toward self-adhesive mesh systems that eliminate embedding coat cycles and reduce skilled labor dependency.
Growth Catalysts
- OSHA silica exposure limits:Tighter workplace dust standards are accelerating specification of pre-coated mesh tapes that suppress airborne particulates during sanding operations.
- Level 5 finish mandates:Municipal building code adoption of critical-lighting finish classes in commercial interiors is elevating performance requirements for crack-resistant reinforcement systems.
- Cement board substrates:Synthetic stucco and exterior insulation finish systems in commercial construction are pulling alkali-resistant fiberglass formulations into specification sheets.
Market Restraints
- Glass fiber supply concentration:Upstream mineral wool and glass fiber production clusters in specific manufacturing corridors create raw material bottleneck risks for tape substrate supply.
- Multi-generational contractor preference:Established finishing crews maintain allegiance to paper tape and embedding compound techniques learned through apprenticeship pipelines.
- Joint compound cost volatility:Gypsum and petroleum-based additive price swings compress margin predictability for contractors bundling tape with compound systems.
Strategic Opportunities
- Prefabricated wall panel integration:Off-site construction factories in Texas and Florida represent untapped demand for pre-applied joint reinforcement systems.
- EPA VOC emission credits:Low-VOC adhesive formulations qualify for federal procurement preference programs in government building contracts.
- Composite corner hybrid systems:Convergence of tape and bead functions into single-application products opens specification in large-scale multifamily developments.
Industry Challenges
- ASTM C475 certification timelines:Third-party testing protocols for tensile strength validation create six-to-nine month product qualification delays for formulation changes.
- Skilled taper workforce contraction:Aging journeyman demographics and reduced vocational training pipeline output constrain installation quality consistency across regional contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drywall Joint Tape Market |
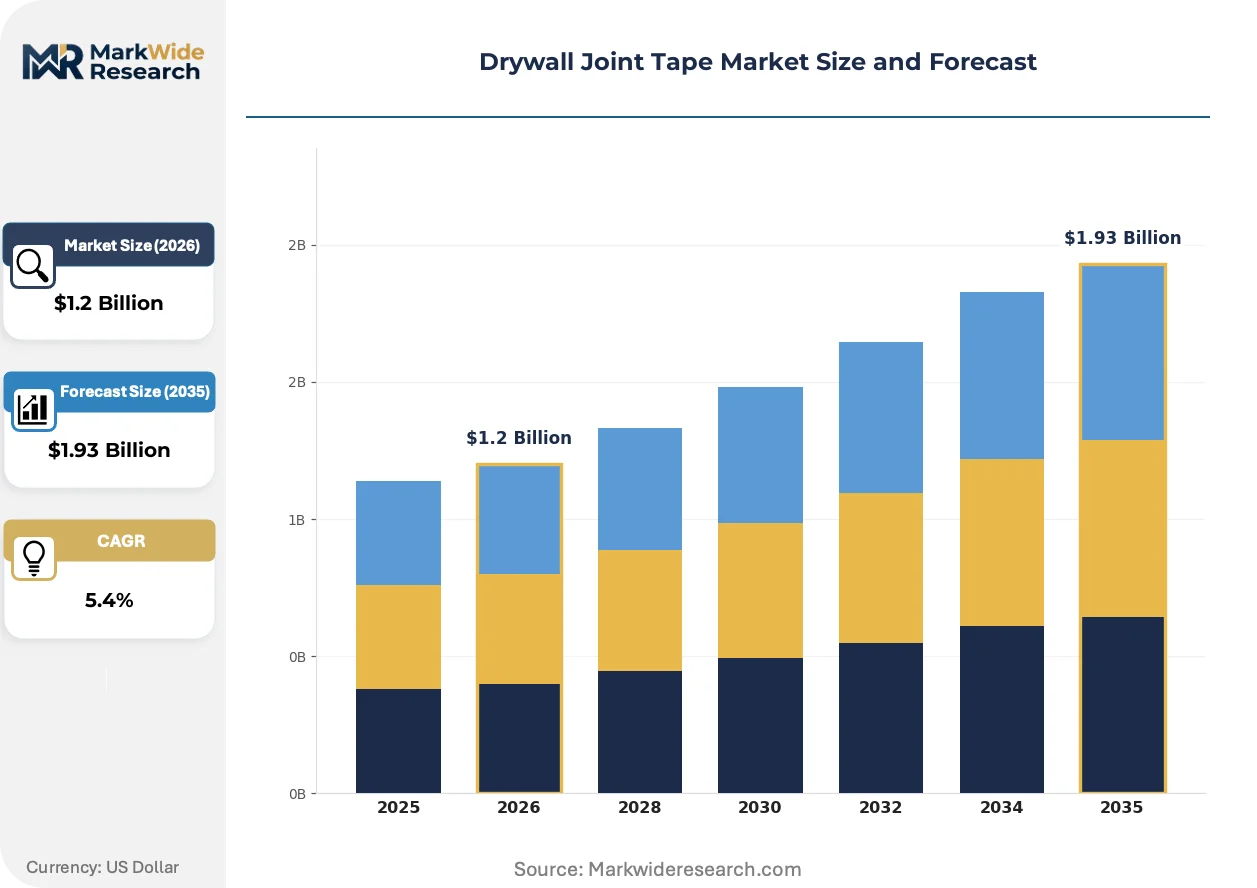
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.93 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Tape, Fiberglass Tape, Mesh Tape, Plastic Tape Technology: Self-Adhesive, Non-Adhesive, Alkali-Resistant, Pressure-Sensitive Application: Residential Construction, Commercial Construction, Renovation Projects, Interior Decoration End User: Contractors, Drywall Installers, Paint & Decorating Firms, Construction Material Suppliers |
| Companies Covered | CertainTeed Corporation, Strait-Flex, USG Corporation, Shurtape Technologies, Grip-Rite, Saint-Gobain, Sherwin-Williams Company, Scapa, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drywall Joint Tape Market Trends and Innovations
Product formulation and application methodology are diverging along contractor demographic lines, with technology-enabled installation systems gaining ground among emerging workforce entrants while traditional methods retain hold among established trades.
Self-adhesive fiberglass mesh tape is decomposing the traditional three-coat embedding process into a single-pass application. Residential contractors in Arizona and Nevada are specifying these systems on over half of new single-family starts. The technology is compressing skilled labor hour requirements per unit and flattening the experience curve for apprentice finishers.
EPA volatile organic compound regulations for construction adhesives are forcing reformulation of pressure-sensitive tape backings. Manufacturers are substituting water-based acrylic systems for solvent-borne alternatives. Self-adhesive mesh variants face the steepest compliance redesign burden due to their adhesive-dependent installation mechanism.
Direct contractor supply arrangements are displacing traditional two-step distribution through building material dealers. Large regional drywall contractors in Georgia and North Carolina are negotiating volume commitments directly with tape manufacturers. This channel compression is most visible in the Sun Belt states where housing start concentration creates procurement scale advantages for consolidated contractor networks.
Drywall Joint Tape Market Segmentation
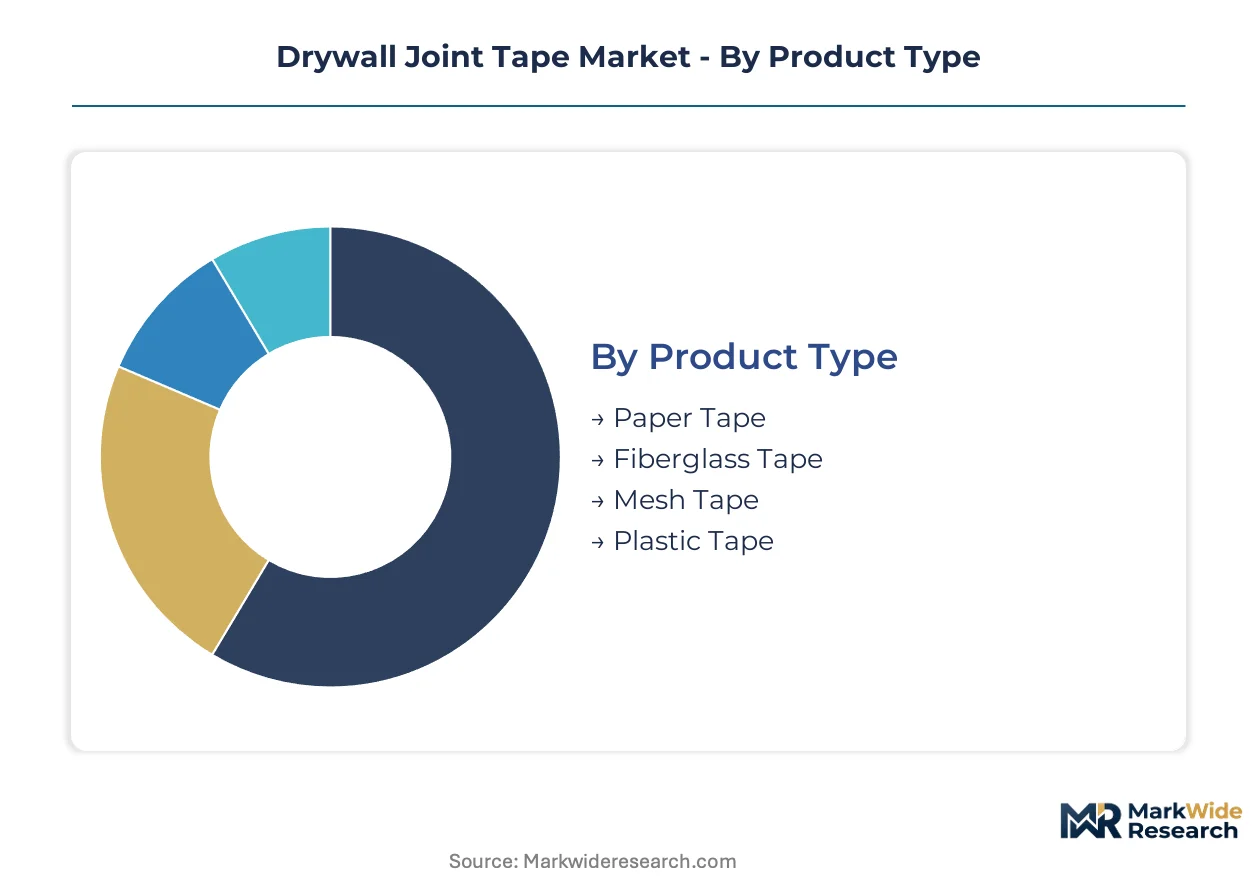
Drywall joint tape segmentation reveals divergent margin structures across substrate technologies and installation methods. Product type and technology categories command premium pricing through formulation complexity, while application and end-user segments distribute volume across residential velocity and commercial specification intensity.
Product Type:
Margin pools concentrate in fiberglass and mesh substrates where alkali-resistant coatings and self-adhesive backings justify price premiums over commodity paper grades.
- Paper Tape:Traditional cellulose-based substrate embedded in joint compound through three-coat application cycles. Demand concentrates among renovation contractors in the American Midwest where multi-generational finishing crews maintain apprenticeship-trained techniques and resist adhesive-backed alternatives.
- Fiberglass Tape:Woven glass fiber construction delivers tensile strength ratings exceeding ASTM C475 minimums. Sun Belt residential contractors in Arizona and Texas specify this substrate on over half of new single-family starts where speed-to-drywall-completion compresses project timelines.
- Mesh Tape:Open-weave synthetic construction with self-adhesive backing eliminates embedding coat requirements. Demand is climbing fastest among emerging workforce entrants lacking traditional taper apprenticeship training.
- Plastic Tape:Polymer-based flexible strip engineered for high-movement joints and synthetic stucco systems. Cement board substrate specifications in Florida commercial exteriors pull this segment into EIFS assemblies.
Paper tape holds installed capacity across renovation-heavy markets. Mesh tape is rotating up the share rankings in new residential construction.
Technology:
Application method determines labor cost absorption, with adhesive-backed systems capturing contractor preference where skilled taper availability constrains crew scaling.
- Self-Adhesive:Pressure-sensitive backing bonds directly to gypsum panel seams without embedding compound. Georgia and North Carolina contractors negotiate direct manufacturer supply arrangements to secure volume pricing on this labor-reducing technology.
- Non-Adhesive:Conventional substrate requiring mechanical embedding in wet joint compound. Established finishing crews in the Northeast maintain specification allegiance where multi-coat finishing remains quality-assurance standard practice.
- Alkali-Resistant:Corrosion-stable coating protects glass fiber integrity against cement board alkalinity. Synthetic stucco and EIFS specifications in commercial construction across the Sun Belt drive specification intensity for this formulation.
- Pressure-Sensitive:Enhanced adhesive chemistry delivering immediate tack strength for vertical and overhead applications. OSHA silica exposure compliance is accelerating specification of pre-coated variants that suppress airborne particulates during sanding operations.
Non-adhesive systems retain legacy specification in renovation markets. Self-adhesive technology is expanding most quickly through residential new-build channels.
Application:
Velocity differentiates segment economics, with residential construction compressing installation timelines and commercial projects demanding performance certification under critical lighting.
- Residential Construction:High-volume single-family and multifamily developments where installation speed determines crew productivity metrics. Prefabricated wall panel factories in Texas and Florida represent emerging demand for pre-applied joint reinforcement systems.
- Commercial Construction:Level 5 finish mandates in municipal building codes elevate crack-resistance requirements for reinforcement systems under critical lighting conditions. Alkali-resistant formulations gain specification where cement board substrates dominate exterior assemblies.
- Renovation Projects:Existing structure retrofit work where substrate condition variability demands adaptable finishing techniques. Paper tape retains dominance among traditional contractors where matching existing texture patterns requires multi-coat embedding expertise.
- Interior Decoration:Aesthetic finish applications including feature walls and architectural detail work. Paint and decorating firms in high-end residential markets specify premium mesh systems for seamless surface preparation.
Renovation projects hold installed capacity through contractor demographic inertia. Residential construction is gaining share fastest through housing start velocity in the Sun Belt.
End User:
Procurement scale and technical specification authority separate contractor networks from material supplier intermediaries in channel economics.
- Contractors:Regional drywall installation firms consolidating procurement through direct manufacturer negotiations. Large Georgia and North Carolina operators leverage housing start concentration to extract volume commitments bypassing traditional dealer distribution.
- Drywall Installers:Specialized finishing crews whose apprenticeship pipeline output constrains installation quality consistency. Aging journeyman demographics in the Midwest and Northeast limit workforce expansion for traditional embedding techniques.
- Paint & Decorating Firms:Interior finish specialists requiring surface preparation systems compatible with premium coating applications. Level 5 finish specifications in commercial interiors drive alkali-resistant mesh specification through this channel.
- Construction Material Suppliers:Distributor intermediaries facing channel compression as consolidated contractor networks source direct. Building material dealers in the Sun Belt are losing tape category volume to manufacturer-direct arrangements.
Construction material suppliers hold legacy channel position. Contractors are climbing the fastest through procurement consolidation and direct supply negotiations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for glass fiber substrates shapes regional supply security, with net-exporting manufacturing corridors commanding procurement leverage over tape-producing economies. Trade flows concentrate raw material advantage in specific mineral wool production zones.
United States
Sun Belt housing velocity in Arizona, Texas, and Florida compresses drywall installation timelines toward self-adhesive mesh systems. EPA volatile organic compound regulations pressure adhesive reformulation for pressure-sensitive backings. Atlanta and Charlotte contractor networks negotiate direct manufacturer supply arrangements, bypassing traditional building material dealers.
China
Massive gypsum board installation volumes in residential and commercial construction sustain mesh tape demand at scale. GB standards for interior finishing materials govern tensile strength and adhesion performance requirements. Yangtze River Delta manufacturing clusters produce fiberglass substrates for both domestic tape production and regional export.
Germany
Commercial renovation activity across industrial zones maintains specification for traditional paper tape embedding techniques. REACH chemical regulations influence adhesive formulation choices for self-adhesive variants entering the market. North Rhine-Westphalia construction supply distributors serve as intermediaries for Central European tape procurement.
India
Rapid urban residential development in Maharashtra and Gujarat generates volume demand for cost-optimized finishing systems. BIS certification requirements for construction materials create compliance thresholds for imported tape products. Mumbai and Pune contractor markets exhibit technology transition toward mesh systems among emerging workforce entrants.
Brazil
Residential construction recovery in São Paulo and Rio de Janeiro metropolitan areas drives gypsum board finishing demand. ANVISA oversight of construction material safety influences product formulation standards for interior applications. Southeast Brazilian distributor networks consolidate procurement for regional drywall installation firms.
Drywall Joint Tape Market Competitive Landscape
Listed leaders compete with private specialists across substrate technology and distribution channel positioning. The vendor base clusters around three tiers: integrated mineral fiber producers controlling upstream glass fiber supply, specialized tape manufacturers focusing on application-specific formulations, and diversified construction material suppliers leveraging existing contractor relationships. Competitive moves concentrate on direct contractor supply arrangements and alkali-resistant coating technology licensing.
Among North American construction material conglomerates, CertainTeed Corporation and USG Corporation exemplify scale-driven positioning through dedicated contractor channels and upstream integration into gypsum and glass fiber substrates. Saint-Gobain anchors the integrated producer archetype with captive mineral wool capabilities feeding tape substrate production. Strait-Flex occupies a specialist position in composite corner bead and tape hybrid systems. These three company patterns represent the dominant competitive configurations: diversified construction material platforms, integrated mineral fiber producers, and application-specific technology specialists.
| Leading Market Players |
|---|
| CertainTeed Corporation |
| Strait-Flex |
| USG Corporation |
| Shurtape Technologies |
| Grip-Rite |
| Saint-Gobain |
| Sherwin-Williams Company |
| Scapa |
| 3M Company |
| Others |
Pricing and Supply Chain Analysis
ASTM C475 certification requirements gate both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb six-to-nine month testing timelines while contractors pay premiums for validated tensile performance. This regulatory threshold segments the market between certified premium substrates and uncertified commodity imports, concentrating margin capture among incumbents with in-house testing capabilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the drywall joint tape market. Price differentiation rests on alkali-resistant coating certification and self-adhesive backing chemistry, with Sun Belt contractors showing lowest sensitivity due to labor-cost savings from mesh systems. Cost compression in paper tape grades is intensifying because glass fiber supply bottlenecks push mid-tier buyers toward commodity cellulose alternatives. Residential renovation contractors in the Midwest exhibit highest price sensitivity, clinging to traditional embedding techniques despite longer installation cycles.
Supply Chain Analysis
Glass fiber substrate production clusters in the American Southeast, China's Yangtze River Delta, and Germany's North Rhine-Westphalia corridor create raw material chokepoints for tape manufacturers worldwide. Upstream supply draws from mineral wool processing, petroleum-based adhesive feedstocks, and specialty alkali-resistant coatings. Single-source vulnerability concentrates in glass fiber roving supply, where three integrated producers control majority substrate output. Distribution runs through direct manufacturer-contractor arrangements in high-velocity housing markets, bypassing traditional building material dealers in Georgia, North Carolina, and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-finished wall panel systems pose a material substitution threat that incumbent tape manufacturers must navigate through specification defense and prefabrication partnerships. Incumbents face pressure to demonstrate irreplaceable value in joint reinforcement as off-site construction factories capture share in Sun Belt states.
For Market Incumbents: Compound defensive positioning through ASTM C475 certification moats and captive glass fiber supply arrangements with Yangtze River Delta substrate producers. Secure specification lock-in with Texas and Florida prefabricated panel factories before composite reinforcement alternatives gain traction. Prioritize alkali-resistant coating R&D to defend premium tier against commodity mesh imports.
For New Entrants and Emerging Players: EPA VOC compliance fast-track opens procurement preference in federal government building contracts, creating a wedge for low-emission adhesive formulations. Target Georgia and North Carolina contractor networks with direct supply arrangements, bypassing dealer markups in markets where housing start concentration enables volume commitments. Lead with self-adhesive mesh systems that flatten the apprentice experience curve in labor-constrained Sun Belt regions.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across self-adhesive mesh manufacturing as water-based acrylic adhesive systems displace solvent-borne equipment requirements. Long-term viability favors specialists with backward integration into glass fiber substrates and direct contractor channel control. Watch for inflection when Level 5 finish mandates spread beyond current municipal adopters to statewide building codes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Fiber Substrates | Saint-Gobain's captive mineral wool supply insulates margin from raw material volatility. |
| Direct Contractor Supply Arrangements | Atlanta and Charlotte networks extract volume pricing bypassing traditional dealer distribution. |
| Alkali-Resistant Coating Certification | Florida EIFS specifications reward corrosion-stable formulations with premium positioning. |
| Low-VOC Adhesive Reformulation | EPA compliance qualifies manufacturers for federal procurement preference programs. |
| Prefabricated Panel Partnerships | Texas and Florida factories represent emerging demand for pre-applied joint reinforcement. |
Research Methodology
Desk research of customs trade databases, SEC construction material filings, and ASTM standards documentation preceded structured interviews with regional drywall contractors, building material procurement directors, adhesive formulation chemists, and prefabricated panel factory operations managers. Primary fieldwork validated secondary findings through bottom-up crew productivity assessments and top-down housing start correlation analysis across Sun Belt metropolitan statistical areas.
Variance-decomposition across the modeling period isolates demand drivers by substrate technology, application method, and regional construction velocity. Segmentation dimensions include product type, adhesive technology, end-use construction category, and contractor procurement scale. CAGRs derive from housing start projections, labor cost inflation assumptions, and regulatory adoption curves for Level 5 finish mandates. Industry-specific inputs incorporate gypsum board installation rates and glass fiber capacity utilization from Yangtze River Delta manufacturing clusters.
Decision-makers should treat outputs as directional under base assumptions of sustained Sun Belt housing velocity and stable EPA regulatory timelines; material deviation in mortgage rate environments or silica exposure rulemaking would warrant model refresh. Practitioners should keep alternative scenarios live as prefabricated construction adoption and alkali-resistant coating technology evolution reshape specification patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Qatar Facade Market
Building Materials
India Cement Market
Building Materials
Steel Sleepers Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
East Africa Cement Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
Europe Cement Market
Building Materials
Masonry Cement Market
Building Materials
Exterior Doors Market
Building Materials
Building and Construction Sheets Market
Building Materials
Mass Timber Construction Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
North America Cement Market