
 Concrete Blocks and Bricks Market | 2026-2036
Concrete Blocks and Bricks Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Blocks and Bricks Market Intelligence
India's BIS certification for fly ash utilization in concrete products is rebalancing raw material procurement across the sector. UltraTech Cement Ltd leverages its integrated clinker-to-block pipeline to control input costs across multiple states. CEMEX S.A.B. de C.V. anchors its position through R&D intensity in lightweight aggregate formulations. CRH competes by extending its distribution reach into secondary cities where contractor loyalty remains underdeveloped.
Concrete blocks and bricks comprise molded or pressed masonry units with compressive strengths ranging from 3.5 MPa to 50 MPa, serving as primary structural and envelope elements in buildings and civil works. Load-bearing blocks dominate volume in multi-story residential frames where structural efficiency governs specification, while insulating blocks capture expanding share in energy-code-compliant commercial envelopes where thermal performance commands premium positioning. Cement-based products retain scale leadership though fly ash blends gain ground as BIS norms tighten and power-plant waste streams stabilize.
India's BIS, the EPA under US federal standards, and the EU Green Deal's embodied-carbon benchmarks collectively reshape product compliance and market access thresholds. BIS mandates on fly ash minimums force reformulation of conventional cement mixes, while EPA criteria for coal combustion residuals govern US sourcing of supplementary cementitious materials. Stakeholders must monitor regulatory divergence between India's prescriptive material rules and Europe's performance-based carbon accounting to avoid stranded capacity in cross-border supply chains.
Market Dynamics
India's BIS fly ash mandates are forcing cement-to-block supply chains to reconfigure around power-plant waste streams, compressing traditional clinker economics and redistributing competitive advantage toward integrated producers with captive ash sourcing.
Growth Catalysts
- Load-bearing block specification:Multi-story residential frames in Maharashtra and Gujarat specify structural units rated 15-35 MPa, pulling volume from clay brick alternatives as urban floor-area ratios tighten.
- EU Green Deal embodied-carbon benchmarks:Commercial envelope projects across Germany and France now require Environmental Product Declarations, creating specification pull for low-carbon block formulations with calcined clay or geopolymers.
- State-level infrastructure programs:India's Pradhan Mantri Awas Yojana and allied state housing missions channel block procurement through standardized tenders, aggregating demand into predictable offtake pipelines.
Market Restraints
- Clinker price volatility:Energy-intensive cement kiln operations expose block margins to natural gas and petcoke cost swings, particularly acute for independent producers without captive limestone quarries.
- Fly ash supply concentration:Thermal power plant closures and grid decarbonization in Western Europe and parts of the US threaten supplementary cementitious material availability, forcing reformulation costs.
- Clay brick substitution persistence:Rural and semi-urban construction in India's northern states retains fired clay preference due to entrenched mason skill bases and lower upfront unit costs.
Strategic Opportunities
- Secondary city distribution gaps:India's tier-2 and tier-3 urban centers lack organized block supply, creating whitespace for producers with mobile batching and project-site casting capabilities.
- Insulating block thermal performance:Expanded polystyrene or aerated concrete cores meeting ECBC and comparable energy codes command 25-40% price premiums in commercial envelope specifications.
- Carbon capture integration:Pilot projects binding CO2 into curing processes are qualifying for EU Innovation Fund and US IRA 45Q credits, positioning early adopters for compliance-grade product differentiation.
Industry Challenges
- Geopolymer formulation expertise:Alkali-activated binder chemistry demands materials science talent scarce in traditional block manufacturing, slowing BIS-compliant low-carbon product rollout.
- Curing chamber capex:Steam-cured autoclaved aerated concrete lines require 8-12 million euro investments with 6-8 year payback horizons, constraining mid-cap expansion.
- Multi-jurisdiction certification lag:Producers targeting both Indian export markets and EU Green Deal compliance face overlapping BIS, CE marking, and EPD verification timelines that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Blocks and Bricks Market |
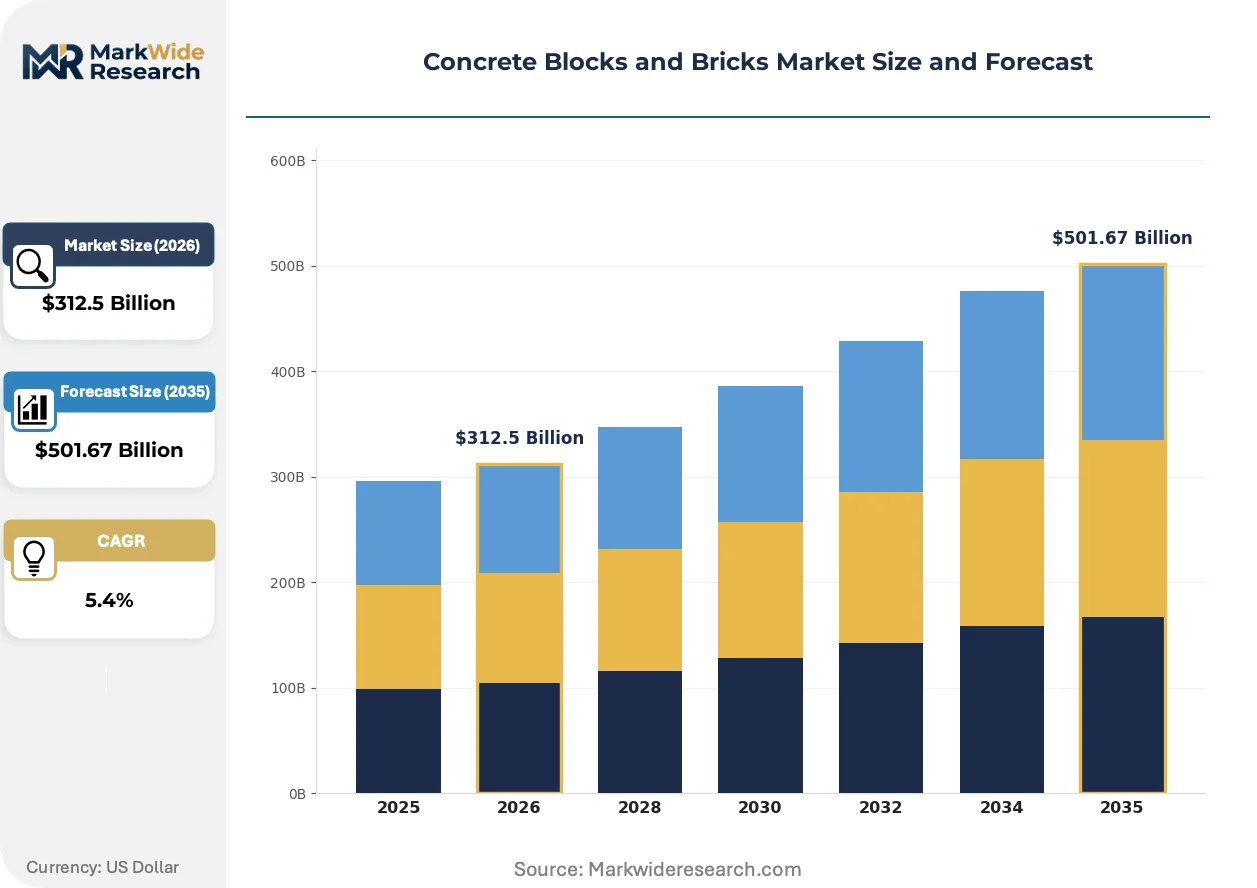
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $501.67 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Load-Bearing Blocks, Insulating Blocks, Solid Bricks, Hollow Bricks End Use: Residential Construction, Commercial Infrastructure, Industrial Applications, Landscaping Projects Material: Cement, Fly Ash, Aggregate, Recycled Materials Manufacturing Technique: Extrusion, Molding, Pressing, Handcrafted |
| Companies Covered | UltraTech Cement Ltd, CEMEX S.A.B. de C.V., CRH, General Shale, Inc., Acme Brick Company, Wienerberger AG, Xella Group, Midwest Block & Brick, Boral, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Blocks and Bricks Market Strategic Shifts & Innovations
Material science advances and regulatory carbon accounting are compressing the viable formulation window for conventional Portland cement blocks, while digital fabrication and logistics platforms reshape how masonry units reach job sites.
Geopolymer and alkali-activated binders are overtaking conventional fly ash-Portland blends in precast commercial envelope specifications. German and Dutch facade contractors now source these for projects requiring sub-400 kg CO2 per cubic meter embodied carbon. The shift is compressing lime and clinker demand curves in North European supply chains.
REACH restrictions on crystalline silica exposure limits are forcing block cutting and finishing operations toward wet-process dust suppression or automated enclosed saws. Italian and Spanish masonry subcontractors report 15-20% equipment retrofit costs, with compliance timelines tightest for small-batch custom producers serving heritage restoration.
Project developers in India's affordable housing segment now specify ready-to-install precast wall panels over site-laid blocks, collapsing traditional masonry labor schedules. Maharashtra's PMAY-urban contractors report 30% faster enclosure completion, though the shift fragments procurement across panel fabricators and erection crews rather than consolidating with block merchants.
Concrete Blocks and Bricks Market Segmentation
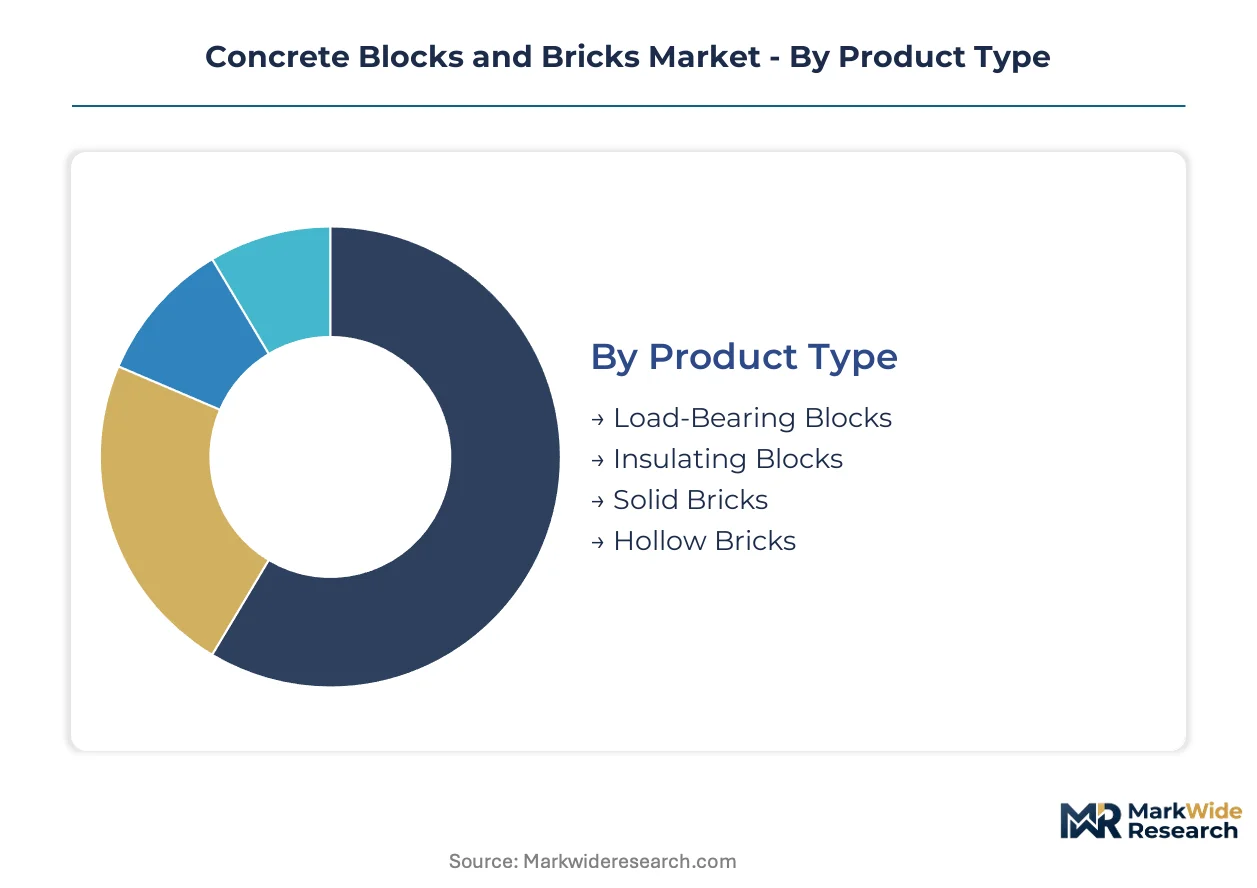
Concrete blocks and bricks segment across structural performance, thermal properties, and manufacturing economics. Specification choices cascade through material sourcing, curing investments, and distribution logistics.
Product Type:
Structural performance ratings differentiate product portfolios and dictate manufacturing capex requirements.
- Load-Bearing Blocks:Compressive strengths from 15 MPa to 35 MPa support multi-story residential frames in Maharashtra and Gujarat. Urban floor-area ratio tightening pulls volume from clay brick alternatives as developers maximize vertical density.
- Insulating Blocks:Expanded polystyrene or aerated concrete cores deliver thermal resistance values meeting ECBC and comparable energy codes. Commercial envelope specifications in Germany and France command substantial price premiums for sub-400 kg CO2 per cubic meter embodied carbon performance.
- Solid Bricks:Dense cementitious units serve foundation courses and damp-proofing applications where moisture resistance governs selection.
- Hollow Bricks:Voided cores reduce material intensity and dead load in non-structural infill applications across India's affordable housing segment.
Mature deployment sits with load-bearing blocks. Newer deployment is concentrated in insulating blocks.
End Use:
Application contexts reshape procurement scale, certification requirements, and contractor relationships.
- Residential Construction:India's Pradhan Mantri Awas Yojana channels block procurement through standardized tenders, aggregating demand into predictable offtake pipelines across Maharashtra and Gujarat state housing missions.
- Commercial Infrastructure:Environmental Product Declaration requirements under EU Green Deal benchmarks govern specification for German and French facade projects, filtering supplier qualification.
- Industrial Applications:Heavy-duty flooring and retaining wall specifications demand 50 MPa compressive ratings with sulfate-resistant cement formulations.
- Landscaping Projects:Aesthetic surface finishes and custom dimensions serve municipal hardscaping and private estate development with smaller batch sizes.
Volume concentrates in residential construction. Margin expansion is steepest in commercial infrastructure.
Material:
Input composition determines regulatory compliance positioning and exposure to supply chain volatility.
- Cement:Portland clinker base retains manufacturing familiarity but faces margin compression from energy-intensive kiln economics and natural gas price swings.
- Fly Ash:BIS mandates minimum utilization rates in Indian concrete products, forcing reformulation and redistributing advantage toward producers with captive power-plant sourcing agreements.
- Aggregate:Crushed limestone and granite fillers govern weight, strength, and regional sourcing radius based on quarry proximity.
- Recycled Materials:Construction and demolition waste streams qualify for EU Green Deal circular economy credits and US IRA sustainable materials incentives.
Regulatory pressure is reshaping cement. Fly ash blends are gaining specification share fastest.
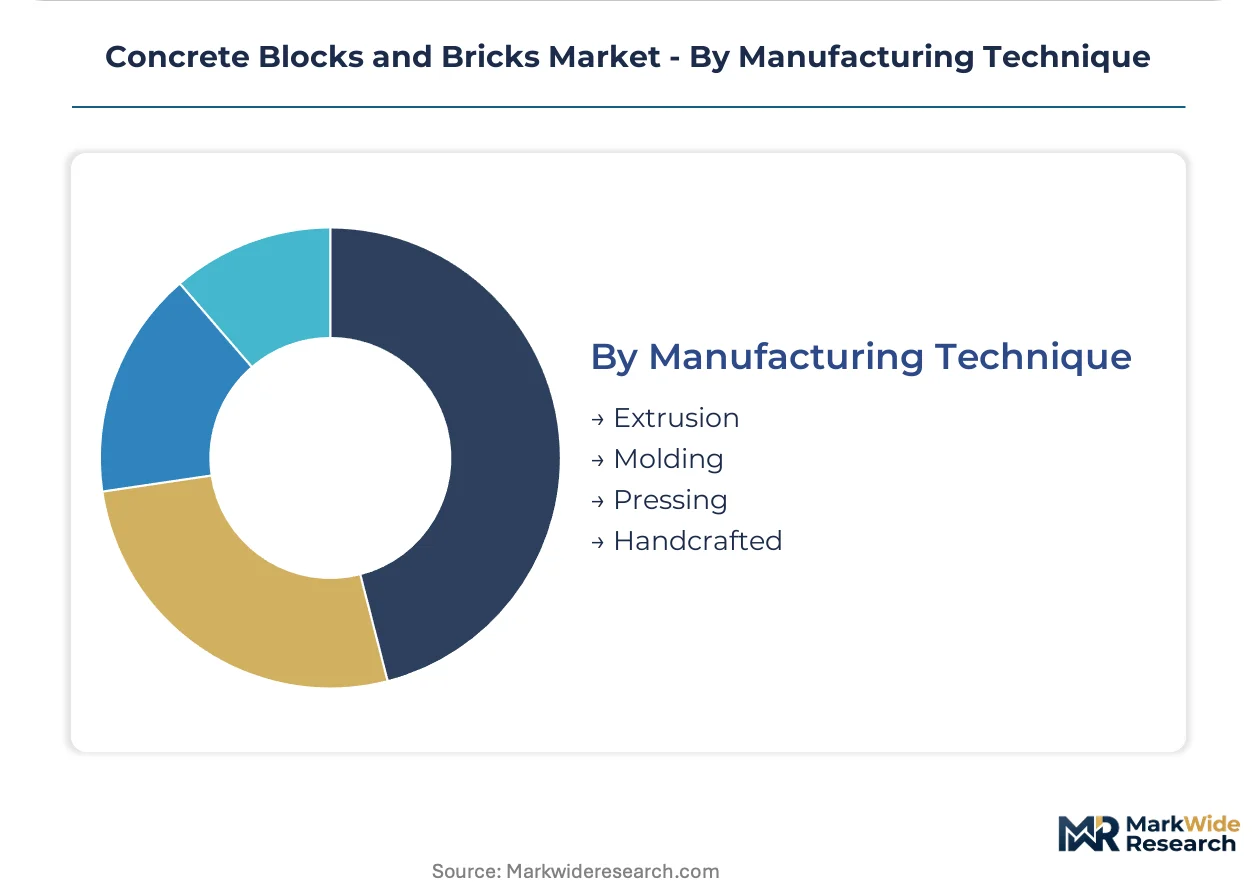
Manufacturing Technique:
Process selection locks in capital intensity, product consistency, and scale economies.
- Extrusion:Continuous forming suits high-volume hollow block production with dimensional precision for automated masonry systems.
- Molding:Vibration-compacted wet cast delivers surface finish quality for architectural exposed block applications.
- Pressing:Dry compaction enables rapid cycle times and lower curing energy for standard structural units.
- Handcrafted:Labor-intensive forming persists in heritage restoration and specialty textured finishes where batch sizes resist mechanization.
Scale economics favor extrusion and pressing. Handcrafted output commands niche premiums in restoration markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai-Pune corridor anchors the densest block consumption cluster worldwide. Maharashtra's state housing missions channel standardized procurement through this corridor. Gujarat's industrial townships radiate demand from Ahmedabad-Surat belt.
United States
Texas and Florida metro construction drives structural block specification. EPA coal combustion residual criteria govern supplementary cementitious material sourcing. Houston-Gulf Coast petrochemical corridor hosts integrated producers with captive fly ash agreements.
Germany
Commercial envelope retrofits and new-build facades demand low-carbon block formulations. EU Green Deal embodied-carbon benchmarks and EPD requirements filter supplier qualification. Rhine-Ruhr industrial belt concentrates autoclaved aerated concrete manufacturing.
India
Affordable housing stock expansion across Maharashtra and Gujarat pulls volume from clay brick alternatives. BIS fly ash utilization mandates reshape cement-to-block supply chains. Ahmedabad-Surat industrial corridor redistributes competitive advantage toward integrated producers.
China
Urban renewal and infrastructure replacement sustain block demand in Yangtze and Pearl River deltas. GB standards and dual carbon goals tighten embodied-carbon thresholds. Shenzhen-Dongguan manufacturing zone pilots geopolymer binder formulations for commercial projects.
United Arab Emirates
Mega-project construction and district cooling integration specifications drive insulating block adoption. Dubai Municipality green building regulations mandate thermal performance ratings. Jebel Ali industrial zone concentrates precast and masonry manufacturing for Gulf export markets.
Concrete Blocks and Bricks Market Key Industry Players
The competitive structure tilts toward integrated cement-to-block conglomerates with captive raw material sourcing. Mid-cap regional specialists occupy secondary city distribution gaps where contractor loyalty remains underdeveloped. Three archetypes dominate: multinational building materials conglomerates, national cement-backed block producers, and regional masonry specialists. Capacity expansion and portfolio diversification toward insulating and low-carbon formulations constitute the primary competitive vectors.
Among India-based cement conglomerates, UltraTech Cement Ltd exemplifies vertical integration from clinker to finished block. Mexican multinational CEMEX S.A.B. de C.V. occupies a position within the R&D-intensive lightweight materials tier. Irish-American building materials group CRH sits within the geographic expansion archetype, extending distribution reach into underserved secondary markets. These three anchors represent distinct strategic postures: captive supply control, formulation innovation, and distribution density.
| Leading Market Players |
|---|
| UltraTech Cement Ltd |
| CEMEX S.A.B. de C.V. |
| CRH |
| General Shale, Inc. |
| Acme Brick Company |
| Wienerberger AG |
| Xella Group |
| Midwest Block & Brick |
| Boral |
| Others |
Cost & Logistics Intelligence
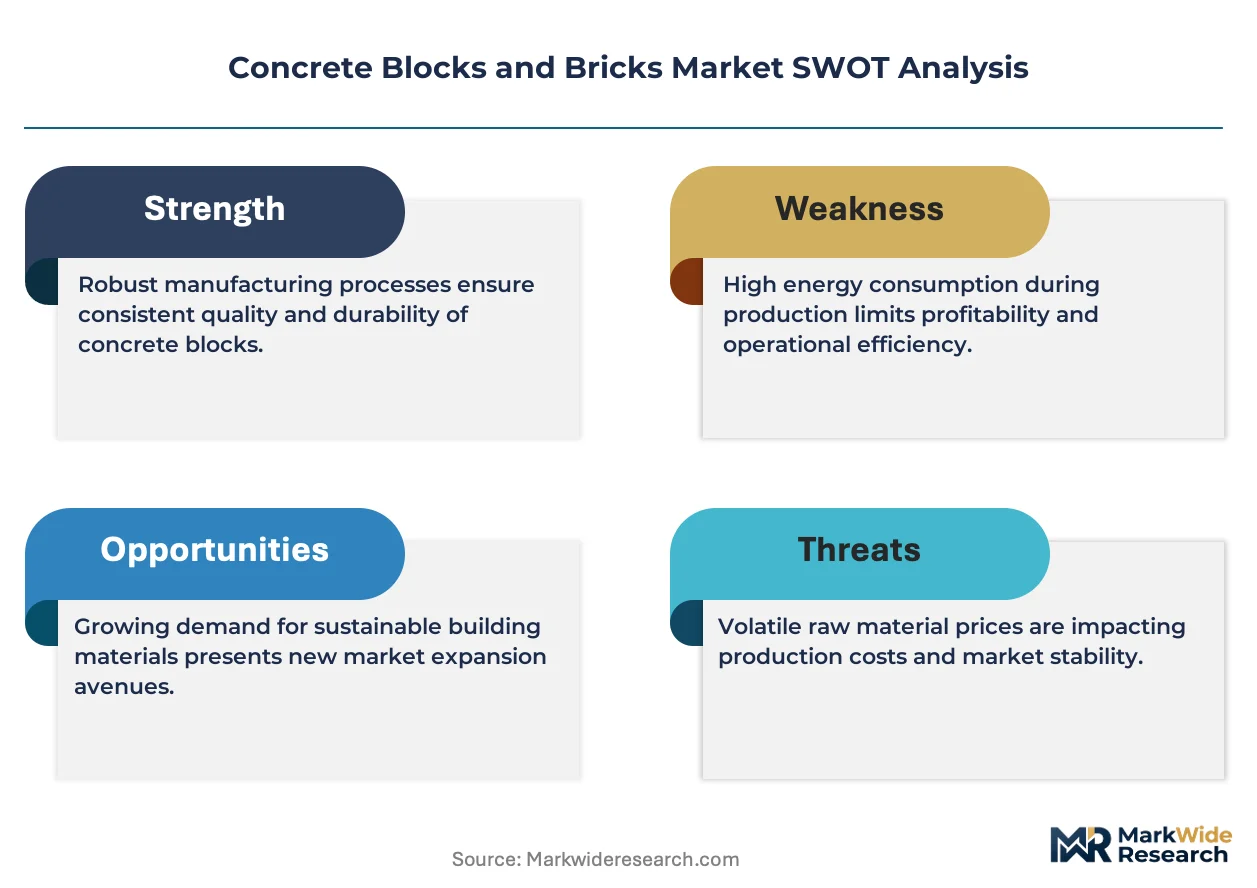
Maharashtra's PMAY-urban contractors specifying 15-35 MPa load-bearing blocks for multi-story frames are compressing margins for independent producers lacking captive fly ash sourcing, forcing supply chains to consolidate around integrated cement-to-block pipelines or absorb reformulation costs.
Pricing Analysis
Performance-based pricing anchors on compressive strength ratings and thermal resistance values meeting ECBC or comparable energy codes. Three-tier pricing structure across premium insulating blocks, standard load-bearing units, and economy hollow bricks reflects certification grade and volume scale differentiation. Cost compression in the economy tier is intensifying because clay brick substitution persists in rural northern India. State housing missions aggregating standardized tender volumes prove least price-sensitive, while fragmented tier-2 and tier-3 contractor bases drive aggressive unit economics.
Supply Chain Analysis
Regional distribution centers in the Mumbai-Pune and Ahmedabad-Surat corridors feed hub-and-spoke patterns radiating into secondary cities. Manufacturing concentrates in India, China, and Germany, with each market drawing from distinct raw material bases. Clinker, fly ash, and crushed limestone dependencies create exposure to thermal power plant closures and grid decarbonization trends. Single-source vulnerability runs through concentrated fly ash supply from legacy coal plants. Distribution runs through project-site direct delivery for large infrastructure contracts and merchant stockists serving fragmented residential builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS fly ash utilization mandates erect a cost-of-compliance barrier that moats integrated producers while stranding independent block manufacturers unable to secure captive power-plant waste stream agreements.
For Market Incumbents: Lock in fly ash supply agreements with thermal power operators before grid decarbonization accelerates, and expand autoclaved aerated concrete capacity in the Ahmedabad-Surat belt to capture insulating block premiums. Geopolymer formulation expertise scarcity threatens mid-cap expansion timelines, making R&D talent acquisition the priority lever against low-carbon product rollout delays. For New Entrants and Emerging Players: Tier-2 and tier-3 city contractors lacking organized block supply present whitespace for mobile batching and project-site casting capabilities. Mobile production units serving Maharashtra's secondary urban centers offer the most penetrable entry point. Anchor go-to-market around speed-to-site and customized dimensional specifications rather than competing on unit price against established merchant stockists. For Investors and Strategic Acquirers: Re-rating potential sits with regional masonry specialists possessing distribution density in underserved secondary markets given accelerating PMAY-urban procurement aggregation. Long-term viability favors producers with backward integration into clinker and captive fly ash sourcing. Watch for BIS tightening minimum fly ash utilization rates as the inflection signal for stranded capacity risk among independent producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fly Ash Sourcing | Captive supply agreements with NTPC and state power utilities secure BIS-compliant input volumes. |
| Autoclaved Aerated Concrete Capacity Expansion | Steam-cured lines meeting ECBC thermal codes capture 25-40% price premiums in commercial envelopes. |
| Geopolymer Formulation R&D Investment | Alkali-activated binders sub-400 kg CO2 per cubic meter qualify for EU Green Deal specification pull. |
| Mobile Batching Deployment in Tier-2 Cities | Project-site casting capabilities address distribution gaps where contractor loyalty remains underdeveloped. |
| Carbon Capture Curing Process Pilot | CO2-binding qualification for EU Innovation Fund credits positions compliance-grade product differentiation. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cement plant managers, PMAY-urban procurement officers, masonry subcontractor crews, and distribution channel partners. BIS notifications, EPA coal combustion residual criteria, EU Green Deal embodied-carbon benchmarks, and state housing mission tender documents provided compliance and demand-side validation. Bottom-up block production estimates triangulated against top-down construction activity indices across the analysis window.
Data-stream reconciliation connected plant-level capacity utilization with state-level infrastructure program disbursement timelines. Segmentation modeling spanned product type, end-use application, material composition, and manufacturing technique dimensions. CAGRs derived from elasticity-adjusted construction output projections and substitution rate assumptions for clay brick displacement. Fly ash supply concentration curves and clinker price volatility bands served as industry-specific forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to thermal power plant retirement schedules, BIS mandate tightening, and EU carbon border adjustment implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Europe Building and Construction Sheets Market
Building Materials
Pozzolana Cement Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
Spain Architectural Coatings Market
Building Materials
US Facade Market
Building Materials
Natural Stone Slab Market
Building Materials
Indonesia Architectural Coatings Market
Building Materials
Global Facade Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Low-E Construction Glass Market
Building Materials
Global White Cement Market
Building Materials
Exterior Doors Market
Building Materials
Earthen Plasters Market
Building Materials
Global Metal Cladding Market
Building Materials
West Africa Cement Market