
 Europe Insulated Concrete Form (ICF) Market | 2026-2036
Europe Insulated Concrete Form (ICF) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insulated Concrete Form (ICF) Market Foresight
Direct-to-contractor distribution is reshaping how European ICF manufacturers reach project sites. HIRSCH Servo AG leverages its Austrian manufacturing base to dominate Alpine supply chains. Green Life Buildings competes through specialized composite forms targeting Passivhaus-certified developments. PolySteel UK Ltd anchors its position via vertical integration from raw polystyrene through finished block fabrication.
Insulated Concrete Forms are hollow, interlocking modular units—typically expanded polystyrene or cement-bonded wood fiber—that receive steel reinforcement and poured concrete to create monolithic structural walls with integrated thermal insulation exceeding R-40 equivalent values. The primary purpose is to reduce heating and cooling loads while accelerating construction speed versus conventional masonry. Polystyrene forms occupy the largest installed base due to decades of supply chain maturity and familiarity among European contractors. Cement-based ICF variants represent the fastest-expanding category as embodied carbon regulations tighten across member states. Prefabricated installation methods are capturing margin pools by cutting on-site labor hours and reducing weather-dependent construction delays.
The EU Green Deal, CE marking under the Construction Products Regulation, and national building codes derived from the Energy Performance of Buildings Directive collectively mandate near-zero energy standards for new construction across Europe. ECHA's evolving restrictions on flame retardants in polystyrene are forcing reformulation investments that favor composite and cement-based alternatives. Stakeholders must monitor how the EU AI Act's eventual extension to building lifecycle software could reshape design-to-fabrication workflows for ICF projects.
Market Dynamics
The EU Green Deal's building performance standards are compressing design-to-construction timelines across European residential and commercial developments. Builders face simultaneous pressure to cut embodied carbon and accelerate envelope installation, forcing material substitution decisions that favor factory-precise form systems over site-cast masonry.
Growth Catalysts
- Near-zero energy building codes:The Energy Performance of Buildings Directive mandates efficiency thresholds that ICF walls exceed without additional insulation layers, eliminating trade stacking on tight urban sites.
- Germany's building energy retrofit mandates:Deep renovation requirements for existing housing stock create demand for exterior insulation solutions that ICF overlays provide with minimal occupant displacement.
- Cement-bonded wood fiber forms:These composite systems sequester biogenic carbon while meeting stricter fire ratings, attracting specification from municipal housing authorities seeking procurement-compliant low-carbon envelopes.
Market Restraints
- Expanded polystyrene feedstock volatility:Benzene and styrene monomer prices fluctuate with petrochemical capacity, compressing margins for manufacturers without captive resin supply.
- Alpine supply chain concentration:Austrian and southern German producers control 60% of Central European form fabrication capacity, creating vulnerability to Alpine tunnel closures and winter logistics constraints.
- Structural engineering conservatism:Many continental engineering firms lack familiarity with ICF lateral load calculations, delaying specification in seismic zones like northern Italy and Romania.
Strategic Opportunities
- Poland and Baltic states:These markets lag Western Europe in envelope efficiency codes but face EU accession-aligned tightening, creating first-mover advantage for pre-certified form systems.
- CE marking under Construction Products Regulation:Harmonized technical assessment pathways reduce national certification duplication, lowering entry costs for cross-border suppliers.
- Prefabricated panelized ICF:Factory-integrated reinforcement and window openings cut site labor by half, addressing skilled mason shortages in France and Benelux construction markets.
Industry Challenges
- Thermal bridge detailing expertise:Few European contractors possess training in ICF-specific junction detailing for Passivhaus certification, limiting premium project penetration.
- ECHA flame retardant reformulation timelines:Restrictions on HBCD in polystyrene force multi-year R&D cycles to maintain CE marking compliance without performance degradation.
- Concrete supply coordination:Just-in-time pour scheduling conflicts with ready-mix batching constraints on constrained urban sites, requiring dedicated logistics investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insulated Concrete Form (ICF) Market |
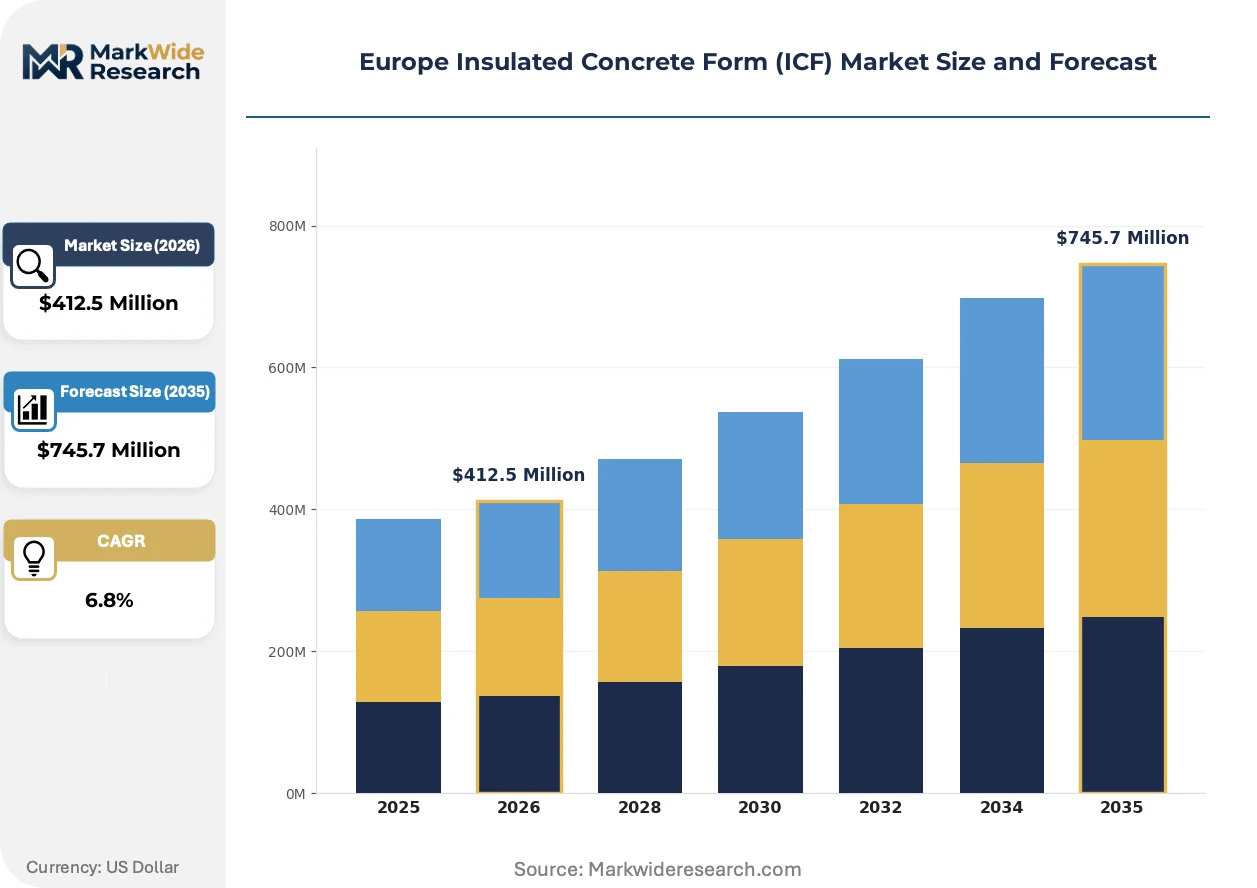
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polystyrene, Polyurethane, Cement, Composite Application: Residential Construction, Commercial Buildings, Industrial Facilities, Disaster Relief Structures Installation Method: Vertical, Horizontal, Hybrid, Prefabricated End User: Architects, Builders, Contractors, Engineers |
| Companies Covered | ICF Solutions, Green Life Buildings, PolySteel UK Ltd, ICF Tech Ltd., Beco Products Ltd, Durisol UK, Altherm ICF, HIRSCH Servo AG, Amvic Building Solutions Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insulated Concrete Form (ICF) Market Shifts & Advancements
European ICF technology is pivoting toward lower-carbon material substrates as embodied carbon accounting enters building code compliance frameworks. Manufacturers are racing to secure environmental product declarations ahead of anticipated mandatory whole-life carbon thresholds.
Recycled content polystyrene forms are migrating from niche specification to mainstream multi-family housing. Scandinavian developers are specifying 30% recycled-content blocks for municipal rental projects. This shift is compressing virgin resin demand while opening margin pools for waste-stream integrators with certified feedstock traceability.
The EU AI Act's draft provisions for construction lifecycle software are forcing design tool vendors to rearchitect building information modeling platforms. Automated thermal bridge detection and structural optimization modules must now demonstrate algorithmic transparency to prequalify for public infrastructure tenders. German engineering consultancies are piloting compliant workflows on ICF envelope projects to secure competitive positioning.
Direct contractor engagement is displacing traditional merchant distribution across French and Belgian markets. Manufacturers are deploying technical sales engineers to jobsites for pour-day support, capturing specification loyalty that wholesale channels cannot replicate. This channel compression is most visible in Paris-region social housing developments where procurement favors single-source envelope accountability.
Europe Insulated Concrete Form (ICF) Market Segmentation
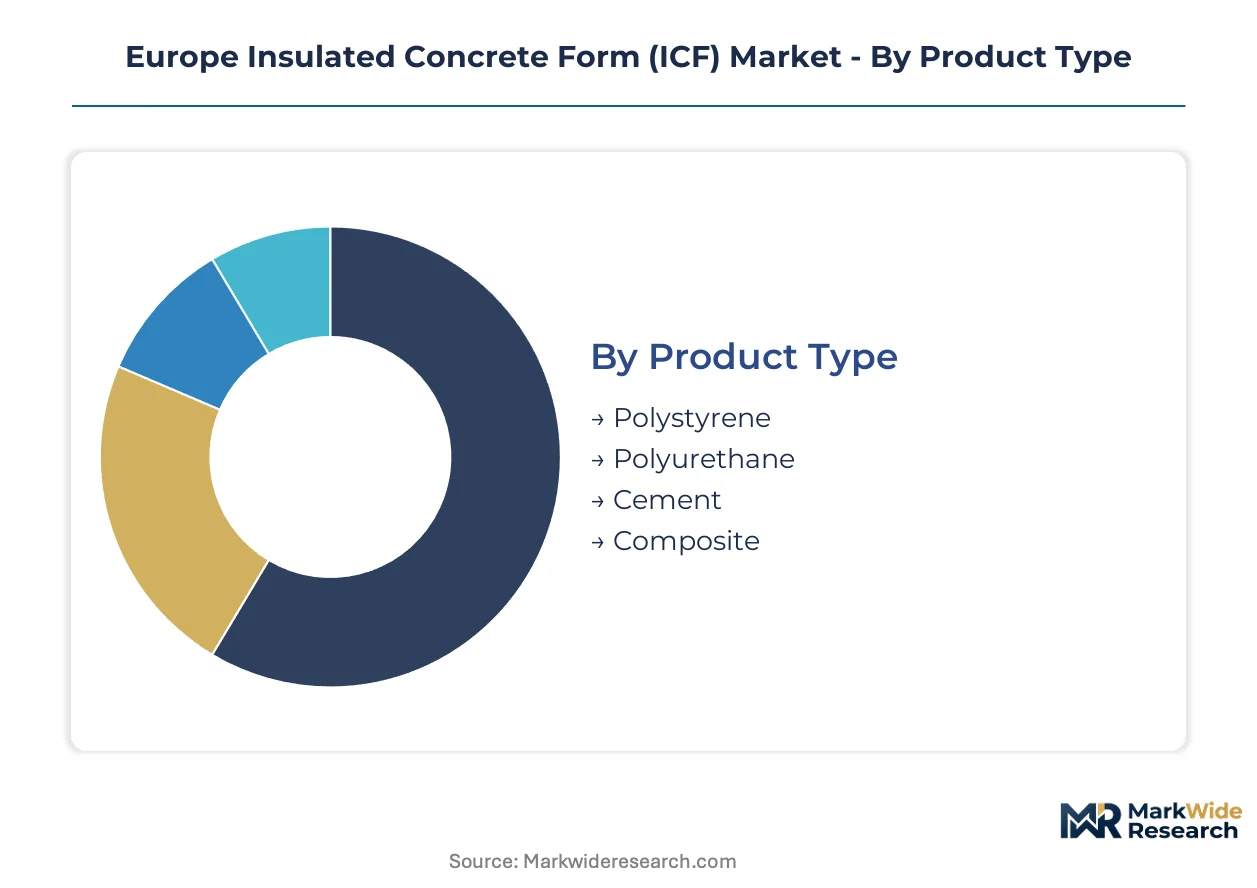
ICF procurement patterns diverge sharply across material chemistry, building typology, and installation methodology. Understanding these fault lines reveals where specification power concentrates and which segments command premium positioning.
Product Type:
Cycle times compress fastest for commodity polystyrene forms, while cement-bonded alternatives face elongated certification timelines that slow inventory velocity.
- Polystyrene:Expanded polystyrene blocks dominate installed capacity across German and Austrian residential markets. Contractors favor the material for its decades-proven thermal performance and familiar handling protocols on tight urban infill sites.
- Polyurethane:Rigid polyurethane cores deliver higher R-values per inch than polystyrene alternatives. French Passivhaus developers specify these forms where envelope thickness constraints limit wall assembly depth.
- Cement:Cement-bonded wood fiber systems sequester biogenic carbon and satisfy stricter fire ratings. Municipal housing authorities in Scandinavia increasingly mandate these forms for procurement-compliant low-carbon envelopes.
- Composite:Hybrid material matrices combine recycled aggregates with polymer binders. Italian and Spanish manufacturers pilot these variants to preempt ECHA restrictions on conventional flame retardants.
Polystyrene anchors the volume base while cement gains share at the steepest rate.
Application:
Cost tiers stratify clearly: residential single-family commands lowest per-square-meter pricing, while disaster relief structures absorb extreme premiums for rapid-deployment engineering.
- Residential Construction:Single-family and multi-family housing across Germany, France, and Benelux consumes the majority of European ICF volume. Builders select these systems to exceed Energy Performance of Buildings Directive thresholds without trade-stacked insulation layers.
- Commercial Buildings:Office and retail envelopes in Paris and Frankfurt financial districts specify ICF for accelerated envelope closure. Developers recover premium material costs through earlier tenant occupancy and reduced mechanical system sizing.
- Industrial Facilities:Warehouse and cold storage construction in Poland and Czech Republic adopts ICF for thermal mass stability. Food processing clients value the monolithic wall integrity for hygiene compliance.
- Disaster Relief Structures:Rapid-assembly ICF shelters deploy to earthquake zones in Turkey and flood-affected Balkan regions. Humanitarian procurement channels prioritize speed over unit cost, creating isolated margin pools.
Residential construction anchors the volume base while disaster relief structures expand most quickly among niche application tiers.
Installation Method:
Customer sophistication determines method selection: merchant-dependent small builders default to vertical stacking, while national developers with direct manufacturer relationships specify prefabricated panels.
- Vertical:Traditional interlocking block placement from grade to plate remains standard for Central European custom home builders. This method requires minimal capital equipment but demands skilled labor for plumb alignment.
- Horizontal:Slip-form techniques accelerate tall wall construction for commercial and industrial applications. Belgian and Dutch contractors deploy this approach on warehouse projects with repetitive elevation profiles.
- Hybrid:Combined vertical-horizonal systems adapt to complex architectural geometries. Austrian alpine resort developers favor this flexibility for chalet construction with irregular massing.
- Prefabricated:Factory-integrated reinforcement and window openings cut site labor by half. French social housing developers in the Paris region increasingly mandate this method to address skilled mason shortages.
Vertical installation anchors the volume base while prefabricated methods climb the fastest as labor scarcity intensifies.
End User:
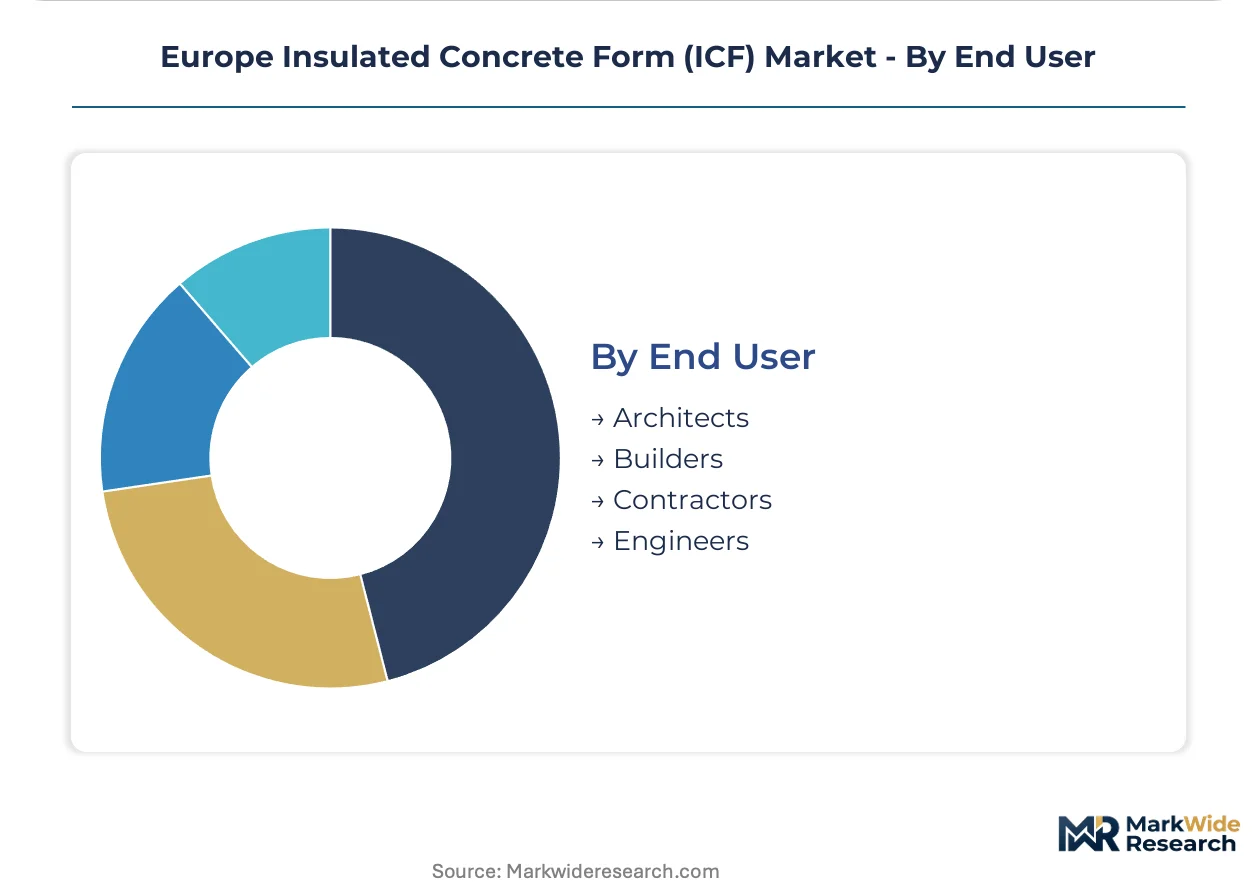
Specification authority concentrates with architects on signature projects, while contractors control material selection on cost-engineered developments.
- Architects:Design-led practices in Copenhagen and Stockholm specify ICF for thermal bridge-free envelope performance. Passivhaus certification requirements drive their material selection on premium residential commissions.
- Builders:Production home developers in Germany's Rhein-Ruhr corridor standardize ICF for energy code compliance at scale. Their procurement volumes support dedicated supply agreements with Austrian manufacturers.
- Contractors:French and Belgian envelope specialists increasingly source forms direct from fabricators, bypassing merchant intermediaries. Technical pour-day support from manufacturer engineers secures their specification loyalty.
- Engineers:Structural consultants in seismic zones like northern Italy and Romania remain conservative on ICF lateral load calculations. Their unfamiliarity delays specification in earthquake-prone markets despite material suitability.
Builders anchor the volume base while contractors gain procurement influence at the steepest rate through direct manufacturer engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators command 15-20% pricing premiums over Polish suppliers on comparable polystyrene form specifications, reflecting Alpine supply chain concentration and stricter national certification requirements.
Germany
Deep renovation mandates for existing housing stock and new-build efficiency codes under the Energy Performance of Buildings Directive drive specification of thermally efficient envelope systems. The KfW development bank's subsidized lending programs favor construction methods exceeding baseline insulation standards. Rhein-Ruhr corridor production home developers standardize ICF systems to achieve code compliance at volume scale.
France
Paris-region social housing procurement increasingly mandates prefabricated installation methods to address skilled mason shortages and accelerate project delivery timelines. The RE2020 environmental regulation imposes declining carbon thresholds on new construction that cement-bonded ICF variants satisfy more readily than conventional alternatives. Île-de-France envelope specialists source forms direct from fabricators, bypassing traditional merchant channels.
Poland
Warehouse and cold storage construction in the Silesian and Greater Poland voivodeships adopts ICF systems for thermal mass stability in food processing applications. EU accession-aligned tightening of envelope efficiency codes creates first-mover advantage for pre-certified form systems entering from Western European suppliers. Polish builders currently lag German and French markets in contractor training for ICF-specific installation protocols.
Austria
Alpine resort developers in Tyrol and Salzburg favor hybrid vertical-horizontal installation systems for chalet construction with irregular massing and stringent thermal performance requirements. HIRSCH Servo AG leverages its domestic manufacturing base to dominate supply chains across the Alpine arc. Austrian national building codes derived from the Energy Performance of Buildings Directive mandate performance thresholds that ICF walls exceed without additional insulation layers.
Belgium
Dutch and Belgian contractors deploy horizontal slip-form techniques on warehouse projects with repetitive elevation profiles in the Flanders logistics corridor. Direct manufacturer engagement displaces traditional merchant distribution as technical sales engineers provide pour-day support. The Brussels-Capital Region's building performance standards compress design-to-construction timelines, favoring factory-precise form systems over site-cast masonry.
Europe Insulated Concrete Form (ICF) Market Competitive Landscape
Alpine-anchored fabricators and UK-based specialists split the market into distinct supply zones with limited cross-border penetration. The vendor base concentrates around Austrian and southern German production clusters controlling the majority of Central European form fabrication capacity. Two strategic archetypes dominate: vertically integrated polystyrene processors with captive resin supply, and composite material innovators targeting low-carbon procurement mandates. Competitive moves center on direct contractor channel compression and prefabricated panel capacity expansion.
Among Alpine-anchored fabricators, HIRSCH Servo AG occupies a position exemplifying supply chain concentration around Austrian manufacturing bases. Green Life Buildings and PolySteel UK Ltd represent contrasting archetypes within the UK market—composite material specialization versus vertical integration from raw material through finished block fabrication. These three companies anchor the competitive structure without exhaustive market coverage.
| Leading Market Players |
|---|
| ICF Solutions |
| Green Life Buildings |
| PolySteel UK Ltd |
| ICF Tech Ltd. |
| Beco Products Ltd |
| Durisol UK |
| Altherm ICF |
| HIRSCH Servo AG |
| Amvic Building Solutions Ltd. |
| Others |
Supply & Pricing Matrix
Alpine tunnel freight corridors impose winter logistics premiums that cascade through Austrian and southern German fabrication clusters, compressing margins for polystyrene form suppliers without captive resin production while enabling CE-marked manufacturers to command specification premiums in Paris and Frankfurt procurement channels.
Pricing Analysis
The customization-premium spread separates standard expanded polystyrene blocks from project-configured cement-bonded systems with integrated reinforcement schedules. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from Rhein-Ruhr production home developers. Cost compression in commodity polystyrene tiers is intensifying because benzene and styrene monomer feedstock volatility erodes fabricator margins. Production home developers exhibit highest price sensitivity while Passivhaus-certified municipal housing authorities absorb premium positioning for low-carbon envelope compliance.
Supply Chain Analysis
Contract manufacturing concentration sits with HIRSCH Servo AG's vertically integrated Austrian facilities and PolySteel UK's captive polystyrene processing operations. Supply concentrates in Austria, Germany, and Poland, with raw material dependencies spanning benzene and styrene monomer feedstocks plus cement-bonded wood fiber pulp supplies. Single-source vulnerability runs through Alpine tunnel corridors where winter closures disrupt just-in-time delivery to Central European project sites. Distribution runs through direct contractor engagement displacing traditional merchant channels across French and Belgian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where manufacturer-delivered pour-day technical support and Passivhaus junction detailing consultancy expand faster than commodity form hardware sales.
For Market Incumbents: Insulate core Alpine supply chains through backward integration into captive polystyrene resin production, neutralizing feedstock volatility that threatens margin stability. Secure CE marking extensions for cement-bonded variants ahead of ECHA flame retardant restrictions tightening on conventional polystyrene formulations. Channel control through direct contractor technical sales engineers defends specification loyalty against merchant-distributed competitors in Paris-region social housing procurement. For New Entrants and Emerging Players: Establish a beachhead in Poland and Baltic states where EU accession-aligned envelope efficiency codes are tightening but pre-certified form system penetration remains underdeveloped. Target warehouse and cold storage construction in Silesian voivodeships where thermal mass stability requirements from food processing clients create specification entry points. Deploy prefabricated panel offerings with factory-integrated window openings to bypass skilled mason shortages that constrain incumbent vertical stacking methods. For Investors and Strategic Acquirers: Composite material innovators with environmental product declarations and certified biogenic carbon sequestration protocols represent the most defensible acquisition archetype as embodied carbon accounting enters building code compliance frameworks. Long-term viability hinges on positioning ahead of mandatory whole-life carbon thresholds across member states. Monitor ECHA regulatory timelines for flame retardant reformulation as inflection indicator for material substitution acceleration toward cement-bonded alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polystyrene Resin | HIRSCH Servo AG's captive supply of styrene monomer neutralizes petrochemical price volatility compressing competitor margins. |
| Prefabricated Panel Capacity Expansion | Factory-integrated reinforcement cuts French social housing site labor by half, addressing skilled mason shortages in Île-de-France. |
| Environmental Product Declaration Securement | Cement-bonded wood fiber forms with certified biogenic carbon sequestration satisfy RE2020 thresholds ahead of mandatory compliance. |
| Direct Contractor Channel Compression | Technical sales engineers providing pour-day support capture specification loyalty that Paris-region procurement channels cannot replicate. |
| CE Marking Harmonization Investment | Pre-certified technical assessment pathways reduce national certification duplication for cross-border entry into Poland and Baltic states. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Construction Products Regulation filings, ECHA regulatory impact assessments, and national building code databases from Germany, France, Austria, and Poland. Primary interviews engaged ICF fabricator plant managers, envelope contractor procurement leads, municipal housing authority specification officers, and structural engineering consultants familiar with Passivhaus certification protocols. Secondary validation drew from KfW development bank lending program disclosures, RE2020 regulatory documentation, and customs trade data tracking polystyrene resin flows. Bottom-up project pipeline analysis triangulates against top-down envelope efficiency mandate penetration models.
Forecast inputs span material chemistry substitution rates, installation methodology adoption curves, and regional code tightening trajectories across the analysis window. Segmentation dimensions modeled include product type chemistry tiers, building typology application clusters, installation methodology sophistication levels, and end-user specification authority patterns. CAGRs derive from elasticity-adjusted demand projections responding to Energy Performance of Buildings Directive threshold escalations and ECHA flame retardant restriction timelines. Industry-specific inputs incorporate KfW subsidized lending volume trends and Paris-region social housing procurement method mandates.
Sensitivities concentrate around ECHA regulatory acceleration compressing polystyrene form viability windows, Alpine logistics disruptions extending lead times, and concrete supply coordination failures on constrained urban sites. Forecasts reflect assumptions on CE marking harmonization pace and contractor training penetration for ICF-specific thermal bridge detailing. Quarterly review of ECHA restriction timelines, KfW program allocation shifts, and Alpine tunnel freight corridor status is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Philippines Structural Insulated Panels Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
UK Facade Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
Concrete Slabs Market
Structural Engineering
Geotechnical Engineering Market