
 Refractory Cement Market | 2026-2036
Refractory Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Refractory Cement Market Analytics
India's refractory manufacturing corridor is fragmenting as new domestic capacity targets steel self-sufficiency. RHI Magnesita leverages vertical integration from magnesite mining to finished monolithics, securing raw material certainty. Vesuvius anchors its position through specialized flow control refractories for continuous casting. Krosaki Harima Corporation competes on advanced silica-alumina formulations for glass tank applications.
Refractory cement denotes a hydraulic bonding system combining calcium aluminate clinker with selected aggregates, designed to withstand temperatures exceeding 1,400°C while maintaining structural integrity in thermal cycling environments. The material serves primarily as linings for furnaces, kilns, and reactors where conventional Portland cement would fail. Low cement castables command premium positioning due to superior hot strength and reduced porosity, while ultra-low cement variants represent the fastest-growing formulation class as energy-intensive industries pursue thinner, more durable linings. Conventional high-cement products retain volume dominance in emerging markets where initial cost sensitivity outweighs lifecycle performance considerations.
EPA emissions standards and OSHA workplace exposure limits in the United States compel reformulation toward lower silica and hexavalent chromium content. REACH registration requirements and the EU Green Deal carbon border adjustments in Europe reshape competitive access for imported refractory products. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography may not transfer cleanly to another, fragmenting product portfolios and testing regional manufacturing flexibility.
Market Dynamics
Blast furnace relining cycles in Indian steel production are compressing from ten-year intervals toward seven-year cycles under tighter emissions protocols, forcing refractory cement specifications toward higher-performance formulations that withstand accelerated thermal stress.
Growth Catalysts
- EPA Emissions Standards:US steel producers face binding limits on particulate and hexavalent chromium discharge, compelling wholesale replacement of conventional high-cement linings with low-cement alternatives that reduce permeability and leaching risk.
- India's Steel Self-Sufficiency Push:The country's PLI scheme for specialty steel is expanding domestic blast furnace capacity, creating sustained demand for calcium aluminate-based monolithics in new build and rebuild cycles.
- Ultra-Low Cement Formulations:These advanced castables deliver superior hot strength and reduced porosity, enabling thinner lining designs that cut thermal mass and fuel consumption in integrated mills.
Market Restraints
- Magnesite Supply Concentration:Captive mining rights in Austria, Turkey, and China concentrate high-purity dead-burned magnesite supply among vertically integrated refractory producers, limiting formulation flexibility for independent blenders.
- REACH Registration Burden:European ECHA compliance costs for calcium aluminate clinker and reactive alumina imports create asymmetric market access, disadvantaging smaller exporters to EU member states.
- Silicon Carbide Substitution:Advanced ceramic-matrix composites and pre-fired silicon carbide shapes are displacing cement-bonded linings in select high-abrasion zones of cement kilns and waste incinerators.
Strategic Opportunities
- Hydrogen-Ready Furnace Retrofits:European steelmakers preparing for hydrogen-direct reduction arc furnace transitions require entirely new refractory chemistries resistant to hydrogen embrittlement and altered thermal profiles.
- EU Green Deal Carbon Border Adjustments:The CBAM mechanism creates competitive shelter for EU-based refractory producers against imports from carbon-intensive manufacturing jurisdictions, rewarding localized production investments.
- Digital Refractory Monitoring:Integration of IoT thermocouple arrays and predictive wear algorithms enables outcome-based lining service contracts, shifting revenue from material sales to performance guarantees.
Industry Challenges
- Refractory Installation Technician Shortage:Specialized skills in gunning, ramming, and casting of monolithic linings are aging out in Germany, Japan, and the United States faster than apprenticeship pipelines replenish.
- Multi-Jurisdiction Certification Complexity:Divergent BIS, ASTM, and EN standards for castable classification create SKU proliferation, forcing manufacturers to maintain parallel inventory and testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refractory Cement Market |
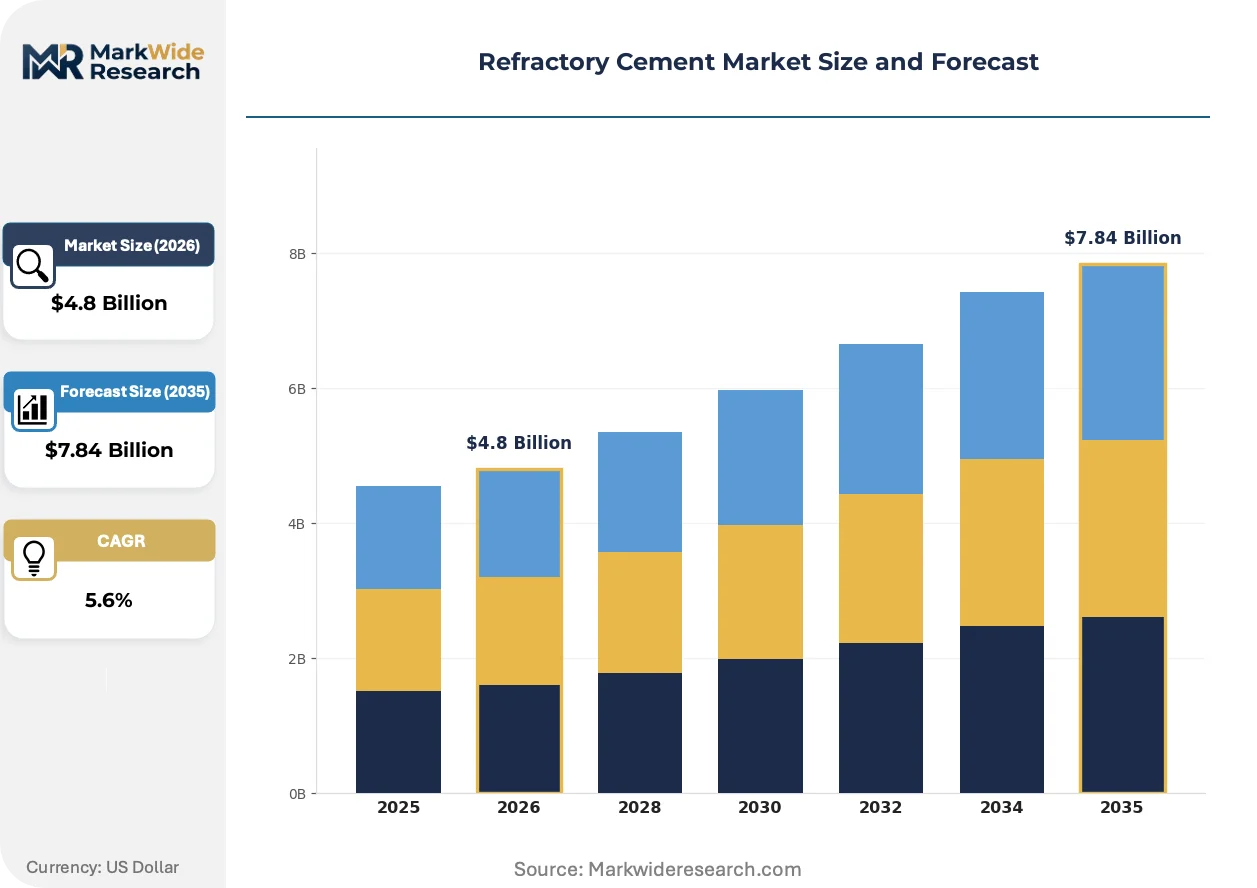
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Cement, Ultra-Low Cement, Conventional, Castable Application: Steel Production, Glass Manufacturing, Cement Industry, Petrochemical Processing End User: Heavy Industries, Construction Companies, Energy Sector, Manufacturing Firms Form: Blocks, Coatings, Castings, Preformed Shapes |
| Companies Covered | RHI Magnesita, Vesuvius, Saint-Gobain, Krosaki Harima Corporation, Shinagawa Refractories Co., Ltd., Imerys, Calderys, HarbisonWalker International, Morgan Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refractory Cement Market Evolving Landscape
Thermal efficiency mandates and digitalization are restructuring how refractory cement is specified, procured, and deployed across energy-intensive industries. Formulation chemistry, regulatory compliance architecture, and buyer-vendor relationships are all undergoing simultaneous recalibration.
Nano-engineered colloidal silica binders are replacing conventional calcium aluminate hydraulic bonds in critical superstructure applications. Leading glass tank operators in Germany and Japan have adopted these systems for crown repairs requiring extended campaign life. The technology is migrating from specialty rebuilds toward standard new construction specifications as total cost-of-ownership data accumulates.
REACH registration requirements for calcium aluminate clinker are tightening purity and traceability documentation across EU supply chains. ECHA's 2023 update to Annex XVII restrictions on chromium(VI) compounds is forcing reformulation of traditional chrome-magnesite and chrome-alumina castables. Steel producers in Poland and Italy are accelerating qualification of chromium-free spinel-bonded alternatives ahead of enforcement deadlines.
Integrated steel mills are consolidating refractory procurement under single-source performance contracts spanning installation, maintenance, and residual value recovery. Traditional material suppliers in India and Brazil are losing direct mill relationships to full-service refractory management firms. This consolidation is most visible in blast furnace and basic oxygen furnace operations where unplanned outages carry catastrophic cost penalties.
Refractory Cement Market Segmentation
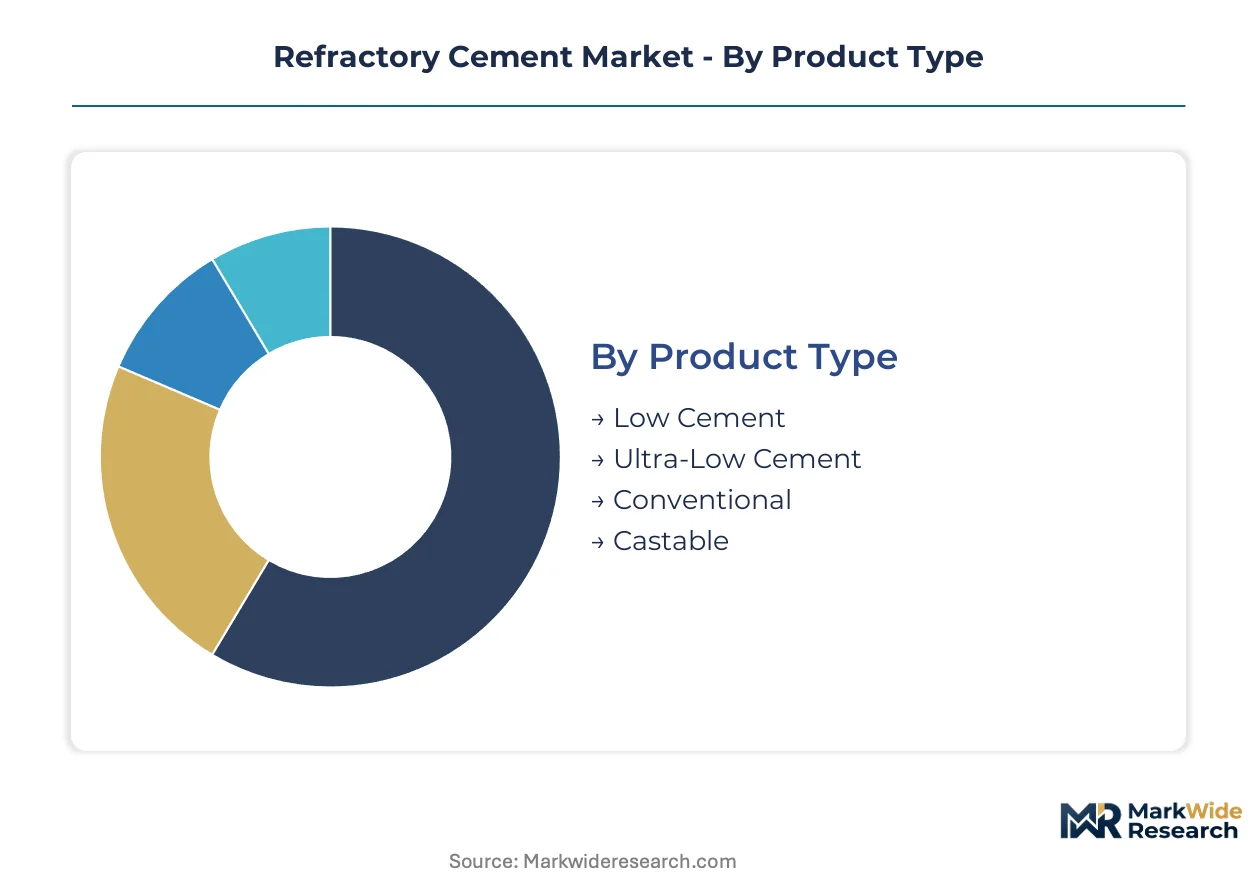
Refractory cement specifications diverge sharply across thermal cycling intensity, installation method, and regulatory exposure. Segmentation mapping reveals which formulations command lifecycle premiums versus which serve as commodity replacements in cost-sensitive rebuild cycles.
Product Type:
Cycle times compress fastest in ultra-low cement formulations as steel mills chase thermal efficiency, while conventional high-cement products turn over slowest in emerging market maintenance schedules.
- Low Cement:Calcium aluminate content below 8% enables superior hot strength and reduced permeability against slag penetration. Indian integrated steel mills specify these for blast furnace hearth linings under tighter emissions protocols that accelerate relining frequency.
- Ultra-Low Cement:Sub-3% cement levels with microsilica and dispersant packages deliver thinnest practical lining designs. European hydrogen-direct reduction pilot furnaces are qualifying these chemistries first, given unproven thermal profiles in hydrogen-rich atmospheres.
- Conventional:Standard calcium aluminate bonded castables retain dominance in Southeast Asian cement kiln repairs where initial cost sensitivity outweighs lifecycle performance tracking.
- Castable:Pumpable and shotcrete-applied monolithics reduce skilled labor dependency in Japanese steelworks facing technician shortages.
Conventional products dominate installed base. Ultra-low cement formulations are where expansion concentrates.
Application:
Cost tier separation runs sharpest here, with steel production absorbing premium formulations and cement industry maintenance defaulting to standard grades.
- Steel Production:Blast furnace stacks, torpedo ladles, and basic oxygen vessels demand the highest performance tier. Polish and Italian mills are converting chrome-magnesite linings to chromium-free spinel alternatives ahead of ECHA enforcement deadlines.
- Glass Manufacturing:Crown and superstructure repairs in German float glass tanks have adopted nano-engineered colloidal silica binders for extended campaign life, migrating from specialty rebuilds toward standard specifications.
- Cement Industry:Preheater tower and kiln inlet zones in Brazilian operations balance abrasion resistance against fuel cost pressures, often selecting silicon carbide-enhanced castables.
- Petrochemical Processing:Fluid catalytic cracker units and reformer furnaces in US Gulf Coast facilities face EPA hexavalent chromium discharge limits, compelling low-cement conversions that reduce leaching risk.
Steel production commands premium formulation share. Glass manufacturing is climbing the fastest on total cost-of-ownership validation.
End User:
Customer type determines procurement consolidation intensity, with heavy industries shifting toward single-source performance contracts and construction companies remaining fragmented.
- Heavy Industries:Integrated steel and petrochemical operators in India and Brazil are consolidating refractory procurement under full-service management firms covering installation through residual value recovery.
- Construction Companies:Project-based contractors in the US and Germany maintain spot purchasing relationships, lacking volume leverage for performance-guarantee negotiations.
- Energy Sector:Waste-to-energy incinerator operators in Japan specify preformed silicon carbide shapes displacing cement-bonded linings in high-abrasion grate zones.
- Manufacturing Firms:Specialty ceramics and non-ferrous metal producers across Austria and Turkey source from vertically integrated magnesite miners with captive dead-burned ore supply.
Heavy industries concentrate volume. Energy sector specifications are gaining share fastest on thermal efficiency mandates.
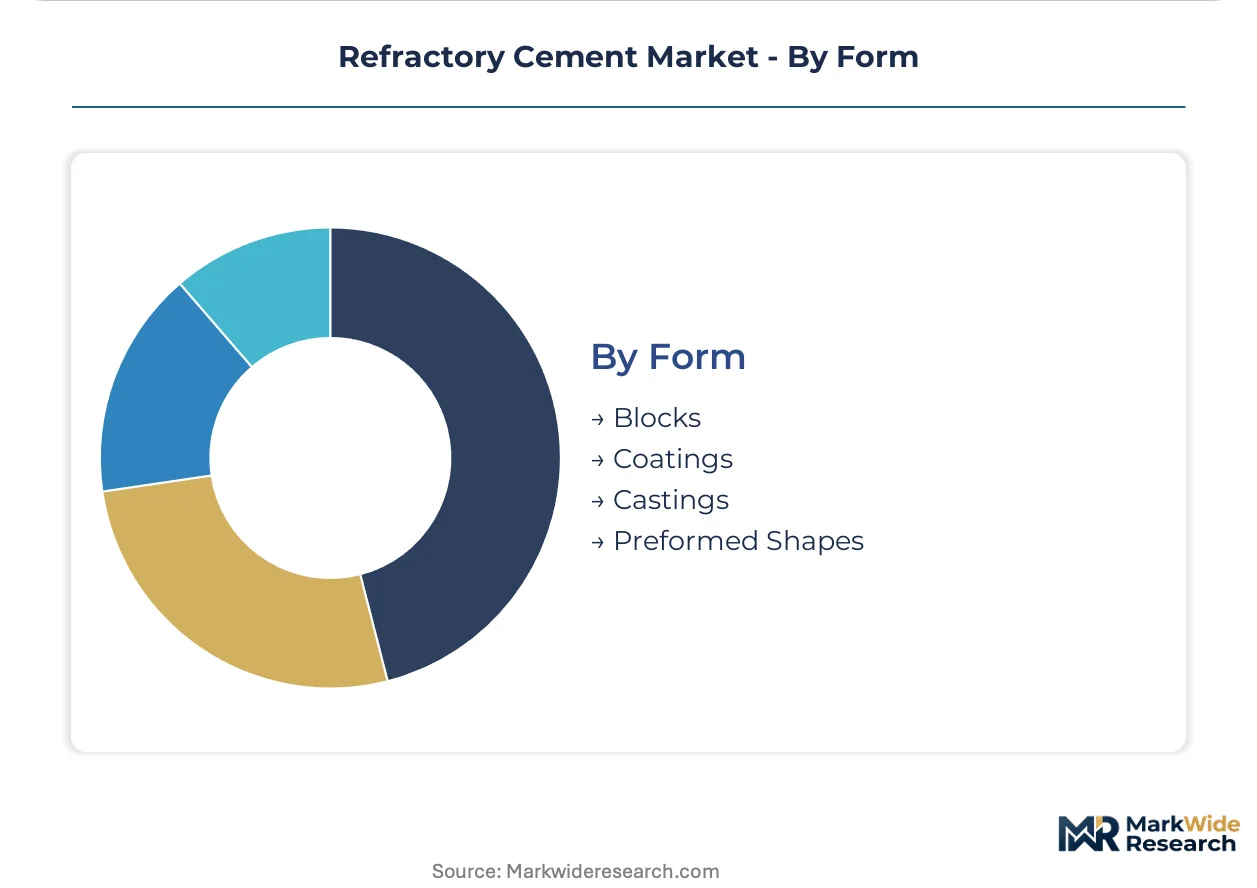
Form:
Supply concentration shapes competitive access, with preformed shapes requiring capital-intensive pressing infrastructure and coatings remaining most accessible to regional blenders.
- Blocks:Standard pressed and fired shapes serve commodity replacement cycles in Indian cement sector maintenance, with BIS certification requirements creating inventory complexity for multi-jurisdiction suppliers.
- Coatings:Trowel and spray-applied repair mortars address emergency outage scenarios in US steel mini-mills where unplanned downtime carries catastrophic cost penalties.
- Castings:Site-poured monolithics dominate new construction specifications across European hydrogen-ready furnace retrofits requiring custom lining geometries.
- Preformed Shapes:Precision-pressed burner blocks and impact pads anchor positions for specialized flow control suppliers serving continuous casting operations.
Blocks dominate installed base. Preformed shapes are where specification value is concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Indian steel mills prioritize blast furnace relining frequency under emissions pressure, while European operators invest in hydrogen-ready chemistries. US specifications pivot on EPA discharge limits, and Chinese producers optimize for captive magnesite supply chains.
India
Blast furnace relining cycles compress toward seven-year intervals under tighter emissions protocols. The PLI scheme for specialty steel expands domestic capacity, sustaining demand for calcium aluminate monolithics. Integrated mills in the Bhilai-Rourkela corridor specify higher-performance formulations to withstand accelerated thermal stress.
United States
EPA hexavalent chromium and particulate discharge limits compel wholesale replacement of conventional high-cement linings. Gulf Coast petrochemical facilities face binding exposure thresholds, driving low-cement conversions that reduce permeability. Steel producers in the Great Lakes industrial belt absorb premium formulations to mitigate leaching risk.
Germany
REACH Annex XVII restrictions on chromium(VI) compounds force reformulation of traditional chrome-magnesite castables. ECHA compliance costs reshape competitive access for imported calcium aluminate clinker. Glass tank operators in the Rhine-Ruhr region adopt nano-engineered colloidal silica binders for extended campaign life.
China
Captive mining rights in Liaoning and Shandong provinces concentrate high-purity dead-burned magnesite supply among vertically integrated producers. Domestic steel capacity expansion absorbs formulated refractories for new build cycles. Environmental enforcement in the Yangtze River Delta tightens particulate standards for kiln operations.
Japan
Specialized gunning and ramming skills age out faster than apprenticeship pipelines replenish. METI efficiency mandates push thinner lining designs in integrated steelworks. Continuous casting operations in the Chubu region anchor demand for precision flow control refractories.
Refractory Cement Market Competitive Landscape
Capability concentration sits with vertically integrated miners of dead-burned magnesite; scale advantage sits with full-service refractory management firms covering installation through residual value recovery. The vendor base stratifies across three tiers: captive resource holders, formulation specialists, and regional blenders. Two dominant competitive moves define positioning: backward integration into magnesite mining and consolidation of procurement relationships under single-source performance contracts.
Among European-anchored suppliers, RHI Magnesita and Imerys exemplify the vertically integrated archetype, securing raw material certainty from mining through finished monolithics. Vesuvius occupies a position on the specialized flow control vector, serving continuous casting operations where unplanned outages carry catastrophic cost penalties. These three names anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| RHI Magnesita |
| Vesuvius |
| Saint-Gobain |
| Krosaki Harima Corporation |
| Shinagawa Refractories Co., Ltd. |
| Imerys |
| Calderys |
| HarbisonWalker International |
| Morgan Advanced Materials |
| Others |
Value Network & Pricing Analysis
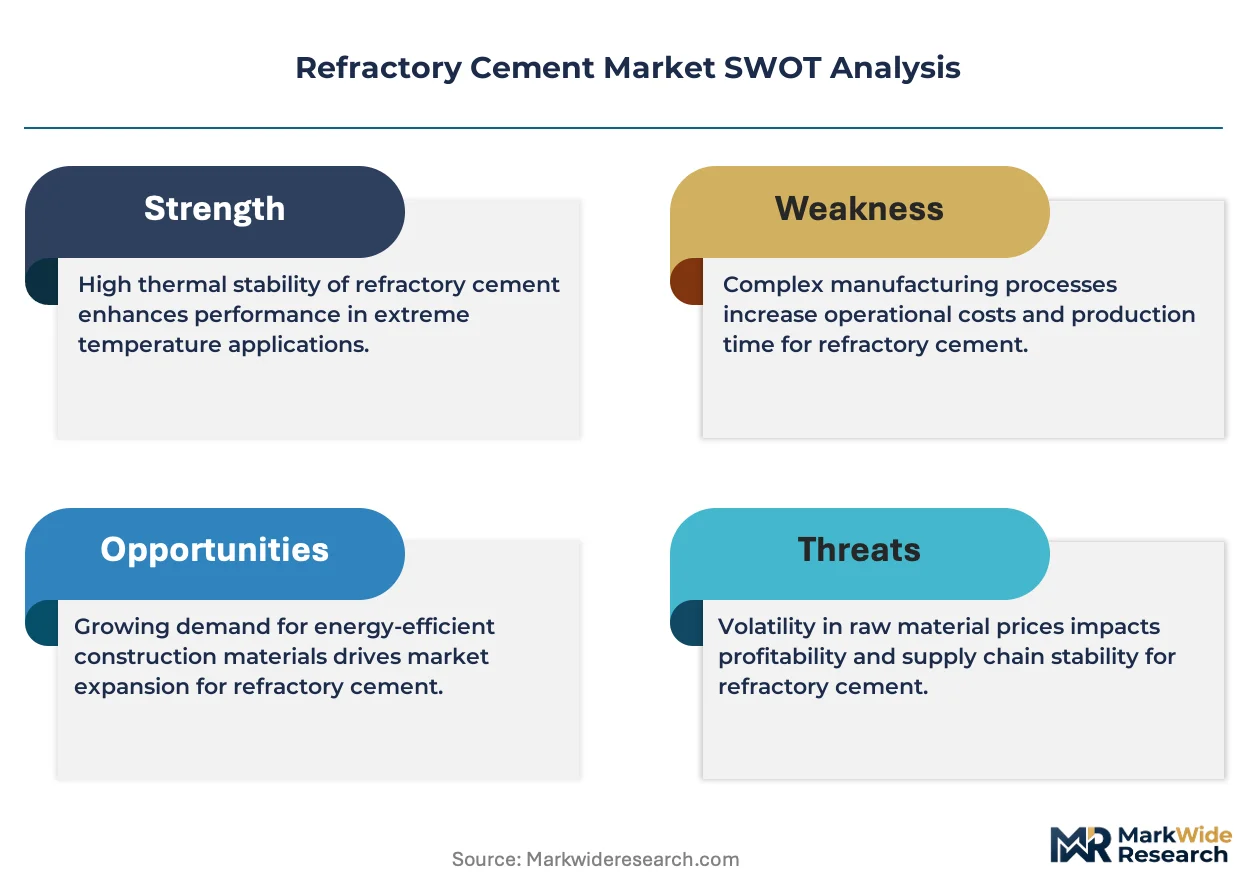
Captive mining rights in Austria, Turkey, and China for high-purity dead-burned magnesite concentrate margin pools with vertically integrated refractory producers, forcing independent blenders to absorb raw material volatility or cede share to upstream-controlled competitors.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between integrated steel mills and refractory suppliers, insulating premium-tier buyers from spot volatility while project-based contractors in construction face raw material pass-through exposure. Three-tier pricing structure across premium, standard, and economy levels separates ultra-low cement formulations for hydrogen-ready furnaces from conventional high-cement products in Southeast Asian maintenance cycles. Cost compression in standard-grade castables is intensifying because Brazilian and Indian cement producers prioritize initial acquisition cost over lifecycle performance tracking. Heavy industries with consolidated procurement under single-source performance contracts exhibit lowest price sensitivity, while construction companies lacking volume leverage face acute margin pressure.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for European steelmakers qualifying new refractory suppliers, compressing working capital for independent blenders competing against vertically integrated majors with captive financing capacity. Geographic supply concentrates in China, Austria, and Turkey for dead-burned magnesite, with Brazil and India serving as secondary hubs for bauxite-derived calcium aluminate clinker. Formulation chemistry draws from reactive alumina, microsilica, and specialty dispersant packages sourced through concentrated chemical distributor networks. Single-source vulnerability runs through Liaoning province magnesite operations, where environmental enforcement intermittently disrupts export availability. Distribution runs through regional blending facilities co-located with steel mill clusters, minimizing freight exposure for monolithic products with limited shelf stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refractory cement market fragmentation creates niche opportunities as hydrogen-direct reduction furnace retrofits and REACH-driven chrome-free reformulation split established specification standards, opening entry points for specialized chemistry suppliers.
For Market Incumbents: Harden supply security through backward integration into magnesite mining or binding long-term offtake agreements with Austrian and Turkish ore producers, insulating against raw material volatility that threatens margin stability. Deepen captive production of reactive alumina and microsilica to reduce dependency on chemical distributor intermediaries. Invest in ECHA pre-registration documentation for calcium aluminate clinker imports to defend EU market access against compliance-cost barriers affecting smaller competitors. For New Entrants and Emerging Players: Southeast Asian cement kiln maintenance represents the most penetrable geography, where conventional high-cement castables retain dominance and local blending capacity remains fragmented against global majors. Target Brazilian preheater tower repairs with silicon carbide-enhanced formulations that balance abrasion resistance against fuel cost pressures. Pursue qualification partnerships with regional construction contractors lacking direct mill relationships, leveraging project-based spot purchasing to bypass consolidated procurement gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed refractory management firms consolidating installation-through-residual-value recovery contracts across Indian and Brazilian steel corridors. Five-to-ten year viability hinges on hydrogen furnace chemistry qualification timelines and digital monitoring technology integration. Monitor ECHA enforcement deadlines for chromium(VI) compound restrictions as inflection indicator for chrome-free spinel formulation adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesite Mining | Captive ore supply from Austria and Turkey secures raw material certainty against export disruptions. |
| Hydrogen-Ready Furnace Chemistry Qualification | European steelmakers preparing for direct reduction arc furnace transitions require entirely new refractory specifications. |
| Digital Refractory Monitoring Integration | IoT thermocouple arrays enable outcome-based service contracts shifting revenue from material sales to performance guarantees. |
| REACH-Compliant Chrome-Free Reformulation | ECHA Annex XVII restrictions on chromium(VI) compounds force accelerated adoption of spinel-bonded alternatives in Poland and Italy. |
| Regional Blending Facility Expansion | Co-location with steel mill clusters in India's Bhilai-Rourkela corridor minimizes freight exposure for monolithic products. |
Research Methodology
Cross-validation between plant manager interviews at integrated steel mills and customs trade data for calcium aluminate clinker imports anchors the qualitative findings in quantifiable flow patterns. Primary fieldwork engaged refractory procurement directors, technical R&D leads at formulation specialists, installation contractors specializing in gunning and ramming techniques, and regulatory affairs managers navigating ECHA compliance pathways. Secondary validation drew from SEC 10-K filings of publicly traded refractory producers, BIS certification registries for Indian castable classifications, ECHA REACH submission databases, and trade association reports from regional steel federations. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the analysis window.
Calibration against historical relining cycle data from European and Indian blast furnace operations refined the projection framework. Segmentation dimensions modeled include cement content tier, end-use application intensity, installation method, and regional regulatory cluster. CAGRs derived from weighted average of demand elasticity estimates and capacity expansion announcements. Industry-specific forecast inputs incorporated PLI scheme capacity targets for Indian specialty steel and EPA enforcement timelines for hexavalent chromium discharge limits.
Practitioners should monitor ECHA enforcement action intensity, hydrogen furnace pilot project scale-up rates, and magnesite export licensing changes in Liaoning province for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
US Cement Tiles Market
Building Materials
Engineered Wood Product Market
Building Materials
East Africa Cement Market
Building Materials
Stone Adhesive Market
Building Materials
Fiber Cement Market
Building Materials
Southeast Asia Concrete Admixtures Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Earthen Plasters Market
Building Materials
Masonry Cement Market
Building Materials
Ireland Cement Market
Building Materials
Global Building Panels Market
Building Materials
Steel Products Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Lightweight Cellular Concrete Market