
 Steel Slag Market | 2026-2036
Steel Slag Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Slag Market Analytics
Slag processing as a service-component layer is consolidating around integrated logistics and quality-certification bundles that steel mills now sell alongside raw material. ArcelorMittal leverages its European processing network to control blast furnace slag beneficiation. Nippon Steel Corporation anchors high-purity granulated output for specialty cement blends in East Asian markets. POSCO competes on scale, operating some of the largest slag cooling and magnetic separation facilities globally.
Steel slag is the non-metallic byproduct of steelmaking, composed primarily of calcium silicates, iron oxides, and alumina formed during the separation of molten steel from impurities; its industrial purpose centers on replacing virgin aggregate and clinker in heavy construction. Granulated slag leads value capture due to its hydraulic reactivity and premium pricing in blended cement formulations, while air-cooled slag occupies the mature road-base segment with thinner margins. LD slag from basic oxygen furnaces is the fastest-growing product type as steelmakers invest in metal recovery and phosphorus stabilization technologies.
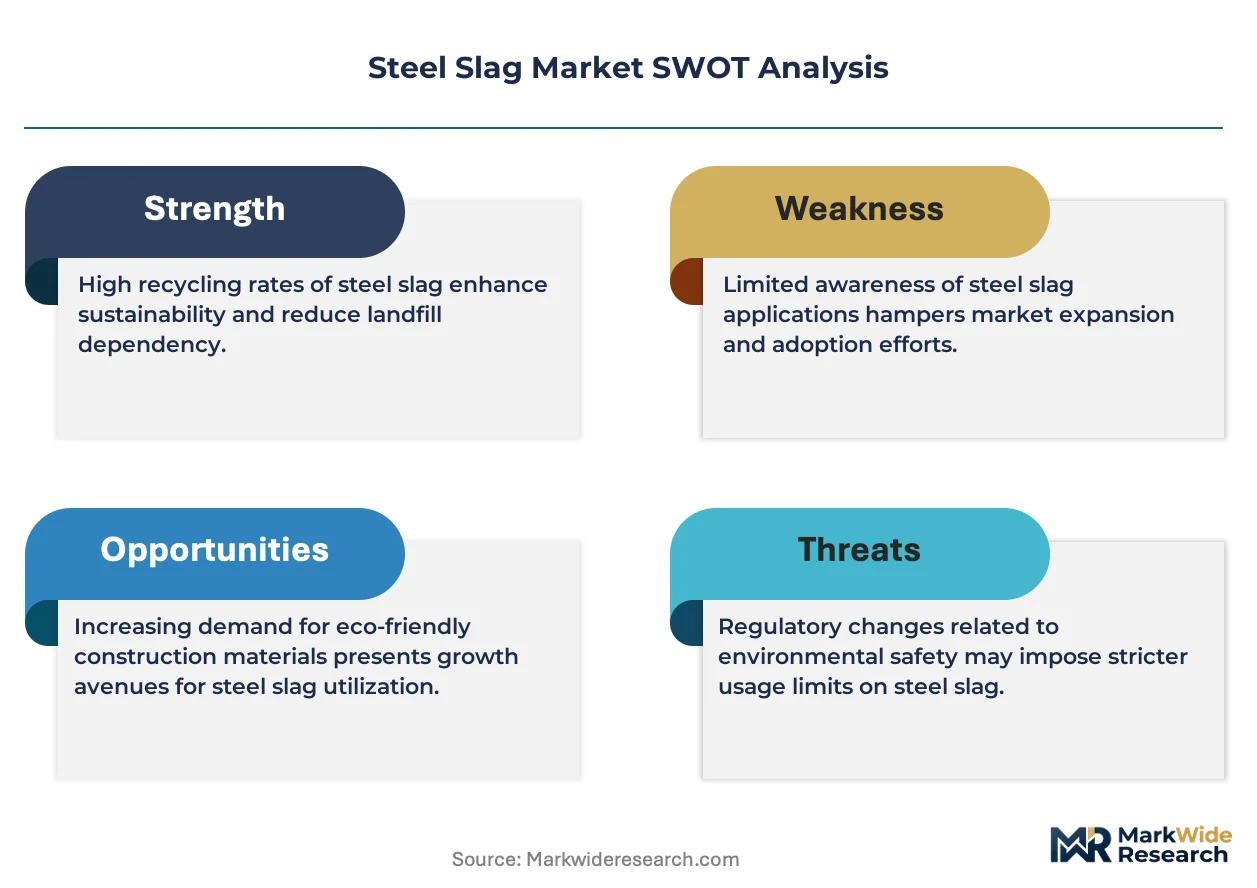
China's MEE enforces emissions caps on slag stockpiles under dual carbon targets, while India's CEA mandates fly-ash and slag utilization rates in government infrastructure projects to reduce landfill pressure. The EU's CSRD will require Scope 3 disclosure for construction materials, elevating traceability demands on slag supply chains. Stakeholders must monitor how carbon-border adjustments and evolving national building codes reshape competitive access across integrated steel regions.
Market Dynamics
Cement producers are consolidating slag procurement under long-term offtake agreements tied to carbon-intensity benchmarks, compressing spot-market liquidity and elevating integrated steel mills to gatekeeper status over supplementary cementitious material supply chains.
Growth Catalysts
- India's PLI scheme:Infrastructure subsidies under the Production Linked Incentive framework are accelerating bulk slag consumption in government road and dam projects.
- EU CSRD disclosure mandates:Scope 3 reporting requirements for construction materials are forcing contractors to source certified low-carbon slag alternatives to virgin aggregate.
- Phosphorus stabilization:Metal recovery technologies for LD slag are unlocking new feedstock volumes previously stockpiled as waste.
Market Restraints
- Electricity cost volatility:Granulation and magnetic separation are energy-intensive; European mills face margin compression from grid price spikes.
- Chinese supply concentration:Blast furnace slag beneficiation capacity clusters in Hebei and Shandong provinces, creating single-point failure risk.
- Natural aggregate substitution:Crushed limestone remains price-competitive in road-base applications where certification premiums do not apply.
Strategic Opportunities
- Southeast Asia infrastructure buildout:Vietnam and Indonesia lack domestic granulation capacity, creating import demand for processed slag.
- Carbon-capture concrete:Slag's hydraulic reactivity is converging with mineral carbonation processes to produce negative-emission building materials.
- Digital quality certification:Blockchain-traceable slag batches command price premiums from ESG-focused contractors in Nordic markets.
Industry Challenges
- Metallurgical expertise scarcity:Slag chemistry optimization requires specialized knowledge in calcium-silicate phase control that retiring blast furnace operators possess.
- Leaching compliance timelines:Batch testing for heavy metal mobility under varying national environmental standards delays shipment releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Slag Market |
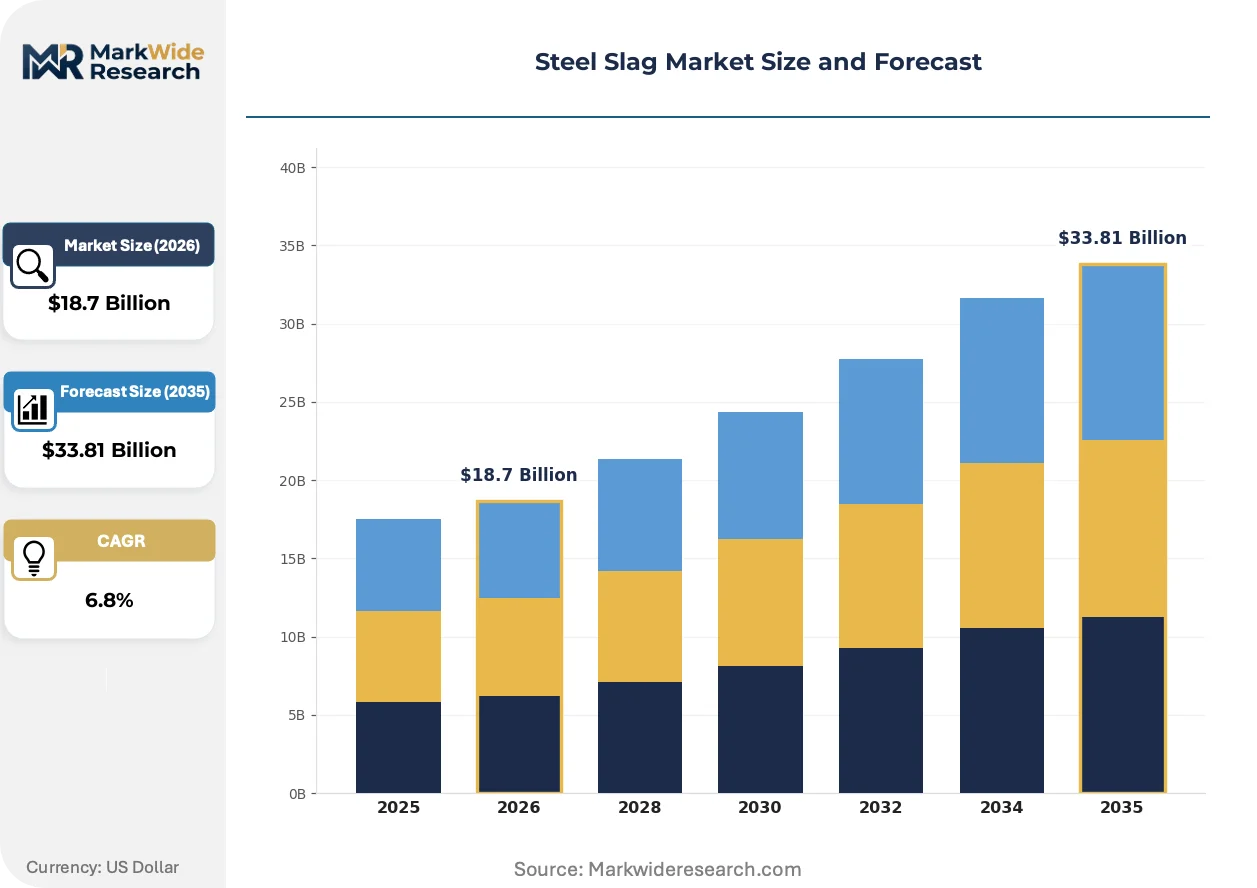
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled Slag, Granulated Slag, LD Slag, Stainless Steel Slag Application: Construction, Road Base, Cement Production, Agriculture End User: Construction Companies, Road Maintenance Agencies, Cement Manufacturers, Agricultural Sector Packaging Type: Bulk Bags, Loose, Custom Packaging, Palletized |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, POSCO, China Baowu Steel Group, Tata Steel, JFE Steel Corporation, Steel Authority of India Limited, Thyssenkrupp AG, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Slag Market Evolving Landscape
Slag valorization is pivoting from commodity aggregate sales toward engineered cementitious products with certified carbon footprints, rewiring how steel mills monetize byproduct streams.
Artificial intelligence-driven predictive cooling is converging with traditional blast furnace slag processing to optimize glass content and reactivity. Cement blenders in Germany and Japan are adopting AI-graded granulated output for high-performance concrete formulations. This convergence is compressing quality variance and enabling premium pricing tiers tied to predictable hydraulic performance.
China's MEE enforcement of dual carbon targets is tightening emissions caps on unprocessed slag stockpiles, forcing steelmakers to accelerate beneficiation investments or face operating penalties. The policy is shifting slag from waste liability to tracked co-product status. Basic oxygen furnace operators in Jiangsu and Anhui provinces are responding by integrating magnetic separation lines to recover metallic iron before granulation.
Long-term offtake contracting is displacing spot procurement among European ready-mix concrete producers seeking supply security for certified low-carbon product lines. The shift is concentrating buyer power with integrated steel mills that can guarantee batch-level carbon accounting. This pattern is most visible in the Netherlands and Denmark where public infrastructure tenders mandate embodied carbon thresholds.
Steel Slag Market Segmentation
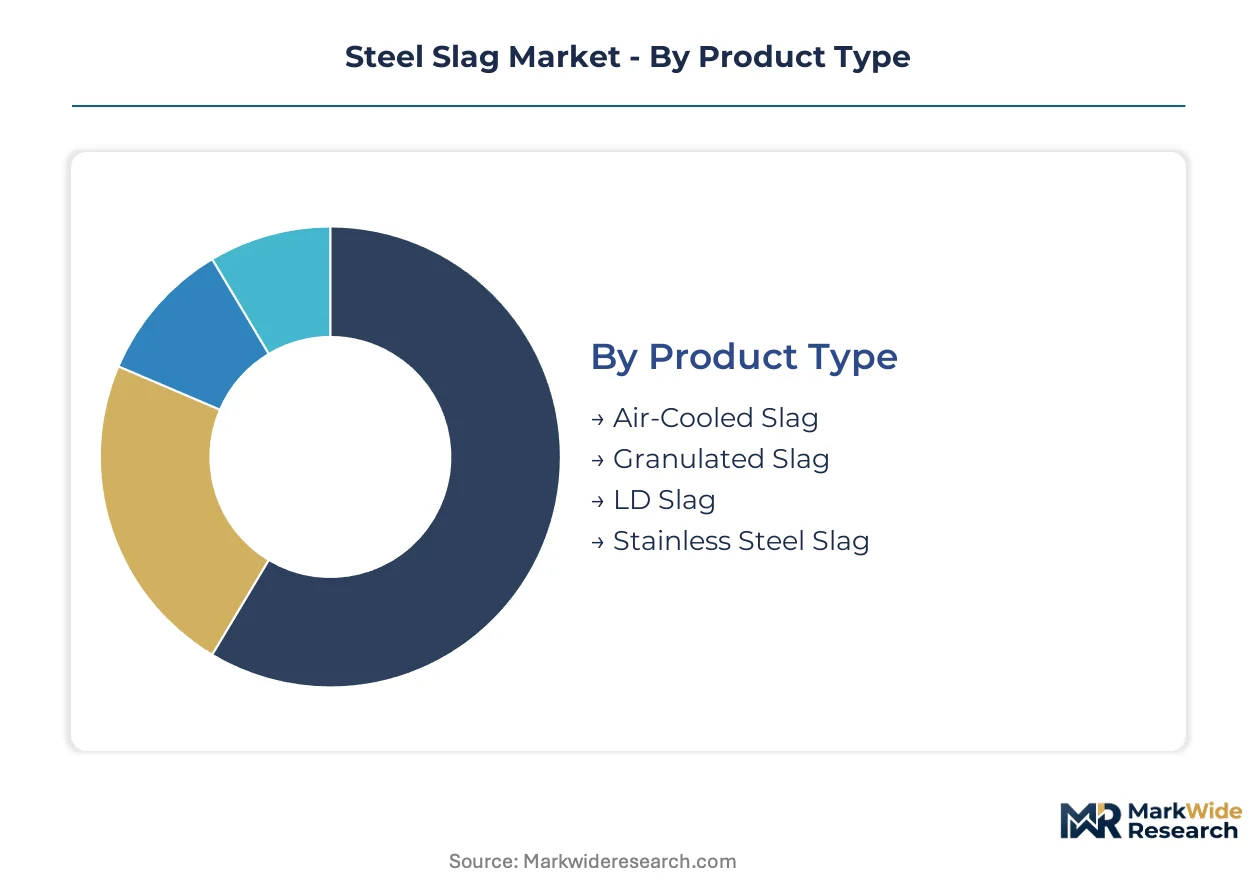
Steel slag market segmentation reflects divergent processing intensities and certification requirements across construction supply chains. Product chemistry and cooling methods determine value capture, while application specifications dictate logistics and quality protocols.
Product Type:
Granulation technology and cooling rates define the reactivity spectrum and pricing tiers across slag categories.
- Granulated Slag:Rapid water-quenching produces glassy calcium-silicate structures with hydraulic reactivity comparable to Portland cement clinker. Cement manufacturers in Germany and Japan prioritize this grade for high-performance concrete formulations where carbon-intensity benchmarks apply.
- LD Slag:Basic oxygen furnace output contains recoverable metallic iron and stabilized phosphorus compounds requiring magnetic separation and weathering treatment. Indian steelmakers under CEA utilization mandates are expanding metal recovery lines to unlock previously stockpiled volumes for road and dam projects.
- Air-Cooled Slag:Slow atmospheric cooling yields crystalline aggregate for unbound road base and railway ballast with lower processing energy input.
- Stainless Steel Slag:Chromium and nickel content requires specialized leaching protocols before construction use; limited volumes serve niche marine and chemical-resistant applications.
Granulated slag leads on scale; LD slag leads on momentum.
Application:
End-use specifications split the market between commodity aggregate and engineered cementitious material with divergent margin profiles.
- Cement Production:Granulated slag serves as supplementary cementitious material replacing clinker at rates up to 50% in blended cements. European ready-mix producers under CSRD disclosure mandates source certified low-carbon batches with blockchain-traceable emissions data.
- Construction:Processed slag aggregate substitutes virgin crushed rock in structural concrete and masonry units where strength grading and dimensional stability are specified.
- Road Base:Unbound and hydraulically bound layers consume air-cooled and weathered LD slag in heavy-duty pavement foundations with thinner certification premiums.
- Agriculture:Liming applications utilize calcium-rich slag to neutralize acidic soils; regulatory scrutiny on heavy metal mobility limits deployment to specific soil chemistry profiles.
Cement production commands the highest value per ton; road base moves the largest absolute volumes.
End User:
Procurement scale and technical capability determine whether buyers access spot markets or integrated mill offtake agreements.
- Cement Manufacturers:Integrated producers with in-house grinding capacity source granulated slag under long-term contracts tied to carbon-intensity thresholds and quality consistency metrics.
- Construction Companies:General contractors and specialty concrete suppliers purchase certified aggregate and blended cement products with specified embodied carbon limits for public infrastructure tenders.
- Road Maintenance Agencies:Government highway departments procure bulk air-cooled and processed LD slag through competitive bidding for pavement rehabilitation and new alignment projects.
- Agricultural Sector:Regional distributors and farming cooperatives acquire liming materials through agricultural supply chains with soil testing and application advisory services.
Cement manufacturers concentrate buying power; road agencies drive spot price formation.
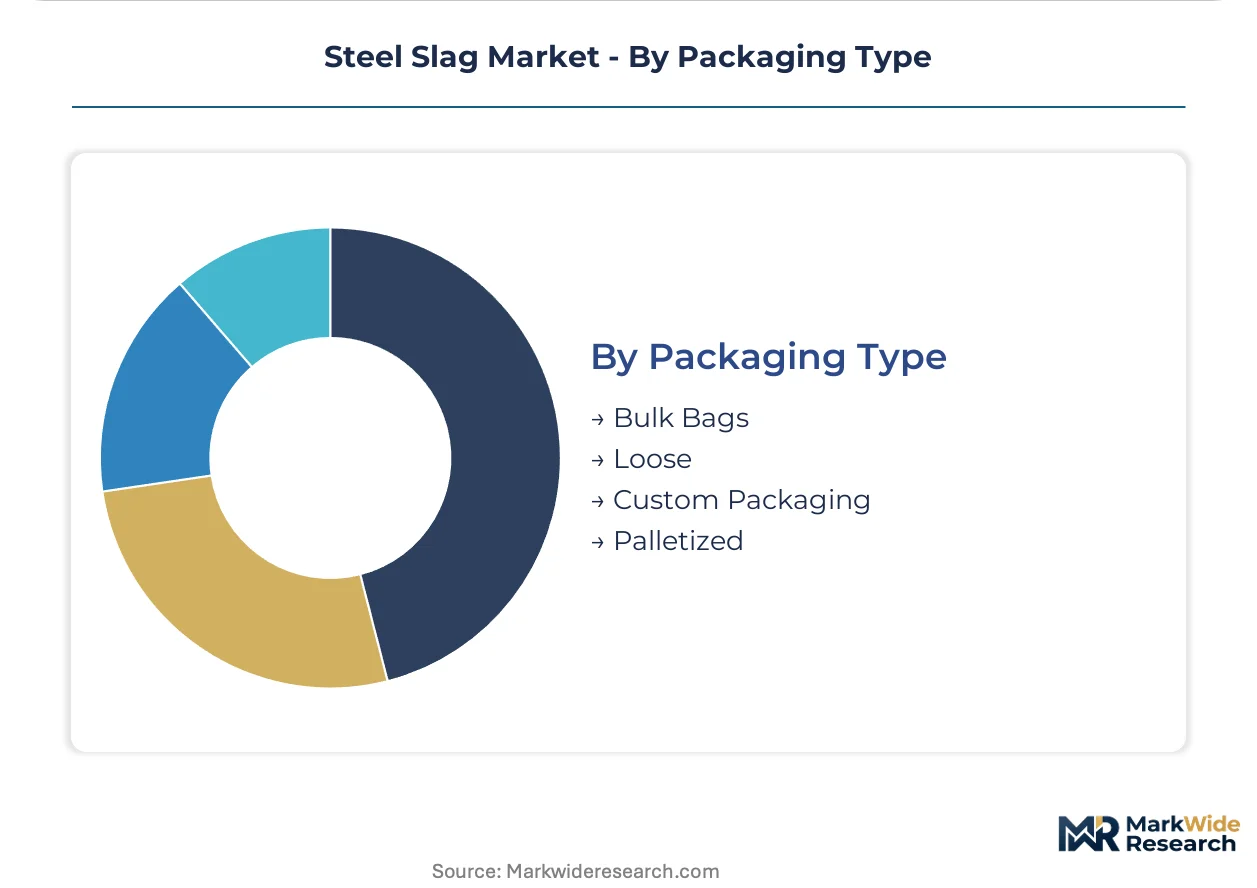
Packaging Type:
Logistics configuration aligns with end-user material handling infrastructure and project scale requirements.
- Bulk Bags:One-tonne flexible intermediate bulk containers serve ready-mix plants and mid-scale construction sites lacking pneumatic unloading systems.
- Loose:Direct pneumatic or conveyor delivery from slag processing plants to cement grinding stations and large infrastructure projects minimizes handling costs at volume.
- Custom Packaging:Specialty blends and high-purity grades for research or repair applications require moisture-barrier and contamination-controlled containers.
- Palletized:Shrink-wrapped bagged product enables forklift handling at small commercial and agricultural endpoints with limited storage infrastructure.
Loose delivery dominates tonnage; bulk bags capture margin in fragmented downstream markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel slag processing capacity migrates toward jurisdictions with lower carbon-compliance costs and stronger infrastructure subsidy regimes, creating divergent investment patterns across integrated steel corridors.
China
Hebei and Shandong provinces host the densest blast furnace slag beneficiation clusters, serving domestic cement demand and export markets. MEE emissions caps under dual carbon targets now penalize unprocessed slag stockpiles, forcing mills in Jiangsu and Anhui to accelerate magnetic separation and granulation investments. The Yangtze River Delta concentration is tightening as environmental enforcement intensifies.
India
CEA utilization mandates for fly-ash and slag in government infrastructure projects are unlocking previously stockpiled LD slag volumes for road and dam construction. Steel Authority of India Limited and private mills in Odisha and Jharkhand are expanding metal recovery lines to meet PLI scheme procurement quotas. The eastern steel belt is becoming the primary beneficiation hub for bulk aggregate supply.
Germany
Ready-mix concrete producers under CSRD disclosure mandates source certified low-carbon granulated slag with blockchain-traceable emissions data. Thyssenkrupp and ArcelorMittal's European processing networks control blast furnace slag beneficiation for specialty cement blends. The Ruhr industrial corridor anchors high-purity output for Nordic and Benelux infrastructure tenders with embodied carbon thresholds.
United States
Nucor Corporation and electric arc furnace operators in the Southeast are developing slag valorization for road-base applications where natural aggregate price premiums are narrow. EPA leaching protocols for heavy metal mobility create compliance timelines that delay shipment releases from stockpiles in Indiana and Ohio. The Midwest rust belt retains latent processing capacity awaiting regulatory clarity on beneficial reuse classification.
Japan
JFE Steel Corporation and Nippon Steel Corporation anchor granulated slag output for high-performance concrete formulations in earthquake-resistant construction. METI industrial efficiency standards incentivize slag cooling optimization to maximize glass content and hydraulic reactivity. The Chubu and Kansai industrial zones concentrate beneficiation capacity for specialty cement exports to Southeast Asian markets lacking domestic granulation infrastructure.
Steel Slag Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated steel mills dominating high-value granulated slag supply chains while independent processors compete on road-base aggregate volume. The market structure concentrates around three archetypes: captive steel mill beneficiation units, independent toll processors, and cement-integrated grinding stations. Consolidation is accelerating through long-term offtake contracting that locks in supply security for carbon-certified product lines. Geographic expansion and technology licensing represent the dominant competitive vectors as players seek access to infrastructure subsidy regimes in India and Southeast Asia.
Among integrated steel producers, ArcelorMittal, Nippon Steel Corporation, and POSCO occupy positions that exemplify the scale-driven archetype, leveraging captive blast furnace output to control beneficiation quality and batch-level carbon accounting. These entities represent the gatekeeper tier that cement manufacturers must contract with for certified supplementary cementitious material supply. Their geographic footprints span European, East Asian, and emerging market corridors where infrastructure buildout and emissions disclosure mandates are converging to elevate slag from waste liability to tracked co-product status.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| POSCO |
| China Baowu Steel Group |
| Tata Steel |
| JFE Steel Corporation |
| Steel Authority of India Limited |
| Thyssenkrupp AG |
| Nucor Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between blockchain-traceable granulated slag and unbound air-cooled aggregate manifests in divergent margin structures and procurement channel configurations across the value chain. Premium-tier material commands long-term offtake contracting with integrated steel mills, while commodity road-base product flows through spot-market distributors with thinner logistics bundles.
Pricing Analysis
Distributor margin compression in European granulated slag channels reflects the shift toward direct mill-to-cement-producer contracting under CSRD disclosure mandates. Three-tier pricing structure across premium-certified, standard-grade, and economy road-base levels separates carbon-accounted batches from unverified aggregate. Pricing pressure stems from electricity cost volatility in granulation and magnetic separation operations. Cement manufacturers under Scope 3 reporting requirements show least price sensitivity; road maintenance agencies in price-competitive limestone markets exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Hebei, Shandong, and Odisha anchor hub-and-spoke patterns for blast furnace and LD slag beneficiation. Supply draws from iron ore, metallurgical coke, and electricity inputs with energy intensity varying by cooling method. Single-source vulnerability concentrates in China's Yangtze River Delta environmental enforcement zone. Distribution runs through captive steel mill logistics networks for certified material and independent bulk handlers for commodity aggregate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in steel slag valorization rests on carbon-accounting premiums displacing commodity spot sales, with certification infrastructure investment unlocking tiered pricing capture.
For Market Incumbents: Deploy long-term offtake contracting as the primary lever to lock cement manufacturer procurement under Scope 3 compliance timelines. ArcelorMittal and Nippon Steel Corporation's European and East Asian processing networks demonstrate how captive beneficiation capacity defends against independent toll processors. Backward integration into magnetic separation and AI-driven cooling optimization preserves quality variance compression that commands premium tiers. For New Entrants and Emerging Players: Toll processors in Vietnam and Indonesia represent the most penetrable channel partner type for import-dependent Southeast Asian infrastructure buildout. White-space targets include granulation capacity gaps in ASEAN markets and digital certification services for ESG-focused Nordic contractors. A processing-as-a-service model bundling logistics and quality verification offers lower capital entry than greenfield beneficiation investments. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale beneficiation specialists possessing metallurgical expertise in calcium-silicate phase control as retiring blast furnace operators exit. Long-term viability over a multi-year horizon favors acquisition targets with established CEA utilization mandate relationships in India or CSRD-compliant carbon accounting infrastructure in Europe. The signal to watch is carbon-border adjustment implementation timing affecting competitive access across integrated steel regions.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks cement producers under Scope 3 disclosure mandates into contracted offtake security. |
| Backward Integration | Captive magnetic separation and granulation capacity defends quality consistency premiums. |
| Green Certification Program | Blockchain-traceable batch carbon accounting commands price premiums from ESG-focused contractors. |
| Joint Venture | Local partnerships in Vietnam and Indonesia bypass granulation capacity deficits for regional supply. |
| Capacity Expansion | Metal recovery line investments in Odisha and Jharkhand unlock PLI scheme procurement quotas. |
Research Methodology
Bottom-up cement and construction sector modeling reconciled against top-down steel mill slag output tracking forms the analytical core of this study. Primary interviews with blast furnace operators, cement procurement directors, road agency materials engineers, and slag processing plant managers combined with secondary validation from customs trade data, CEA utilization reports, SEC filings of integrated steel producers, and EU emissions disclosure registries. Triangulation across stakeholder inputs and documented production flows ensures segment-level consistency.
Historical trendline analysis of granulated slag substitution rates and LD slag metal recovery volumes established baseline trajectories across the projection horizon. Segmentation modeling incorporated product type, application specification, end-user procurement scale, and regional regulatory framework dimensions. CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements in beneficiation infrastructure. Forecast inputs included electricity price volatility assumptions and carbon-border adjustment implementation scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese MEE enforcement intensity and EU CSRD disclosure timeline acceleration. Outputs reflect documented assumptions on infrastructure subsidy continuity and metallurgical expertise availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
West Africa Cement Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Construction Glass Market
Building Materials
Spain Cement Market
Building Materials
Bolt (Fastener) Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Cement Market
Building Materials
Engineered Wood Product Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Composite Rebar Market
Building Materials
Low-E Construction Glass Market