
 Composite Decking and Railing Market | 2026-2036
Composite Decking and Railing Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Decking and Railing Market Analysis
Premium capped composite decking is collapsing the price gap with tropical hardwoods while delivering superior moisture resistance and fade warranties. Trex Company leverages proprietary recycling infrastructure to control feedstock costs across its Nevada and Virginia manufacturing sites. Fiberon anchors its position through specialized PVC-wood hybrid formulations that target coastal humidity zones. Azek dominates the fully synthetic segment with cellular PVC technology that eliminates organic fiber content entirely.
Composite decking and railing comprises extruded or molded profiles manufactured from wood-plastic blends, mineral-reinforced thermoplastics, or cellular PVC, typically formulated with coupling agents and UV stabilizers to achieve dimensional stability under cyclic wet-dry exposure. These systems serve as load-bearing exterior surfaces and fall-protection barriers for elevated structures, replacing pressure-treated lumber in environments where rot, insect damage, or chemical leaching pose durability concerns. Decking boards manufactured from recycled wood-Polypropylene blends capture the largest volume share due to established reclaim supply chains and contractor familiarity with fastening systems. Railing systems represent the fastest-expanding product category as building codes tighten guardrail height and infill requirements across jurisdictions. Professional installation channels concentrate margin pools through bundled design-build contracts that specify complete material packages.
US demand responds to ICC-ES evaluation reports and ASTM D7032 structural performance standards that govern span ratings and fastening compatibility. EPA regulations on pressure-treated lumber disposal costs are tilting lifecycle economics toward recyclable alternatives. California's Department of Forestry and Fire Protection maintains wildland-urban interface building codes that classify composite assemblies by flame-spread index. Stakeholders must track evolving ASTM test protocols for surface temperature performance and fastener corrosion compatibility as product formulations diversify.
Market Dynamics
Residential outdoor living investment is accelerating material substitution away from pressure-treated lumber as homeowners prioritize low-maintenance durability and wildfire-resistant construction in high-risk zones.
Growth Catalysts
- California Title 24 Standards:Wildland-urban interface building codes mandate flame-spread index classifications for exterior assemblies, creating compliance-driven demand for certified composite systems.
- Pressure-Treated Lumber Disposal Costs:EPA regulations on treated wood waste classification tilt lifecycle economics toward recyclable alternatives with lower end-of-life liability.
- Sun Belt Climate Conditions:Cyclic wet-dry exposure and intense UV radiation in southern US states favor moisture-resistant decking formulations over traditional timber.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and PVC resin prices fluctuate with crude oil indices, compressing margin stability for extrusion-dependent manufacturers.
- Recycled Wood Fiber Supply Concentration:Reclaim streams cluster near urban demolition corridors and pallet manufacturing hubs, creating geographic supply asymmetries.
- Surface Temperature Performance:Dark-pigmented composite boards absorb solar radiation exceeding safe barefoot contact thresholds, limiting color palette options in high-insolation markets.
Strategic Opportunities
- Coastal Humidity Zones:Salt-air corrosion accelerates railing system replacement cycles in Florida and Gulf Coast municipalities, expanding addressable market for PVC-hybrid formulations.
- Design-Build Bundling:Professional installation channels capture margin pools through complete material packages spanning decking, railing, and integrated lighting systems.
- ASTM D7032 Evolution:Pending test protocol updates for fastener corrosion compatibility create first-mover advantage for manufacturers with pre-validated fastening systems.
Industry Challenges
- Skilled Installer Shortage:Proper gapping, thermal expansion accommodation, and hidden-fastener techniques require trained labor pools that lag demand growth in booming construction markets.
- ICC-ES Evaluation Timeline:Structural performance certification for novel board profiles spans 12-18 months, delaying product launches relative to formulation innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Decking and Railing Market |
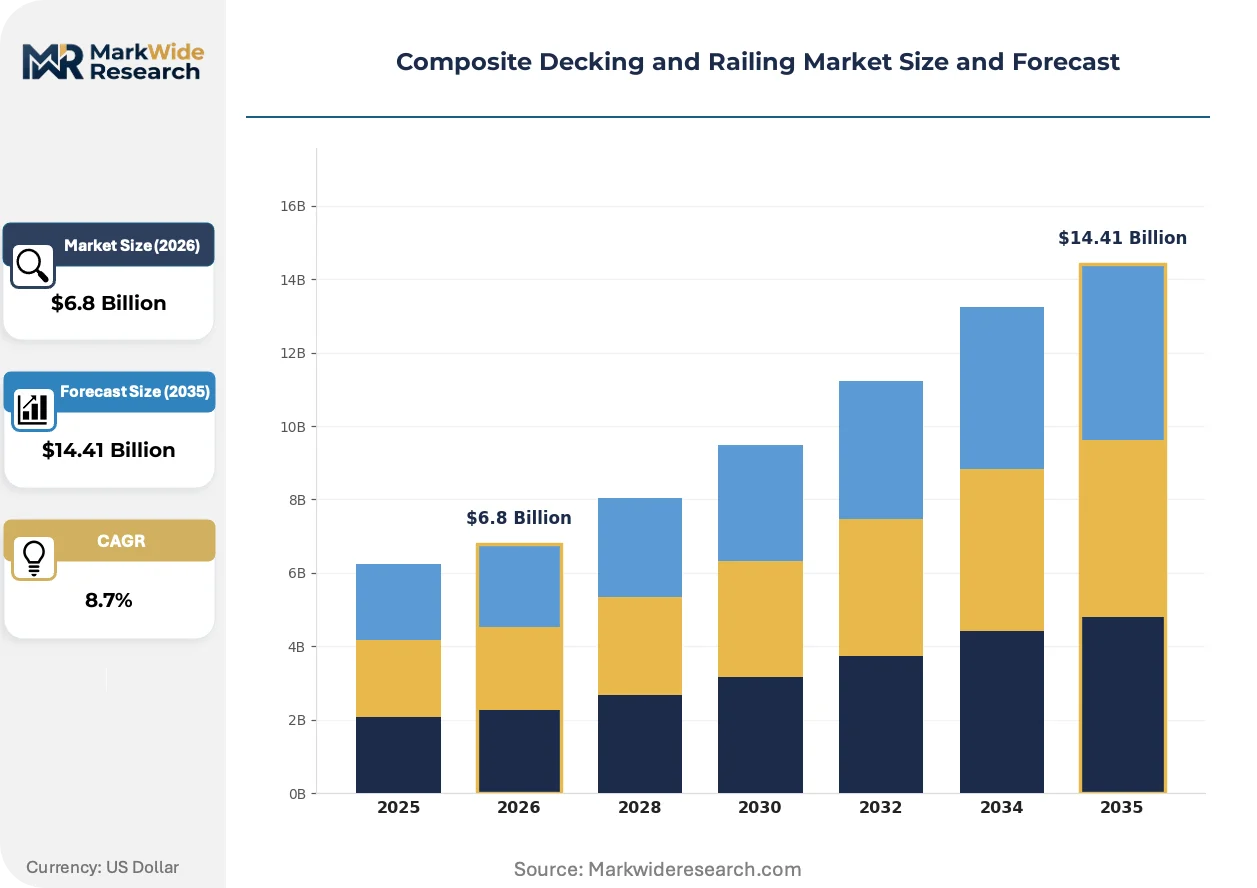
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Recycled Wood, PVC, Bamboo, Polypropylene End User: Residential, Commercial, Hospitality, Public Spaces Product Type: Decking Boards, Railing Systems, Accessories, Fasteners Installation Type: DIY, Professional, Prefabricated, Custom |
| Companies Covered | Azek, UPM Biocomposites, Trex Company, TAMKO Building Products, Advanced Environmental Recycling Technologies, Fiberon, Envision, Larson, TimberTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Decking and Railing Market Emerging Trajectories
Material science advances and code-driven performance mandates are fragmenting the competitive landscape between wood-plastic blends, mineral-composite thermoplastics, and fully synthetic cellular PVC systems.
Co-extruded capstock technology is fragmenting the premium segment by delivering tropical hardwood aesthetics with encapsulated moisture barriers. High-end residential builders in fire-prone California counties specify these products for WUI compliance without sacrificing visual warmth. The technology compresses price positioning between entry composites and genuine hardwood imports.
California's Department of Forestry and Fire Protection maintains escalating flame-spread index thresholds for wildland-urban interface construction. Manufacturers reformulate mineral loadings and combustion modifiers to achieve Class A or Class B ratings. Coastal municipalities lag interior jurisdictions in adoption, creating asynchronous regulatory pressure across the state.
Homeowner specification behavior now prioritizes bundled warranty coverage over initial material cost. Design-build contractors respond by sourcing complete systems from single manufacturers to align fade, stain, and structural guarantees. This pattern concentrates most visibly in Arizona and Nevada markets where extreme thermal cycling accelerates failure modes.
Composite Decking and Railing Market Segmentation
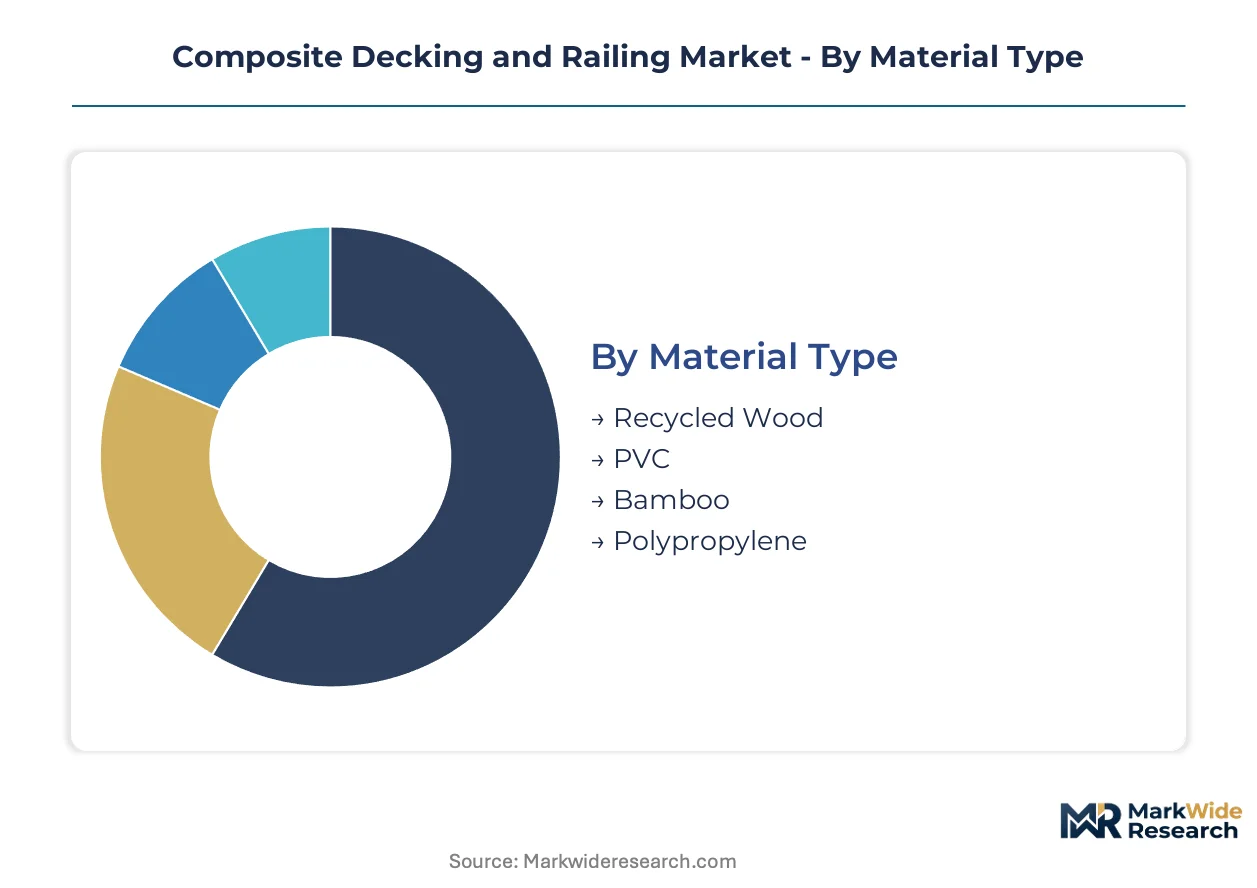
Material formulation and installation channel selection determine compliance pathways, warranty coverage, and lifecycle cost structures for composite decking procurement. Regulatory frameworks in fire-prone jurisdictions and coastal humidity zones create asymmetric demand concentration across segment combinations. Contractors and specifiers navigate these constraints through bundled product-category selections that align with local code enforcement intensity.
Material Type:
California's Department of Forestry and Fire Protection flame-spread index classifications and EPA pressure-treated lumber disposal regulations differentiate material viability across wildland-urban interface and standard construction zones.
- Recycled Wood:Wood-plastic blends incorporating reclaimed pallet and construction debris fiber dominate volume through established reclaim supply chains near urban demolition corridors. Sun Belt residential builders specify these formulations for cost-competitive replacement of pressure-treated lumber in jurisdictions without WUI mandates.
- PVC:Cellular polyvinyl chloride eliminates organic fiber content entirely, delivering Class A flame-spread ratings required by California Title 24 standards. Coastal Florida and Gulf Coast municipalities drive specification for salt-air corrosion resistance in railing applications.
- Bamboo:Rapid-renewable grass fiber composites appeal to sustainability-focused commercial developers pursuing LEED certification credits. Supply concentration limits scale in North American extrusion infrastructure.
- Polypropylene:Mineral-reinforced thermoplastic formulations achieve dimensional stability under extreme thermal cycling in Arizona and Nevada desert climates. Feedstock volatility ties margin stability to crude oil index movements.
Established volume favors recycled wood; emerging adoption favors PVC.
End User:
Project scale and liability exposure shape specification authority, with commercial developers prioritizing certified systems and residential homeowners emphasizing first-cost economics.
- Residential:Single-family outdoor living investment concentrates in design-build bundled contracts spanning decking, railing, and integrated lighting. Sun Belt states account for disproportionate share due to climate-driven maintenance avoidance.
- Commercial:Multi-family and mixed-use developers mandate ICC-ES evaluation reports and ASTM D7032 compliance for structural performance liability coverage. Warranty alignment across complete material packages dominates procurement criteria.
- Hospitality:Resort and hotel properties prioritize surface temperature performance and fade resistance under intense UV exposure. Dark-pigmented board limitations constrain color palette options in high-insolation markets.
- Public Spaces:Municipal park and boardwalk projects face extended ICC-ES certification timelines that delay product launches relative to private-sector innovation cycles. Federal procurement guidelines favor recyclable end-of-life alternatives.
Residential channels capture margin through bundling; commercial specifications are climbing the fastest.
Product Type:
Code-driven guardrail height and infill requirement tightening across jurisdictions accelerates railing system replacement cycles independent of decking board wear.
- Decking Boards:Co-extruded capstock technology delivers tropical hardwood aesthetics with encapsulated moisture barriers. California WUI compliance without visual warmth sacrifice commands premium positioning.
- Railing Systems:Guardrail assemblies represent the steepest expansion trajectory as building codes tighten height and infill standards. Salt-air corrosion in Florida accelerates replacement demand for PVC-hybrid formulations.
- Accessories:Integrated lighting, drainage, and fascia components complete design-build material packages. Single-manufacturer sourcing aligns fade, stain, and structural guarantees.
- Fasteners:Hidden-fastener and corrosion-compatible hardware pending ASTM protocol updates create first-mover advantage for pre-validated systems. Proper gapping and thermal expansion techniques require trained installer labor pools.
Decking boards anchor revenue scale; railing systems are gaining share fastest.
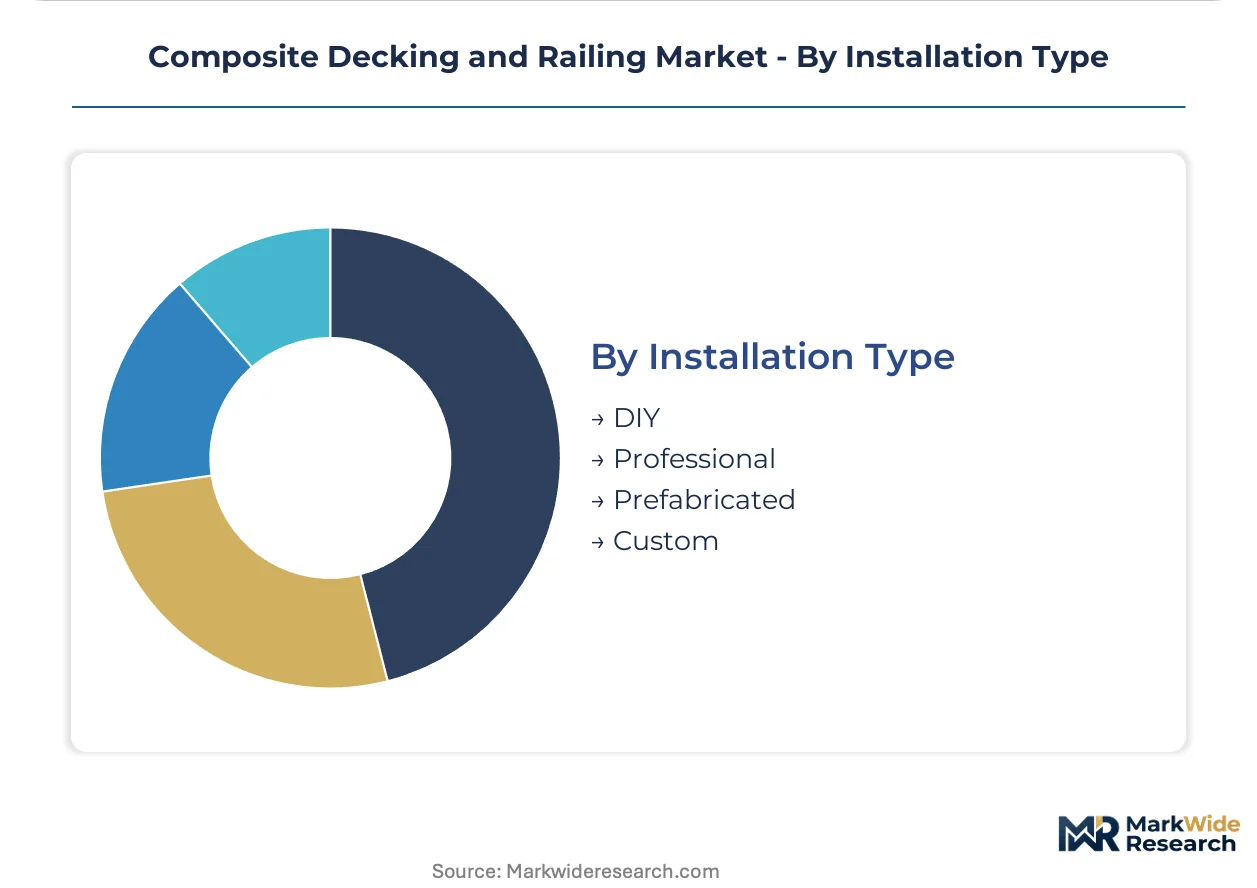
Installation Type:
Labor availability constraints and thermal expansion complexity fragment execution models between homeowner self-install and certified contractor channels.
- DIY:Big-box retail distribution serves maintenance-averse homeowners in standard construction zones without WUI complexity. Surface temperature performance limitations restrict dark-color sales in high-insolation regions.
- Professional:Design-build contractors capture margin pools through complete material packages and warranty alignment. Skilled installer shortages lag demand growth in booming construction markets.
- Prefabricated:Modular deck and balcony assemblies accelerate multi-family project timelines. ICC-ES evaluation reports govern structural performance certification for novel profile configurations.
- Custom:High-end residential builders in fire-prone California counties specify co-extruded premium systems for code compliance with aesthetic differentiation. Extended lead times accompany 12-18 month certification cycles.
Professional installation concentrates margin capture; prefabricated approaches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows concentrate from North American extrusion facilities toward Pacific Rim construction markets, while European recyclers supply Mediterranean coastal developments. Export volumes track regulatory divergence on flame-spread standards and wildfire-resistant construction mandates.
United States
Sun Belt residential construction drives material substitution away from pressure-treated lumber. California's Department of Forestry and Fire Protection enforces wildland-urban interface codes that classify composite assemblies by flame-spread index. Manufacturing clusters in Nevada and Virginia control feedstock costs through proprietary recycling infrastructure.
Germany
Commercial developers specify mineral-reinforced thermoplastics for multi-family outdoor spaces. ECHA REACH regulations govern chemical composition of wood-plastic blends entering European distribution. Industrial concentration in North Rhine-Westphalia serves Benelux export channels with certified structural profiles.
China
Rapid urbanization accelerates demand for low-maintenance exterior solutions in coastal humidity zones. GB standards for building materials establish performance benchmarks for moisture-resistant formulations. Yangtze River Delta manufacturing bases supply Southeast Asian hospitality developments with co-extruded capstock systems.
Australia
Intense UV exposure and salt-air corrosion drive specification for fade-resistant decking in Queensland resort construction. The country's national building code mandates guardrail height compliance that expands railing system replacement cycles. Melbourne and Sydney distribution hubs coordinate Pacific Island project logistics.
Canada
Pressure-treated lumber disposal costs under federal environmental guidelines tilt lifecycle economics toward recyclable alternatives. Ontario and British Columbia builders prioritize moisture-resistant formulations for cyclic freeze-thaw exposure. Quebec extruders supply northeastern US markets through established cross-border channels.
Composite Decking and Railing Market Vendor Landscape
Concentration sits with integrated manufacturers possessing captive recycling infrastructure and proprietary formulation patents. The competitive terrain splits between wood-plastic blend specialists, cellular PVC pure-plays, and mineral-composite thermoplastic innovators. Strategic moves center on backward integration into reclaimed fiber supply chains and co-extrusion technology licensing arrangements.
Among North American building materials specialists, Azek, Trex Company, and Fiberon exemplify distinct formulation archetypes. Azek occupies a position within the fully synthetic cellular PVC segment. Trex Company anchors the recycled wood-plastic blend category through vertically integrated reclaim operations. Fiberon represents the PVC-wood hybrid specialization targeting coastal humidity applications.
| Leading Market Players |
|---|
| Azek |
| UPM Biocomposites |
| Trex Company |
| TAMKO Building Products |
| Advanced Environmental Recycling Technologies |
| Fiberon |
| Envision |
| Larson |
| TimberTech |
| Others |
Supply Flow & Price Mechanics
California's Department of Forestry and Fire Protection flame-spread index classifications gate both supply qualification and price differentiation simultaneously, as manufacturers must achieve Class A or Class B ratings to access WUI-compliant construction zones while premium capstock formulations command positioning above entry-level wood-plastic blends.
Pricing Analysis
Professional installation contractors anchor a three-tier pricing structure across premium, standard, and economy levels, with co-extruded capstock systems commanding spreads over bare recycled wood composites due to encapsulated moisture barriers and fade warranties. Price differentiation hinges on certification tier and geographic delivery cost, with California WUI-compliant products carrying premiums over standard construction zone alternatives. Cost compression in the economy tier is intensifying because reclaimed wood fiber supply concentrates near urban demolition corridors. Homeowner DIY segments exhibit highest price sensitivity, while commercial developers pursuing ICC-ES evaluation reports show lowest sensitivity.
Supply Chain Analysis
The United States and China anchor North American and Asia-Pacific extrusion capacity respectively, with Nevada and Virginia manufacturing clusters serving Sun Belt demand while Yangtze River Delta bases supply Southeast Asian hospitality developments. Feedstock draws from polypropylene resin, reclaimed pallet fiber, and mineral reinforcement additives. Single-source vulnerability concentrates in recycled wood fiber reclaim streams clustered near pallet manufacturing hubs. Distribution runs through professional contractor channels and big-box retail networks serving diverging installation archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Material science fragmentation between wood-plastic blends, cellular PVC, and mineral-composite thermoplastics creates niche specialization opportunities as code-driven performance mandates multiply certification pathways.
For Market Incumbents: Secure captive supply of reclaimed wood fiber through backward integration into urban demolition corridor reclaim operations, insulating margin stability from geographic supply asymmetries. Expand co-extrusion technology licensing arrangements to capture royalty streams from formulation differentiation without capacity overextension. Trex Company's proprietary recycling infrastructure exemplifies this defensive posture against petrochemical feedstock volatility.
For New Entrants and Emerging Players: Anchor in coastal humidity zone railing replacement cycles, where salt-air corrosion accelerates PVC-hybrid specification in Florida and Gulf Coast municipalities underserved by incumbent distribution density. Target prefabricated modular deck assemblies for multi-family developers facing skilled installer shortages and compressed project timelines. Pursue ASTM D7032 pre-validation partnerships with fastener manufacturers to exploit pending protocol updates.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed building materials platforms possessing ICC-ES evaluation report portfolios but lacking co-extrusion capstock capabilities. The five-to-ten year viability window favors targets with demonstrated WUI compliance traction in California counties and established professional contractor channel relationships. Watch ICC-ES certification timeline compression as an inflection signal for product launch velocity relative to formulation innovation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reclaim Operations | Captive wood fiber supply insulates Trex Company from geographic reclaim asymmetries near demolition corridors. |
| Co-Extrusion Technology Licensing | Patent licensing to regional extruders expands premium capstock penetration without capital-intensive capacity builds. |
| ASTM D7032 Pre-Validation Partnerships | Fastener manufacturer alliances create first-mover positioning ahead of pending corrosion compatibility protocol updates. |
| Prefabricated Modular Assembly Development | Modular deck systems address skilled installer shortages compressing multi-family project timelines in booming construction markets. |
| California WUI Compliance Certification | Class A flame-spread rating unlocks premium positioning in wildland-urban interface construction zones governed by Title 24 standards. |
Methodological Framework
A spread of perspectives from composite decking plant managers, professional contractor procurement leads, building code enforcement officials, and big-box retail category buyers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through ICC-ES evaluation report databases, EPA treated wood disposal regulation filings, ASTM test protocol documentation, and California Department of Forestry and Fire Protection code enforcement records. Bottom-up volume builds across material type, end user, product category, and installation channel segments triangulated against top-down macroeconomic drivers.
Segmentation dimensions modeled include material formulation archetype, project scale and liability exposure, product system component, and execution model complexity across the projection horizon. CAGRs were derived from regression analysis of historical substitution patterns against regulatory mandate adoption curves and residential construction permit flows. Industry-specific forecast inputs incorporated wildland-urban interface code expansion timelines and petrochemical feedstock price elasticity assumptions.
Material uncertainties — including ICC-ES certification timeline delays, reclaimed wood fiber supply disruptions, and petrochemical price volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory adoption velocity and contractor channel expansion capacity. Recalibration cycles align with material shifts in California Title 24 enforcement intensity and ASTM D7032 protocol finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
Cement Tiles Market
Building Materials
China Cement Market
Building Materials
Building and Construction Plastics Market
Building Materials
Building and Construction Sheets Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Earthen Plasters Market
Building Materials
East Africa Wall Putty Market
Building Materials
US Cement Tiles Market
Building Materials
Cellular Concrete Market
Building Materials
Industrial Concrete Flooring Market