
 Vertical Garden Construction Market | 2026-2036
Vertical Garden Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Garden Construction Market Intelligence
Demand from large-scale public parks is decoupling from the high-margin commercial spaces segment, where aesthetic and branding value justify premium investments. This shift favors specialized installers over general contractors. Biotecture Limited leverages its proprietary hydroponic systems for bespoke corporate headquarters. Sempergreen BV specializes in large-scale, prefabricated modular panels for faster project completion. Elmich Pte Ltd positions its solutions for tropical climates with a focus on durability.
Vertical garden construction involves the design and installation of living walls or green facades on building exteriors or interior surfaces. These systems integrate a growing medium, structural support, and often automated irrigation and fertigation. Their primary purpose is to improve building aesthetics, provide thermal insulation, and enhance urban biodiversity. Modular panels dominate the product landscape due to installation speed, while felt systems offer flexibility for complex designs in residential and hospitality venues.
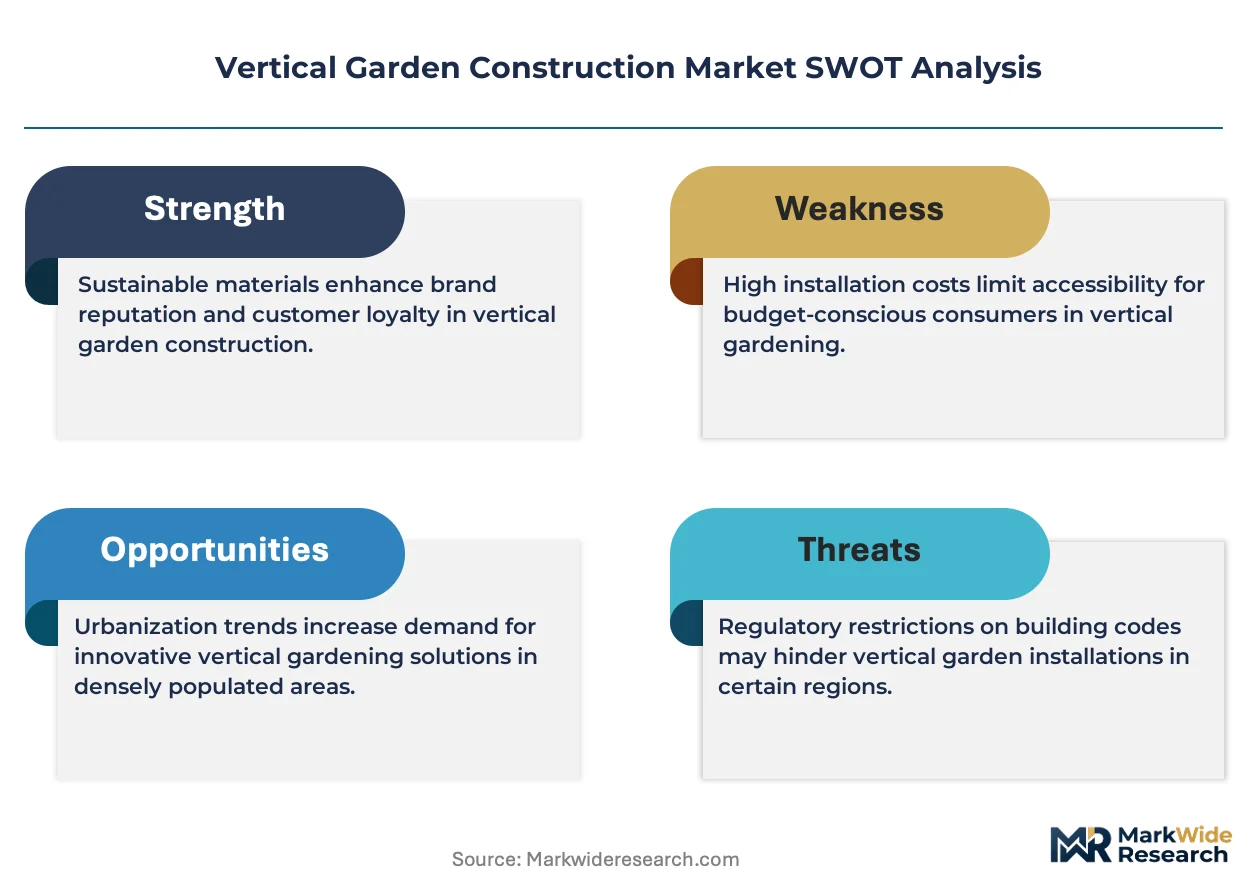
Regulatory frameworks like the EU Green Deal and building codes in cities like Singapore directly mandate or incentivize green wall installations. In the United States, LEED certification standards award points for vegetated surfaces, influencing architectural specifications. These policies are critical for creating market demand beyond private-sector aesthetic choices. The central challenge for end users remains navigating the trade-off between upfront installation costs and long-term operational savings on energy and water.
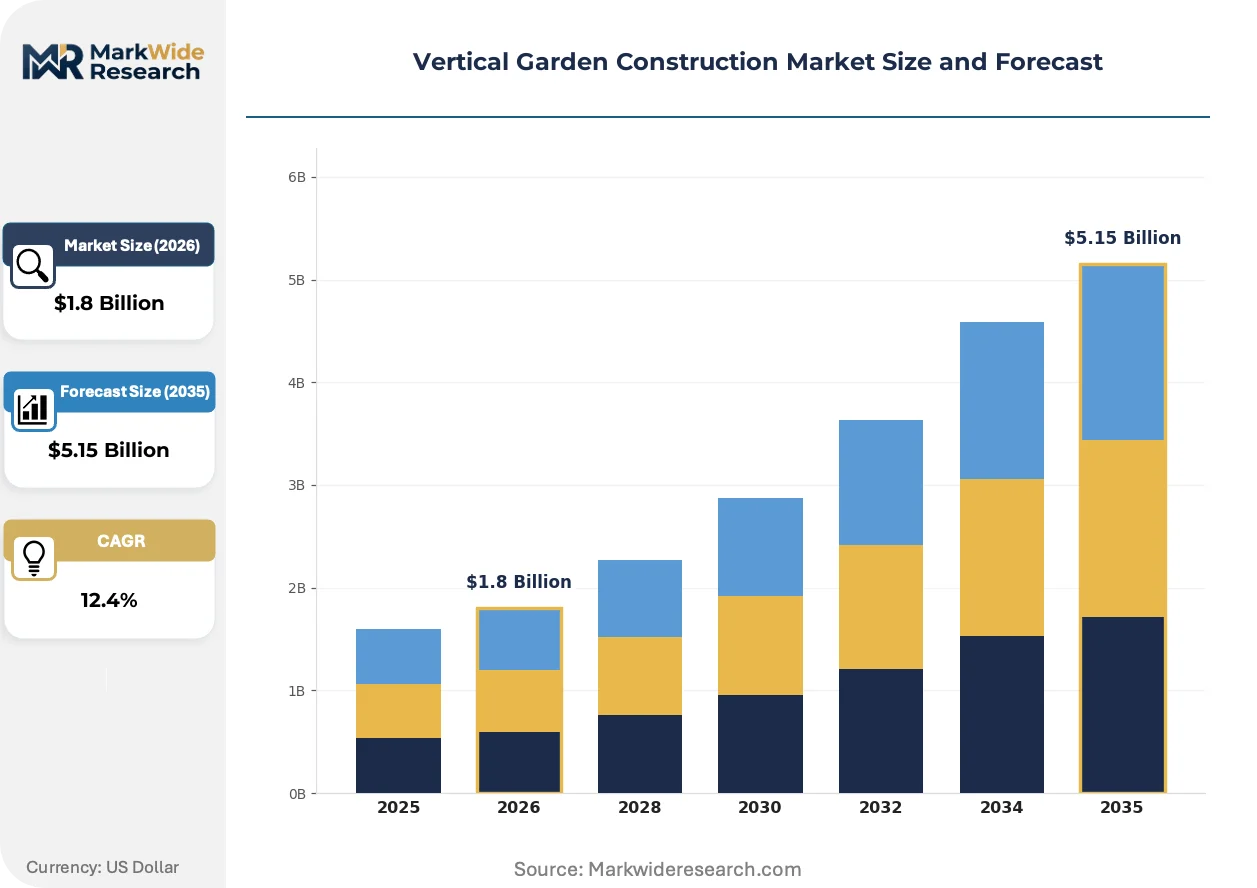
Market Dynamics
The proliferation of green building certification standards is the central force shaping the vertical garden construction market. Frameworks like LEED and BREEAM are standardizing project requirements, shifting green walls from purely aesthetic additions to quantifiable assets for sustainability and energy performance.
Growth Catalysts
- Regulatory Mandates:Policies like the EU Green Deal and specific urban greening ordinances in cities such as Singapore are compelling developers to integrate vegetated surfaces into new commercial and residential buildings to meet environmental targets.
- Corporate Sustainability Goals:Demand from the corporate sector is strong, with companies in commercial real estate using living walls to enhance brand image, improve employee well-being, and achieve sustainability objectives outlined in ESG reports.
- Installation Efficiency:The development of prefabricated modular panels allows for significantly faster and more predictable installation compared to older felt-based systems, reducing on-site labor costs and project timelines for large-scale commercial projects.
Market Restraints
- High Initial Capital Outlay:The significant upfront investment for structural supports, irrigation systems, and specialized installation remains a primary barrier for many potential clients, particularly in the residential and small commercial segments.
- Maintenance Complexity:Long-term system viability requires specialized horticultural and technical knowledge for managing automated irrigation, fertigation, and pest control, creating a high total cost of ownership and dependency on service contracts.
- Competition from Alternatives:Lower-cost aesthetic solutions, including traditional container gardening, artificial green walls, and large-scale murals, present a substitution threat by offering visual greening without the associated cost and maintenance complexity.
Strategic Opportunities
- Retrofitting Existing Buildings:A substantial opportunity exists in retrofitting older building stock in dense urban cores across North America and Europe, where vertical gardens can improve thermal insulation and modernize aesthetics.
- Smart System Integration:Integrating living wall systems with IoT sensors and building management platforms allows for data-driven, automated control of water, light, and nutrients, optimizing plant health and resource efficiency.
- Water Scarcity Mandates:In arid regions like the Middle East and the Southwestern United States, regulations promoting water conservation create demand for highly efficient, closed-loop hydroponic vertical gardens that minimize water consumption.
Industry Challenges
- Specialized Labor Shortage:The industry faces a scarcity of technicians who possess the hybrid skillset of horticulture, plumbing, and electrical systems integration necessary for the installation and long-term maintenance of complex living wall systems.
- Performance Standardization Gaps:A lack of universally accepted standards for measuring and verifying the thermal performance, air quality improvement, and biodiversity benefits of vertical gardens makes it difficult for end-users to justify investment based on ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Garden Construction Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Panels, Felt Systems, Hydroponic Structures, Trellis Frames, Prefabricated Walls Application: Commercial Spaces, Residential Complexes, Urban Farming, Hospitality Venues, Public Parks Installation Method: Indoor Mounting, Outdoor Fixed, Portable Units, Self-Supporting, Suspended End User: Architects, Landscaping Firms, Facility Managers, Event Planners, Interior Designers |
| Companies Covered | LiveWall, LLC, Biotecture Limited, Sempergreen BV, ANS Group Global Ltd, Atlantis Corporation Australia Pty Ltd, Elmich Pte Ltd, Fytogreen Australia, PAISAJISMO URBANO, ZTC International Landscape Solutions (P) Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Garden Construction Market Strategic Shifts & Innovations
The market's evolution is marked by a transition of vertical gardens from static architectural elements to dynamic, integrated building systems. This shift is driven by advancements in materials science, automation, and a more sophisticated understanding of their ecological and economic benefits.
Prefabricated living wall panels that embed irrigation lines, growing media, and sensor housings are gaining significant traction. Commercial developers and public infrastructure projects are the primary adopters, valuing the speed and quality control offered by factory-built components. This technology is modularizing the entire installation workflow, compressing project schedules and reducing dependency on specialized on-site labor.
Urban greening policies are becoming more prescriptive, directly influencing design specifications. For example, Singapore's LUSH program mandates specific green plot ratios, making features like green walls a condition for development approval. This regulatory pressure transforms vertical gardens from an optional feature into a required building component for architects and developers operating in high-density cities.
Client purchasing models are evolving from one-off installation projects toward long-term service agreements that guarantee system performance and plant vitality. This trend disrupts the traditional role of general contractors, favoring specialized firms that can provide ongoing maintenance, monitoring, and plant replacement. The model is most pronounced in the premium hospitality and corporate headquarters segments, where aesthetic upkeep is critical.
Vertical Garden Construction Market Segmentation
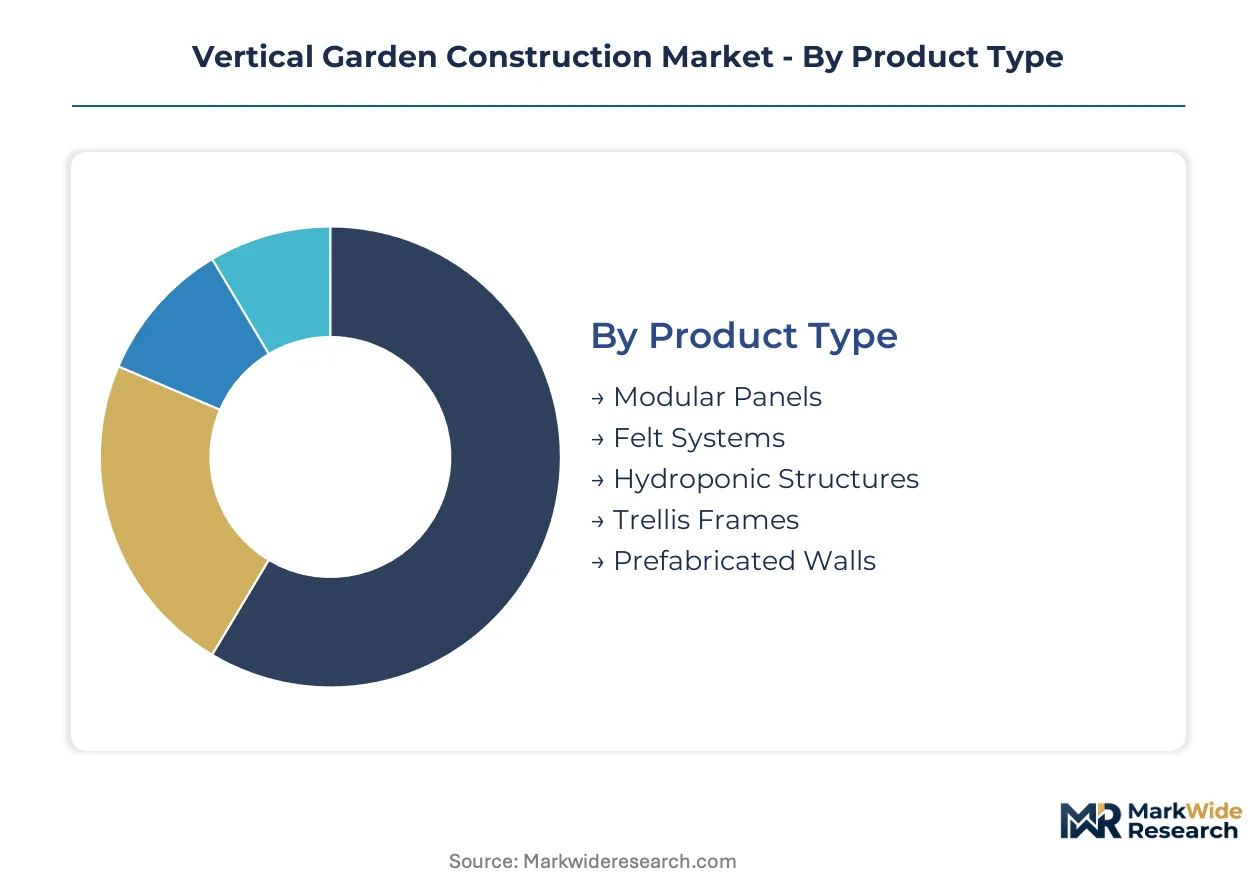
The vertical garden construction market segmentation provides a granular understanding of demand drivers and technological preferences across distinct categories. This analysis highlights how various product types, applications, installation methods, and end-user profiles influence market dynamics and investment priorities.
Product Type:
Product type segmentation highlights how different vertical garden systems integrate into building designs, ranging from fully embedded solutions to more modular, standalone applications.
- Modular Panels:These prefabricated units integrate growing media, irrigation, and structural support, offering rapid installation and scalability for large commercial projects. Commercial developers in dense urban centers like Singapore favor modular panels for their efficiency.
- Hydroponic Structures:These advanced systems circulate nutrient-rich water directly to plant roots, minimizing water use and enabling precise control over growing conditions. Demand for hydroponic structures is high in arid regions and for urban farming initiatives.
- Felt Systems:Flexible felt pockets or mats attach to vertical surfaces, allowing for diverse plant arrangements and complex designs, particularly in residential and hospitality venues.
- Trellis Frames:Structural frameworks support climbing plants, providing a natural green facade that can adapt to various architectural styles and offer shading benefits.
- Prefabricated Walls:Factory-assembled wall sections with integrated vegetation offer consistent quality and accelerated on-site deployment for large-scale infrastructure projects.
Volume placements concentrate in Modular Panels; the faster expansion belongs to Hydroponic Structures.
Application:
Application analysis differentiates market demand across various end-use environments, each with distinct budget considerations and aesthetic requirements.
- Commercial Spaces:Living walls enhance corporate headquarters, retail environments, and office buildings, aligning with corporate sustainability goals and improving brand image. Property developers use vertical gardens as a quantifiable asset for LEED certification.
- Hospitality Venues:Hotels, restaurants, and resorts deploy vertical gardens to create unique aesthetic experiences, attract clientele, and provide a premium, biophilic atmosphere. These installations require high aesthetic upkeep.
- Residential Complexes:Vertical gardens in multi-family dwellings and private homes improve aesthetics, provide privacy, and offer limited space for urban gardening.
- Urban Farming:Vertical systems support food production in dense urban areas, contributing to local food security and reducing transportation costs for fresh produce.
- Public Parks:Government initiatives integrate vertical gardens into public spaces, improving urban biodiversity and providing green infrastructure in densely populated cities.
Commercial Spaces represent the largest revenue stream; Urban Farming is climbing the fastest.
Installation Method:
Installation method segmentation reflects the deployment scale and structural integration required for different vertical garden projects, influencing project logistics.
- Indoor Mounting:Systems attached to interior walls improve indoor air quality, enhance aesthetics, and contribute to employee well-being in corporate environments. These installations often feature automated irrigation.
- Outdoor Fixed:Permanently affixed to building exteriors, these large-scale installations provide thermal insulation, reduce urban heat island effects, and enhance architectural appeal. Outdoor fixed systems require robust structural support.
- Portable Units:Freestanding or movable vertical gardens offer flexibility for temporary events, office reconfigurations, or residential patios, without permanent structural alterations.
- Self-Supporting:Independent structures that do not rely on building facades for primary support, suitable for large public installations or as standalone landscape features.
- Suspended:Systems hung from ceilings or overhead structures create dramatic visual effects, often seen in atriums, shopping malls, and large hospitality spaces.
Outdoor Fixed installations dominate project volume; Portable Units are gaining share fastest for flexible applications.
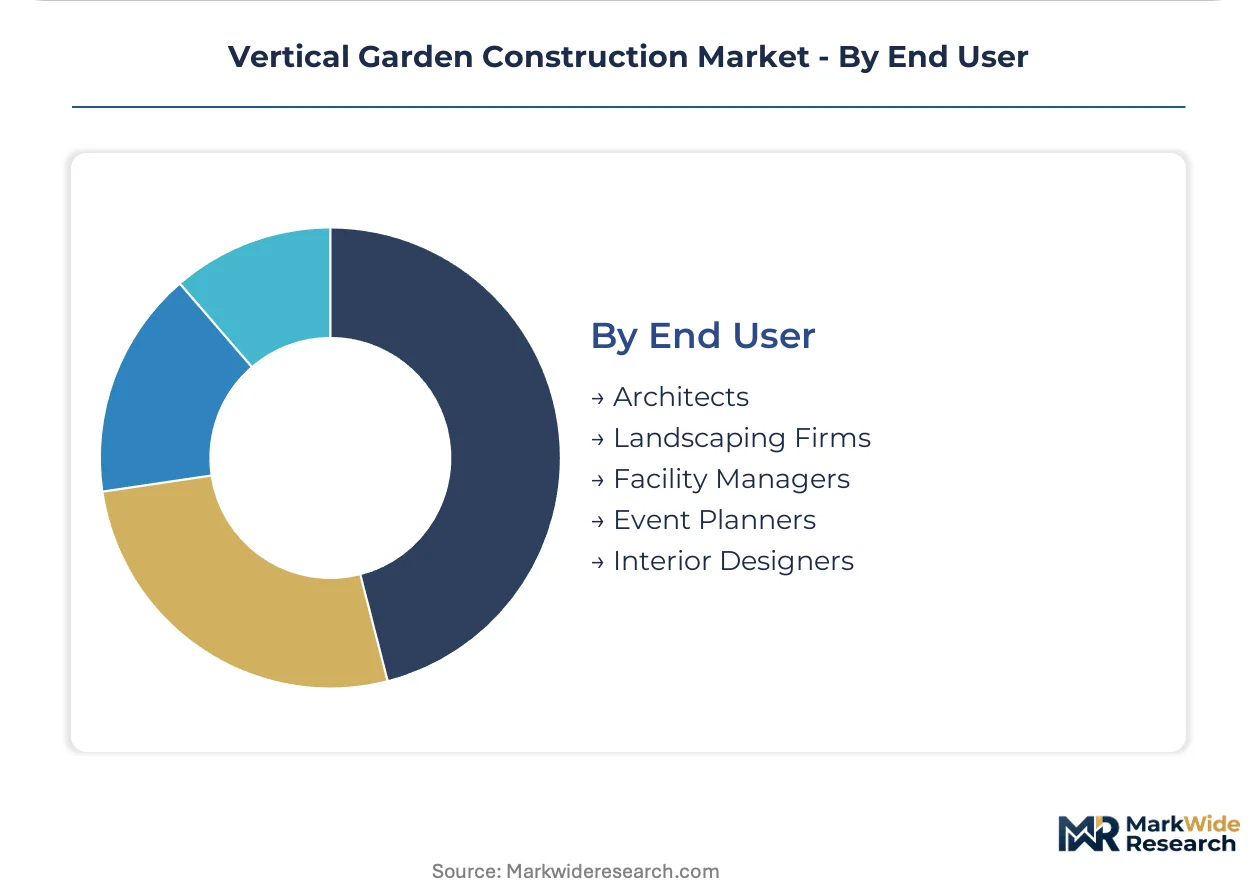
End User:
End user segmentation identifies the primary decision-makers and influencers within the vertical garden construction value chain, each with specific procurement needs.
- Architects:These professionals integrate vertical gardens into initial building designs, specifying systems that meet aesthetic, structural, and green building certification requirements. Architects influence product selection based on performance.
- Landscaping Firms:Specialized landscaping companies handle the installation, horticultural design, and ongoing maintenance of living wall systems, leveraging their plant expertise. They often partner with architects and developers.
- Facility Managers:Responsible for building operations and maintenance, facility managers oversee the long-term viability and performance of installed vertical gardens, including irrigation and plant health.
- Event Planners:These professionals utilize portable or temporary vertical garden installations to enhance the aesthetics of conferences, exhibitions, and corporate events.
- Interior Designers:Interior designers incorporate smaller, aesthetically focused vertical gardens into indoor spaces to improve ambiance and introduce natural elements.
Architects drive initial design specifications; Facility Managers show the steepest expansion trajectory for long-term operational contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's LUSH program, mandating specific green plot ratios, drives significant concentration of vertical garden construction projects within the city-state. This regulatory push transforms vertical gardens from optional features into required building components for developers. Similar government initiatives in other dense urban centers globally also spur market activity.
Singapore
Urban density and a strong emphasis on biophilic design fuel demand for vertical gardens in Singapore. The LUSH program directly mandates green plot ratios, making such installations a condition for development approval. The Marina Bay area sees extensive green facade integration, enhancing architectural appeal and environmental performance for commercial and residential towers.
United Arab Emirates
Mitigating extreme climates and promoting water conservation are key demand drivers in the United Arab Emirates. Local municipal building codes increasingly encourage green infrastructure to improve urban environments. Dubai's Expo City and other master-planned communities integrate large-scale vertical gardens into their designs, often employing advanced hydroponic systems.
Germany
Germany's focus on energy efficiency and urban biodiversity generates substantial demand for vertical garden solutions. The EU Green Deal and national building codes incentivize green wall installations for their thermal insulation properties. Berlin and Frankfurt feature numerous corporate headquarters incorporating living walls to meet stringent sustainability targets and enhance employee well-being.
United States
Corporate sustainability goals and the extensive need for building retrofits drive demand in the United States. LEED certification standards award valuable points for vegetated surfaces, strongly influencing architectural specifications. New York City and San Francisco exhibit high demand for both interior and exterior green walls in commercial real estate developments and luxury residential projects.
China
Addressing urban pollution and managing rapid urbanization are primary factors boosting vertical garden construction in China. The nation's dual carbon goals and local green building policies push for integrated vegetated surfaces. Shanghai and Shenzhen actively implement vertical greening projects in new urban developments and public infrastructure, aiming for greener cityscapes.
Vertical Garden Construction Market Key Industry Players
Top-tier vendors anchor the specialized vertical garden construction market, while a broader base of regional firms serves localized demand. The market structure is tiered, with premium players focusing on bespoke corporate and hospitality projects. Specialized installers, modular panel fabricators, and integrated system providers represent key strategic archetypes. Companies pursue strategic partnerships for broader project delivery and invest in smart system integration to differentiate offerings.
Specialists in advanced vertical garden solutions include Biotecture Limited, a UK-based firm known for its proprietary hydroponic systems in corporate headquarters. Sempergreen BV, a Netherlands-based company, anchors the prefabricated modular panel segment with solutions for faster project completion. Elmich Pte Ltd, a Singaporean entity, positions its solutions for tropical climates, emphasizing durability and system longevity. These firms exemplify the market's shift towards specialized offerings and integrated service models, moving beyond general contracting in high-margin segments.
| Leading Market Players |
|---|
| LiveWall, LLC |
| Biotecture Limited |
| Sempergreen BV |
| ANS Group Global Ltd |
| Atlantis Corporation Australia Pty Ltd |
| Elmich Pte Ltd |
| Fytogreen Australia |
| PAISAJISMO URBANO |
| ZTC International Landscape Solutions (P) Ltd |
Cost & Logistics Intelligence
Specialized labor costs for horticultural and technical expertise significantly influence installation project quotes and the long-term pricing of maintenance service agreements. This cost component directly impacts profitability across all vertical garden segments.
Pricing Analysis
Short project lead times command premium pricing for vertical garden installations, especially for commercial developers needing rapid deployment. The dominant pricing model is project-based for initial installation, shifting to long-term service agreements for ongoing maintenance. Price differentiation stems from customization requirements, the complexity of automated systems, and bundled after-sales service contracts. Pricing softness reflects competition from lower-cost aesthetic solutions like artificial green walls and traditional landscaping. Residential and small commercial segments exhibit the highest price sensitivity, while premium hospitality and corporate headquarters prioritize aesthetic value over upfront cost.
Supply Chain Analysis
Dual-sourcing requirements are emerging for critical components like modular panels, driven by large commercial projects to mitigate single-supplier risk. Supply of prefabricated modular panels concentrates in China, while specialized hydroponic systems often originate from the Netherlands and Germany. Elmich Pte Ltd sources components for tropical climates from Southeast Asia. The industry depends on consistent supplies of growing media, automated irrigation components, and lightweight structural supports. Commodity price volatility for plastics and metals used in structural frames poses a structural risk. Distribution runs primarily through specialized installers and direct partnerships with large property developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vertical garden construction market is poised for consolidation, as escalating maintenance complexity forces out general contractors lacking specialized horticultural and technical expertise. This market shift favors integrated solution providers.
For Market Incumbents: Deepen proprietary hydroponic system R&D to maintain a technological edge against emerging modular panel fabricators. Secure long-term service contracts with corporate clients to ensure recurring revenue streams and increase client stickiness. Invest in certified training programs for specialized labor to address the industry's critical skill shortage. The threat of lower-cost alternative greening solutions demands continuous innovation in performance metrics.
For New Entrants and Emerging Players: Launch via strategic partnerships with architectural firms specializing in retrofitting existing urban buildings in North America. Target underpenetrated segments like public parks and urban farming initiatives with cost-effective, easily scalable modular solutions. The residential complexes segment offers a penetrable entry point for portable or smaller felt systems due to lower upfront investment. Offer bundled installation and simplified maintenance packages to overcome initial capital outlay and complexity barriers for smaller clients.
For Investors and Strategic Acquirers: The proliferation of new green building mandates in major urban centers is the leading indicator that vertical garden installations will shift from optional features to essential building components. This market exhibits strong long-term viability over a 5-10 year window, driven by sustained urban greening and corporate sustainability agendas. Acquire specialized firms with proprietary smart irrigation and fertigation technologies or strong regional market share in arid climates. Watch for increased M&A activity among modular panel manufacturers as a sign of market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Innovation in Hydroponic Systems | Enhances water efficiency and nutrient delivery, appealing to arid regions and urban farming initiatives. |
| Strategic Partnerships with Architectural Firms | Secures early integration into large-scale commercial and public infrastructure projects. |
| Expansion of After-Sales Service Contracts | Ensures long-term revenue stability and manages complex maintenance needs for clients. |
| Investment in Specialized Labor Training | Addresses the critical shortage of hybrid horticultural and technical skills for system upkeep. |
| Geographic Expansion into Retrofit Markets | Captures significant opportunity in modernizing older building stock in North American and European cities. |
Research Approach
Independent corroboration across green building certification bodies, urban planning departments, and horticultural research institutes underwrites the qualitative findings. Primary interviews included property developers, specialized vertical garden installers, landscape architects, and facility managers. Secondary validation drew from government reports on urban greening, corporate ESG disclosures, and industry association publications. A bottom-up approach to market sizing was triangulated with top-down validation from macro-economic indicators.
Rate-of-change decomposition analyzes growth drivers and restraints across the analysis window. Segmentation dimensions modeled include product type, application, installation method, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data trends and projected market shifts. Key forecast inputs include urban density growth and green building certification uptake rates.
The model assumes a particular technology adoption path for smart irrigation systems; alternative pathways for advanced sensor integration would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and economic growth in key urban centers. Deviation in global raw material supply chains would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Modular and Portable Building Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
El Salvador Construction Market
Building Construction
Europe Prefab Wood Buildings Market
Building Construction
North America Modular Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
Latin America Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
China Modular Construction Market
Building Construction
North America Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Japan Construction Market
Building Construction
Honduras Construction Market