
 Global Builders Joinery and Carpentry of Wood Market | 2026-2036
Global Builders Joinery and Carpentry of Wood Market Size, Share, and Industry Trends Forecast 2026-2036
Global Builders Joinery and Carpentry of Wood Market Foresight
Modular window-and-door bundling is hardening as the dominant procurement format across large-scale residential developments. ASSA ABLOY leverages its hardware integration capabilities to control specification channels for bundled joinery systems. Masonite International anchors North American supply through specialized interior door platforms. Pella Corporation differentiates via advanced glazing-wood frame combinations for high-performance envelopes.
Builders joinery and carpentry of wood encompasses the fabrication and installation of structural and non-structural wooden components including doors, windows, stair assemblies, and custom mouldings, typically employing kiln-dried hardwoods or engineered timber laminates with moisture content below 19 percent to ensure dimensional stability in variable climates. Its primary purpose is to provide weather-resistant building envelopes, interior spatial division, and aesthetic finish carpentry within residential, commercial, and institutional construction. Doors and windows occupy the largest product category by installed value, though cabinets and custom mouldings capture disproportionate margin pools from renovation-driven demand. Residential housing leads application volume, while commercial complexes represent the fastest-growing segment as biophilic design principles expand specification of exposed timber interiors.
EPA regulations on formaldehyde emissions from composite wood products shape material sourcing decisions for US manufacturers, while the EU Green Deal's embodied-carbon thresholds are redirecting specification toward certified sustainable timber across European construction markets. China's GB standards for wooden building components enforce fire-resistance ratings that determine market access for imported joinery products. Stakeholders must monitor how tightening lifecycle-assessment requirements in multiple jurisdictions will reshape supplier qualification criteria and material certification burdens.
Market Dynamics
EU Green Deal embodied-carbon thresholds are compressing specification timelines for timber joinery across European construction markets, forcing manufacturers to requalify material sourcing and accelerate certified supply chain documentation.
Growth Catalysts
- Prefabricated timber construction:China's tier-one cities are scaling factory-built timber systems for mid-rise residential towers, compressing on-site installation cycles and reducing labor dependency.
- EU Green Deal carbon rules:Tightening lifecycle-assessment thresholds for building materials are redirecting specification toward FSC-certified timber and engineered wood products with verified low embodied carbon.
- Biophilic design mandates:Commercial office and hospitality developers are specifying exposed timber interiors to meet wellness certification standards, expanding demand for premium architectural millwork.
Market Restraints
- Adhesive cost volatility:Formaldehyde-based resins and polyurethane binders face feedstock price swings tied to petrochemical markets, compressing margins on engineered wood joinery.
- Import certification friction:China's GB standards for fire-resistance ratings create non-tariff barriers for European and North American joinery manufacturers seeking market access.
- Steel and aluminum substitution:High-performance metal window and door systems compete for commercial envelope specifications where thermal performance requirements exceed timber capabilities.
Strategic Opportunities
- Modular window-door bundling:Large-scale residential developers in Germany and the Netherlands are consolidating procurement into packaged envelope systems, creating specification control points for integrated suppliers.
- Cross-laminated timber convergence:Integration of CLT structural panels with prefabricated joinery components is enabling whole-building timber solutions for multi-story construction.
- Renovation-driven custom millwork:Aging housing stock in Japan and South Korea is generating replacement demand for bespoke interior doors, stair assemblies, and decorative mouldings.
Industry Challenges
- Skilled carpenter scarcity:Traditional joinery craftsmanship is declining across European apprenticeship pipelines, forcing manufacturers to automate fabrication or accept quality variability.
- Multi-jurisdiction certification burden:Manufacturers exporting to US, EU, and Chinese markets simultaneously face conflicting formaldehyde emission standards, fire-rating tests, and chain-of-custody documentation requirements.
- Moisture management complexity:Kiln-dried timber specifications vary by climate zone, creating inventory segmentation challenges for global suppliers serving humid subtropical and arid continental markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Builders Joinery and Carpentry of Wood Market |
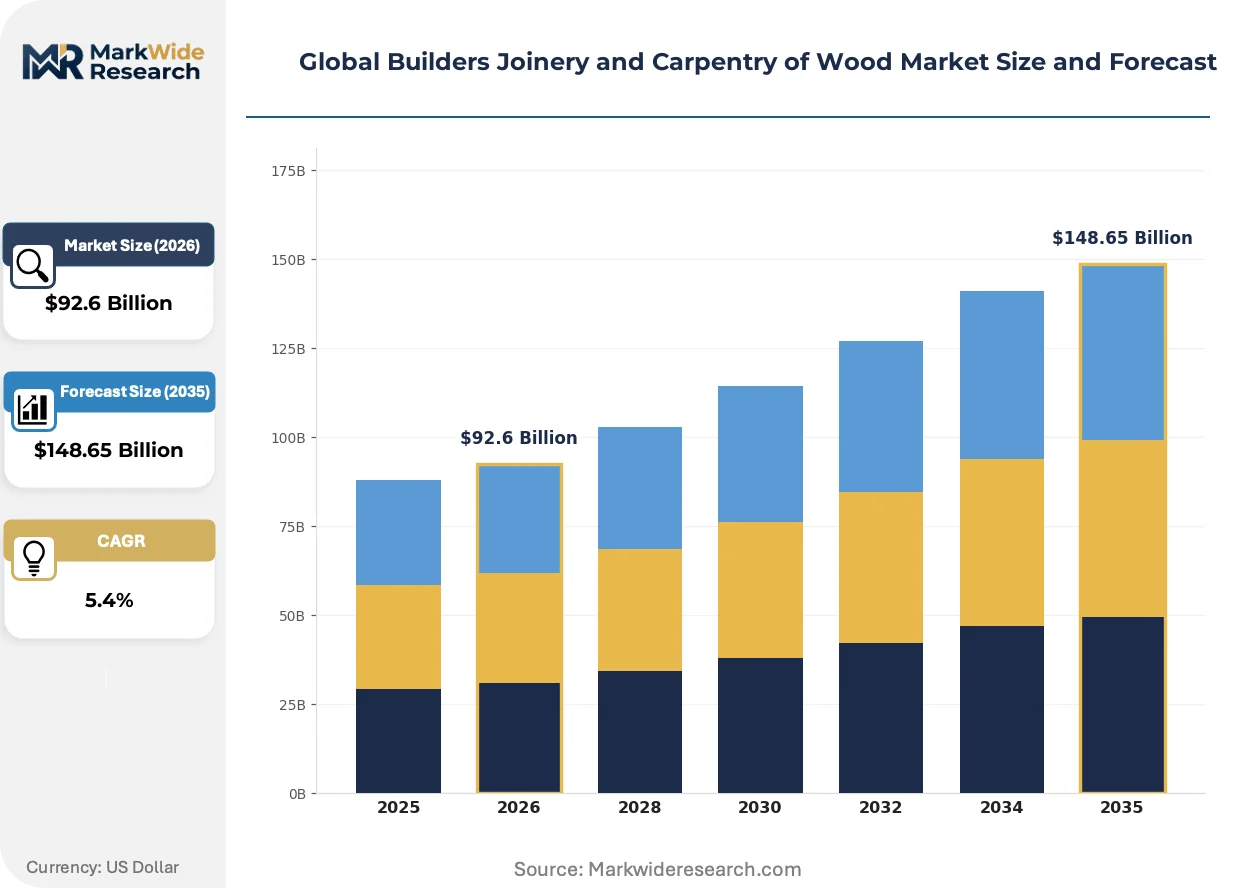
| Market Size in 2026 | $92.6 Billion |
| Market Size in 2035 | $148.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Doors, Windows, Frames, Stairs, Cabinets, Mouldings Material: Oak, Pine, Cedar, Birch, Walnut, Maple Application: Residential Housing, Commercial Complexes, Institutional Buildings, Public Infrastructure End User: Construction Contractors, Interior Designers, Property Developers, Renovation Service Providers |
| Companies Covered | ASSA ABLOY, VELUX Group, Masonite International, YKK AP Inc, VKR Holding, JELD-WEN Holding Inc, Pella Corporation, Shenzhen Runcheng Chuangzhan Woodworking, Andersen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Builders Joinery and Carpentry of Wood Market Shifts & Advancements
Digital fabrication and regulatory carbon accounting are converging to transform how wooden joinery is specified, produced, and validated across construction supply chains.
Cross-laminated timber (CLT) and mass plywood panel systems are modularizing traditional stick-frame construction methods. Mid-rise residential developers in Austria and Sweden are adopting factory-cut CLT floor and wall panels with integrated door and window openings. This technology is modularizing on-site labor requirements, compressing project schedules from months to weeks while reducing construction waste streams.
The EU Green Deal's embodied-carbon disclosure mandates are reshaping material qualification protocols. Construction product manufacturers must now submit Environmental Product Declarations verified under EN 15804 standards to access public procurement channels. German and French general contractors are prioritizing suppliers with cradle-to-grave carbon data, marginalizing joinery producers lacking third-party lifecycle assessments.
Developers are consolidating envelope procurement into single-source contracts for windows, doors, and hardware. Large residential builders in Australia and Canada are bypassing traditional distributor networks to contract directly with integrated joinery manufacturers. This pattern concentrates specification authority with a smaller pool of qualified suppliers capable of delivering certified, warrantied, and digitally coordinated building envelope systems.
Global Builders Joinery and Carpentry of Wood Market Segmentation
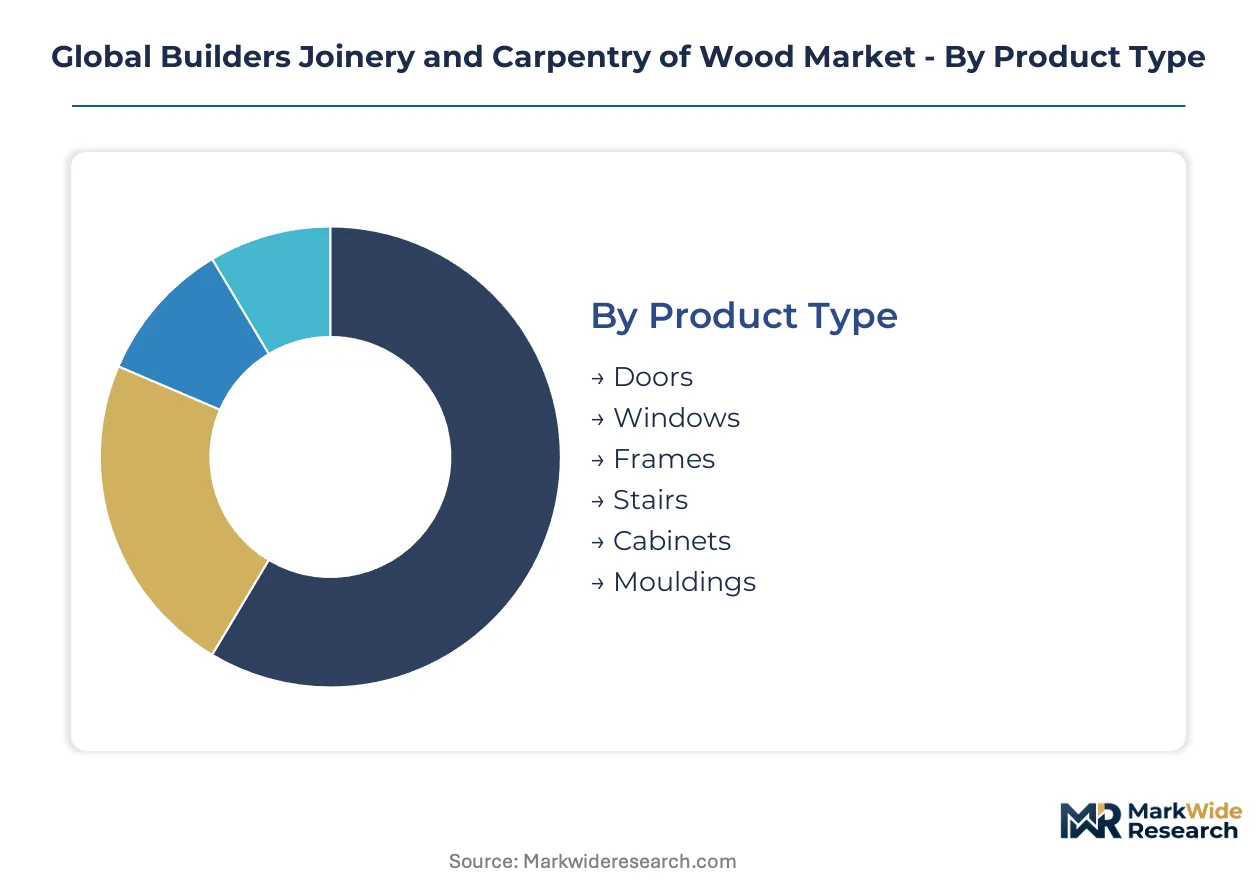
Segmentation in wooden joinery reveals how procurement authority, material certification requirements, and fabrication complexity fragment supply chains across construction verticals. Understanding these divides exposes where specification control concentrates and where margin pools shift between commodity and custom fabrication.
Product Type:
Standardized millwork competes with bespoke architectural components for specification authority across this category, with procurement consolidation favoring bundled envelope systems over discrete component sourcing.
- Doors:Engineered core construction with veneer overlays or solid timber stile-and-rail assemblies meeting fire-resistance and acoustic ratings. German residential developers specify bundled door-hardware systems through single-source contracts to compress procurement cycles and warranty coordination.
- Windows:Wood frame profiles integrated with glazing units, weatherseals, and hardware into factory-assembled casements. China's tier-one cities are scaling prefabricated timber window-wall systems for mid-rise towers, reducing on-site labor dependency and installation variability.
- Frames:Structural and non-structural perimeter assemblies for door and window openings.
- Stairs:Custom-engineered timber stringers, treads, and railings for interior vertical circulation.
- Cabinets:Modular and built-in storage systems for kitchens, baths, and commercial interiors.
- Mouldings:Decorative trim, baseboards, and cornice profiles for finished carpentry.
Leading the category by volume: Doors. Growing fastest: Windows.
Material:
Certification requirements and climate-zone performance specifications fragment sourcing strategies across hardwood and softwood species, with embodied-carbon disclosure rules favoring regionally sourced, FSC-verified timber.
- Oak:Dense hardwood favored for exterior joinery and high-traffic interior applications requiring abrasion resistance and dimensional stability. EU Green Deal lifecycle-assessment mandates are redirecting French and Belgian specification toward PEFC-certified European oak with verified low embodied carbon.
- Pine:Softwood species kiln-dried to sub-19% moisture content for interior millwork and painted finish carpentry. North American production concentrates in the US Southeast and Pacific Northwest, where integrated sawmill-dry kiln operations serve modular home manufacturers with volume contracts.
- Cedar:Naturally rot-resistant softwood specified for exterior applications and humid climates.
- Birch:Fine-grained hardwood for interior doors and cabinet faces requiring smooth paint or stain finishes.
- Walnut:Premium hardwood for architectural millwork and luxury residential interiors.
- Maple:Hard, dense species for stair treads, flooring transitions, and institutional applications.
Volume leadership sits with Pine. Steepest expansion trajectory: Oak, driven by EU carbon-accounting procurement rules.
Application:
Project scale and specification authority determine whether joinery is procured through developer-direct contracts or subcontractor-tier distribution, with public infrastructure imposing distinct certification burdens.
- Residential Housing:Single-family and multi-family construction generating volume demand for standardized doors, windows, and cabinets. Australia's large residential builders are consolidating envelope procurement into direct manufacturer contracts, bypassing traditional distributor networks.
- Commercial Complexes:Office, retail, and hospitality developments specifying exposed timber interiors for biophilic design compliance. Sweden's commercial developers integrate CLT structural panels with prefabricated joinery for whole-building timber solutions.
- Institutional Buildings:Schools, healthcare facilities, and government construction with extended durability requirements.
- Public Infrastructure:Transportation terminals, civic buildings, and utilities subject to public procurement regulations.
Residential Housing commands volume. Commercial Complexes are gaining share fastest on wellness certification demand.
End User:
Technical capability and project complexity determine whether end users source through specification control or subcontractor delegation, with renovation markets demanding different service models than new construction.
- Construction Contractors:General and specialty contractors managing envelope installation and finish carpentry on new builds. Dutch mid-rise residential contractors are adopting factory-cut CLT panels with integrated door and window openings to compress project schedules.
- Interior Designers:Specification professionals directing custom millwork, stair design, and decorative moulding selection for premium residential and hospitality projects.
- Property Developers:Asset owners consolidating procurement authority for multi-building programs.
- Renovation Service Providers:Replacement specialists serving aging housing stock in Japan and South Korea with bespoke interior door, stair, and moulding solutions.
Construction Contractors dominate volume. Renovation Service Providers are expanding most quickly on housing stock replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the largest volume of engineered wood joinery while Germany and the United States dominate precision manufacturing capacity. This production-consumption divide shapes trade flows and certification requirements across major construction markets.
China
Prefabricated timber construction is scaling rapidly in tier-one cities including Shanghai and Shenzhen, compressing on-site installation cycles for mid-rise residential towers. GB standards for fire-resistance ratings determine market access for imported joinery products. Yangtze River Delta manufacturing clusters supply factory-cut window-wall systems to domestic developers reducing labor dependency.
Germany
Residential housing construction is expanding adoption of engineered wood joinery across multi-family developments in Berlin and Munich. EU Green Deal embodied-carbon thresholds are redirecting specification toward FSC-certified timber with verified low lifecycle emissions. Bavarian fabricators are consolidating procurement into bundled door-hardware systems through single-source contracts.
United States
Renovation-driven demand for custom millwork is accelerating in aging housing stock across Northeast and Midwest metropolitan areas. EPA regulations on formaldehyde emissions from composite wood products shape material sourcing decisions for domestic manufacturers. Pacific Northwest integrated sawmill-dry kiln operations serve modular home builders with volume pine contracts.
Japan
Aging housing stock is generating replacement demand for bespoke interior doors, stair assemblies, and decorative mouldings in Tokyo and Osaka metropolitan regions. METI building energy codes influence thermal performance specifications for wooden window systems. Kanto region renovation service providers are expanding specialized millwork offerings for premium residential retrofits.
Australia
Large residential builders are consolidating envelope procurement into direct manufacturer contracts, bypassing traditional distributor networks in Sydney and Melbourne. TGA-equivalent building product certification requirements govern structural timber joinery specifications. New South Wales and Victoria developers are adopting factory-cut CLT panels with integrated door and window openings.
Global Builders Joinery and Carpentry of Wood Market Competitive Landscape
The competitive structure tilts toward integrated building envelope specialists controlling specification channels through bundled hardware-joinery systems. Three strategic archetypes dominate: European hardware-integrated multinationals, North American specialized door platforms, and Asia-Pacific factory-scale fabricators. Competitive moves concentrate on procurement consolidation partnerships and certified supply chain documentation acceleration.
Among hardware-integrated multinationals, ASSA ABLOY exemplifies the specification control archetype through integrated security and joinery platforms. Masonite International and Pella Corporation anchor North American supply positions through specialized interior door and high-performance glazing-wood frame combinations respectively. These three occupy positions across the premium-tier and volume-contracting segments without overlapping direct competition.
| Leading Market Players |
|---|
| ASSA ABLOY |
| VELUX Group |
| Masonite International |
| YKK AP Inc |
| VKR Holding |
| JELD-WEN Holding Inc |
| Pella Corporation |
| Shenzhen Runcheng Chuangzhan Woodworking |
| Andersen Corporation |
| Others |
Supply & Pricing Matrix
A pronounced certification-grade divergence between FSC-verified European oak and untreated Southeast Asian softwoods manifests in both contract pricing and supplier qualification burdens, with German developers paying substantial premiums for cradle-to-grave carbon documentation while Chinese factory-scale producers compete on volume without lifecycle-assessment overhead.
Pricing Analysis
Margin tightening in commodity-grade pine interior doors reflects adhesive cost volatility tied to petrochemical feedstock swings. Three-tier pricing structure across premium certified-oak, standard FSC-softwood, and economy untreated-pine levels separates specification-grade architectural millwork from modular residential bundles. Pricing pressure accelerates in standard tiers as Chinese prefabricated timber systems compress installation labor costs. Renovation service providers in Japan exhibit highest price sensitivity, while German commercial developers prioritize certified supply chains over unit economics.
Supply Chain Analysis
Skilled carpenter scarcity across Bavarian fabrication clusters and Pacific Northwest sawmill-dry kiln operations constrains output expansion regardless of raw material availability. Supply concentrates in Germany, China, and the United States, with Yangtze River Delta factory-scale producers feeding domestic prefabricated construction demand. Kiln-dried hardwoods, formaldehyde-based resins, and engineered timber laminates constitute critical input dependencies. Single-source vulnerability around FSC-certified European oak creates qualification bottlenecks for EU Green Deal compliance. Distribution runs through developer-direct contracting for large residential programs, bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under acute supply constraints, with qualified FSC-certified timber capacity failing to match EU Green Deal procurement timelines and propping structural pricing premiums.
For Market Incumbents: Extend certification documentation capabilities to capture specification control points as EU embodied-carbon thresholds tighten. Accelerate backward integration into FSC-verified European oak supply to defend margin position against adhesive cost volatility and steel-aluminum window substitution threats.
For New Entrants and Emerging Players: Australia's renovation service providers represent an underserved buyer archetype bypassed by large-scale developer-direct contracting. Target bespoke interior door and stair assembly replacement demand in Japan's aging housing stock through specialized millwork service models, or establish CLT-integrated joinery fabrication for Dutch mid-rise residential contractors seeking compressed project schedules.
For Investors and Strategic Acquirers: Re-rating potential sits with hardware-integrated envelope specialists given procurement consolidation into bundled window-door-hardware systems. Long-term viability favors manufacturers with captive FSC supply and digital fabrication capabilities. Watch for inflection when EU public procurement channels begin rejecting suppliers lacking verified Environmental Product Declarations.
| Strategic Initiative | Industry Significance |
|---|---|
| FSC Supply Chain Certification | EU Green Deal procurement rules marginalize uncertified joinery producers from public infrastructure contracts. |
| CLT-Integrated Fabrication | Austrian and Swedish developers compress project schedules through factory-cut panels with pre-cut door and window openings. |
| Developer-Direct Contracting | Australian and Canadian residential builders consolidate envelope procurement authority with integrated manufacturers. |
| Digital Fabrication Investment | German fabricators automate stile-and-rail assembly to offset skilled carpenter scarcity across European apprenticeship pipelines. |
| Fire-Rating Compliance Acceleration | China's GB standards create non-tariff barriers requiring dedicated testing protocols for European and North American market entry. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with joinery fabrication plant managers, procurement leads at German residential developers, FSC chain-of-custody auditors, and Pacific Northwest sawmill operations directors. EPA formaldehyde emission databases, EU EPD verification registries, and Chinese GB standard compliance records provided material qualification benchmarks. Bottom-up volume modeling across product categories reconciled with top-down construction spend allocations.
Reconciliation of production capacity surveys, import-export flows, and construction permit data streams generated volume and value estimates across the projection horizon. Segmentation dimensions included product type, material certification grade, application vertical, and end-user procurement authority, with regional regulatory clusters treated as distinct market access conditions. CAGRs derived from trend extrapolation of prefabricated timber adoption rates and renovation cycle replacement demand, cross-referenced against EU Green Deal implementation timelines and China's dual carbon policy enforcement.
Revisions become necessary when EU embodied-carbon disclosure mandates accelerate ahead of certified supply chain readiness, or when China's GB fire-rating standards tighten import access unexpectedly. Material deviation in these regulatory triggers warrants pause and re-evaluation of demand forecasts and supplier qualification assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Calcium Aluminate Cement Market
Building Materials
Australia Architectural Coatings Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
United States White Cement Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
Building and Construction Plastics Market
Building Materials
HDG Steel Pipe Market
Building Materials
North America Engineered Stone Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Exterior Doors Market
Building Materials
North America Construction Aggregates Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
Europe Dry-Mix Mortar Market
Building Materials
Acoustic Damping Tiles Market
Building Materials
Cladding Market