
 Silt Curtain Market | 2026-2036
Silt Curtain Market Size, Share, and Industry Trends Forecast 2026-2036
Silt Curtain Market Intelligence
The European Union's Water Framework Directive is shifting the cost-of-entry calculus for manufacturers by mandating stricter turbidity limits near construction sites. Elastec specializes in rapid-deployment containment systems for emergency response and construction. GEI Works competes through its extensive product range catering to both marine construction and environmental protection. Nilex Inc. leverages its expertise in geosynthetic materials to offer durable erosion control solutions.
A silt curtain is a flexible, floating barrier used to control the dispersion of suspended solids in a body of water. These systems typically consist of a geotextile fabric, such as polypropylene, attached to a flotation boom and a ballast chain for stability. Within applications, dredging projects and marine construction constitute the largest sources of demand. Polypropylene is the leading material type, valued for its high tensile strength and resistance to marine degradation.
Regulatory frameworks from bodies like the US EPA and China's Ministry of Ecology and Environment (MEE) directly mandate the use of silt curtains in sensitive projects. Compliance with ISO 14001 environmental management standards also encourages adoption among multinational construction firms. The key decision for suppliers will be balancing material durability against emerging requirements for biodegradable or recyclable components.
Market Dynamics
The silt curtain market's core dynamic is the tension between accelerating coastal and marine infrastructure development and the parallel tightening of environmental regulations. Mandates from bodies like the US EPA and the European Union are setting non-negotiable performance floors for sediment control.
Growth Catalysts
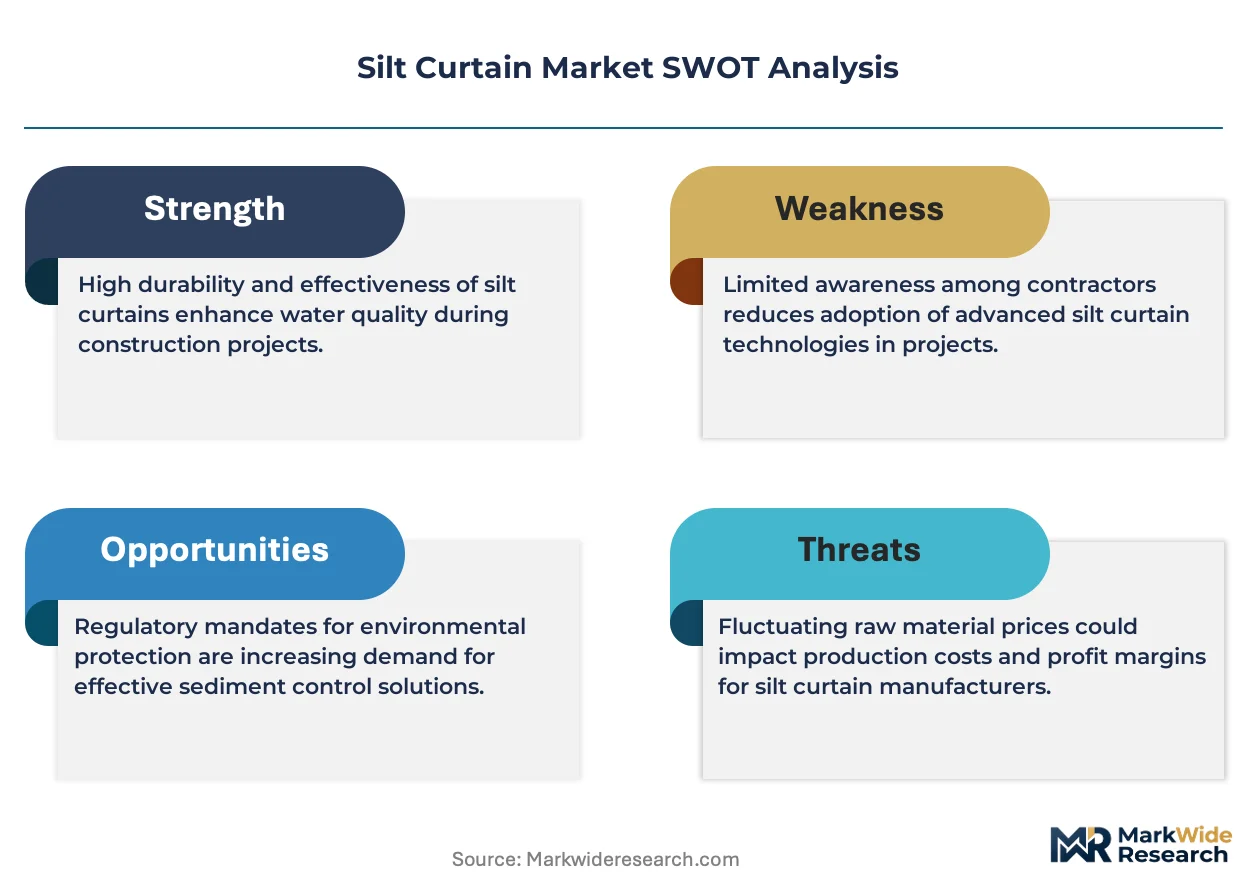
- Regulatory Mandates:The European Union's Water Framework Directive and the US Clean Water Act enforce strict turbidity limits, directly compelling the use of silt curtains in construction and dredging near sensitive waterways.
- Infrastructure Investment:Massive public and private investment in port expansion, bridge construction, and coastal reclamation projects, particularly in China and Southeast Asia, creates a foundational source of demand.
- Dredging Activity:An increase in capital and maintenance dredging to deepen shipping channels for larger container vessels is a primary catalyst, as these operations generate significant sediment plumes that require containment.
Market Restraints
- Operational Limitations:Standard silt curtains exhibit reduced effectiveness in high-velocity currents, strong wave action, or deep-water applications, limiting their use in certain challenging marine environments without significant engineering modifications.
- Input Material Costs:Price volatility for high-grade polypropylene and other geotextile fabrics, which form the core of the curtain, can compress manufacturer margins and increase the total project cost for end-users.
- Alternative Solutions:In some applications, particularly near-shore or in calmer waters, alternative methods like dewatering tubes, cofferdams, or natural vegetative buffers can present a more cost-effective or suitable option for erosion and sediment control.
Strategic Opportunities
- Biodegradable Materials:Development of high-strength, biodegradable, or fully recyclable geotextile fabrics presents a significant opportunity to address end-of-life disposal concerns and appeal to projects with stringent sustainability requirements.
- Aquaculture Expansion:The growing aquaculture industry offers a new application frontier, using specialized curtains to contain waste, manage algae blooms, and protect farmed fish populations from external contaminants.
- Emerging Market Adoption:Increasing regulatory enforcement in developing regions across South America and Africa for mining and infrastructure projects opens new geographic markets for suppliers as local standards align with international norms.
Industry Challenges
- Installation Expertise Gap:The effective deployment, anchoring, and maintenance of large-scale silt curtain systems require specialized training and equipment, and a scarcity of skilled installation crews can lead to project delays and performance failures.
- Compliance Fragmentation:Manufacturers and contractors face the operational challenge of navigating a complex and varied landscape of local, state, and national regulations, each with unique testing and performance specifications.
- Durability and Disposal:A key challenge is engineering curtains that can withstand harsh marine conditions for the project's duration while also meeting growing client and regulatory pressure for environmentally responsible disposal or recycling post-use.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silt Curtain Market |
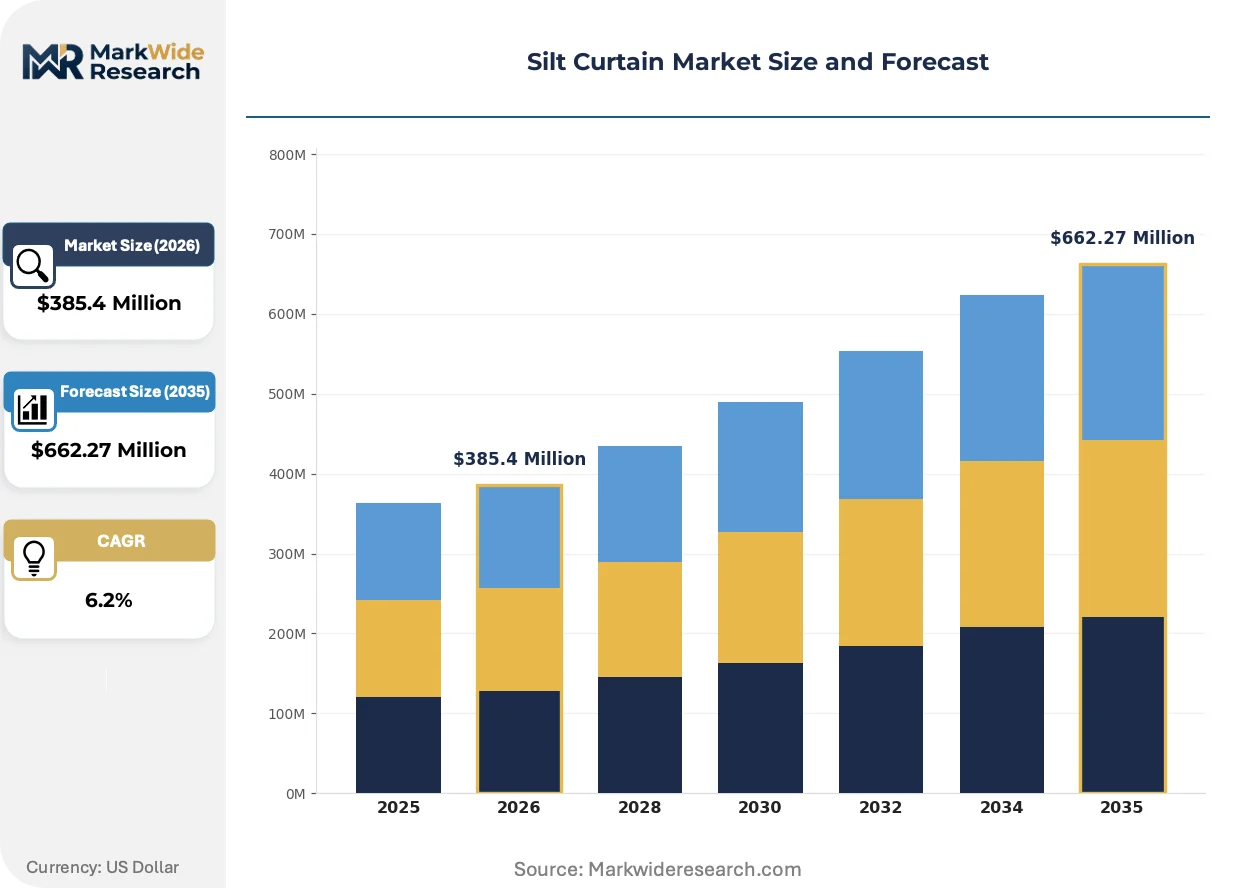
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polyester, Nylon, Wool, Cotton Application: Marine Construction, Environmental Protection, Erosion Control, Sediment Management, Dredging Projects Installation Method: Boat Deployment, Fixed Anchoring, Floating Barrier, Shoreline Securing End User: Port Authorities, Environmental Agencies, Construction Firms, Water Resource Managers |
| Companies Covered | ACME Environmental, Cunningham Covers, ABASCO LLC, Coastal Dynamics, Texas Boom Company, Elastec, Nilex Inc., Marinetek Group, GEI Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silt Curtain Market Strategic Shifts & Innovations
The market is reshaping around the integration of digital technologies and advanced material science to meet demands for greater environmental accountability. This evolution is shifting silt curtains from passive barriers to active components of a project's environmental management system, driven by regulatory pressure and client sophistication.
Smart silt curtains integrating submersible sensors for real-time turbidity and water quality monitoring are gaining traction. Operators of critical infrastructure, including port authorities and offshore energy developers, are adopting these systems to ensure continuous compliance with environmental permits. This integration of IoT sensors and data analytics is electrifying the product category, transforming passive barriers into active environmental management tools that provide auditable performance data.
China's Ministry of Ecology and Environment (MEE) is enforcing stricter controls on marine ecosystem protection as part of the country's broader environmental and "dual carbon" objectives. This policy shift compels developers in marine construction and dredging to move beyond basic compliance toward proactive, high-performance sediment containment. The dredging and coastal infrastructure segments are most affected, driving a preference for more durable, Type II and Type III curtain systems capable of withstanding longer deployment cycles.
A clear behavioral shift is occurring as large engineering and construction firms move from direct purchasing to full-service leasing and deployment contracts. This model bundles the silt curtain product with specialized installation, ongoing monitoring, maintenance, and final removal, effectively outsourcing operational risk to the curtain supplier. The trend is most visible in North American and European markets where high labor costs and stringent regulatory penalties make specialized, turnkey solutions more attractive.
Silt Curtain Market Segmentation
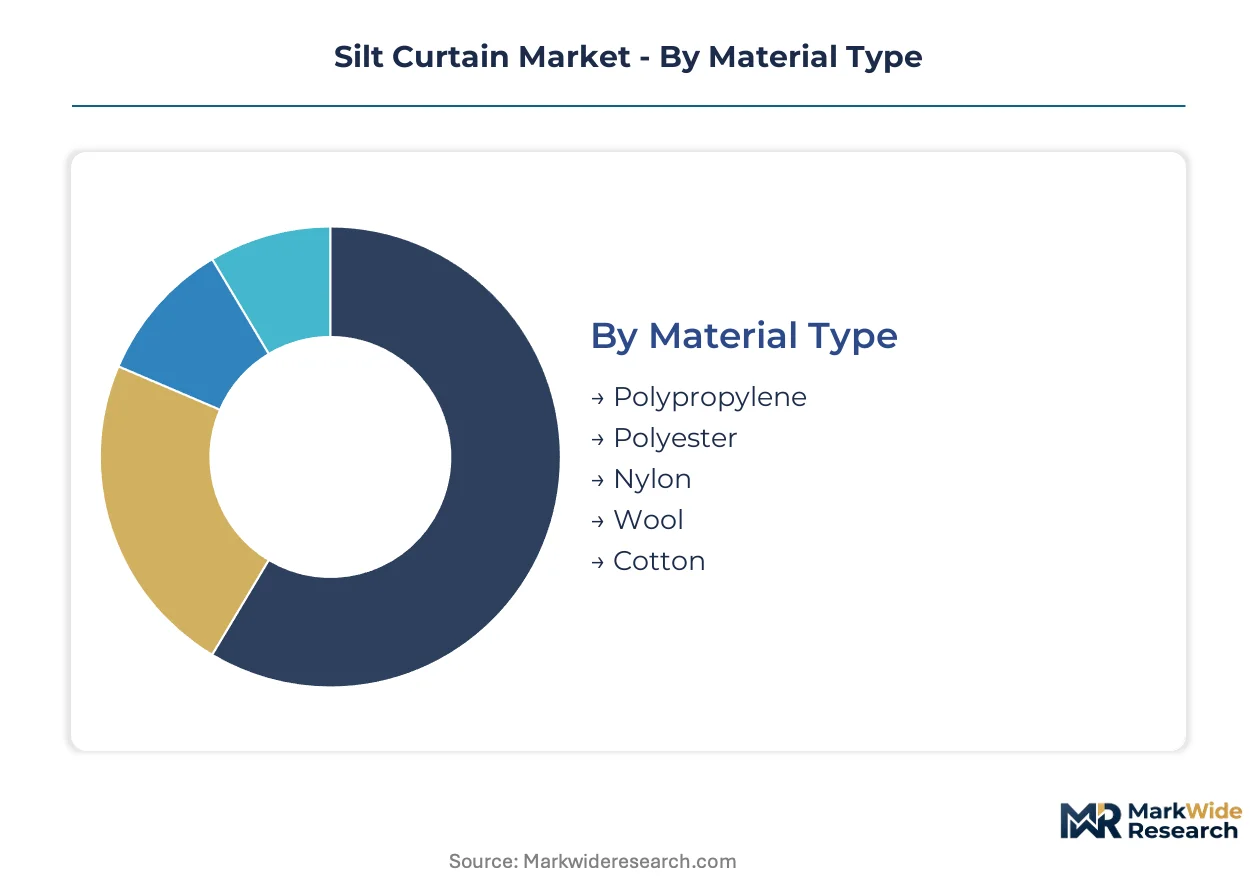
The silt curtain market's segmentation reflects diverse operational requirements and material science advancements. Understanding these divisions helps stakeholders identify key demand drivers and evolving technological preferences across various aquatic environments. Each segment plays a distinct role in managing water quality during construction and environmental remediation efforts.
Material Type:
Supply concentration for silt curtain materials heavily influences product specifications and cost structures across the industry.
- Polypropylene:This synthetic polymer offers high tensile strength and resistance to marine degradation, ideal for long-term deployment in harsh saltwater. China's extensive port development projects drive demand.
- Polyester:Known for its excellent UV resistance and dimensional stability, polyester geotextiles maintain structural integrity under prolonged sun exposure. European infrastructure projects frequently specify polyester.
- Nylon:Nylon provides superior abrasion resistance, making it suitable for applications where curtains may experience friction against submerged structures.
- Wool:Primarily used in niche biodegradable applications, wool curtains offer a natural, short-term solution in environmentally sensitive freshwater areas.
- Cotton:Cotton offers a biodegradable option for temporary, low-impact projects, particularly in calm, inland waterways.
Today's leader: Polypropylene. Tomorrow's challenger: Polyester.
Application:
The application landscape for silt curtains dictates specific performance requirements and deployment strategies across diverse aquatic environments.
- Dredging Projects:These operations generate significant sediment plumes, requiring robust silt curtains to prevent dispersion and comply with environmental regulations. Demand concentrates in major shipping channels.
- Marine Construction:This segment includes port expansion, bridge building, and coastal reclamation, where curtains contain turbidity from piling and excavation. China's coastal infrastructure development programs drive demand.
- Environmental Protection:This application focuses on safeguarding sensitive ecosystems from pollution during nearby industrial or construction activities.
- Erosion Control:Silt curtains prevent soil erosion and sediment runoff from land-based activities into adjacent waterways.
- Sediment Management:This broad application covers various strategies for controlling and containing suspended solids in water bodies.
Dredging Projects currently command the largest volume, while Environmental Protection is expanding most quickly.
Installation Method:
Installation method directly impacts deployment efficiency and operational costs, influencing overall project volume and complexity.
- Fixed Anchoring:This method involves securing the silt curtain to the seabed using anchors, providing long-term stability in moderate currents. US infrastructure projects frequently utilize fixed anchoring.
- Floating Barrier:These systems rely on ballast chains and flotation booms to create a suspended barrier, suitable for dynamic water conditions. Port authorities in Europe often deploy floating barriers.
- Boat Deployment:This method utilizes specialized vessels to unroll and position silt curtains, ideal for rapid response or large-area coverage in open water.
- Shoreline Securing:This technique anchors curtains directly to the land, preventing sediment runoff from coastal construction sites.
Floating Barrier installations currently dominate, while Shoreline Securing is gaining share fastest.
End User:
End-user types define specific procurement patterns and regulatory compliance needs within the silt curtain market.
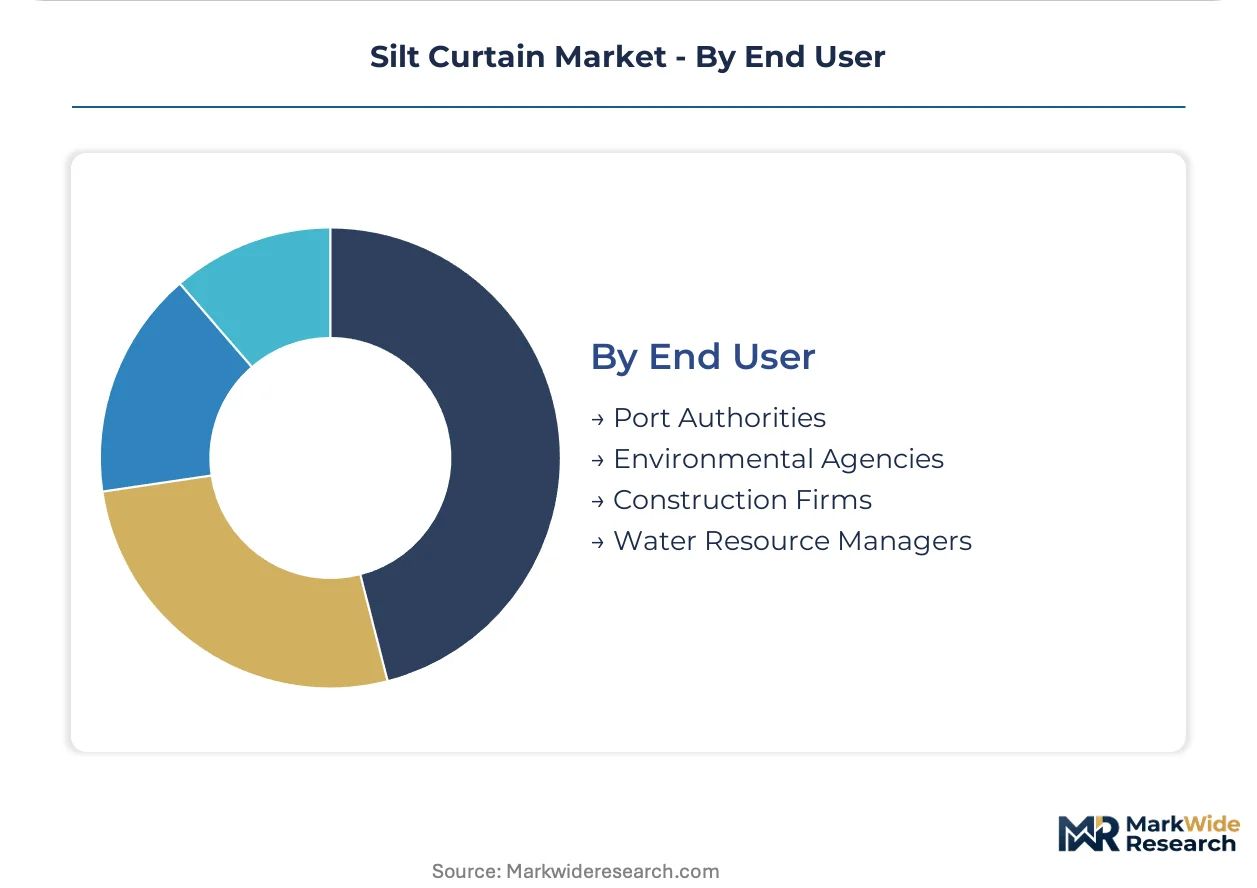
- Construction Firms:These entities require silt curtains for managing turbidity during dredging, piling, and marine infrastructure projects. Demand from multinational construction firms is strong in Southeast Asia.
- Port Authorities:Responsible for maintaining navigable waterways and environmental compliance, port authorities deploy silt curtains during maintenance and expansion. Major ports in China prioritize high-durability systems.
- Environmental Agencies:These government bodies specify and sometimes deploy silt curtains for remediation projects or regulatory enforcement.
- Water Resource Managers:This group uses silt curtains for controlling sediment in rivers, lakes, and reservoirs, focusing on water quality.
Construction Firms represent the largest customer base, with Environmental Agencies showing increasing procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The silt curtain market initially scaled in regions undertaking extensive marine infrastructure development and environmental remediation efforts. Early applications concentrated in areas with significant dredging activities and coastal construction projects, establishing foundational demand patterns. Regulatory pressures for sediment control further solidified market presence in these pioneering geographies.
China
China's extensive port expansion and coastal reclamation projects generate substantial demand for silt curtains. The Ministry of Ecology and Environment (MEE) enforces strict marine ecosystem protection, compelling advanced containment solutions. Major port cities like Shanghai and Shenzhen require high-durability Type II and Type III systems for continuous operations.
United States
United States large-scale dredging projects to maintain navigable waterways drive silt curtain procurement. The US EPA's Clean Water Act mandates stringent sediment control during construction near sensitive aquatic environments. Infrastructure initiatives along the Gulf Coast and Atlantic seaboard require specialized systems for bridge and port upgrades.
Germany
Germany's market demand is influenced by the European Union's Water Framework Directive, which sets strict turbidity limits. The country's extensive inland waterways and North Sea ports necessitate effective sediment management during maintenance and expansion. Hamburg's port authority frequently deploys floating barriers to manage turbidity from ongoing dredging activities.
India
India's growing investment in port modernization and coastal infrastructure projects creates a significant demand base. The country's environmental regulations, aligned with international standards, increasingly require sediment control measures for large construction sites. Major coastal development zones like Gujarat and Andhra Pradesh are seeing increased adoption of these protective barriers.
Australia
Australia's significant mining and infrastructure projects in coastal areas generate demand for erosion control. Environmental protection agencies impose strict guidelines for sediment runoff, particularly impacting sensitive marine ecosystems like the Great Barrier Reef. Port developments in Western Australia and Queensland utilize silt curtains for turbidity management during expansion.
Silt Curtain Market Key Industry Players
The competitive structure tilts toward specialized manufacturers offering tailored solutions for diverse aquatic environments. The market features a blend of established players with broad product portfolios and niche providers focusing on specific applications or material innovations. Strategic archetypes include full-service providers offering turnkey installation and material specialists leveraging advanced geotextiles. Geographic expansion into emerging markets and portfolio diversification into biodegradable solutions represent dominant competitive moves.
Within the full-service provider archetype, Elastec exemplifies rapid-deployment containment systems, crucial for emergency response and construction projects demanding quick deployment. GEI Works occupies a position catering to both marine construction and environmental protection, offering an extensive product range that addresses varied operational requirements. Nilex Inc. represents a material specialist, leveraging its deep expertise in geosynthetic materials to offer durable erosion control solutions, particularly where longevity is paramount. These companies, through their distinct approaches, anchor different segments of the market by emphasizing either operational agility, broad application coverage, or material science innovation to meet evolving client and regulatory demands across diverse aquatic environments.
| Leading Market Players |
|---|
| ACME Environmental |
| Cunningham Covers |
| ABASCO LLC |
| Coastal Dynamics |
| Texas Boom Company |
| Elastec |
| Nilex Inc. |
| Marinetek Group |
| GEI Works |
| Others |
Cost & Logistics Intelligence
The European Union's Water Framework Directive, mandating stricter turbidity limits, forces suppliers to innovate with high-performance materials and integrated services. This demand-side pressure compels the supply chain to prioritize compliance-driven solutions, impacting material specifications and overall project pricing.
Pricing Analysis
Bundled full-service leasing and deployment contracts are reshaping pricing structures, moving beyond transactional product sales. Price differentiation stems from material durability, such as Type II or Type III curtain systems, and the level of specialized installation and monitoring services provided. Pricing pressure stems from the volatility of high-grade polypropylene costs, which can compress manufacturer margins. Large engineering and construction firms, facing stringent regulatory penalties, exhibit lower price sensitivity for comprehensive, risk-mitigating solutions.
Supply Chain Analysis
Logistics and freight costs significantly influence the overall supply chain, particularly for bulky geotextile fabrics and flotation booms. Supply concentration for core materials like polypropylene primarily resides in China and other Asian industrial centers. The market relies heavily on raw material inputs such as polypropylene and polyester geotextiles, along with components like ballast chains. Commodity price volatility for these core materials represents a structural supply chain risk. Distribution runs through specialized marine contractors and direct sales to large construction firms and port authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, where the cost of specialized installation expertise and stringent regulatory compliance in North America contrasts with emerging market opportunities driven by foundational infrastructure buildout.
For Market Incumbents: Extend existing product lines with advanced biodegradable or fully recyclable geotextile options to meet evolving sustainability mandates. Invest in specialized training programs for large-scale system deployment to address the installation expertise gap. Diversify service offerings into full-service leasing and monitoring packages, especially for critical infrastructure projects. This approach mitigates threats from alternative solutions and fragmented regulatory landscapes.
For New Entrants and Emerging Players: Begin with niche applications such as aquaculture containment or specialized erosion control in environmentally sensitive freshwater areas. Target emerging markets across South America and Africa where regulatory enforcement is increasing and local standards align with international norms. Focus on developing cost-effective, fit-for-purpose solutions that address specific regional challenges, leveraging advanced material science for competitive advantage.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized manufacturers developing smart silt curtain technology or proprietary biodegradable materials. The long-term viability of this market is underpinned by continuous global infrastructure development and tightening environmental regulations. Seek acquisition targets that possess strong intellectual property in advanced materials or proven expertise in deploying complex, integrated monitoring systems. The signal to watch is the widespread adoption of mandatory lifecycle assessment requirements for marine construction materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Biodegradable Geotextiles | Addresses environmental disposal concerns and appeals to projects with stringent sustainability requirements. |
| Expand Full-Service Leasing Models | Outsources operational risk for construction firms, offering turnkey solutions in North America and Europe. |
| Integrate IoT for Real-time Monitoring | Transforms passive barriers into active environmental management tools, ensuring continuous compliance for port authorities. |
| Target Aquaculture Applications | Opens a new application frontier for specialized curtains to manage waste and protect farmed fish populations. |
| Geographic Expansion into Africa | Captures demand from increasing regulatory enforcement and infrastructure projects in developing regions. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct a robust market analysis. Combining insights from construction firm executives, port authority managers, and environmental agency officials provided qualitative depth. Secondary validation involved cross-referencing data from US EPA reports, China MEE directives, and EU Water Framework Directive documents.
The analytical framework cross-referenced historical market performance against expert panel input to project future trends over the projection horizon. Segmentation dimensions modeled included material type, application, installation method, end-user, and geographic region, alongside specific curtain types like Type II and Type III. Compound Annual Growth Rates were calculated from historical data and expert panel projections, incorporating inputs like coastal infrastructure investment budgets and regulatory compliance spending.
Caveats apply where geopolitical shifts, unforeseen material cost volatility, or rapid technological disruption in sediment control could materially shift the outlook. Forecasts reflect assumptions documented through this comprehensive approach. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Septic Tanks Market
Environmental Engineering
Aerobic Treatment Units Market