
 Qatar Facade Market | 2026-2036
Qatar Facade Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Facade Market Analytics
Project-specifier channels in Qatar is fragmenting as main contractors diversify supplier rosters beyond legacy relationships. Qatar Meta Coats W.L.L (QMC) leverages in-house metal fabrication to secure stadium and museum contracts. Bemo International anchors its position through specialized unitized system engineering for high-rise commercial towers. Everest Aluminum Co WLL differentiates via precision extrusion capabilities serving premium residential developments in Lusail.
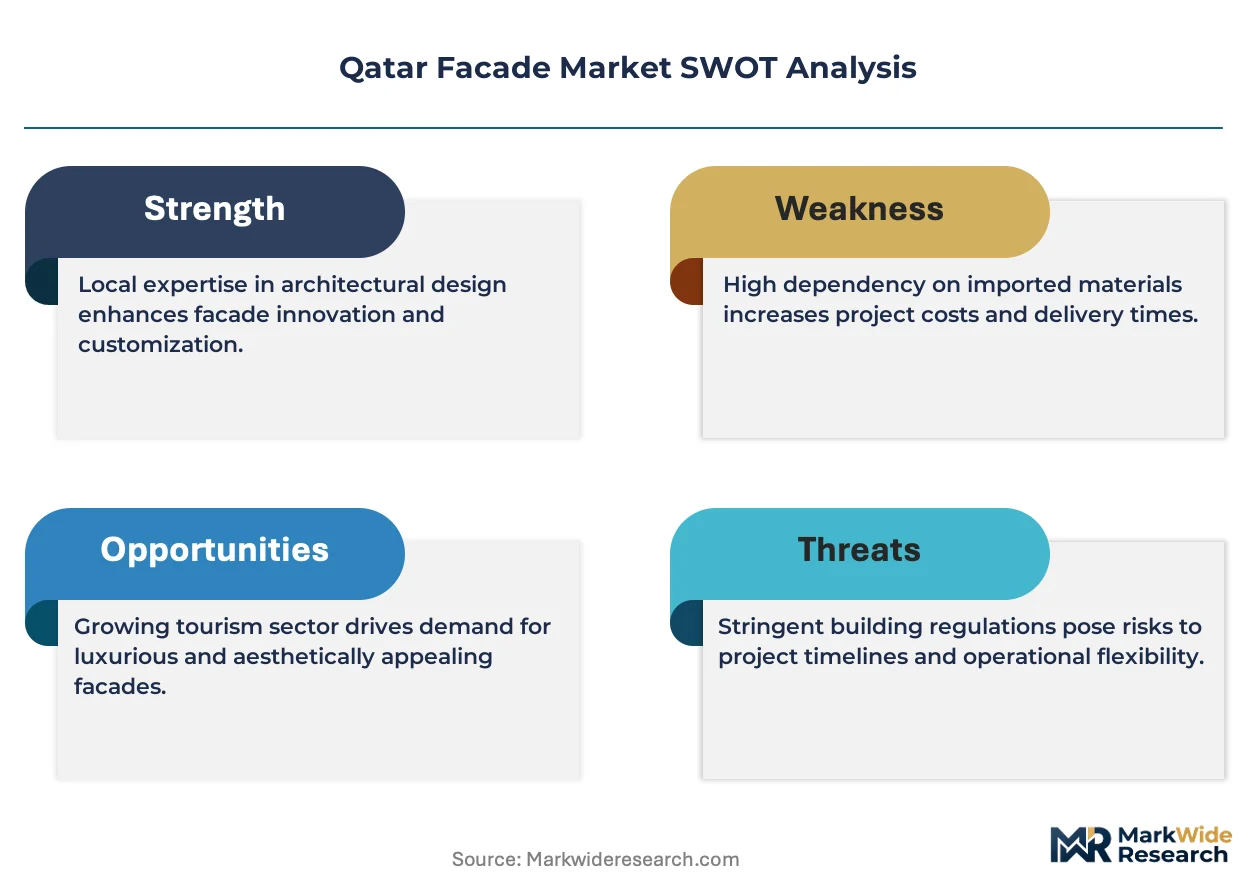
A facade is the exterior envelope system of a building, comprising cladding panels, glazing units, structural framing, and weatherproofing membranes engineered to resist wind loads, thermal transfer, and moisture ingress while controlling daylight transmission. Its primary purpose is to protect interior spaces and reduce HVAC energy consumption. Glass dominates Qatar's premium commercial segment where solar heat gain coefficient specifications drive specification decisions. Ventilated facades represent the fastest-growing technology category as developers pursue passive cooling performance in hospitality structures. Metal cladding sustains stable demand across industrial facilities where cost predictability outweighs aesthetic premium.
Qatar's Ministry of Municipality and Environment enforces building energy codes that mandate thermal transmittance limits for envelope assemblies, directly elevating demand for high-performance composite and insulated glazing systems. The Gulf Organization for Research and Development administers GSAS sustainability ratings that incentivize facade recyclability and embodied carbon reduction. Contractors and specifiers must monitor evolving mandatory disclosure requirements for facade material sourcing as Qatar advances its national sustainability framework ahead of major event legacy conversions.
Market Dynamics
Qatar's tightening thermal performance mandates for building envelopes are forcing developers to abandon conventional curtain wall specifications in favor of high-performance composite systems, compressing supplier qualification timelines and elevating engineering complexity for facade contractors.
Growth Catalysts
- GSAS Sustainability Ratings:The Gulf Organization for Research and Development's green building framework incentivizes facade recyclability and embodied carbon reduction, pulling premium specifications into hospitality and mixed-use towers.
- Ventilated Facade Technology:Passive cooling performance requirements in hospitality structures are accelerating adoption of rainscreen and double-skin systems across West Bay and Lusail developments.
- Lusail Smart City Build-Out:Qatar's planned city expansion is concentrating demand for unitized glazing and metal cladding systems in premium residential and commercial clusters.
Market Restraints
- Aluminum Price Volatility:Primary aluminum input costs fluctuate with energy pricing, compressing margin predictability for extrusion-dependent contractors serving industrial facilities.
- Fabrication Capacity Concentration:In-house metal fabrication capabilities cluster among established Doha-based suppliers, limiting new entrant access to stadium-scale and museum contracts.
- Thermal Transmittance Compliance Burden:Ministry of Municipality and Environment energy codes mandate complex testing protocols that extend project qualification cycles for imported glazing systems.
Strategic Opportunities
- Event Legacy Conversion Pipeline:Stadium and temporary venue repurposing into commercial and hospitality assets will generate retrofit demand for high-performance envelope upgrades.
- Integrated Photovoltaic Facades:Building-integrated solar technology convergence with curtain wall systems offers untapped potential for mixed-use towers pursuing net-zero targets.
- Direct Developer Contracting:Main contractor roster diversification is opening direct specification channels between facade specialists and commercial building developers in Doha.
Industry Challenges
- Facade Engineering Talent Scarcity:Thermal modeling and computational fluid dynamics expertise required for high-performance glazing design remains concentrated among senior specialists.
- GSAS Certification Timeline Compression:Sustainability rating documentation requirements extend pre-construction phases, straining project cash flow for specialist contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Facade Market |
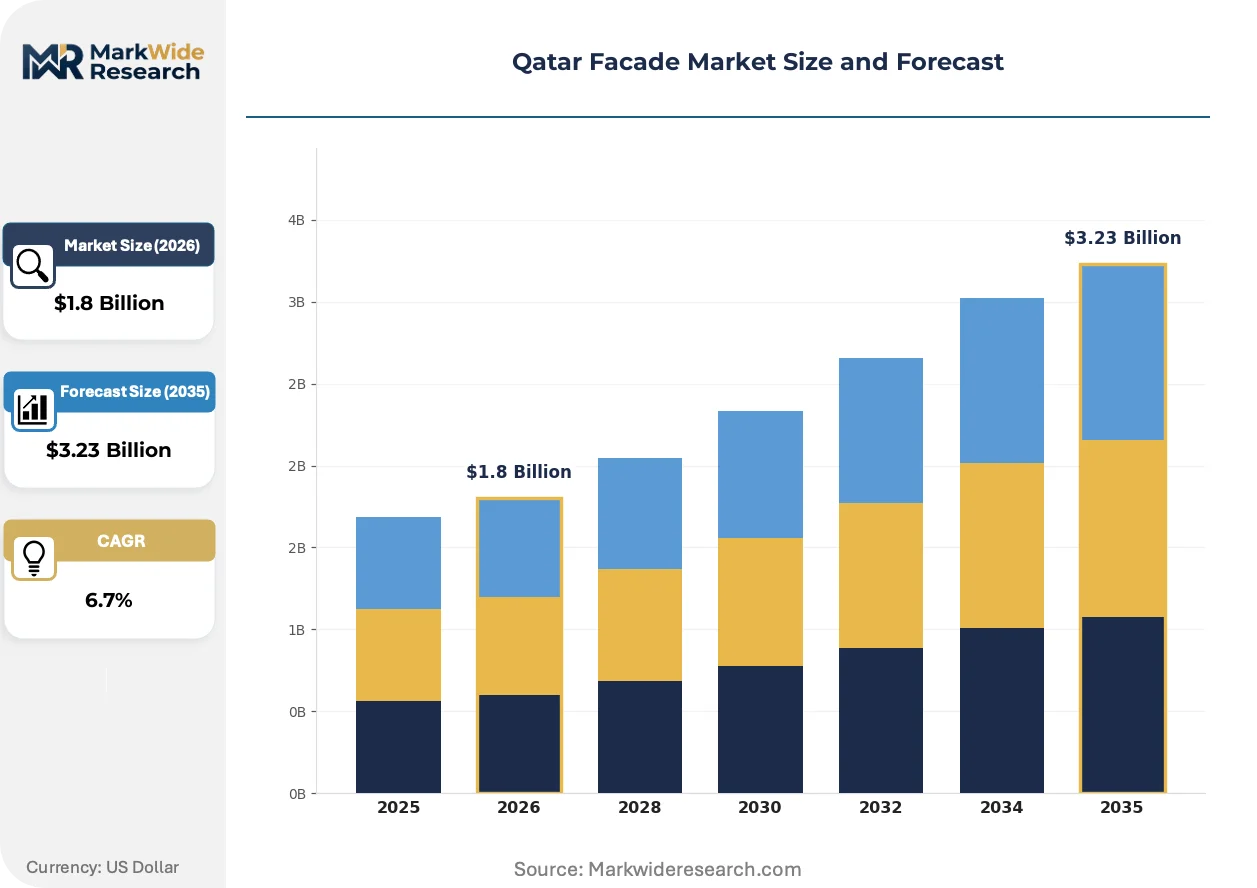
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Metal, Composite, Stone Application: Commercial Buildings, Residential Projects, Industrial Facilities, Hospitality Structures Technology: Ventilated Facades, Unitized Systems, Curtain Walls, Traditional Installation Type: New Construction, Renovation, Retrofitting, Prefabricated |
| Companies Covered | Qatar Meta Coats W.L.L (QMC), Alce Engineering Qatar WLL, Bemo International, Everest Aluminum Co WLL, Norwood Qatar LLC, Alutec, Aluglass Co Ltd, Alumasa Qatar, Sollass Alu & Glass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Facade Market Evolving Landscape
Active specification channels in Qatar are compressing traditional procurement cycles as developers pursue faster envelope delivery for hospitality and commercial towers. Three interconnected shifts are reconfiguring how facade systems are engineered, procured, and deployed.
Electrochromic glazing is collapsing the distinction between fixed solar control and dynamic daylight management in premium commercial towers. Hospitality developers along the Doha Corniche are specifying these systems for guest room facades to eliminate external shading hardware. The technology is collapsing first-cost premiums against operational energy savings over five-year payback horizons.
Qatar's Ministry of Municipality and Environment is enforcing mandatory thermal transmittance disclosure for all envelope assemblies above 10,000 square meters. The regulation is disqualifying conventional single-glazed curtain wall systems from new commercial permits. High-rise towers in West Bay are responding with triple-glazed unitized specifications and thermally broken framing.
Developer procurement teams are consolidating facade specifications under design-build contracts rather than traditional design-bid-build sequences. Main contractors are absorbing engineering risk and selecting specialist subcontractors through pre-qualification rather than open tender. This concentration is most visible in Lusail's mixed-use districts where single-source envelope responsibility reduces interface coordination.
Qatar Facade Market Segmentation
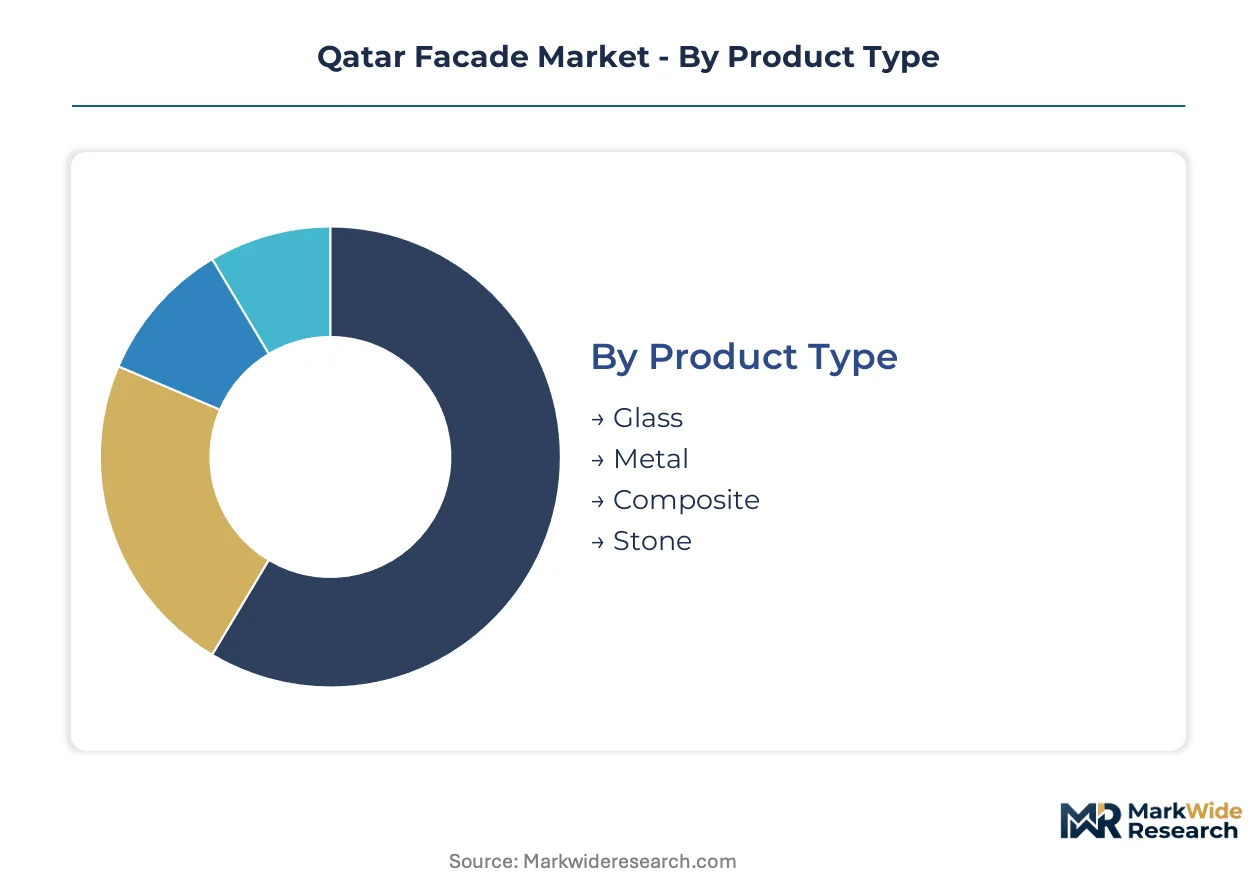
Facade specification in Qatar fragments across performance tiers, installation methods, and end-use requirements. Procurement teams align material selection with GSAS sustainability mandates, thermal transmittance codes, and project delivery timelines. Understanding segment boundaries clarifies where engineering complexity concentrates and where cost predictability dominates.
Product Type:
After-sales service intensity varies sharply across material categories, with high-performance glazing demanding specialized maintenance protocols and metal systems requiring periodic coating restoration.
- Glass:Triple-glazed and electrochromic specifications dominate premium commercial towers along West Bay, where solar heat gain coefficient optimization drives procurement decisions. Doha Corniche hospitality developers specify these systems to eliminate external shading hardware while meeting Ministry of Municipality and Environment thermal transmittance mandates.
- Metal:Aluminum extrusion and composite panel systems anchor industrial facility envelopes where cost predictability outweighs aesthetic premium. Lusail premium residential clusters specify precision-extruded metal cladding for durability in high-salinity coastal conditions.
- Composite:High-performance insulated panels serve mixed-use towers pursuing GSAS sustainability ratings through embodied carbon reduction and recyclability compliance.
- Stone:Natural and engineered stone cladding sustains demand in cultural and government buildings where material permanence signals institutional permanence.
Glass holds the largest share; momentum sits with Composite as GSAS ratings tighten material disclosure requirements.
Application:
Cost tier stratification across end-use segments determines specification flexibility, with hospitality and commercial towers absorbing premium engineering costs unavailable to industrial clients.
- Commercial Buildings:Unitized glazing and double-skin systems dominate West Bay high-rises where energy code compliance compresses conventional curtain wall viability. Developers absorb extended qualification cycles for imported high-performance systems to secure municipal permits.
- Hospitality Structures:Ventilated facades and electrochromic glazing concentrate along the Doha Corniche, where guest experience and passive cooling performance justify capital investment. Five-year operational energy payback horizons collapse first-cost premiums against lifecycle savings.
- Residential Projects:Metal cladding and conventional glazing serve Lusail's premium residential clusters, balancing aesthetic differentiation with construction schedule pressure.
- Industrial Facilities:Cost-predictable metal panel systems sustain stable demand where thermal performance requirements remain less stringent than commercial mandates.
Commercial Buildings command the deepest specification investment; Hospitality Structures are expanding most quickly as event legacy conversions accelerate envelope upgrade demand.
Technology:
Volume concentration shifts toward pre-engineered systems as design-build procurement compresses traditional tender timelines and transfers engineering risk to contractors.
- Ventilated Facades:Rainscreen and double-skin configurations represent the steepest expansion trajectory across Qatar's hospitality segment, delivering passive cooling performance without mechanical intervention. West Bay and Lusail developments specify these systems to meet GSAS sustainability benchmarks while reducing HVAC capital expenditure.
- Unitized Systems:Factory-assembled curtain wall units reduce site labor requirements and interface coordination complexity for high-rise commercial towers. Main contractors in Lusail's mixed-use districts consolidate envelope responsibility under single-source design-build arrangements.
- Curtain Walls:Conventional stick-built systems sustain residual demand in mid-rise commercial projects where schedule flexibility permits longer installation timelines.
- Traditional:Masonry and single-skin metal applications persist in industrial and secondary commercial assets where energy code grandfathering or cost constraints limit system upgrade.
Unitized Systems hold the largest share; Ventilated Facades are gaining share fastest as thermal performance mandates tighten.
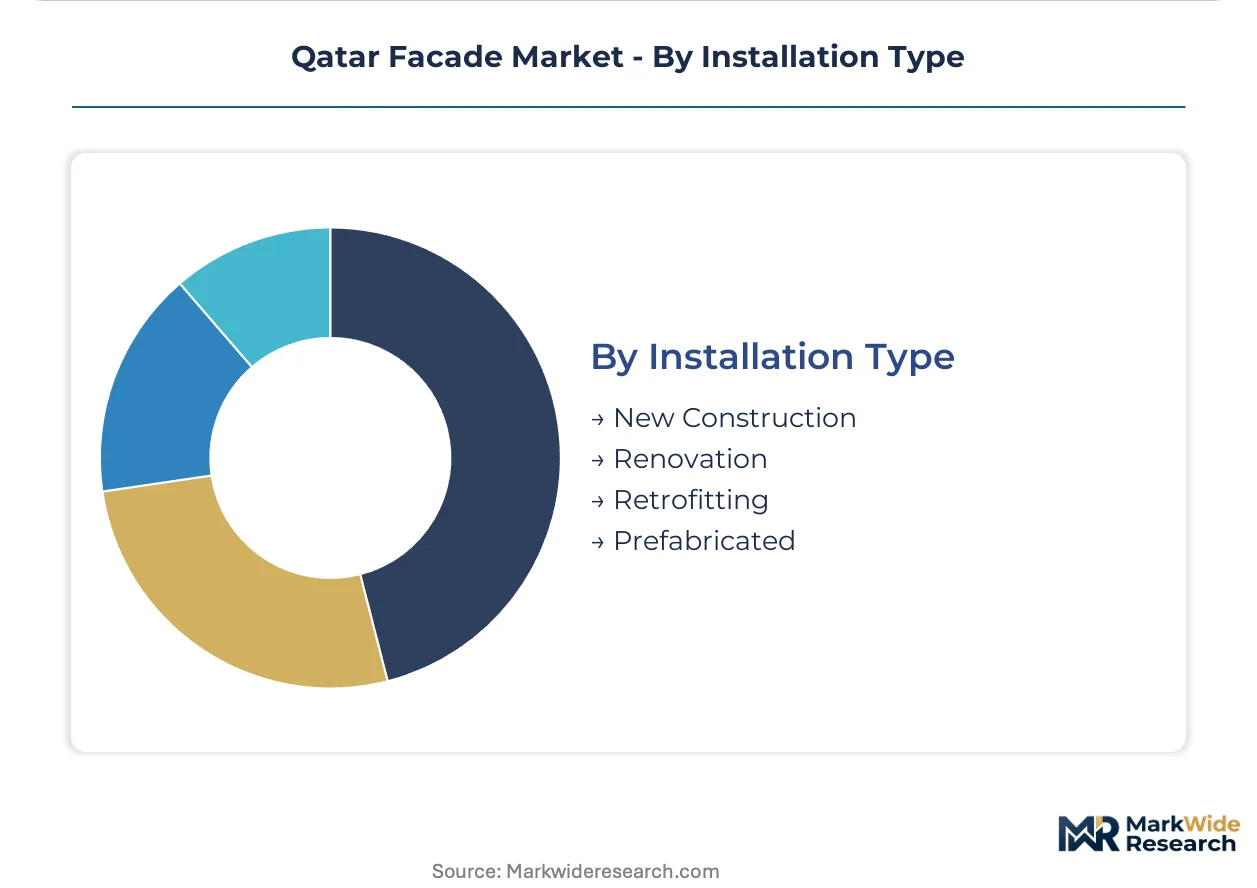
Installation Type:
Customer type differentiation separates developer-led new construction from asset-owner renovation decisions, with procurement authority and timeline pressure diverging sharply.
- New Construction:Design-build envelope contracts dominate Lusail and West Bay developments, with main contractors pre-qualifying specialist subcontractors rather than open tender. Integrated specification of glazing, framing, and weatherproofing reduces interface risk for commercial tower developers.
- Retrofitting:High-performance envelope upgrades concentrate in stadium and temporary venue repurposing for commercial and hospitality use, generating demand for triple-glazed and thermally broken systems that meet current energy codes without structural replacement.
- Renovation:Selective facade replacement in existing commercial stock addresses localized failure while preserving structurally sound envelope components.
- Prefabricated:Off-site panel assembly reduces site labor exposure and accelerates envelope closure for schedule-constrained hospitality projects.
New Construction holds the largest share; Retrofitting shows the strongest momentum as Qatar advances event legacy asset conversions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamad International Airport expansion and Lusail Light Rail transit corridor anchor Qatar's facade demand geography, connecting Doha's commercial core to new development clusters across the peninsula.
Doha
West Bay's high-rise commercial towers and the Doha Corniche hospitality corridor concentrate specification activity for triple-glazed unitized systems. The Ministry of Municipality and Environment enforces thermal transmittance disclosure mandates for envelope assemblies exceeding 10,000 square meters. Electrochromic glazing procurement is accelerating along the waterfront as developers eliminate external shading hardware.
Lusail
The planned city's mixed-use districts and premium residential clusters generate concentrated demand for metal cladding and ventilated facade systems. GSAS sustainability ratings administered by the Gulf Organization for Research and Development pull composite panel specifications into hospitality and commercial assets. Design-build envelope contracts are consolidating procurement under single-source responsibility.
Al Wakrah
Industrial zone expansion and logistics facility construction sustain stable demand for cost-predictable metal panel systems. Thermal performance requirements remain less stringent than commercial mandates, favoring aluminum extrusion and single-skin applications. Coastal salinity conditions drive specification toward corrosion-resistant coating systems.
Al Khor
North-east development corridors and energy sector facility construction generate intermittent demand for high-durability envelope systems. Legacy industrial infrastructure upgrades are introducing insulated panel specifications where energy efficiency retrofits align with operational cost reduction targets. Fabrication capacity from Doha-based suppliers extends service coverage through dedicated logistics arrangements.
Qatar Facade Market Competitive Landscape
On the supply side, the industry is consolidating around fabrication-capable specialists with in-house metal processing and unitized system engineering competencies. The vendor base clusters into three strategic archetypes: integrated fabricators controlling extrusion and coating operations, engineering-focused system designers, and installation-specialized contractors. Competitive positioning depends on backward integration into aluminum supply and pre-qualification status for design-build envelope contracts.
Among Doha-based integrated fabricators, Qatar Meta Coats W.L.L (QMC) and Everest Aluminum Co WLL occupy positions anchored by captive metal fabrication capabilities. Bemo International represents the engineering-specialist archetype, with system design competencies concentrated in high-rise commercial applications. These three entities exemplify the capability thresholds required for stadium-scale and museum contract access, where qualification timelines and thermal modeling expertise create defensive barriers against new entrant expansion.
| Leading Market Players |
|---|
| Qatar Meta Coats W.L.L (QMC) |
| Alce Engineering Qatar WLL |
| Bemo International |
| Everest Aluminum Co WLL |
| Norwood Qatar LLC |
| Alutec |
| Aluglass Co Ltd |
| Alumasa Qatar |
| Sollass Alu & Glass |
| Others |
Value Network & Pricing Analysis
Doha-based fabrication clusters anchor Qatar's facade supply base, concentrating extrusion capacity and coating operations among a handful of integrated suppliers whose captive metal processing translates into pricing power over project-specific contracts. Main contractors absorb aluminum price volatility through design-build arrangements, passing cost uncertainty downstream to specialist subcontractors or buffering through long-term offtake agreements with Doha-based mills.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates electrochromic and triple-glazed specifications for West Bay commercial towers from conventional unitized systems and basic metal cladding for industrial zones. Price differentiation hinges on GSAS certification grade and thermal transmittance performance, with hospitality developers along the Doha Corniche absorbing premiums for dynamic glazing while industrial facilities in Al Wakrah prioritize cost predictability. Pricing pressure stems from primary aluminum input cost fluctuations tied to energy pricing, compressing margins for extrusion-dependent contractors. Industrial facility buyers exhibit highest price sensitivity, whereas mixed-use tower developers in Lusail accept premium engineering costs to secure municipal permits.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard procurement tools as main contractors manage cash flow across compressed qualification timelines for imported glazing systems. Primary aluminum draws from Bahrain, the UAE, and Saudi Arabia, with high-performance glass and thermally broken framing components sourced from European and East Asian manufacturers. Supply chain risk centers on single-source vulnerability for electrochromic glazing substrates and specialized coating chemistries. Distribution runs through main contractor-led design-build contracts that consolidate envelope responsibility, reducing interface coordination but concentrating supplier qualification barriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's facade market sits in early-cycle recovery as event legacy asset conversions and Lusail build-out reactivate project pipelines after post-event construction lulls. Contracting volumes follow hospitality and commercial tower development schedules tied to national diversification targets.
For Market Incumbents: Entrench fabrication capabilities through backward integration into aluminum supply and thermal modeling talent acquisition, defending against engineering-specialist competitors like Bemo International. Pre-qualification status for GSAS-certified envelope contracts represents the critical defensive moat. Capacity addition in Lusail's mixed-use districts secures proximity to fastest-growing demand clusters.
For New Entrants and Emerging Players: Al Khor's energy sector facility construction and legacy industrial retrofit pipeline offer underpenetrated entry points where thermal performance requirements remain less stringent than commercial mandates. Prefabricated panel assembly for schedule-constrained hospitality projects represents the most penetrable application segment. Direct developer contracting channels bypass main contractor roster barriers established in Doha and Lusail.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated fabricators with captive extrusion and unitized system engineering competencies over pure-play installation contractors. Long-term viability rests on GSAS sustainability rating alignment and thermal performance code compliance capability. Watch electrochromic glazing adoption rates in West Bay hospitality assets as inflection indicator for premium specification penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of precision-extruded profiles reduces cost volatility exposure for Doha-based fabricators. |
| GSAS Certification Investment | Embodied carbon disclosure compliance unlocks specification access for Lusail mixed-use hospitality contracts. |
| Electrochromic Glazing Partnership | Technology licensing agreements with European substrate suppliers accelerate dynamic glazing deployment for Corniche towers. |
| Design-Build Contract Pre-Qualification | Single-source envelope responsibility reduces interface risk for main contractors consolidating Lusail procurement. |
| Thermal Modeling Talent Acquisition | Computational fluid dynamics expertise addresses engineering scarcity constraining high-performance glazing design capacity. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with facade contractors, glazing system specifiers, and Ministry of Municipality and Environment compliance officers; and secondary validation through Qatar Chamber of Commerce construction sector reports, GSAS sustainability rating databases, and customs records for aluminum and glass imports. Bottom-up project pipeline aggregation across West Bay, Lusail, and Al Wakrah development zones was cross-checked against top-down market sizing from contractor revenue disclosures and procurement contract announcements.
Forecast inputs span product type segmentation across glass, metal, composite, and stone systems; application segmentation across commercial, hospitality, residential, and industrial end-uses; technology segmentation across ventilated, unitized, curtain wall, and traditional systems; and installation type segmentation across new construction, retrofitting, renovation, and prefabricated deployment. CAGRs were derived from project-level specification tracking and thermal performance mandate implementation timelines. Aluminum price trajectory assumptions and GSAS rating adoption curves served as industry-specific forecast inputs.
Practitioners should monitor aluminum energy input cost movements, GSAS disclosure requirement expansion, and electrochromic glazing technology cost curves for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Cladding Market
Building Materials
Rubbing Bricks Market
Building Materials
Bolt (Fastener) Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
US Contract Glazing Market
Building Materials
Construction Glass Market
Building Materials
North America Construction Aggregates Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Fiber Cement Market
Building Materials
Malaysia Architectural Coatings Market
Building Materials
Composite Rebar Market
Building Materials
Foam Bricks Market
Building Materials
North America Cement Market
Building Materials
India Aluminum Door and Window Market