
 Facade Gasket Market | 2026-2036
Facade Gasket Market Size, Share, and Industry Trends Forecast 2026-2036
Facade Gasket Market Analysis
ISO 9001 and ASTM C864 qualification cycles is bifurcating the supplier landscape between certified system integrators and commodity extruders. Trelleborg AB leverages its polymer compounding expertise to anchor premium silicone gasket lines for curtain wall projects. Freudenberg Sealing Technologies sustains R&D intensity across multi-material bonding systems. Parker Hannifin Corporation dominates pneumatic-actuated installation tooling that accelerates field deployment.
A facade gasket is a compressible sealing element, typically extruded from EPDM, silicone, or neoprene compounds with Shore A hardness between 40 and 70, designed to accommodate thermal movement and prevent air and moisture infiltration at building envelope joints. Its primary purpose is maintaining pressure-equalized rainscreen performance while reducing HVAC energy loads through controlled air leakage. EPDM formulations occupy the volume core due to cost-efficiency in standard commercial buildings, while silicone segments command margin pools in high-performance facades requiring UV stability across extreme temperature cycles. Custom-cut installation methods are gaining traction in retrofit applications where existing substrate tolerances demand field-adapted solutions.
The EU Green Deal and REACH chemical compliance frameworks in Europe, alongside ASHRAE 90.1 and IECC adoption cycles in the United States, are tightening thermal bridging limits and mandating blower-door performance verification. These regulations are elevating specification requirements for gasket compression set resistance and accelerated aging certification. Stakeholders must monitor evolving code harmonization between national energy standards and local fire-safety amendments that increasingly restrict halogenated compound use in facade assemblies.
Market Dynamics
Curtain wall retrofit cycles in high-rise commercial buildings are compressing specification timelines as ASHRAE 90.1 and EU Green Deal thermal envelope mandates force simultaneous energy audits and gasket replacement decisions.
Growth Catalysts
- EPDM cost-efficiency:Standard commercial buildings in Germany and the United States specify EPDM formulations for baseline thermal performance, anchoring volume demand across mid-rise office stock.
- EU Green Deal enforcement:REACH chemical compliance frameworks in Europe mandate accelerated aging certification, elevating specification barriers and filtering out uncertified commodity suppliers.
- Shanghai Pudong corridor:High-rise density in this cluster generates concentrated demand for silicone gasket systems rated for extreme temperature cycling and UV stability.
Market Restraints
- Silicone feedstock volatility:Silicon metal price swings and energy-intensive polymerization constrain margin predictability for premium gasket lines.
- Supplier concentration risk:ISO 9001 and ASTM C864 qualification cycles bifurcate the landscape between certified system integrators and commodity extruders, limiting buyer choice.
- Halogenated compound restrictions:Local fire-safety amendments increasingly restrict chlorinated and brominated additives in facade assemblies, forcing formulation reformulation costs.
Strategic Opportunities
- New York metropolitan retrofit wave:Aging curtain wall stock and Local Law 97 carbon caps create white space for custom-cut installation methods adapted to substrate tolerance variation.
- Multi-material bonding convergence:Hybrid gasket-to-frame adhesion systems combining silicone compression seals with structural tapes open specification in unitized curtain wall projects.
- Digital specification platforms:Building information modeling integration allows gasket suppliers to embed thermal performance data directly into architect workflows, bypassing traditional distributor channels.
Industry Challenges
- Field technician certification gaps:Proper installation of pressure-equalized rainscreen systems requires trained crews familiar with compression set tolerances, and qualified labor pools remain thin in secondary markets.
- ASTM C864 testing backlog:Accelerated aging and compression set resistance verification cycles stretch 12-18 months, delaying product launches and locking working capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facade Gasket Market |
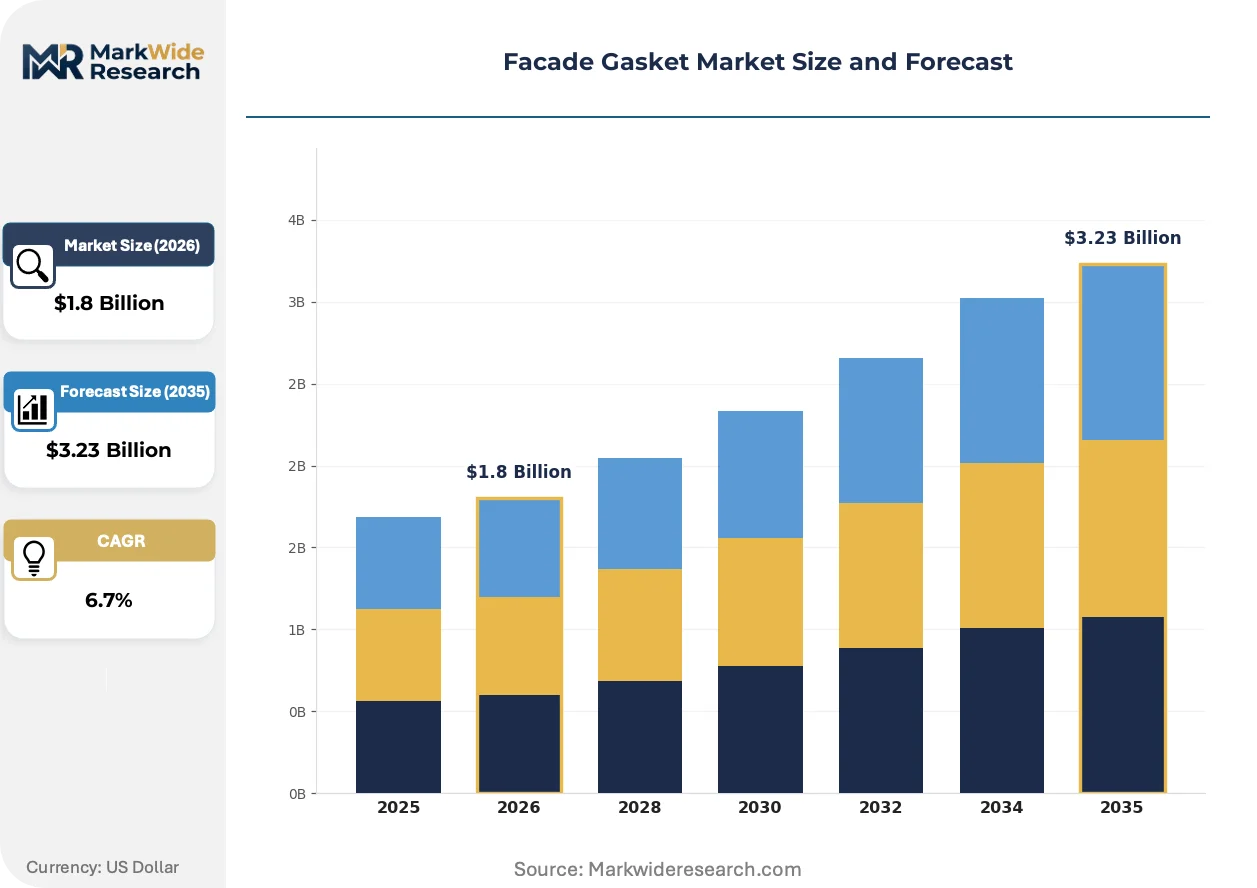
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPDM, PVC, Silicone, Neoprene Application: Commercial Buildings, Residential Towers, Industrial Facilities, Retail Outlets Material: Rubber, Polyurethane, Metal, Plastic Installation Method: Pre-formed, Custom-cut, Continuous, Modular |
| Companies Covered | Parker Hannifin Corporation, Garlock Sealing Technologies, Trelleborg AB, Gates Corporation, Semperit AG Holding, Freudenberg Sealing Technologies, ElringKlinger AG, LOPO International Limited, Cooper Standard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facade Gasket Market Emerging Trajectories
Thermal bridging mitigation is forcing gasket technology toward tighter integration with building envelope modeling software and predictive performance validation.
Co-extruded dual-durometer profiles combining rigid EPDM substrates with soft silicone sealing lips are miniaturizing joint tolerances while maintaining movement accommodation. High-performance facade consultants in Frankfurt's financial district specify these systems for projects requiring simultaneous air barrier and thermal break performance. The technology is compressing traditional two-component gasket assemblies into single-installation solutions, reducing field labor hours.
REACH chemical compliance frameworks in Europe are restricting phthalate plasticizers and certain sulfur cure accelerators in EPDM compounds. Compounders reformulate with bio-based process oils and peroxide cure systems to maintain Shore A hardness specifications. Silicone gasket lines face parallel scrutiny under evolving Substances of Very High Concern candidate list expansions, accelerating R&D migration toward platinum-catalyzed addition cure chemistries.
Architects now specify blower-door performance verification as a contract deliverable rather than a code minimum, shifting risk to gasket suppliers and installers. This compresses payment terms and forces upfront investment in third-party testing partnerships. The pattern is most visible in German commercial projects pursuing Passive House certification and in New York Local Law 97 compliance pathways.
Facade Gasket Market Segmentation
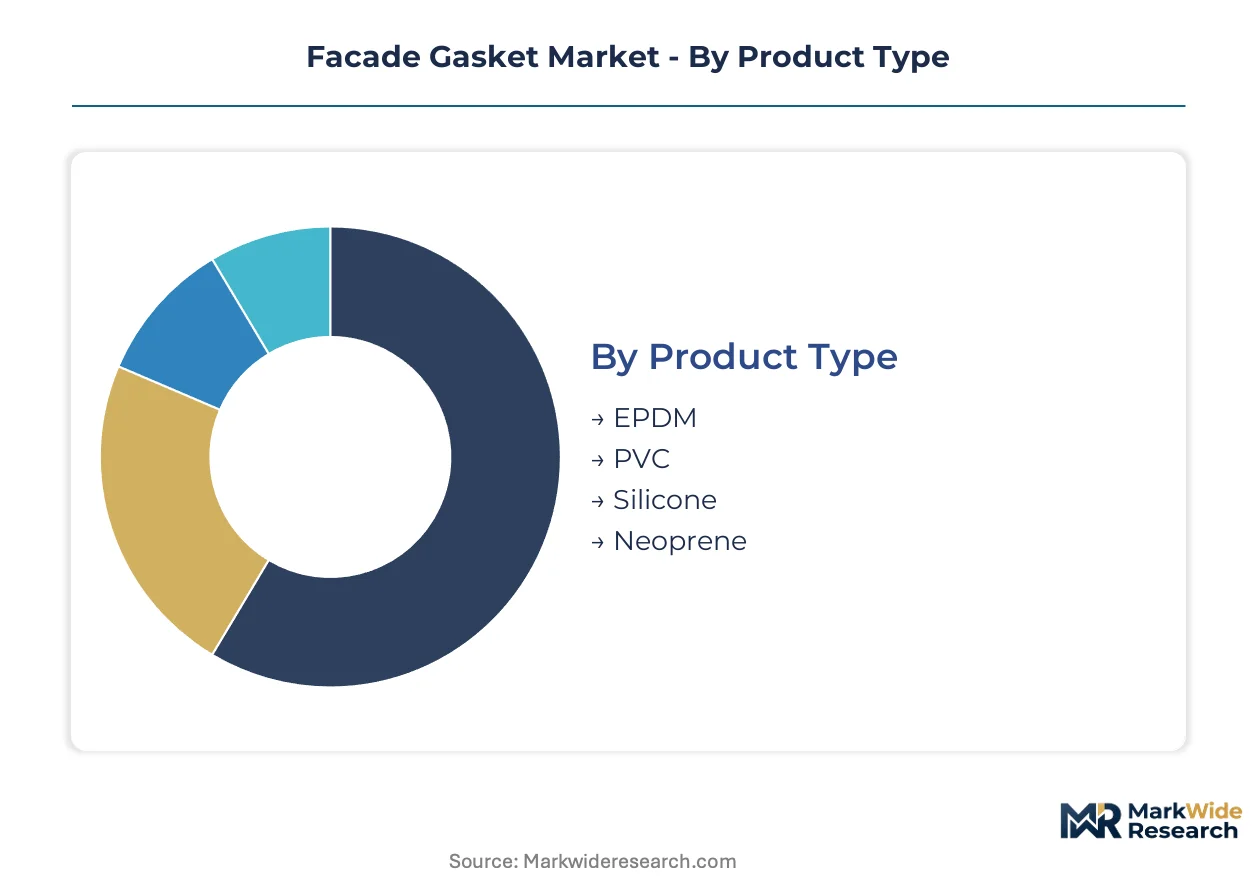
Segmentation in the facade gasket market reveals how material chemistry, installation logistics, and end-use thermal requirements create distinct procurement channels. Specification engineers select gasket systems based on compression set tolerance, substrate compatibility, and regulatory compliance pathways rather than commodity pricing alone.
Product Type:
EPDM and silicone formulations dominate export-led supply chains serving high-performance facade projects across Germany, the United States, and China, while PVC and neoprene lines concentrate in domestic construction markets with shorter specification cycles.
- EPDM:Ethylene-propylene-diene terpolymer compounds deliver Shore A hardness between 40 and 70 with superior compression set resistance for standard commercial buildings. Procurement concentrates in German mid-rise office stock and U.S. ASHRAE 90.1 compliance retrofits where cost-efficiency anchors volume demand.
- Silicone:Platinum-catalyzed addition cure systems provide UV stability across extreme temperature cycles from minus 40°C to 200°C. Shanghai's Pudong corridor and Frankfurt's financial district specify these formulations for high-rise curtain walls where thermal bridging limits are tightest.
- PVC:Plasticized polyvinyl chloride profiles serve budget-sensitive residential and retail applications with moderate movement accommodation requirements.
- Neoprene:Chloroprene-based compounds offer oil and chemical resistance for industrial facility envelope joints exposed to process effluent or maintenance solvents.
EPDM holds the largest share; momentum sits with silicone as EU Green Deal thermal envelope mandates tighten.
Application:
Commercial building specifications command premium pricing tiers due to blower-door performance verification requirements, while residential and industrial segments operate on faster procurement cycles with standardized gasket dimensions.
- Commercial Buildings:Curtain wall retrofits in New York's metropolitan area and Local Law 97 carbon cap compliance drive demand for custom-cut silicone systems with documented air leakage rates below 0.4 cfm per square foot at 75 Pascals.
- Residential Towers:High-rise multifamily construction in secondary U.S. markets and German urban centers specifies EPDM pre-formed profiles for cost-controlled thermal envelope performance.
- Industrial Facilities:Manufacturing plants and logistics warehouses prioritize neoprene and polyurethane formulations resistant to chemical exposure and mechanical abrasion.
- Retail Outlets:Big-box and strip mall construction utilizes PVC and standard EPDM extrusions with rapid field installation timelines.
Commercial buildings generate the highest value per project; residential towers deliver the steepest expansion trajectory through urban densification policies.
Material:
Rubber compounds anchor volume production through established extrusion infrastructure, while metal and plastic alternatives penetrate niche applications requiring structural integration or aesthetic concealment.
- Rubber:EPDM, silicone, and neoprene elastomers constitute the functional core of pressure-equalized rainscreen systems, with compounders in Germany and the United States maintaining ISO 9001 certified production lines for REACH and ASTM C864 compliance.
- Polyurethane:Cast and thermoplastic urethane gaskets serve expansion joint applications requiring higher tear strength and abrasion resistance than standard rubber formulations.
- Metal:Aluminum and stainless steel carrier strips provide structural backing for compression seals in unitized curtain wall systems.
- Plastic:Thermoplastic elastomer and rigid PVC components integrate with glazing beads and snap-in retention profiles for modular installation methods.
Rubber commands the dominant material share; polyurethane is climbing the fastest through hybrid bonding system convergence.
Installation Method:
Pre-formed and continuous extrusion methods suit new construction with controlled substrate tolerances, while custom-cut and modular approaches expand in retrofit markets where field adaptation compensates for existing facade irregularities.
- Pre-formed:Factory-extruded profiles in standard lengths and corner moldings reduce field labor for new curtain wall installations with documented substrate dimensions.
- Custom-cut:Field-measured and cut gasket segments address tolerance variation in aging curtain wall stock across New York's pre-1990 high-rise inventory, requiring trained technician crews and pneumatic-actuated tooling.
- Continuous:Extruded-in-place silicone systems create monolithic seals for complex geometries and irregular joint widths in high-performance facade projects.
- Modular:Clip-in gasket cartridges and snap-fit profiles accelerate replacement cycles in retail and industrial facilities with standardized framing systems.
Pre-formed methods retain the largest installed base; custom-cut approaches are gaining share fastest through accelerated retrofit mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and evolving ASHRAE standards are compressing retrofit timelines across major commercial corridors. Building envelope codes now mandate documented air leakage performance, forcing simultaneous gasket replacement and energy audit decisions in high-rise districts.
United States
New York's metropolitan area drives concentrated demand for custom-cut silicone gasket systems. Local Law 97 carbon caps accelerate curtain wall retrofits in pre-1990 high-rise inventory. ASHRAE 90.1 adoption cycles across multiple states elevate specification requirements for blower-door verification below 0.4 cfm per square foot at 75 Pascals.
Germany
Frankfurt's financial district specifies co-extruded dual-durometer profiles combining rigid EPDM substrates with soft silicone sealing lips. REACH chemical compliance frameworks restrict phthalate plasticizers in EPDM compounds, forcing reformulation with bio-based process oils. Mid-rise office stock in Berlin and Munich anchors volume demand for cost-efficient EPDM formulations.
China
Shanghai's Pudong corridor generates concentrated procurement of platinum-catalyzed silicone gasket systems rated for extreme temperature cycling. Dual carbon goals and tightening GB standards for commercial building energy efficiency compress specification timelines. High-rise density in this cluster demands UV-stable formulations across minus 40°C to 200°C operating ranges.
United Kingdom
London's commercial retrofit wave responds to MEES regulations and evolving Part L conservation standards. Building owners face simultaneous pressure from carbon reduction targets and facade fire-safety amendments restricting halogenated compounds. The Southeast corridor concentrates demand for certified system integrators capable of ASTM C864-compliant documentation.
Japan
Tokyo's high-rise commercial district specifies silicone gasket lines for seismic movement accommodation and thermal bridging mitigation. METI energy efficiency standards and JIS certification requirements filter out uncertified commodity suppliers. Osaka's urban renewal projects generate parallel demand for pressure-equalized rainscreen systems in mixed-use developments.
Facade Gasket Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, creating a bifurcated supplier landscape. ISO 9001 and ASTM C864 qualification cycles concentrate premium specification access among certified system integrators while commodity extruders serve budget-sensitive segments. Three archetypes dominate: polymer compounders leveraging material science expertise, sealing specialists with multi-material bonding capabilities, and pneumatic tooling providers accelerating field deployment. Competitive moves center on R&D intensity for REACH-compliant formulations and strategic partnerships with facade consultants embedding products into BIM workflows.
Within the polymer compounding tier, Trelleborg AB and Freudenberg Sealing Technologies exemplify material science-led positioning. Trelleborg anchors premium silicone gasket lines through Swedish polymer expertise, while Freudenberg occupies a parallel position in multi-material bonding systems. Parker Hannifin Corporation represents the tooling-centric archetype, with pneumatic-actuated installation equipment compressing field labor hours in retrofit applications. These three players collectively illustrate how certification barriers and technical specialization stratify competitive access across specification tiers.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Garlock Sealing Technologies |
| Trelleborg AB |
| Gates Corporation |
| Semperit AG Holding |
| Freudenberg Sealing Technologies |
| ElringKlinger AG |
| LOPO International Limited |
| Cooper Standard |
| Others |
Supply Flow & Price Mechanics
Extrusion capacity utilization at German and Chinese polymer compounders shapes price floors across certified and commodity gasket tiers, concentrating margin power among ISO 9001-qualified integrators while forcing smaller extruders toward undifferentiated EPDM volume plays.
Pricing Analysis
Certification level creates the primary spread between ASTM C864-qualified system integrators and uncertified commodity suppliers. Three-tier pricing structure across premium silicone, standard EPDM, and economy PVC levels reflects compression set performance and REACH compliance documentation. Pricing pressure stems from silicon metal feedstock volatility and energy-intensive polymerization costs in premium silicone lines. Budget-sensitive retail and residential segments exhibit highest price sensitivity, while commercial building developers pursuing Local Law 97 or Passive House certification absorb premium tiers for documented blower-door performance.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes and port congestion at Hamburg and Shanghai anchor inbound logistics costs for silicone raw materials and specialty polymer additives. Supply concentrates in Germany for EPDM compounding expertise, China for silicone polymerization capacity, and the United States for pneumatic tooling integration. Raw material dependencies include silicon metal, ethylene-propylene monomers, and platinum catalysts for addition cure systems. Single-source vulnerability in silicon metal refining creates structural risk. Distribution runs through facade consultant-specified channels and building information modeling platforms that embed thermal performance data directly into architect workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against liquid-applied membrane and structural tape systems that displace traditional compression gaskets in unitized curtain wall projects.
For Market Incumbents: Shield specification access by deepening ASTM C864 certification pipelines and embedding products into BIM workflows before structural tape suppliers capture architect mindshare. Prioritize backward integration into platinum-catalyzed silicone polymerization to offset feedstock volatility. Acquire field technician training capabilities to differentiate on installation quality where labor pools remain thin. For New Entrants and Emerging Players: Anchor in New York's pre-1990 high-rise retrofit wave where custom-cut installation methods address substrate tolerance variation that incumbent pre-formed suppliers cannot easily serve. Target pneumatic-actuated tooling partnerships to compress field deployment hours. Pursue white-label supply agreements with certified system integrators lacking in-house compounding capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with REACH-compliant formulation libraries and established blower-door testing partnerships. Long-term viability hinges on regulatory compliance moats rather than raw material scale. Acquisition targets include regional extruders with ASTM C864 qualification pathways in progress. Monitor EU Green Deal enforcement intensity and Substances of Very High Concern list expansions as inflection indicators for formulation R&D spending requirements.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Migration | Peroxide cure systems and bio-based process oils replace restricted phthalate plasticizers in EPDM compounds. |
| BIM Platform Integration | Embedding thermal performance data into architect workflows bypasses traditional distributor channels. |
| Custom-Cut Installation Capability | Field-adapted solutions capture New York retrofit demand from aging curtain wall stock. |
| Pneumatic Tooling Partnership | Parker Hannifin-style installation equipment compresses labor hours in secondary markets. |
| Dual-Durometer Co-Extrusion Scale-Up | Frankfurt financial district specifications drive single-installation solutions replacing two-component assemblies. |
Methodological Framework
A standing panel of facade consultants, curtain wall system engineers, building envelope commissioning agents, and polymer compounder technical directors provided ongoing calibration across primary interview cycles. Secondary validation drew from ASTM International standard documentation, REACH substance restriction updates, ASHRAE 90.1 adoption tracking, and customs data on silicone polymer trade flows. Bottom-up project pipeline analysis across New York, Frankfurt, and Shanghai construction permits was triangulated against top-down spending estimates from commercial real estate investment databases.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated material chemistry tiers, installation method complexity, end-use thermal performance requirements, and regional regulatory framework clusters. CAGRs were derived from fitted growth curves calibrated to documented retrofit cycle compression and energy code adoption timelines. Industry-specific inputs included blower-door verification penetration rates and REACH compliance cost pass-through estimates.
Material uncertainties — silicon metal price volatility, EU Green Deal enforcement intensity shifts, and local fire-safety amendment trajectories — sit outside the modeled envelope. Forecasts reflect assumptions about certification barrier stability and specification timeline compression. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Malaysia Architectural Coatings Market
Building Materials
Blended Cement Market
Building Materials
Italy Facade Market
Building Materials
Europe Cement Market
Building Materials
Polymer Concrete Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
US Cement Tiles Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Global Building Panels Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Refractory Cement Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
Construction Glass Market