
 Europe Concealed Cistern Market | 2026-2036
Europe Concealed Cistern Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Concealed Cistern Market Insights
Commercial hospitality is rebalancing toward premium wall-hung installations as hotel chains across Spain and Italy prioritize space efficiency. Geberit AG leverages its Swiss manufacturing base to sustain pan-European distribution dominance. Grohe AG anchors its position through intensive R&D in sensor-integrated flushing systems. Viega Group competes aggressively in prefabricated bathroom modules for large-scale German residential developers.
A concealed cistern is a water-flushing reservoir installed within wall cavities or furniture units, typically constructed from high-density polyethylene or ceramic-composite materials, designed to operate at 3-6 litre dual-flush volumes while maintaining acoustic insulation below 20 decibels. Dual flush systems lead product type demand as water-utility tariffs tighten across EU member states, while smart cisterns represent the fastest-growing segment driven by IoT-enabled leak detection and usage analytics. Wall-hung installation dominates new European construction, though prefabricated modules capture expanding share in modular hotel and student-housing projects where offsite manufacturing compresses build schedules.
EU Ecodesign regulations and the F-Gas Regulation indirectly shape material specifications and insulation standards for concealed cistern assemblies, while national building codes in France and Germany enforce specific acoustic and leak-test certifications. REACH compliance governs polymer and sealant chemistry across all imported and domestically manufactured units. Stakeholders must monitor evolving EU water-label criteria and national green-building certification schemes to anticipate procurement specification shifts before they harden into mandatory requirements.
Market Dynamics
EU Green Deal water-efficiency mandates are compressing flush-volume specifications across member states, forcing manufacturers to re-engineer dual-flush mechanisms while maintaining acoustic performance below 20 decibels. This regulatory pressure is restructuring R&D priorities and supplier qualification criteria simultaneously.
Growth Catalysts
- Hospitality Retrofit Cycles:Hotel chains across Germany and France are accelerating replacement timelines as ESG reporting requirements tighten water-intensity disclosures.
- REACH-Compliant Polymer Innovation:High-density polyethylene formulations meeting ECHA sealant chemistry standards are unlocking prefabricated bathroom module adoption.
- Urban Space Constraints:Western European city centers are mandating wall-hung installations in new construction to maximize floor area ratios.
Market Restraints
- Ceramic-Composite Input Volatility:Specialized mineral supply concentration in Southern Europe creates cost unpredictability for premium cistern housings.
- F-Gas Regulation Compliance Burden:Insulation foam chemistry reformulation extends product certification timelines by 8-14 months.
- Acoustic Testing Infrastructure Bottlenecks:Limited certified laboratories in France and Germany throttle new entrant market access.
Strategic Opportunities
- Modular Student Housing:Offsite construction demand in the Netherlands and Belgium is creating specification pull for pre-integrated cistern-furniture systems.
- IoT-Enabled Leak Detection:Sensor-integrated smart cisterns are penetrating luxury residential segments in Switzerland and Austria.
- EU Water Label Anticipation:Early alignment with evolving efficiency grading schemes positions suppliers for mandatory procurement preference.
Industry Challenges
- Dual-Certification Skill Scarcity:Engineers fluent in both acoustic insulation and smart sensor integration command premium compensation.
- Legacy Plumbing Interface Standardization:Incompatible connection geometries across national markets fragment production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Concealed Cistern Market |
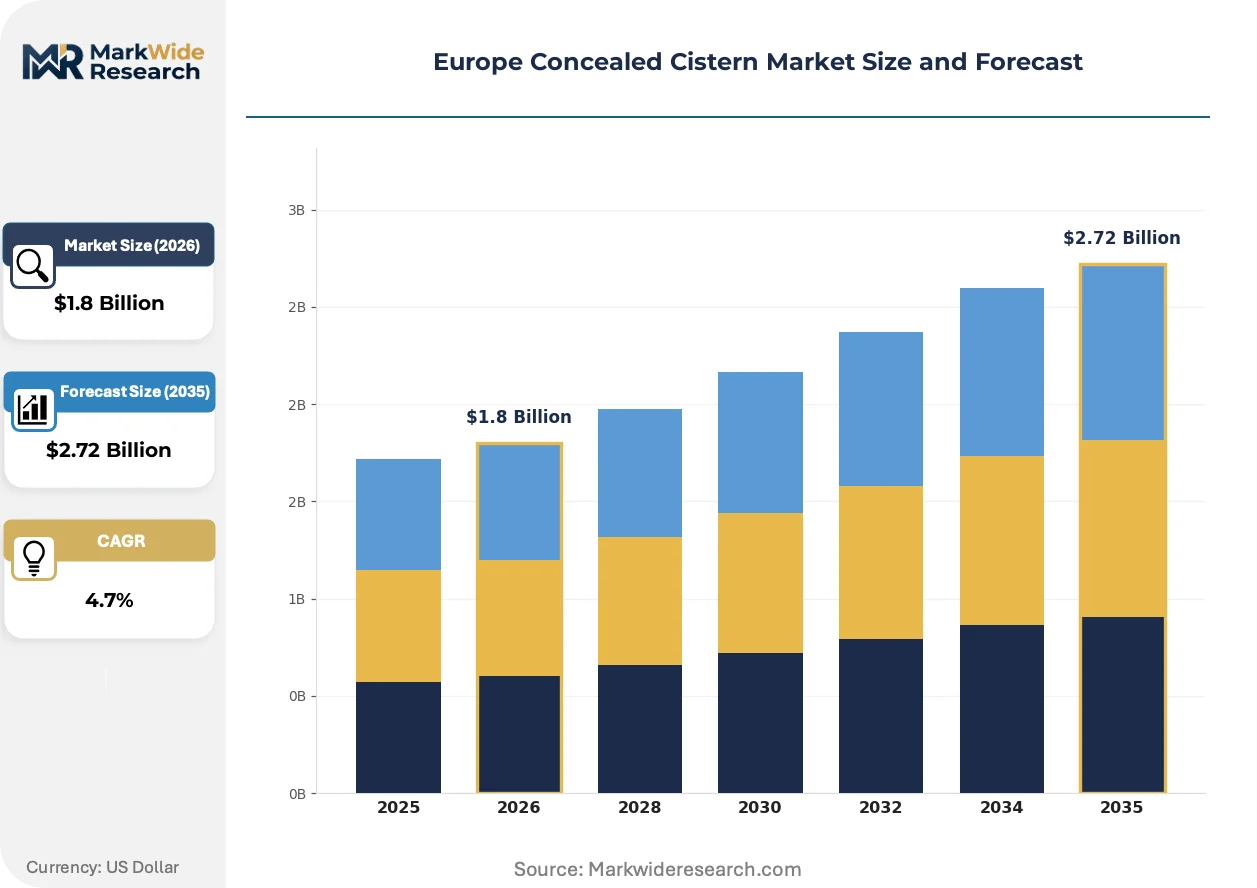
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Flush, Single Flush, Instant Fill, Smart Cisterns End User: Residential, Commercial, Hospitality, Industrial Installation Type: Wall-Hung, Floor-Mounted, Prefabricated, Customized Distribution Channel: Online Retail, Home Improvement Stores, Plumbing Supply, Distributors |
| Companies Covered | Geberit AG, Grohe AG, Viega Group, Siamp, Wirquin Group, TECE GmbH, Roca Sanitario SA, Ideal Standard International, Villeroy & Boch AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Concealed Cistern Market Trends and Innovations
Concealed cistern technology is converging with building automation and sustainable materials science, compressing product development cycles while expanding addressable applications. Three distinct trajectories are redefining competitive capability requirements.
Sensor-integrated flushing systems are integrating pressure-sensitive actuation with cloud-connected usage analytics. Boutique hotel operators in Spain and Italy are specifying these units at triple the rate of conventional mechanical alternatives. The technology is integrating facility management software with water-utility billing systems, enabling real-time consumption monitoring.
EU Ecodesign regulations are tightening minimum efficiency thresholds for sanitary ware assemblies. Manufacturers must now document lifecycle water consumption across dual-flush actuation cycles. German residential developers are responding by mandating 3-litre single-flush configurations in new-build specifications.
Specification authority is migrating from general contractors to facilities management platforms. Large-scale hospitality operators in France are consolidating procurement through centralized technical standards teams. This pattern concentrates vendor qualification decisions within a narrowing buyer pool.
Europe Concealed Cistern Market Segmentation
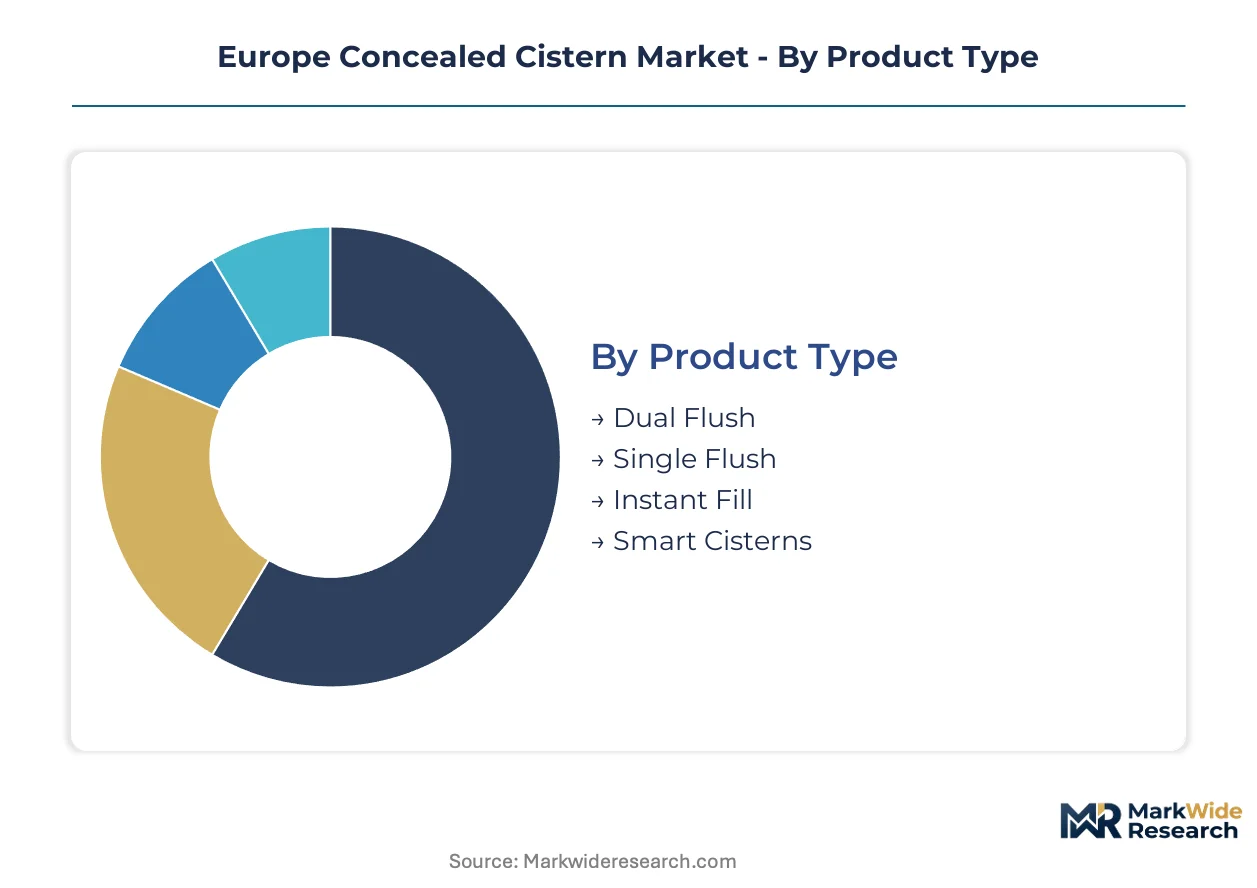
Concealed cistern procurement decisions in Europe diverge sharply across building typologies and regulatory environments. Specification authority concentrates in distinct buyer pools for each segment, reshaping how manufacturers configure product portfolios and channel investments.
Product Type:
Supply concentration in polymer formulation capabilities favors manufacturers with captive high-density polyethylene production in Germany and Switzerland.
- Dual Flush:Mechanisms deliver 3-6 litre selectable volumes through dual-button or dual-lever actuation, with acoustic insulation below 20 decibels mandatory for German and French certification. Demand clusters in Western European urban residential retrofits where EU water-efficiency mandates tighten utility tariffs. REACH-compliant sealant chemistry from ECHA-registered suppliers determines vendor qualification timelines.
- Smart Cisterns:IoT-enabled units integrate pressure sensors, leak detection algorithms, and cloud-connected usage analytics accessible through facility management platforms. Boutique hotel operators in Spain and Italy specify these at triple the rate of mechanical alternatives, driven by ESG water-intensity disclosure requirements. Swiss and Austrian luxury residential developers embed them in high-specification bathroom pods.
- Single Flush:Fixed-volume systems dominate cost-sensitive public housing specifications in Eastern Europe.
- Instant Fill:Rapid-refill mechanisms serve high-traffic commercial restrooms in French transport hubs and German office complexes.
Dual Flush absorbs the bulk of installed capacity; Smart Cisterns is expanding most quickly.
End User:
Cost tier differentiation separates specification committees with centralized technical standards from decentralized procurement.
- Hospitality:Hotel chains across Germany and France consolidate procurement through ESG-mandated water-intensity reduction programs. Wall-hung installations dominate new-build specifications, while retrofit cycles accelerate replacement timelines. Chains in Spain and Italy prioritize sensor-integrated systems for premium positioning.
- Commercial:Office developers in the Netherlands and Belgium specify prefabricated bathroom modules to compress construction schedules. Facility management platforms increasingly control vendor qualification, narrowing the buyer pool to qualified suppliers with pan-European service networks.
- Residential:German developers mandate 3-litre configurations in new-build specifications under tightened EU Ecodesign thresholds.
- Industrial:Manufacturing facilities in Poland and Czechia prioritize durability and minimal maintenance intervals.
Hospitality commands premium pricing tiers; Commercial is gaining share fastest in volume terms.
Installation Type:
Volume concentration in modular construction methods is displacing traditional on-site assembly.
- Wall-Hung:Installations maximize floor area ratios in Western European urban cores where space-optimized bathroom design dominates new construction. French and German building codes enforce specific acoustic and leak-test certifications, creating compliance barriers for non-specialized suppliers. The format enables concealed plumbing and simplified cleaning protocols valued in hospitality settings.
- Prefabricated:Offsite-manufactured bathroom modules integrate cisterns, furniture, and finishes in factory-controlled conditions. Dutch and Belgian student housing developers specify these systems to accelerate build schedules and reduce on-site labor dependencies. German residential developers adopt prefabrication for large-scale projects with standardized unit configurations.
- Floor-Mounted:Traditional configurations persist in heritage building renovations across Italy and Portugal.
- Customized:Bespoke solutions serve luxury residential and boutique hospitality projects in Switzerland and Monaco.
Wall-Hung retains the largest installed base; Prefabricated is climbing the fastest as modular construction scales.
Distribution Channel:
Customer type fragmentation separates project-scale procurement from replacement and renovation demand.
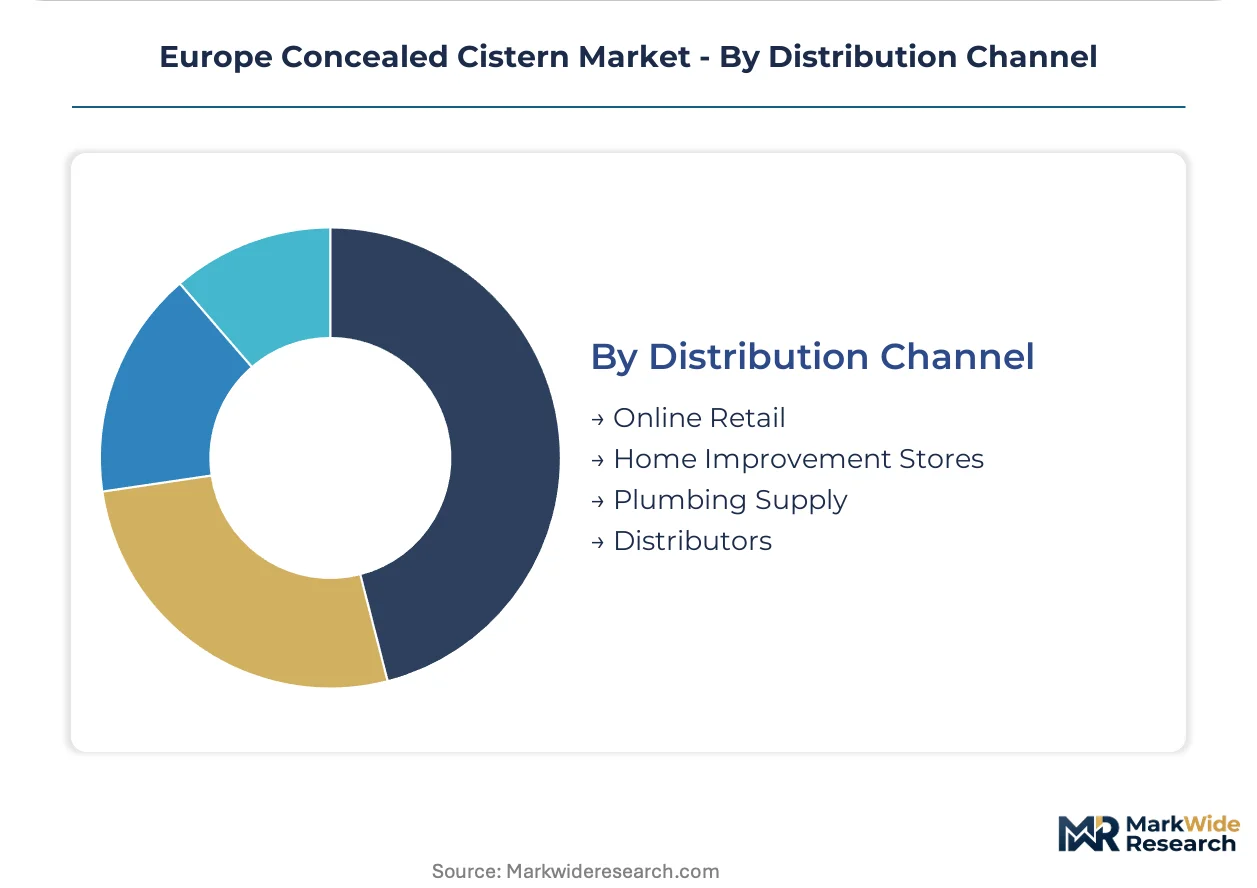
- Plumbing Supply:Specialized distributors dominate commercial and hospitality specification through relationships with facilities management platforms and technical standards teams. French and German markets concentrate vendor qualification decisions within narrowing buyer pools. These channels provide installation support and compliance documentation required for building permit approvals.
- Distributors:Pan-European networks serve large-scale developers with consolidated procurement and logistics coordination. German residential developers leverage distributor relationships for just-in-time delivery to construction sites. REACH compliance documentation and acoustic certification records flow through these channels.
- Home Improvement Stores:Retail networks capture residential renovation demand in suburban and exurban markets.
- Online Retail:Digital channels penetrate replacement part sales and standardized residential configurations.
Plumbing Supply channels handle the majority of project value; Distributors are expanding most quickly through developer consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan zone concentrates German manufacturing capacity for concealed cistern systems. France's Grand Est region anchors cross-border supply chain coordination with Swiss and German component suppliers.
Germany
Hotel retrofit programs in Berlin and Munich accelerate replacement cycles for wall-hung installations. The EU Green Deal's water-efficiency mandates compress flush-volume specifications to 3-litre single-flush configurations. North Rhine-Westphalia hosts prefabricated bathroom module production serving Dutch and Belgian developers.
France
Boutique hotel operators in Paris and Lyon specify sensor-integrated smart cisterns at triple the rate of mechanical alternatives. ANSM and CNIL oversight shapes data governance for IoT-enabled leak detection systems. The Grand Est region coordinates acoustic testing certification with German laboratory networks.
Netherlands
Modular student housing developers in Amsterdam and Rotterdam drive prefabricated cistern-furniture system demand. REACH compliance documentation flows through pan-European distributor networks anchored in Randstad logistics hubs. Eindhoven Region suppliers specialize in rapid-refill mechanisms for high-traffic commercial restrooms.
Switzerland
Luxury residential developers in Zurich and Geneva embed smart cisterns in high-specification bathroom pods. Swissmedic-equivalent building product certification creates technical barriers for non-specialized entrants. The Swiss manufacturing base sustains pan-European distribution dominance for premium wall-hung systems.
Italy
Boutique hospitality chains in Milan and Rome prioritize space-efficient wall-hung installations for premium positioning. Heritage building renovations in Florence and Venice sustain demand for floor-mounted configurations. Ceramic-composite housing production concentrates in Emilia-Romagna with specialized mineral supply dependencies.
Europe Concealed Cistern Market Competitive Landscape
Top-tier vendors anchor pan-European distribution networks, while mid-tier specialists compete through prefabricated module integration. The vendor base stratifies across Swiss-German manufacturing conglomerates, Southern European ceramic specialists, and modular bathroom fabricators. Three archetypes dominate: integrated sanitary ware conglomerates with captive polymer production, precision plumbing component specialists, and prefabricated construction system integrators. Competitive moves concentrate on backward integration into REACH-compliant polymer formulation and strategic partnerships with facilities management platforms.
Among Swiss-based integrated manufacturers, Geberit AG exemplifies the manufacturing conglomerate archetype with captive high-density polyethylene production. Grohe AG and Viega Group occupy positions within the precision component tier, with Grohe representing sensor-integrated flushing system development and Viega anchoring prefabricated bathroom module supply to German residential developers. These three entities collectively illustrate the competitive structure: scale-driven manufacturing integration, technology-led component specialization, and construction-system modularization.
| Leading Market Players |
|---|
| Geberit AG |
| Grohe AG |
| Viega Group |
| Siamp |
| Wirquin Group |
| TECE GmbH |
| Roca Sanitario SA |
| Ideal Standard International |
| Villeroy & Boch AG |
| Others |
Pricing and Supply Chain Analysis
High-density polyethylene resin indices cascade through concealed cistern manufacturing into three distinct pricing tiers, with REACH-compliant formulations commanding premiums that compress margins for non-integrated compounders serving Eastern European public housing developers.
Pricing Analysis
Lead-time premiums separate spot buyers from contract holders, with German hotel retrofit programs paying surcharges for sub-4-week delivery windows while Dutch modular builders capture volume discounts on 12-month offtake agreements. Pricing stratifies across premium sensor-integrated systems, standard dual-flush configurations, and economy single-flush units, with acoustic certification grade serving as the primary differentiation driver. Cost compression in the economy tier intensifies because ceramic-composite housing producers face mineral supply volatility from Southern European quarries. Public housing authorities in Poland and Czechia exhibit highest price sensitivity, while Swiss luxury residential developers demonstrate lowest elasticity.
Supply Chain Analysis
Domestic-content thresholds in French and German public procurement are reshaping sourcing patterns, forcing non-EU polymer suppliers to establish toll-manufacturing arrangements in North Rhine-Westphalia. Manufacturing gravity centers on Germany, Switzerland, and Italy, with captive HDPE production in the Rhine-Ruhr zone anchoring cost structures. Supply chains draw from specialized mineral deposits in Emilia-Romagna, ECHA-registered sealant chemistry from Basel-region compounders, and sensor components from Eindhoven-area electronics clusters. Single-source vulnerability concentrates in acoustic testing certification, where French and German laboratory capacity throttles new entrant qualification timelines. Distribution runs through pan-European plumbing supply networks that consolidate vendor qualification decisions within narrowing buyer pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe concealed cistern market sits in a technology-transition phase, with IoT-enabled sensor systems displacing mechanical actuation in premium hospitality and luxury residential specifications.
For Market Incumbents: Anticipate specification authority migration toward facilities management platforms by deepening captive polymer formulation capabilities and securing pan-European acoustic testing partnerships. Counter modular construction consolidation through prefabricated bathroom module integration with Dutch and Belgian student housing developers. Prioritize backward integration into REACH-compliant sealant chemistry to defend margin position against input volatility. For New Entrants and Emerging Players: Direct-to-facility-manager digital channels offer lower barrier entry than plumbing supply incumbency, particularly for sensor-integrated smart cisterns targeting Spanish and Italian boutique hotel chains. White-space concentrates in modular student housing prefabrication systems for Netherlands-Belgium corridor developers and rapid-refill mechanisms for French transport hub restrooms. Partner with Eindhoven-region electronics suppliers for sensor component sourcing rather than competing on mechanical heritage. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision plumbing component specialists with existing acoustic certification records in Germany and Switzerland, where laboratory bottlenecking creates defensive moats. Long-term viability hinges on 5-10 year water-efficiency regulatory tightening trajectories under EU Green Deal implementation. Watch for EU Water Label mandatory procurement preference signals as inflection indicator for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Formulation | Captive REACH-compliant HDPE production insulates Geberit and Viega from ECHA regulatory volatility. |
| Sensor-Integrated Flushing System Launch | Grohe's pressure-sensitive actuation platforms capture ESG-mandated water-intensity disclosure demand from French hotel chains. |
| Prefabricated Module Partnership | Viega's German residential developer relationships accelerate build schedules through offsite bathroom pod integration. |
| Acoustic Testing Laboratory Accreditation | Grand Est-German laboratory network coordination creates compliance barriers protecting qualified incumbents. |
| Facility Management Platform Integration | Cloud-connected usage analytics penetration concentrates vendor decisions within narrowing hospitality procurement pools. |
Research Methodology
Multi-period observation of flush-volume specification shifts, acoustic certification timelines, and modular construction adoption rates anchored the trend analysis, supplemented by interviews with facilities management platform directors, plumbing supply distributor procurement heads, German residential developer technical standards teams, and ECHA regulatory affairs specialists. Secondary validation drew from EU Ecodesign directive filings, REACH compliance registries, French ANSM data governance guidance, national building code acoustic test requirements, and customs records of HDPE sanitary ware component trade flows. Bottom-up project pipeline enumeration triangulated against top-down construction output forecasts.
Input-output matrices modeled concealed cistern demand across product type, installation format, end-use sector, and distribution channel dimensions throughout the projection horizon. CAGRs derived from regression analysis of historical replacement cycle patterns, regulatory mandate implementation schedules, and water-utility tariff trajectories. Forecast inputs incorporated EU Green Deal water-efficiency threshold tightening assumptions and modular construction penetration curves for Dutch and Belgian student housing.
The model holds under steady EU regulatory implementation pace and stable polymer feedstock availability; deviation in ECHA sealant chemistry restriction timing or Southern European mineral supply disruption would shift volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Composite Decking and Railing Market
Building Materials
Glass Facade Market
Building Materials
Cladding Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
France Architectural Coatings Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
Rubbing Bricks Market
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Portland Cement Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
Building Asphalt Market