
 Cross Laminated Timber (CLT) Market | 2026-2036
Cross Laminated Timber (CLT) Market Size, Share, and Industry Trends Forecast 2026-2036
Cross Laminated Timber (CLT) Market Analysis
Mass timber construction codes are expanding across North America and Europe, lowering insurance and engineering barriers for developers. Stora Enso leverages its integrated Nordic forestry-to-panel supply chain to dominate European project pipelines. Binderholz GmbH anchors Central European production capacity with multi-facility output across Austria and Germany. SmartLam competes aggressively on North American project turnaround times with dedicated U.S. manufacturing assets.
Cross laminated timber consists of orthogonally bonded softwood layers, typically three to nine plies thick, pressed under controlled temperature and pressure to create structural panels rated for load-bearing walls, floors, and roofs. The engineered wood segment leads value generation due to premium pricing on certified structural grades, while residential buildings represent the deepest application pool as mid-rise developers substitute CLT for steel and concrete frames. Glue-laminated manufacturing processes occupy the majority of installed capacity, though dowel-laminated variants are gaining share in moisture-sensitive specifications.
EU Green Deal carbon accounting rules and the F-Gas Regulation indirectly elevate mass timber against emission-intensive alternatives, while U.S. building codes adopted by the International Code Council now explicitly recognize tall wood construction standards. The U.S. EPA and USDA jointly influence forest certification pathways that determine CLT eligibility for federal procurement. Stakeholders must monitor code harmonization between European CE marking requirements and North American ICC performance standards, as divergence creates compliance duplication for multinational suppliers.
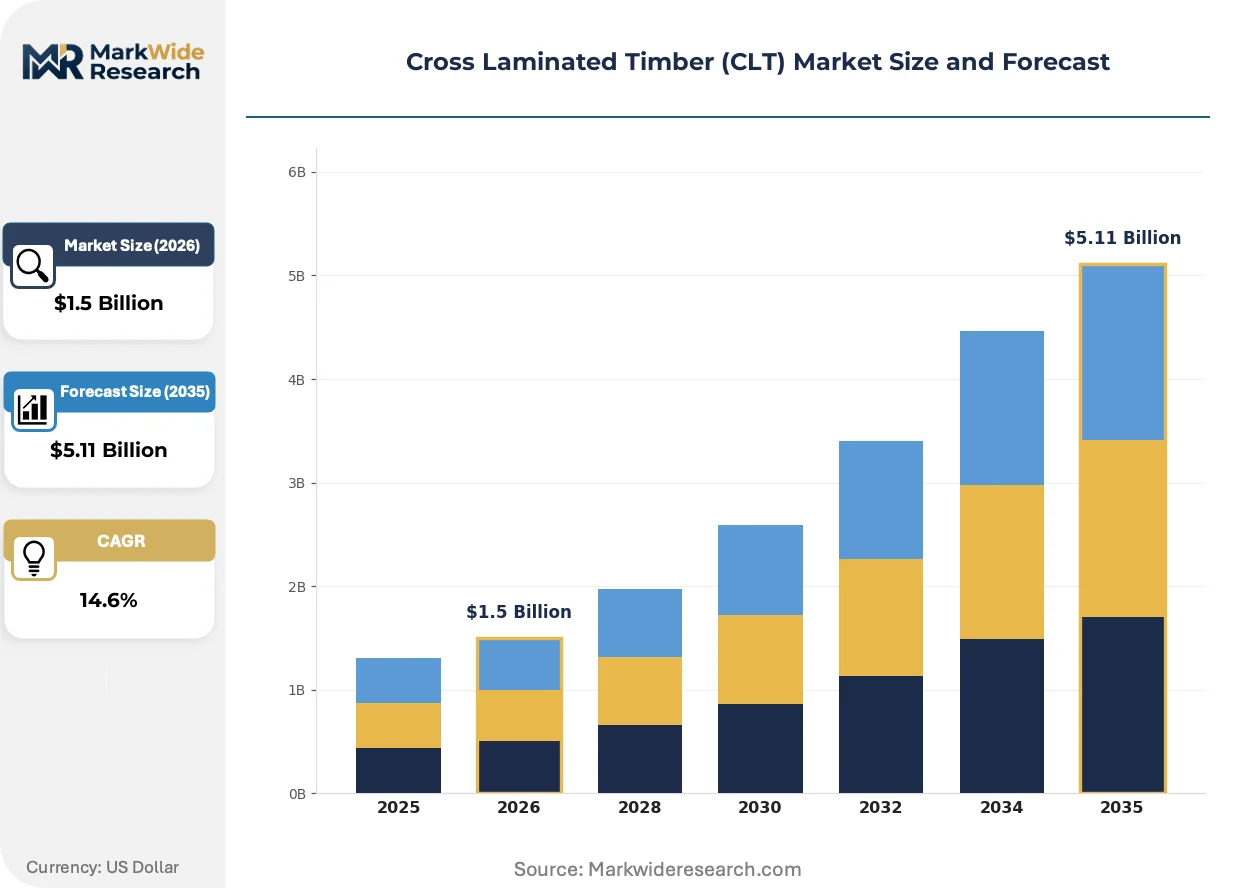
Market Dynamics
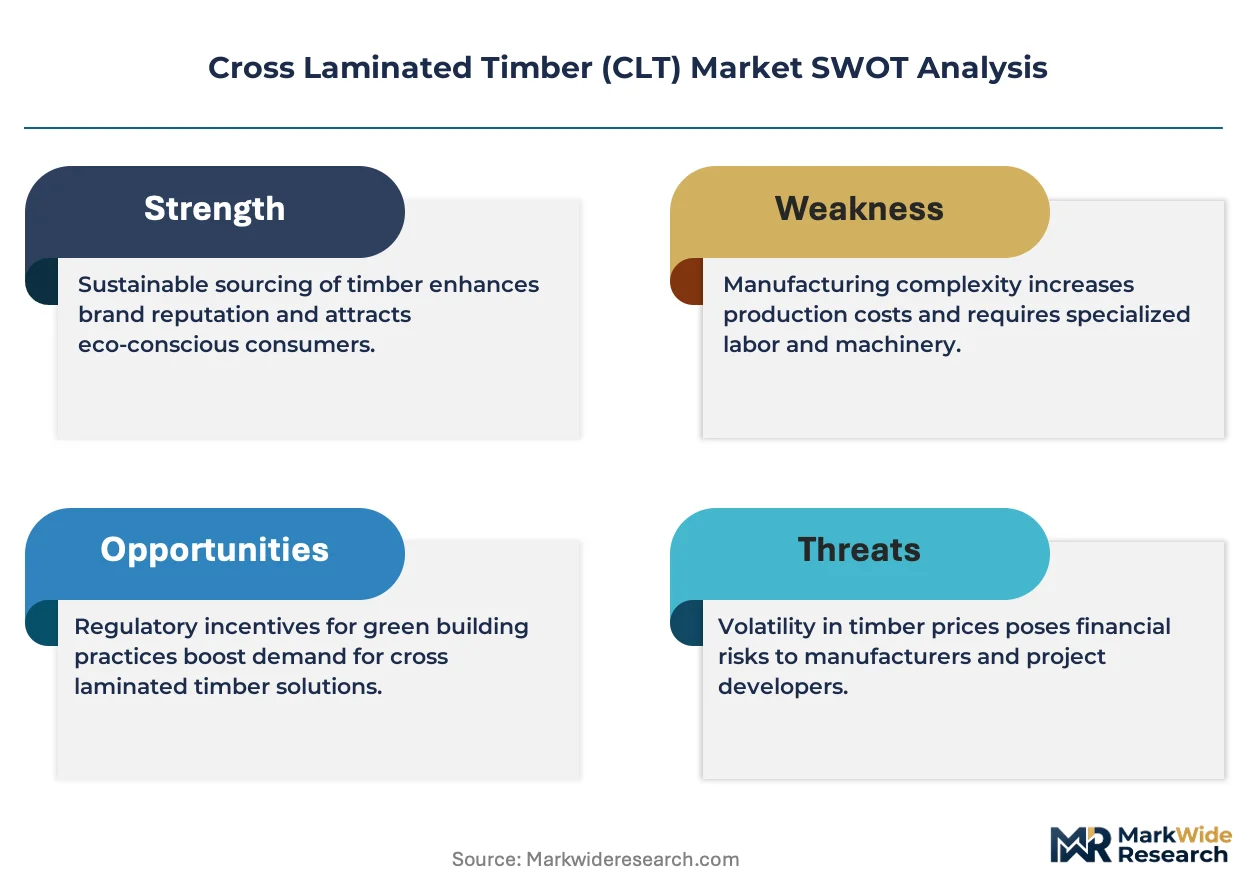
Code harmonization between European CE marking and North American ICC performance standards is forcing multinational CLT suppliers to maintain dual certification pathways, compressing margin structures and favoring producers with integrated testing capabilities.
Growth Catalysts
- EU Green Deal embodied carbon targets:Austria and Germany now mandate lifecycle carbon accounting for public buildings, redirecting structural specifications toward mass timber alternatives.
- Seattle and Portland building code revisions:The International Code Council's tall wood construction standards permit mass timber structures up to eighteen stories, unlocking mid-rise residential pipelines.
- Adhesive chemistry advances:Moisture-resistant polyurethane bonding systems are expanding CLT deployment into humid climate zones previously restricted to steel and concrete.
Market Restraints
- Nordic spruce supply concentration:Stora Enso's integrated forestry-to-panel supply chain controls premium softwood feedstock access, creating input bottlenecks for second-tier producers.
- Fire resistance certification timelines:Extended testing protocols under EN 13501-2 delay project approvals by six to twelve months in EU member states.
- Steel frame substitution threat:Cold-formed steel maintains cost advantages in seismic zones with established engineering supply chains.
Strategic Opportunities
- Underpenetrated UK housing sector:England's shortage of mid-rise residential stock and pending updates to Approved Document B present greenfield demand for mass timber developers.
- Hybrid structural systems:CLT-concrete composite floor slabs are penetrating commercial office specifications in German cities seeking optimized span-to-depth ratios.
- USDA BioPreferred program expansion:Federal procurement preference for certified wood products is creating dedicated demand channels for FSC-certified CLT in government buildings.
Industry Challenges
- Mass timber engineering talent scarcity:European technical universities produce fewer than two hundred specialized structural engineers annually, constraining project design capacity.
- Production equipment lead times:CNC panel processing machinery from Austrian and German suppliers carries eighteen-month delivery backlogs, throttling capacity expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross Laminated Timber (CLT) Market |
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $5.11 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, Lumber, Engineered Wood, Timber Panels Application: Residential Buildings, Commercial Spaces, Industrial Structures, Educational Facilities Design Type: Architectural, Structural, Aesthetic, Functional Manufacturing Process: Glue-Laminated, Dowel-Laminated, Nail-Laminated, Finger-Jointed |
| Companies Covered | Stora Enso, Mayr-Melnhof Holz, Binderholz GmbH, KLH Massivholz GmbH, HASSLACHER Holding GmbH, Structurlam Mass Timber Corporation, Schilliger Holz AG, Eugen Decker Holzindustrie KG, SmartLam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross Laminated Timber (CLT) Market Emerging Trajectories
Digital fabrication workflows and automated quality inspection systems are compressing production cycles while embedding traceability into supply chains from forest harvest to site installation.
Robotic panel finishing systems are unifying surface preparation, precision cutting, and connector routing into single-pass operations. Austrian producers deploy these integrated lines to reduce downstream labor hours by half. The technology is unifying quality control with production speed, compressing delivery timelines for complex geometric specifications.
REACH restrictions on formaldehyde-emitting adhesives are accelerating migration toward bio-based bonding chemistries. German manufacturers reformulate product lines to maintain CE marking compliance ahead of 2025 implementation deadlines. The regulatory shift most affects small-batch producers lacking in-house polymer research capabilities.
Developer procurement teams now specify certified chain-of-custody documentation as a contract precondition rather than a preference. General contractors in the Pacific Northwest substitute bonded panel suppliers who cannot provide FSC or PEFC tracking within seventy-two hours. The behavioral shift is most visible in Seattle's Design Review Board process, where material provenance disclosure affects project approval timelines.
Cross Laminated Timber (CLT) Market Segmentation
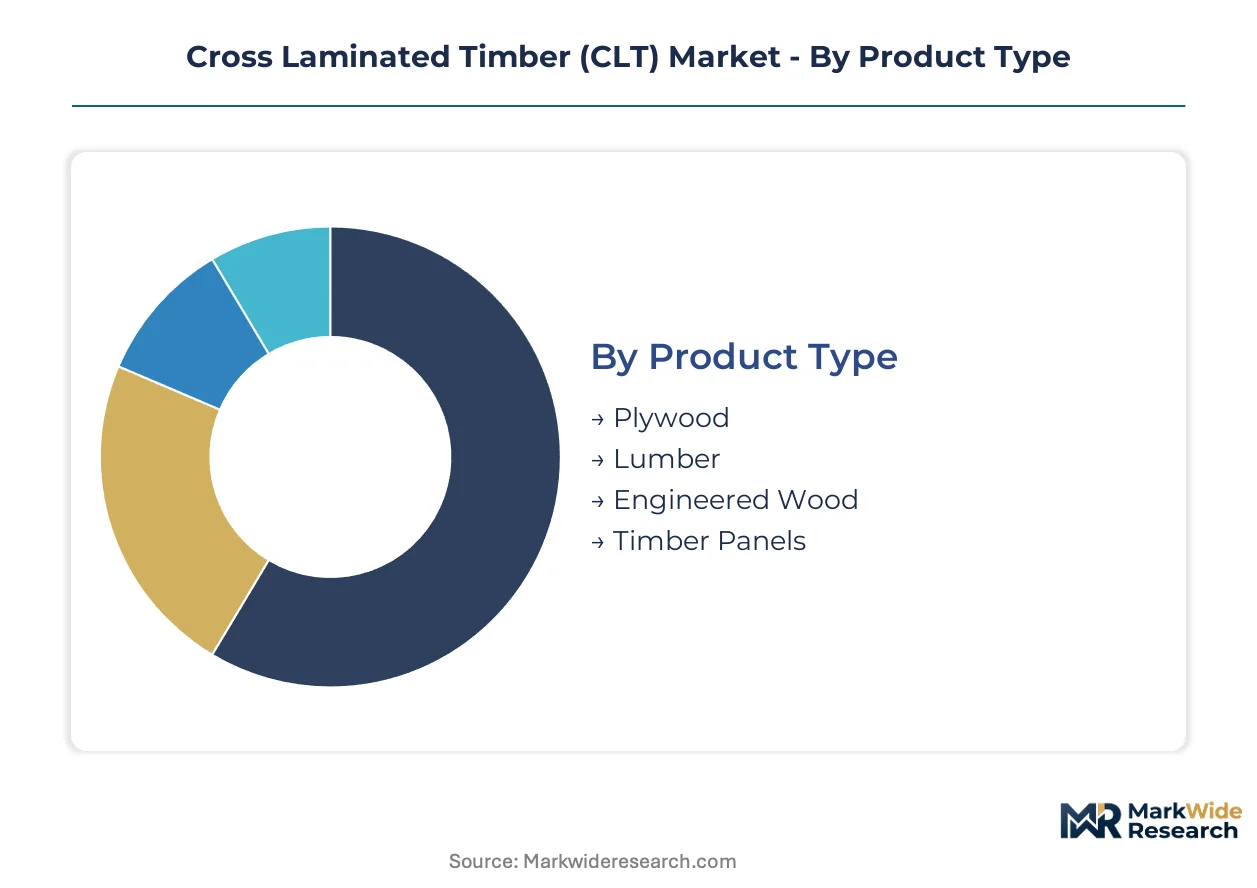
CLT market segmentation reveals how technical specifications, end-use requirements, and manufacturing methods create distinct value tiers. Buyers optimize across structural performance, aesthetic finish, and carbon credentials when selecting panel grades.
Product Type:
Standardization dominates commodity grades while engineered variants command premium positioning through certified structural ratings.
- Engineered Wood:Orthogonally bonded softwood layers create structural panels rated for load-bearing walls, floors, and roofs. Demand concentrates in mid-rise residential construction across Austria and Germany as EU Green Deal embodied carbon targets redirect specifications from steel and concrete frames.
- Timber Panels:Pre-fabricated CLT assemblies integrate insulation, vapor barriers, and connector hardware for rapid site installation. Seattle and Portland developers specify these systems for eighteen-story mass timber structures permitted under International Code Council tall wood standards.
- Plywood:Cross-laminated veneer construction offers cost-efficient sheathing and formwork applications with shorter production cycles than solid-sawn alternatives.
- Lumber:Traditional solid-sawn dimensional timber serves non-structural infill and temporary works where engineered precision is unnecessary.
Leading the category by volume: Engineered Wood. Growing fastest: Timber Panels.
Application:
End-use differentiation tracks fire safety requirements, span-to-depth ratios, and procurement channel access.
- Residential Buildings:Mid-rise multifamily housing represents the deepest application pool as developers substitute CLT for conventional frames. Pacific Northwest building codes now permit mass timber up to eighteen stories, unlocking pipeline capacity in Seattle and Portland.
- Commercial Spaces:CLT-concrete composite floor slabs penetrate office specifications in German cities seeking optimized structural performance. Hybrid systems combine mass timber's carbon advantages with concrete's acoustic and vibration control.
- Educational Facilities:Public procurement mandates in Austria and Germany prioritize lifecycle carbon accounting, directing school construction toward certified mass timber.
- Industrial Structures:Warehouse and logistics buildings adopt nail-laminated variants for cost-sensitive large-span roofs with lower fire rating requirements.
Deepest revenue pool: Residential Buildings. Steepest expansion trajectory: Commercial Spaces.
Design Type:
Aesthetic and functional specifications diverge based on visual exposure and structural visibility in finished buildings.
- Structural:Load-bearing panels with visible wood grain and precision-milled surfaces command premium pricing in architecturally exposed applications. German manufacturers reformulate adhesive systems to maintain CE marking compliance ahead of REACH implementation deadlines.
- Architectural:Custom geometric cutting and surface finishing for landmark buildings requires robotic panel processing with eighteen-month equipment lead times from Austrian and German suppliers.
- Functional:Concealed structural grades prioritize mechanical performance over visual uniformity, serving utilitarian specifications at lower price points.
- Aesthetic:Specialty veneers and tinted finishes for interior feature walls occupy niche demand from boutique hospitality and retail developers.
Highest margin concentration: Structural. Fastest share gain: Architectural.
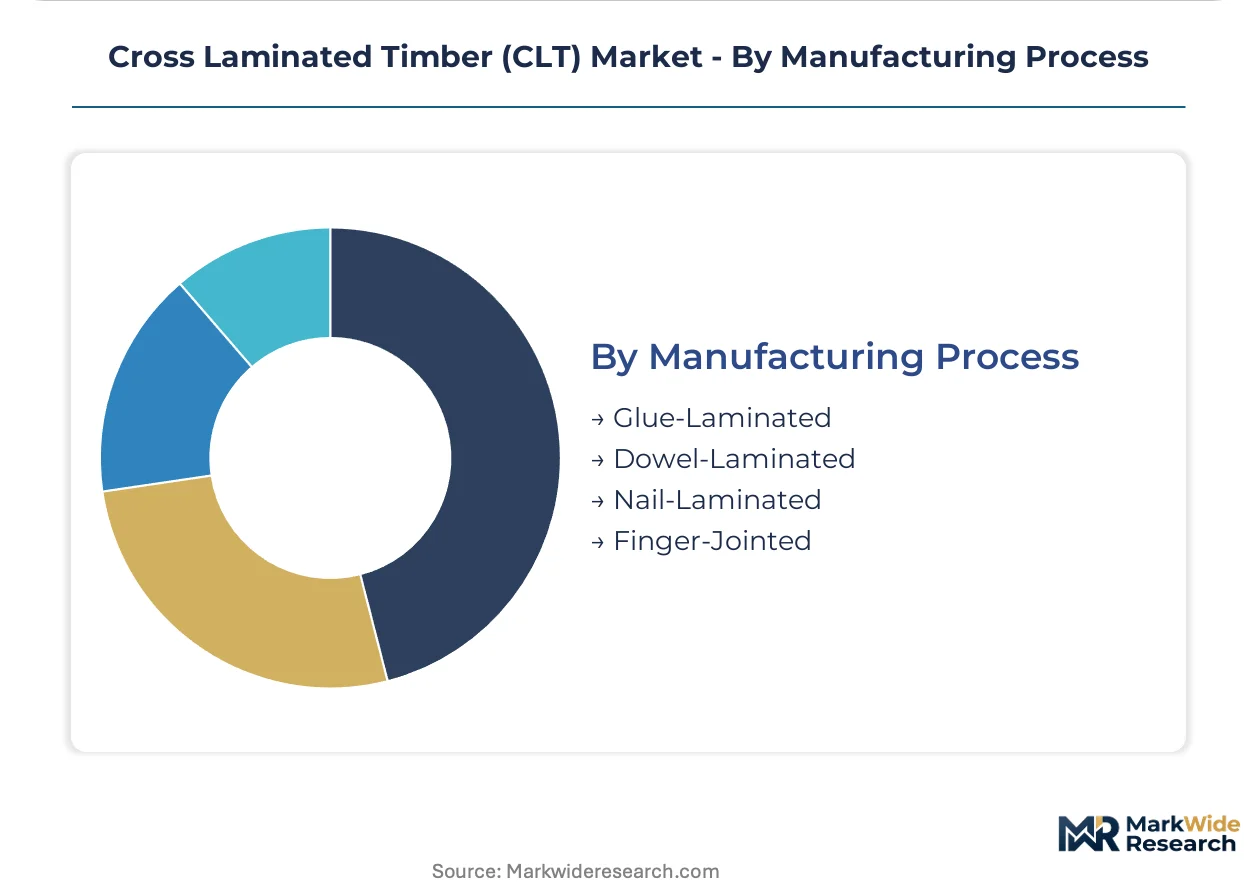
Manufacturing Process:
Adhesive chemistry and mechanical fastening methods determine moisture resistance, fire performance, and regulatory compliance pathways.
- Glue-Laminated:Polyurethane and melamine-urea bonding systems occupy the majority of installed capacity. Moisture-resistant polyurethane formulations are expanding CLT deployment into humid climate zones previously restricted to steel and concrete.
- Dowel-Laminated:Hardwood dowels replace adhesives in moisture-sensitive specifications, gaining share where formaldehyde emissions face regulatory scrutiny. German small-batch producers lacking in-house polymer research face margin pressure from REACH restrictions.
- Nail-Laminated:Mechanical fastening with metal connectors serves cost-driven industrial and agricultural structures with lower certification burdens.
- Finger-Jointed:Lengthwise splicing of solid timber creates continuous laminations for specialty long-span applications with custom engineering.
Dominant installed base: Glue-Laminated. Climbing the fastest: Dowel-Laminated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austria's Timber Construction Initiative designates mass timber as a strategic priority sector, channeling public procurement toward engineered wood systems in Vienna and Salzburg corridors.
Austria
Public building mandates in Vienna and Graz accelerate mid-rise residential pipelines. The national Timber Construction Initiative directs municipal procurement toward lifecycle carbon accounting. Salzburg and Innsbruck clusters concentrate dowel-laminated capacity serving Alpine moisture-sensitive specifications.
Germany
Munich and Berlin developers specify CLT-concrete composite slabs for commercial office spans. REACH restrictions on formaldehyde-emitting adhesives force adhesive reformulation ahead of 2025 deadlines. Baden-Württemberg and Bavaria host automated panel processing lines with eighteen-month equipment backlogs.
United States
Seattle and Portland building codes now permit mass timber structures up to eighteen stories, unlocking mid-rise residential demand. The USDA BioPreferred program creates federal procurement channels for certified wood products. Pacific Northwest manufacturing assets compete aggressively on project turnaround times against European imports.
Canada
British Columbia updates its building code to align with International Code Council tall wood standards. Federal procurement guidelines under the Greening Government Strategy prioritize low-carbon structural materials. Vancouver and Prince George anchor west coast production capacity with integrated forestry-to-panel supply chains.
United Kingdom
England's shortage of mid-rise residential stock creates greenfield demand for mass timber developers. Pending updates to Approved Document B fire safety regulations reshape certification timelines. Greater London and Manchester metropolitan areas concentrate architectural specification expertise for exposed structural applications.
Cross Laminated Timber (CLT) Market Vendor Landscape
Nordic producers anchor one tier with integrated forestry-to-panel supply chains; Central European specialists hold manufacturing density in multi-facility configurations. The vendor base stratifies across three tiers: scale-driven integrated forest products groups, mid-cap regional fabricators with automated processing lines, and niche architectural-grade specialists. Competitive moves concentrate on backward integration into premium softwood feedstock and capacity expansion through Austrian and German equipment procurement.
Among Nordic integrated producers, Stora Enso represents the scale-driven archetype with captive spruce supply. Binderholz GmbH exemplifies the Central European multi-facility model. SmartLam occupies a position among North American turnaround-time competitors with dedicated U.S. manufacturing assets.
| Leading Market Players |
|---|
| Stora Enso |
| Mayr-Melnhof Holz |
| Binderholz GmbH |
| KLH Massivholz GmbH |
| HASSLACHER Holding GmbH |
| Structurlam Mass Timber Corporation |
| Schilliger Holz AG |
| Eugen Decker Holzindustrie KG |
| SmartLam |
| Others |
Supply Flow & Price Mechanics
European structural engineering talent concentration in Austria and Germany creates labor-cost differentials that widen pricing-tier spreads between premium certified grades and commodity panel offerings. Certified mass timber commands substantial premiums where project timelines compress, while standard grades face margin erosion from equipment backlogs and adhesive reformulation costs.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with eighteen-story mass timber projects in Seattle and Portland paying premiums for guaranteed delivery windows while spot inventory clears at discounts. Three-tier pricing structure across premium certified-structural, standard CE-marked, and economy industrial grades separates buyers by fire-rating requirements and aesthetic exposure. Cost compression in standard grades intensifies because CNC machinery backlogs from Austrian suppliers throttle capacity expansion. Commercial developers demonstrate highest price sensitivity, while architecturally exposed landmark projects absorb premiums for visible-grade finishes and chain-of-custody documentation.
Supply Chain Analysis
USDA BioPreferred program domestic-content mandates reshape sourcing patterns for federal procurement channels, favoring FSC-certified North American production over European imports. Supply concentrates in Austria, Germany, and the Pacific Northwest United States, with Nordic spruce feedstock anchoring premium panel output. Raw material dependencies center on polyurethane adhesive formulations, automated CNC processing machinery, and certified softwood lumber grades. Single-source vulnerability runs through Austrian and German equipment suppliers with eighteen-month delivery backlogs. Distribution runs through project-direct channels for large developments and regional fabricator networks for mid-scale residential pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CLT market functions as a vertical-integration race where captive softwood supply and in-house adhesive research capabilities determine margin sustainability. Players securing upstream forestry assets and downstream installation partnerships capture pricing power unavailable to pure-panel producers.
For Market Incumbents: Acquire automated CNC panel processing lines to compress turnaround times against North American competitors. Secure long-term spruce supply contracts in Nordic and Alpine regions before second-tier producers exhaust available feedstock. Defensive positioning requires REACH-compliant adhesive reformulation ahead of formaldehyde restriction deadlines, while capacity expansion in British Columbia and the Pacific Northwest addresses USDA BioPreferred procurement channels.
For New Entrants and Emerging Players: Enter via England's underpenetrated mid-rise residential sector where Approved Document B revisions create greenfield certification pathways. Target hybrid CLT-concrete composite systems for German commercial office specifications seeking optimized span-to-depth ratios. White-space opportunity concentrates in dowel-laminated production for moisture-sensitive Alpine specifications where adhesive-free construction meets regulatory scrutiny. Go-to-market positioning should emphasize rapid project turnaround against European import lead times.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists given EU Green Deal embodied carbon mandates redirecting public procurement toward mass timber alternatives. Long-term viability over the analysis window favors producers with captive forestry assets and multi-facility manufacturing footprints spanning Austria, Germany, and North American markets. Acquisition target archetype: regional fabricators with automated processing lines but lacking upstream integration. Signal to watch: harmonization progress between CE marking and ICC performance standards eliminating dual-certification cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Spruce Forestry | Captive softwood supply secures premium feedstock access against Stora Enso's integrated dominance. |
| Automated CNC Panel Processing Line Deployment | Robotic finishing systems from Austrian suppliers compress delivery timelines for geometric specifications. |
| REACH-Compliant Adhesive Reformulation | Bio-based bonding chemistry investments maintain CE marking access ahead of formaldehyde restrictions. |
| Hybrid CLT-Concrete Composite System Development | German commercial office specifications adopt optimized floor slabs combining carbon and acoustic performance. |
| USDA BioPreferred Certification Pathway | Federal procurement preference under Greening Government Strategy creates dedicated demand channels. |
Methodological Framework
Trade association filings, building code revision records, and forest certification databases formed the secondary backbone for demand quantification. Primary interviews with mass timber structural engineers, municipal procurement officers, CLT plant managers, and general contractors specializing in tall wood construction validated production capacity and project pipeline assumptions. Bottom-up and top-down triangulation reconciled panel shipment data against square-footage permits in Seattle, Portland, Vienna, and Munich corridors.
Bottom-up modeling tracked individual production facility outputs and project-specific procurement records, while top-down analysis calibrated against construction spending flows and embodied carbon accounting mandates. Segmentation dimensions included product grade tier, end-use application, design exposure requirements, and manufacturing process chemistry. CAGRs derived from fitted growth curves incorporating code adoption timelines, equipment delivery backlogs, and adhesive regulatory phase-ins. Industry-specific inputs encompassed EU Green Deal implementation pace and International Code Council tall wood standard adoption rates across U.S. jurisdictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended fire-resistance certification delays or sudden Nordic spruce supply disruptions. Forecasts reflect documented assumptions regarding code harmonization progress and equipment delivery schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Ductile Iron Pipe Market
Building Materials
Mass Timber Construction Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Iron and Steel Slag Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
Roof Cover Boards Market
Building Materials
United States Architectural Coatings Market
Building Materials
Steel Products Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Blind Bolts Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
India Concealed Cistern Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
North America Cement Market
Building Materials
Low-E Construction Glass Market