
 Residential Construction Market | 2026-2036
Residential Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Construction Market Analysis
North America is fragmenting as local zoning boards and municipal permitting offices multiply approval pathways across jurisdictions. D.R. Horton leverages its scale to dominate entry-level single-family production in Texas and the Southeast. Lennar Corporation anchors its position through integrated mortgage and title services that capture buyers across the financing cycle. NVR competes via a land-light asset model that minimizes balance-sheet exposure to speculative lot purchases.
Residential construction encompasses the design, assembly, and finishing of detached houses, attached dwellings, and multi-unit structures using wood framing, concrete foundations, steel reinforcement, and engineered systems for HVAC, electrical, and plumbing distribution. Single-family homes occupy the largest value pool, though multi-family units are gaining share as rental affordability pressures reshape household formation patterns. Wood framing sustains cost advantages in low-rise segments, while concrete and steel intensify in mid-rise multi-family and townhouse applications where fire codes and acoustic standards tighten. Remodeling and renovation applications are deepening as existing housing stock ages and interest rate environments suppress new construction starts relative to replacement demand.
FHA loan underwriting standards, VA eligibility requirements, and local building codes governed by the International Code Council shape product specifications, buyer qualification thresholds, and contractor licensing across US markets. EPA lead-safe renovation rules and energy code adoptions at the state level filter material choices and construction methodologies for older stock rehabilitation. Stakeholders must monitor how municipal zoning reforms and federal housing finance policy recalibrate the economics of greenfield development versus infill density.
Market Dynamics
Millennial household formation is compressing development timelines as first-time buyers demand move-in-ready inventory with embedded smart infrastructure and energy certification.
Growth Catalysts
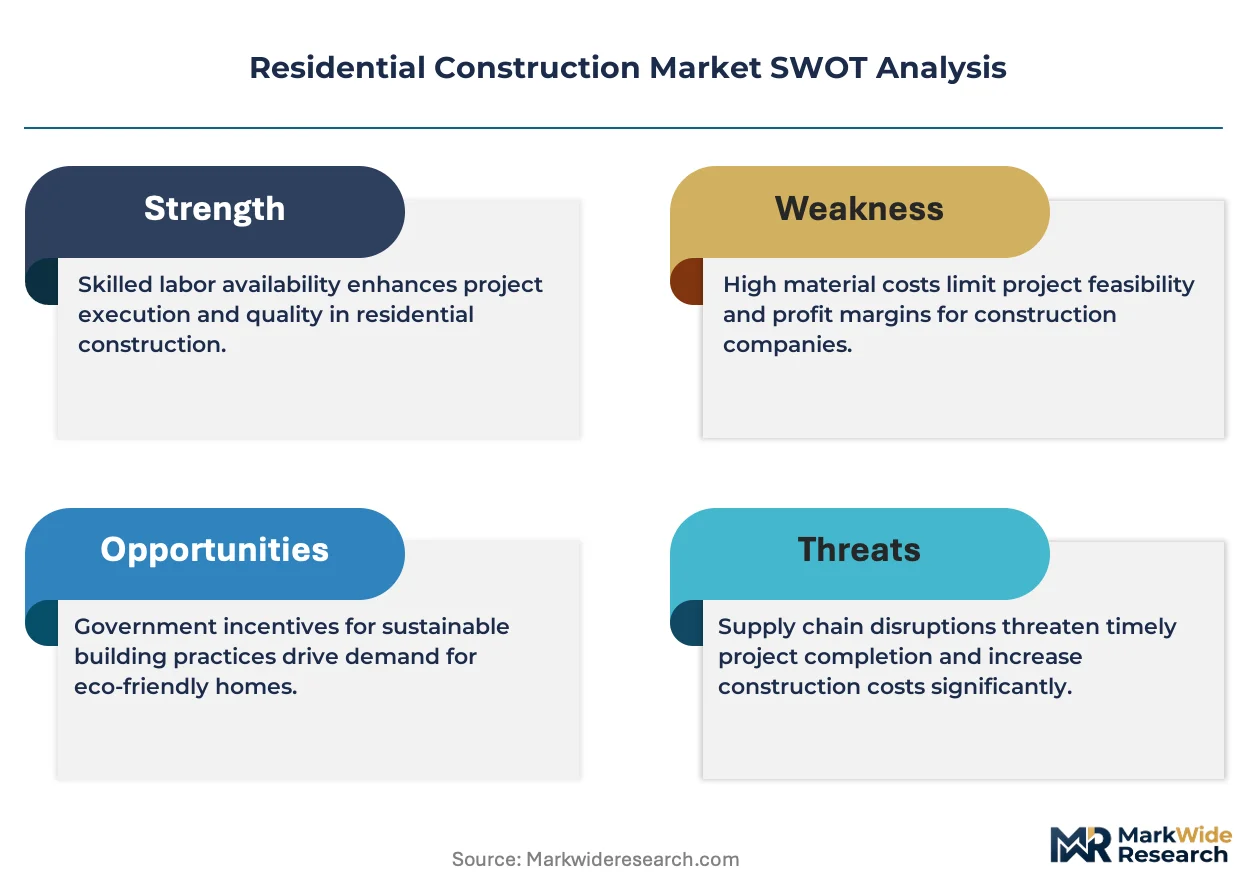
- EPA Energy Efficiency Codes:Tightening thermal envelope standards are mandating higher-performance insulation and HVAC specifications across new single-family permits.
- Sun Belt Migration:Texas, Florida, and Arizona are absorbing population inflows that sustain above-average housing starts relative to national permit velocity.
- Green Building Certifications:LEED and ENERGY STAR designations are commanding resale premiums that accelerate builder adoption of certified materials and systems.
Market Restraints
- Lumber Price Volatility:Softwood framing costs swing with tariff exposure and mill capacity constraints, compressing gross margins on entry-level product lines.
- Local Zoning Fragmentation:Municipal approval pathways multiply across jurisdictions, extending entitlement timelines and carrying costs for greenfield development.
- Skilled Labor Scarcity:Electrician and plumber certification pipelines lag replacement demand, constraining velocity on active construction sites.
Strategic Opportunities
- Suburban Infill Density:Underutilized parcels near existing infrastructure in Texas metro corridors offer lower entitlement risk than exurban greenfield.
- Integrated Solar-Storage Systems:Rooftop photovoltaic with battery backup is penetrating the premium single-family segment as a standard feature rather than upgrade.
- Renovation-Deepening Cycles:Aging housing stock in the Northeast and Midwest is sustaining replacement demand for kitchen, bath, and envelope upgrades despite interest rate headwinds.
Industry Challenges
- Permitting Velocity Compression:International Code Council adoption cycles and local amendment processes create staggered compliance deadlines across state lines.
- Supply Chain Reconfiguration:Cross-border material flows face customs documentation complexity that disrupts just-in-time delivery schedules for engineered wood products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Construction Market |
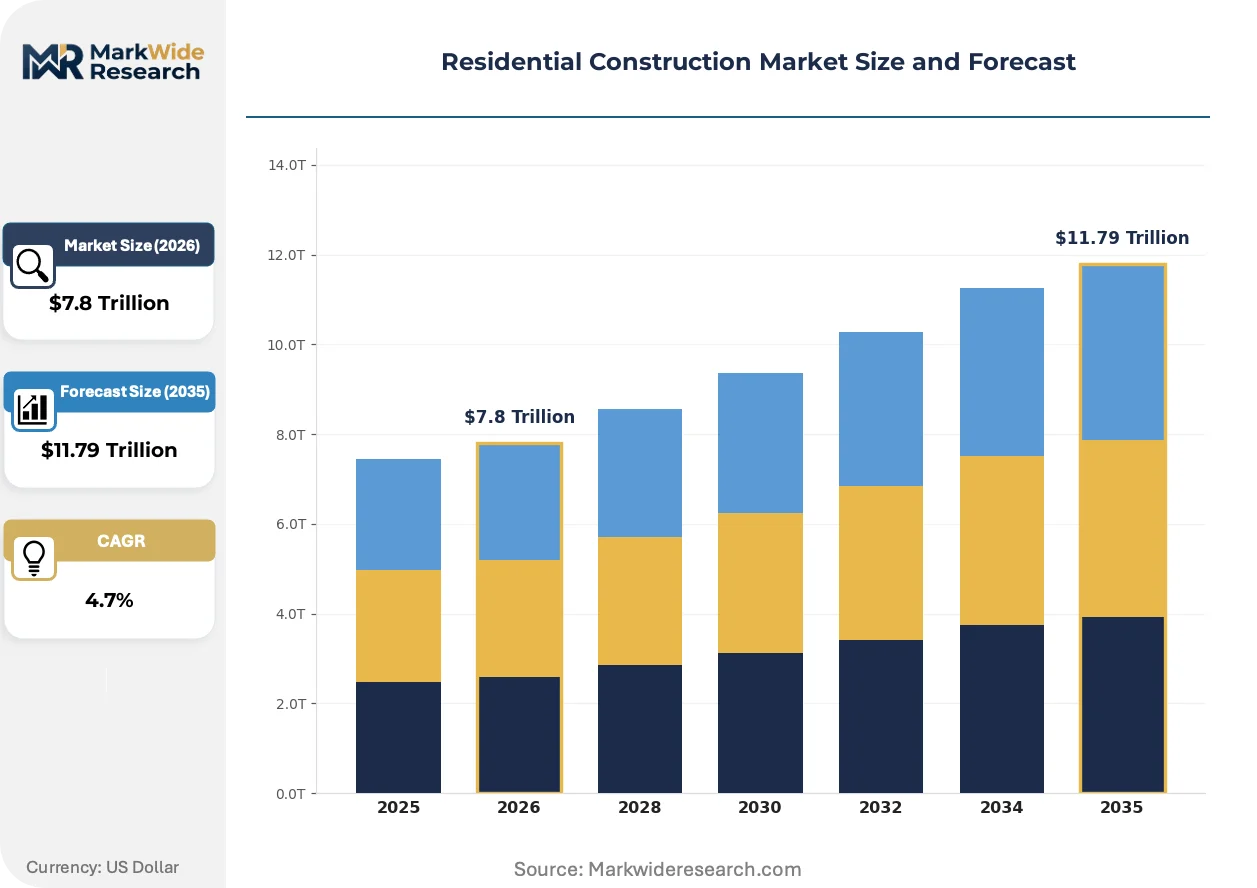
| Market Size in 2026 | $7.8 Trillion |
| Market Size in 2035 | $11.79 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Family Homes, Multi-Family Units, Townhouses, Condominiums Material Type: Wood, Concrete, Steel, Brick Application: New Construction, Remodeling, Expansion, Renovation Financing Model: Conventional Loans, FHA Loans, VA Loans, Cash Purchases |
| Companies Covered | D.R. Horton, Lennar Corporation, PulteGroup, NVR, Taylor Morrison, Toll Brothers, KB Home, Meritage Homes, Century Communities, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Construction Market Emerging Trajectories
Digital fabrication and modular assembly are compressing on-site labor exposure while regulatory pressure on carbon intensity is reshaping material specification protocols.
Cross-laminated timber (CLT) and mass plywood panels are penetrating mid-rise multi-family construction as structural alternatives to concrete and steel. Developers in the Pacific Northwest and Southeast are specifying engineered wood for five-to-twelve-story projects. Conventional cast-in-place concrete framing is rendering obsolete for residential buildings under 85 feet where fire code amendments now permit heavy timber structural systems.
The EPA's lead-safe renovation rules and state-level energy code adoptions are filtering contractor licensing requirements and material choices for older stock rehabilitation. Contractors must maintain RRP certification and document containment protocols on pre-1978 housing. Remodeling specialists in Massachusetts and California are restructuring workflows to accommodate third-party verification of dust clearance sampling.
First-time buyers are consolidating purchasing decisions around mortgage-title-insurance bundles that compress closing timelines and reduce friction. Lennar's integrated services model is being emulated by regional builders seeking to capture financing cycle economics. This bundling concentration is most visible in Texas and Florida where title insurance rates and transfer tax structures vary minimally across county lines.
Residential Construction Market Segmentation
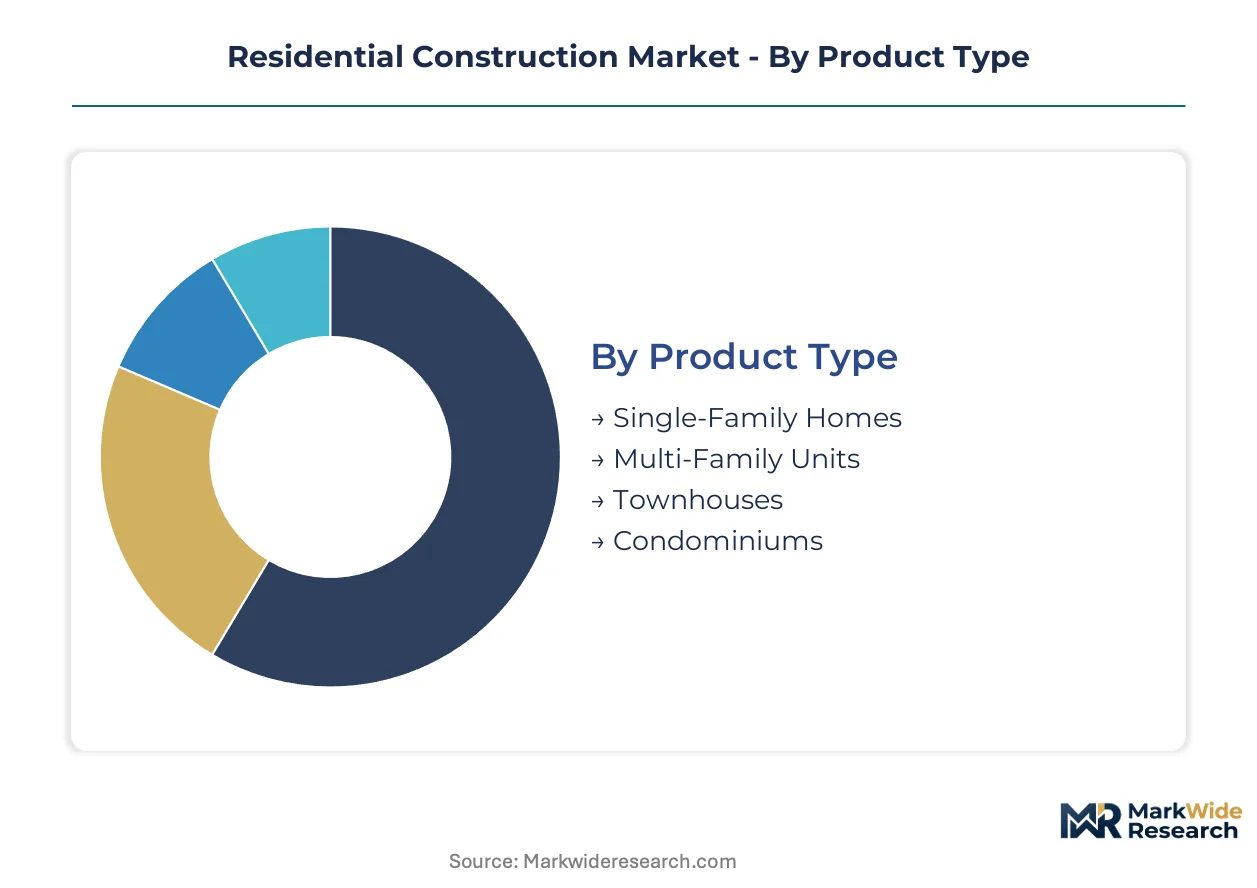
Residential construction segmentation reveals how material specifications, financing structures, and housing typologies interact with regulatory codes and buyer demographics. Builders configure product portfolios across these dimensions to match entitlement timelines with capital deployment strategies.
Product Type:
Cost tier stratification across housing typologies determines land absorption rates and municipal infrastructure contributions per unit.
- Single-Family Homes:Detached structures on individually platted lots utilize platform framing with engineered roof trusses. Texas and Florida permit velocity sustains production volume for entry-level product lines where D.R. Horton and Lennar concentrate site acquisition. EPA energy code adoptions are mandating higher envelope performance standards for this segment.
- Multi-Family Units:Rental-oriented structures with five-plus dwelling units per building employ Type V-A or Type III-A construction classifications. Sun Belt metro corridors absorb above-average starts as household formation compresses into rental tenure before first purchase. Fire code amendments are permitting heavy timber structural systems up to 85 feet.
- Townhouses:Attached single-family dwellings sharing common walls achieve density multiples of 8-12 units per acre. Zoning reforms in suburban jurisdictions are accelerating entitlement timelines for this typology relative to detached product.
- Condominiums:Fee-simple ownership structures with undivided common interest in land and amenities require specialized HOA governance frameworks. Florida and Arizona concentrate conversion activity from rental multi-family to for-sale condominium.
Single-Family Homes holds installed capacity. Multi-Family Units is rotating up the share rankings.
Material Type:
Application-specific material selection responds to fire rating requirements, acoustic standards, and carbon intensity targets across building height bands.
- Wood:Dimensional lumber and engineered wood products dominate platform framing for structures under four stories. Softwood framing costs swing with tariff exposure and mill capacity constraints, compressing gross margins on entry-level product lines.
- Concrete:Cast-in-place and precast systems anchor foundation work and mid-rise structural cores. Texas metro corridors sustain above-average concrete demand for podium-style multi-family construction.
- Steel:Cold-formed steel framing penetrates multi-family and townhouse applications where fire codes and acoustic standards tighten beyond wood capabilities. Light-gauge steel studs achieve 1-2 hour fire ratings required for corridor separation.
- Brick:Clay masonry serves primarily as veneer cladding rather than structural element. Northeast and Midwest renovation cycles sustain replacement demand for brick envelope upgrades despite interest rate headwinds.
Wood commands the largest volume position. Steel is climbing the fastest in mid-rise applications.
Application:
Volume distribution between new construction and improvement activity shifts with interest rate environments and housing stock age profiles.
- New Construction:Greenfield and infill development on previously unimproved parcels requires full entitlement sequencing. Sun Belt migration patterns concentrate new starts in Texas, Florida, and Arizona relative to national permit velocity.
- Remodeling:Kitchen, bath, and systems replacement in existing structures bypasses zoning approvals. Aging housing stock in the Northeast sustains replacement demand for envelope upgrades.
- Expansion:Horizontal or vertical additions to existing residential structures require setback and coverage compliance. Massachusetts and California contractors maintain RRP certification for pre-1978 housing disturbance.
- Renovation:Comprehensive gut rehabilitation of older stock triggers lead-safe renovation rules and energy code compliance. Third-party verification of dust clearance sampling restructures contractor workflows in regulated jurisdictions.
New Construction holds installed capacity. Renovation is rotating up the share rankings.
Financing Model:
Customer type stratification across financing channels determines builder capture of title and insurance economics.
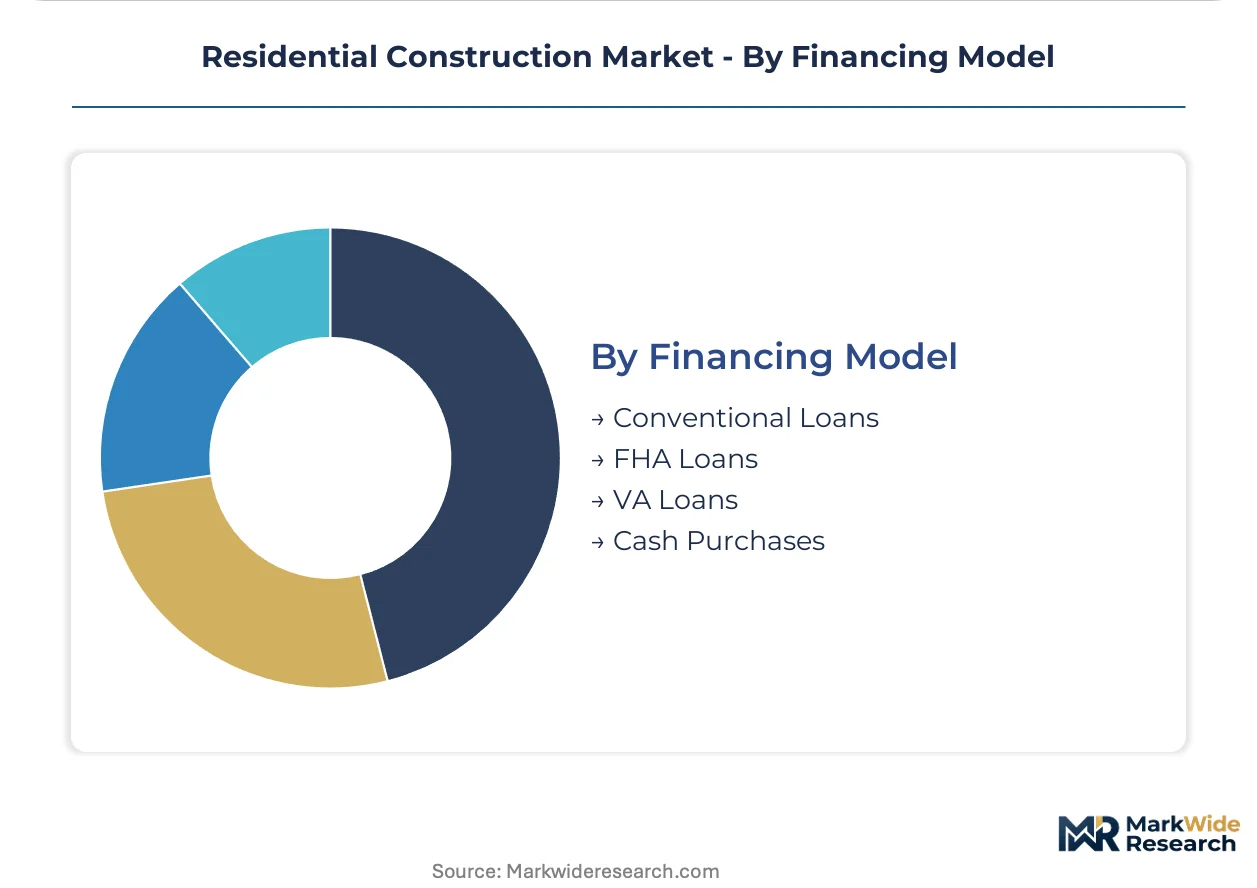
- Conventional Loans:Conforming and jumbo mortgages through private lenders require 20% down payment thresholds for optimal rate pricing. Lennar's integrated mortgage and title services capture buyers across this financing cycle in Texas and Florida.
- FHA Loans:Federal Housing Administration guarantees enable 3.5% minimum down payments for qualified first-time buyers. Millennial household formation compresses development timelines as this cohort demands move-in-ready inventory.
- VA Loans:Department of Veterans Affairs guarantees eliminate down payment requirements for eligible service members. Eligibility requirements shape buyer qualification thresholds in military concentration markets.
- Cash Purchases:Unleveraged acquisition by investors or equity-rich households accelerates closing timelines. Institutional single-family rental operators deploy this model for portfolio accumulation in Sun Belt corridors.
Conventional Loans holds installed capacity. Cash Purchases is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction material suppliers and engineered wood producers cluster near major metropolitan corridors where permit velocity sustains absorption rates. National builders deploy capital across four priority markets where regulatory alignment and demographic inflows converge.
United States
Texas, Florida, and Arizona absorb population inflows that sustain above-average housing starts relative to national permit velocity. EPA energy efficiency codes and FHA loan underwriting standards shape product specifications and buyer qualification thresholds. Dallas-Fort Worth and Houston metro corridors concentrate D.R. Horton and Lennar production volume for entry-level single-family lines.
Canada
Vancouver and Toronto metro areas face supply constraints from municipal zoning fragmentation that extends entitlement timelines. The National Building Code of Canada and provincial energy step codes mandate higher envelope performance standards for new construction. British Columbia's mass timber building code amendments permit heavy timber structural systems up to twelve stories.
Germany
Prefabricated housing manufacturers serve renovation-deepening cycles in aging urban housing stock. The German Energy Saving Ordinance (EnEV) and KfW development bank financing programs accelerate builder adoption of certified materials and systems. Bavaria and Baden-Württemberg industrial clusters supply cross-laminated timber for mid-rise multi-family applications.
Japan
Seismic code requirements and land scarcity drive modular assembly adoption in Tokyo and Osaka metro corridors. METI building energy efficiency standards and the CASBEE green building certification system filter material choices for new construction. Kanto region manufacturers supply precision-engineered wood components for platform framing under four stories.
Australia
Sydney and Melbourne infill density projects face skilled labor scarcity that compresses velocity on active construction sites. The National Construction Code and state-level BASIX thermal performance standards mandate higher-performance insulation specifications. New South Wales and Victoria timber processors supply engineered wood products for low-rise residential segments.
Residential Construction Market Vendor Landscape
National-scale production builders and regional specialists split the market along capital intensity and geographic coverage vectors. The vendor base concentrates around three strategic archetypes: integrated mortgage-title-service operators, land-light asset model competitors, and suburban infill density specialists. Dominant competitive moves include portfolio diversification across financing models and geographic expansion into Sun Belt corridors with above-average permit velocity.
Among US-based production builders, D.R. Horton, Lennar Corporation, and NVR occupy positions that exemplify contrasting strategic approaches. D.R. Horton represents the scale-driven archetype concentrated in Texas and Southeast entry-level segments. Lennar Corporation anchors the integrated services model through captive mortgage and title operations. NVR sits within the land-light tier that minimizes balance-sheet exposure to speculative lot purchases.
| Leading Market Players |
|---|
| D.R. Horton |
| Lennar Corporation |
| PulteGroup |
| NVR |
| Taylor Morrison |
| Toll Brothers |
| KB Home |
| Meritage Homes |
| Century Communities |
| Others |
Supply Flow & Price Mechanics
Canadian softwood lumber mills and engineered wood producers in the Pacific Northwest concentrate upstream capacity, anchoring margin pools with national production builders who negotiate volume offtakes across Texas and Florida metro corridors. This concentration feeds directly into entry-level single-family pricing where D.R. Horton and Lennar deploy scale to compress per-unit framing costs.
Pricing Analysis
EPA energy efficiency codes dictate the pricing tier structure across new construction permits. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified builds from code-minimum production and custom luxury product. Price differentiation rests on certification level and geographic delivery cost from mill to site. Cost compression in the economy tier is intensifying because softwood framing costs swing with tariff exposure. First-time FHA buyers exhibit highest price sensitivity; cash purchasers of investment properties show least.
Supply Chain Analysis
Weyerhaeuser and West Fraser Timber hold concentrated capacity in dimensional lumber and engineered wood products. Supply concentrates in Canada, the US Pacific Northwest, and the US Southeast. Raw material dependencies center on spruce-pine-fir logs, OSB resin binders, and steel fasteners. Single-source vulnerability runs through cross-border softwood lumber flows subject to trade remedy duties. Distribution runs through builder-direct mill relationships and regional lumberyard networks serving contractor accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular and factory-built housing substitutes threaten traditional stick-built incumbents as labor scarcity and cycle-time pressure intensify. Incumbents must navigate this substitution threat while defending entitlement pipelines in fragmented municipal jurisdictions.
For Market Incumbents: Harden land-light asset models to minimize balance-sheet exposure to speculative lot purchases in volatile entitlement environments. Deepen captive mortgage and title operations to capture financing cycle economics across FHA and conventional buyer segments. Defend against modular substitution by compressing field construction timelines through pre-fabricated panel systems.
For New Entrants and Emerging Players: Build out suburban infill density capabilities in Texas metro corridors where underutilized parcels near existing infrastructure offer lower entitlement risk than exurban greenfield. Target renovation-deepening cycles in the Northeast and Midwest where aging housing stock sustains replacement demand for envelope upgrades. Lead with EPA RRP-certified workflows and third-party dust clearance verification as a compliance-forward go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional builders who have consolidated local market share but lack integrated financing capabilities. Long-term viability over the five-to-ten year horizon favors operators with scalable land positions in Sun Belt corridors and captive customer acquisition channels. Watch permitting velocity compression across International Code Council adoption cycles as the key inflection signal for development timeline risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Land-Light Asset Model Expansion | NVR's minimal balance-sheet exposure to speculative lots reduces entitlement timeline risk in fragmented municipal jurisdictions. |
| Integrated Mortgage-Title Service Buildout | Lennar's captive financing operations capture buyer economics across the full purchase cycle in Texas and Florida. |
| Modular Assembly Capability Investment | Factory-built panel systems compress on-site labor exposure while meeting EPA energy code thermal envelope standards. |
| Suburban Infill Density Development | Underutilized parcels near existing infrastructure in Sun Belt metros offer faster entitlement timelines than exurban greenfield. |
| RRP-Certified Renovation Specialization | Lead-safe renovation compliance opens replacement demand in pre-1978 housing stock across Massachusetts and California. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with production builder acquisition executives, municipal permitting officers, lumberyard procurement managers, and HVAC systems specification engineers. Secondary validation drew from EPA energy code adoption databases, International Code Council amendment tracking, US Census Bureau permit statistics, and SEC 10-K filings from publicly traded builders. Bottom-up unit economics and top-down macroeconomic indicators were triangulated to anchor volume and value estimates.
Calibration across historical permit velocity, material cost indices, and financing origination volumes shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include housing typology, construction material, application type, and financing channel. CAGRs were derived from regression analysis of permit trends against demographic inflow patterns. Industry-specific forecast inputs incorporated lumber futures curve movements and FHA loan limit adjustments.
Stress conditions across interest rate environments, tariff exposure on Canadian softwood, and municipal zoning reform momentum were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of permit approval timelines, lumber price volatility, and Sun Belt population migration flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Bathroom Remodeling Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
UK Manufactured Homes Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
Latin America Residential Construction Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Siding Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Canada Residential Construction Market