
 Construction Aggregates Market | 2026-2036
Construction Aggregates Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Aggregates Market Analysis
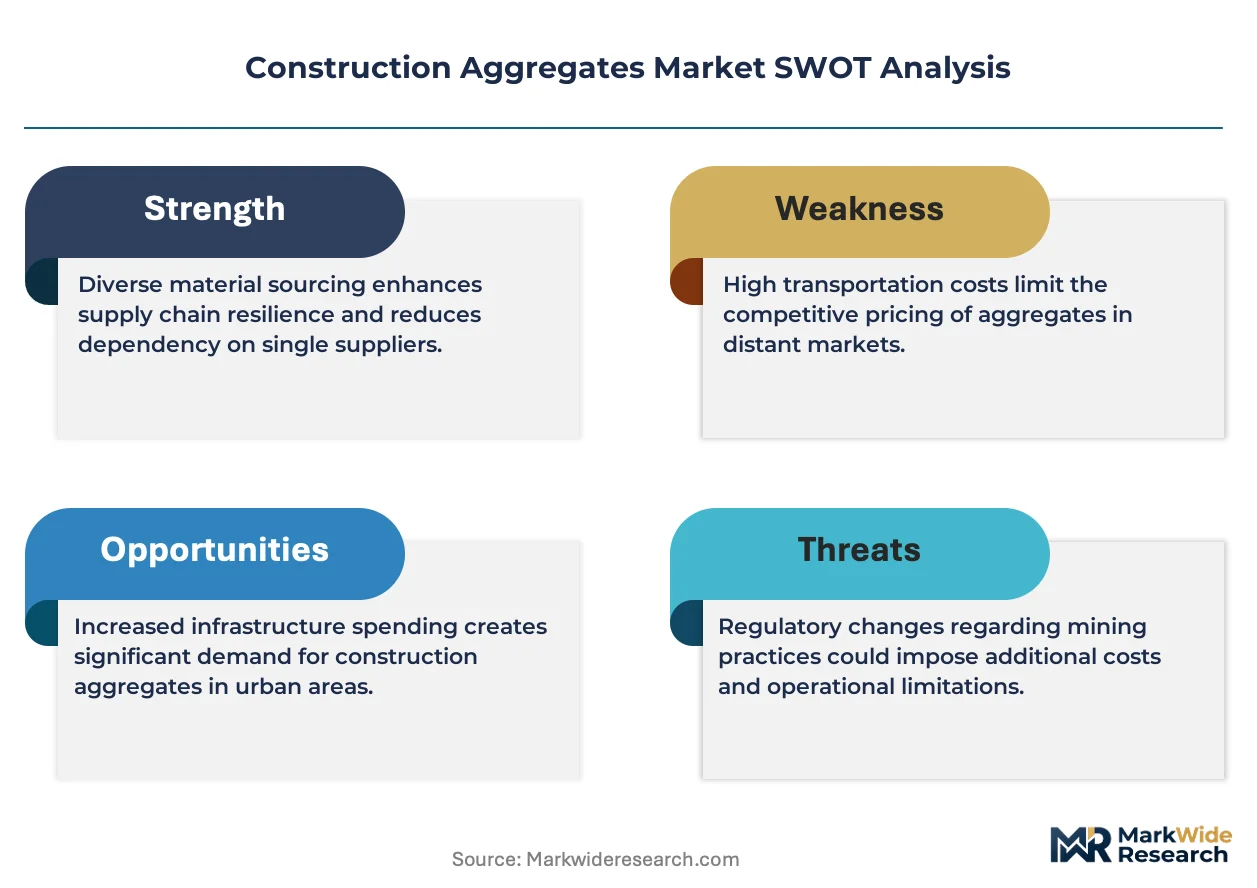
Shortages of licensed quarry operators and heavy equipment technicians is redrawing competitive boundaries across the construction aggregates sector. Vulcan Materials Company leverages its extensive reserve base across the southeastern United States to sustain pricing power in regional markets. CRH plc anchors its position through backward integration into cement production, capturing value across the full construction materials chain. Heidelberg Materials competes on decarbonization credentials, operating carbon-capture pilot projects at select limestone facilities.
Construction aggregates are granular mineral materials—primarily sand, gravel, and crushed stone with specified particle size distributions ranging from 0.075 mm to 75 mm—produced through mechanical crushing, screening, and washing of rock deposits for use as load-bearing components in concrete, asphalt, and road base applications. Crushed stone dominates value capture due to its structural performance in high-specification infrastructure concrete, while recycled aggregates represent the fastest-expanding product type as demolition waste recovery protocols mature across regulated jurisdictions. Sand and gravel sustain mature volume positions in residential and commercial construction, though premium quality grades command disproportionate margin pools in specialized precast and ready-mix applications.
EPA stormwater regulations and OSHA silica exposure limits in the United States, alongside EU Green Deal embodied carbon thresholds and REACH substance restrictions in Europe, are elevating compliance costs while redirecting procurement toward certified low-carbon aggregate sources. China's MEE environmental enforcement actions and GB standards for construction waste recycling are compressing informal quarry operations and accelerating formal sector consolidation. Stakeholders must monitor evolving carbon border adjustment mechanisms and building-level environmental product declarations to anticipate which quality grades and delivery modes will command premium positioning.
Market Dynamics
Construction aggregates markets face structural pressure from China's MEE environmental enforcement actions, which compress informal quarry operations while accelerating formal sector consolidation and certified low-carbon sourcing mandates.
Growth Catalysts
- MEE Environmental Enforcement:China's Ministry of Ecology and Environment actions are shuttering unlicensed quarries and redirecting procurement toward certified producers with verified emission controls.
- Recycled Concrete Mandates:GB standards tightening recycled concrete content specifications are creating compliant demand channels for demolition waste recovery operations.
- Infrastructure Megaprojects:Asia-Pacific transport corridor investments are pulling premium-grade crushed stone into high-specification concrete applications.
Market Restraints
- Diesel Price Volatility:Haulage cost sensitivity constrains delivered pricing power for inland quarry operators dependent on long-distance transport.
- Licensed Operator Scarcity:Shortages of certified quarry managers and heavy equipment technicians limit production expansion regardless of reserve availability.
- Silica Exposure Compliance:OSHA respirable crystalline silica limits elevate dust suppression capital requirements and operational monitoring costs.
Strategic Opportunities
- Carbon Capture Integration:Limestone calcination facilities with pilot carbon capture installations can access EU Green Deal embodied carbon thresholds and premium procurement pools.
- Urban Mining Infrastructure:Dense demolition waste streams in Shanghai and Mumbai offer feedstock proximity advantages for recycled aggregate production.
- Digital Fleet Optimization:Telematics and autonomous haul truck deployment compress extraction costs and extend reserve life at mature quarry sites.
Industry Challenges
- Certification Timeline Compression:Environmental product declaration verification and carbon border adjustment documentation create administrative bottlenecks for export-bound shipments.
- Legacy Equipment Integration:Retrofitting existing crushing circuits with real-time particle size analyzers and automated screening systems demands capital allocation without immediate volume uplift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Aggregates Market |
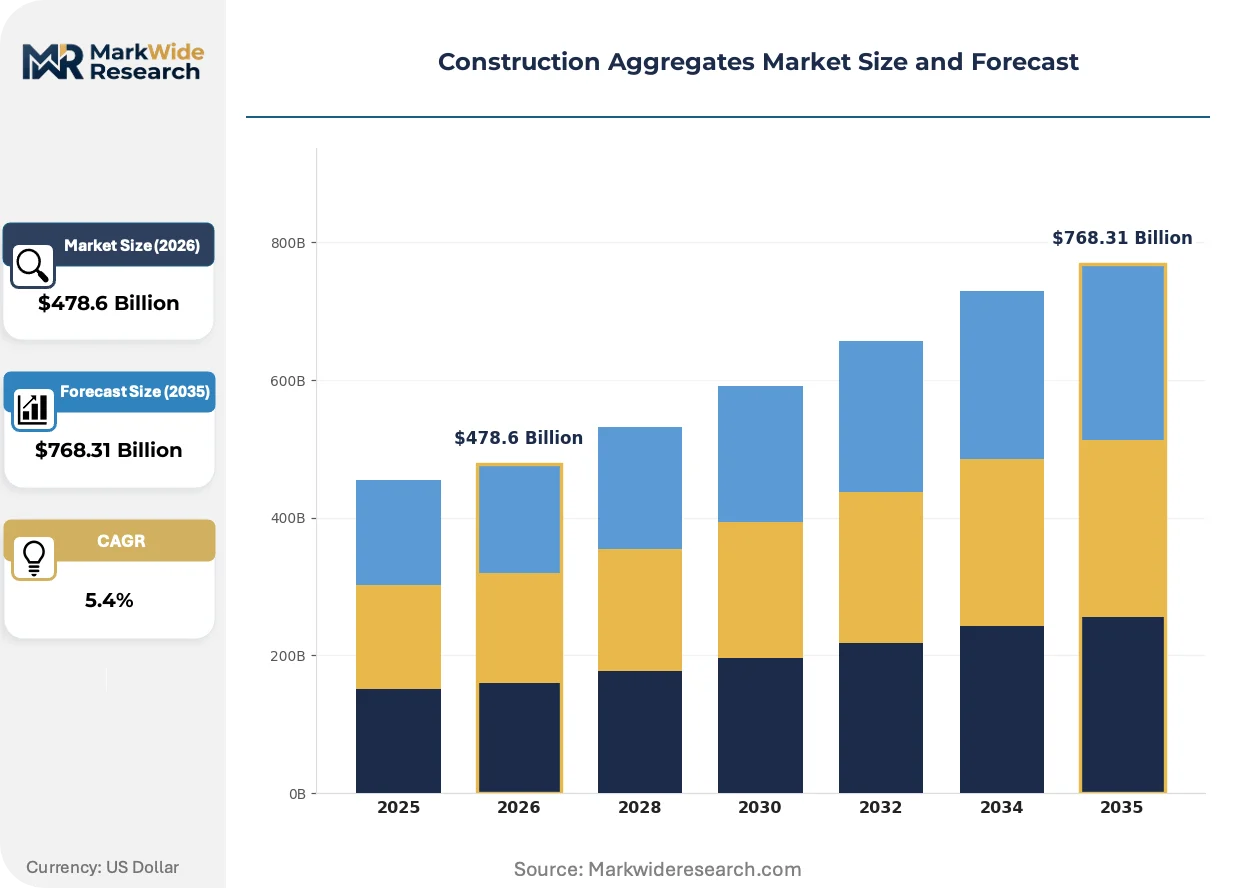
| Market Size in 2026 | $478.6 Billion |
| Market Size in 2035 | $768.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sand, Gravel, Crushed Stone, Recycled Aggregates End Use Industry: Residential Construction, Commercial Construction, Infrastructure, Road Construction Delivery Mode: Bulk Shipment, Bagged Delivery, On-Site Processing, Retail Supply Quality Grade: Fine Aggregate, Coarse Aggregate, Premium Quality, Standard Quality |
| Companies Covered | Vulcan Materials Company, Martin Marietta Materials, CRH plc, Heidelberg Materials, CEMEX SAB de CV, Holcim Ltd., Summit Materials, China Resources Cement Holdings Limited, EUROCEMENT Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Aggregates Market Emerging Trajectories
Digital quarry management and automated quality control systems are compressing extraction-to-delivery cycles while elevating specification consistency for infrastructure-grade applications.
Mobile crushing and screening plants with integrated sensor-based sorting is supplanting fixed-plant configurations for remote infrastructure projects. Mining contractors in Australia and Canada are deploying these units to eliminate haulage from pit to processing. The technology is supplanting traditional centralized processing models and enabling just-in-time aggregate supply for linear construction corridors.
EU Green Deal embodied carbon thresholds are redirecting procurement toward verified low-carbon aggregate sources with third-party certification. Ready-mix concrete producers in Germany and France are now requiring environmental product declarations for all structural-grade inputs. High-specification infrastructure concrete segments are absorbing compliance costs and passing through premium positioning to certified suppliers.
Buyers are consolidating supplier relationships around integrated material-carbon-logistics offerings rather than spot-market commodity purchasing. Large infrastructure developers in India and Brazil are negotiating multi-year offtake agreements with embedded emission reduction trajectories. This pattern is most visible in transport megaprojects where aggregate represents the dominant embodied carbon category.
Construction Aggregates Market Segmentation
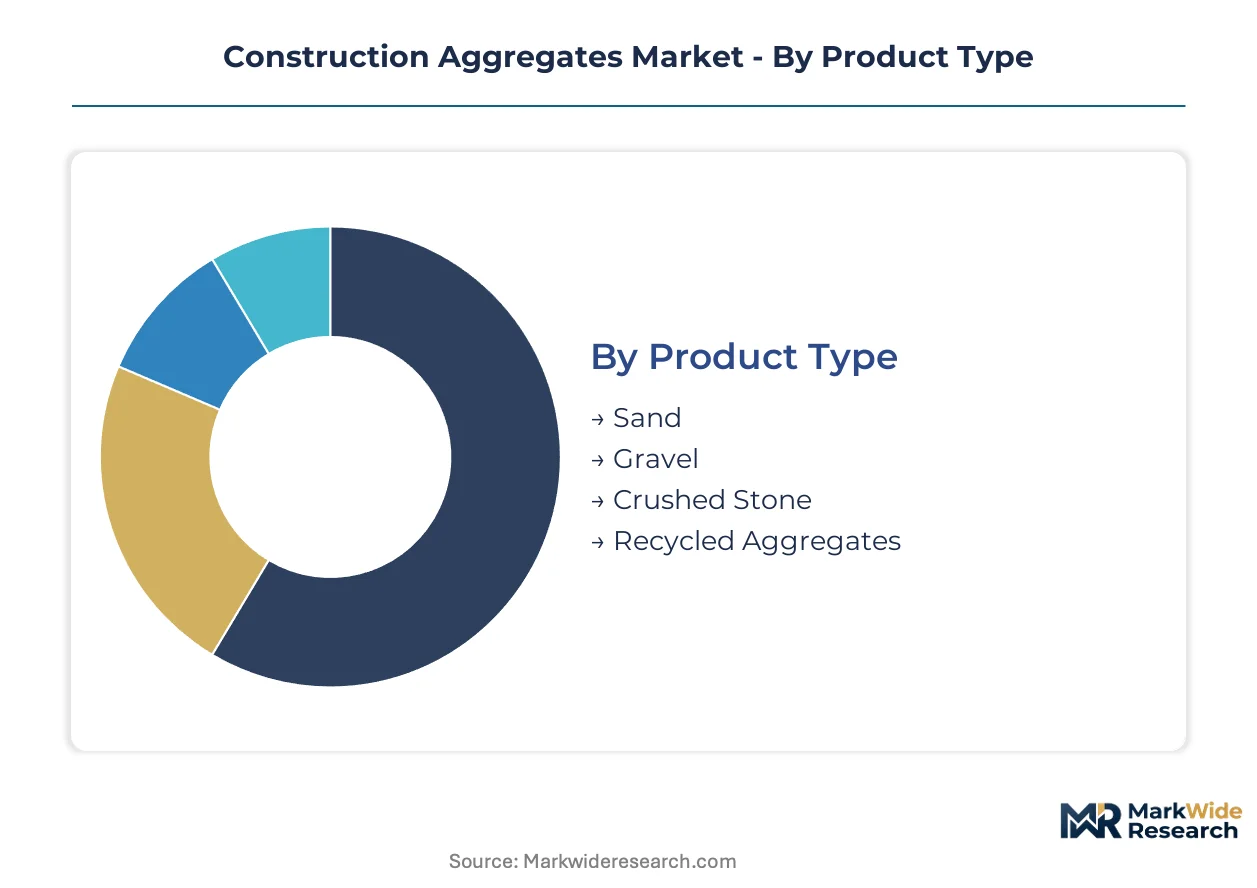
Construction aggregates markets fragment across four distinct dimensions that determine pricing power and procurement patterns. Product type and quality grade define technical specification tiers, while delivery mode and end-use industry shape logistics economics and contract structures.
Product Type:
Margin pools concentrate in high-specification crushed stone and certified recycled aggregates as environmental compliance premiums widen price spreads.
- Crushed Stone:Mechanically crushed rock with controlled particle size distributions from 4.75 mm to 75 mm, engineered for structural concrete and asphalt base courses. Infrastructure megaprojects across India and China are absorbing premium-grade output for high-performance concrete specifications. MEE enforcement actions in China are compressing informal supply and elevating certified producer pricing power.
- Recycled Aggregates:Processed demolition waste meeting GB standards for specified particle sizes and contaminant thresholds. Urban mining operations in Shanghai and Mumbai leverage feedstock proximity to undercut virgin material delivered costs. EU Green Deal embodied carbon thresholds are redirecting German and French procurement toward third-party certified sources.
- Sand:Natural or manufactured granular material below 4.75 mm, sustaining mature volume positions in residential and commercial construction.
- Gravel:Unconsolidated rock fragments used in drainage applications and concrete blending, facing quality grade compression as high-specification demand migrates toward crushed stone.
Crushed stone holds installed capacity. Recycled aggregates is rotating up the share rankings.
End Use Industry:
Application concentration varies sharply by project scale, with linear infrastructure corridors consuming disproportionate tonnage against fixed-site construction.
- Infrastructure:Transport corridors, dams, and utility foundations requiring certified structural-grade aggregates with verified environmental product declarations. Asia-Pacific governments are consolidating procurement around multi-year offtake agreements with embedded emission trajectories. Carbon border adjustment mechanisms are elevating documentation burdens for export-bound shipments.
- Road Construction:Asphalt base and surface courses consuming high-friction crushed stone with specified Los Angeles abrasion values. Australian and Canadian mining contractors are deploying mobile crushing units to eliminate haulage from pit to processing for remote linear projects.
- Residential Construction:Volume-driven demand for standard-grade sand and gravel in foundation and flatwork applications.
- Commercial Construction:Mid-tier specification requirements for structural concrete in building frames and parking structures.
Infrastructure commands contract tenure. Road construction is gaining procurement sophistication fastest.
Delivery Mode:
Logistics configuration directly determines landed cost competitiveness, with bulk shipment and on-site processing capturing divergent margin structures.
- Bulk Shipment:Rail and barge movements of unprocessed or minimally processed material from coastal quarries to urban demand centers. Diesel price volatility constrains inland operator pricing power regardless of reserve quality.
- On-Site Processing:Mobile crushing and screening plants with integrated sensor-based sorting deployed at remote infrastructure corridors. Telematics and autonomous haul truck deployment are compressing extraction costs at mature quarry sites.
- Bagged Delivery:Packaged specialty aggregates for repair and maintenance applications requiring precise quantity control.
- Retail Supply:Localized distribution to small contractors and residential consumers through building material merchants.
Bulk shipment dominates tonnage throughput. On-site processing is climbing the fastest as project owners internalize logistics control.
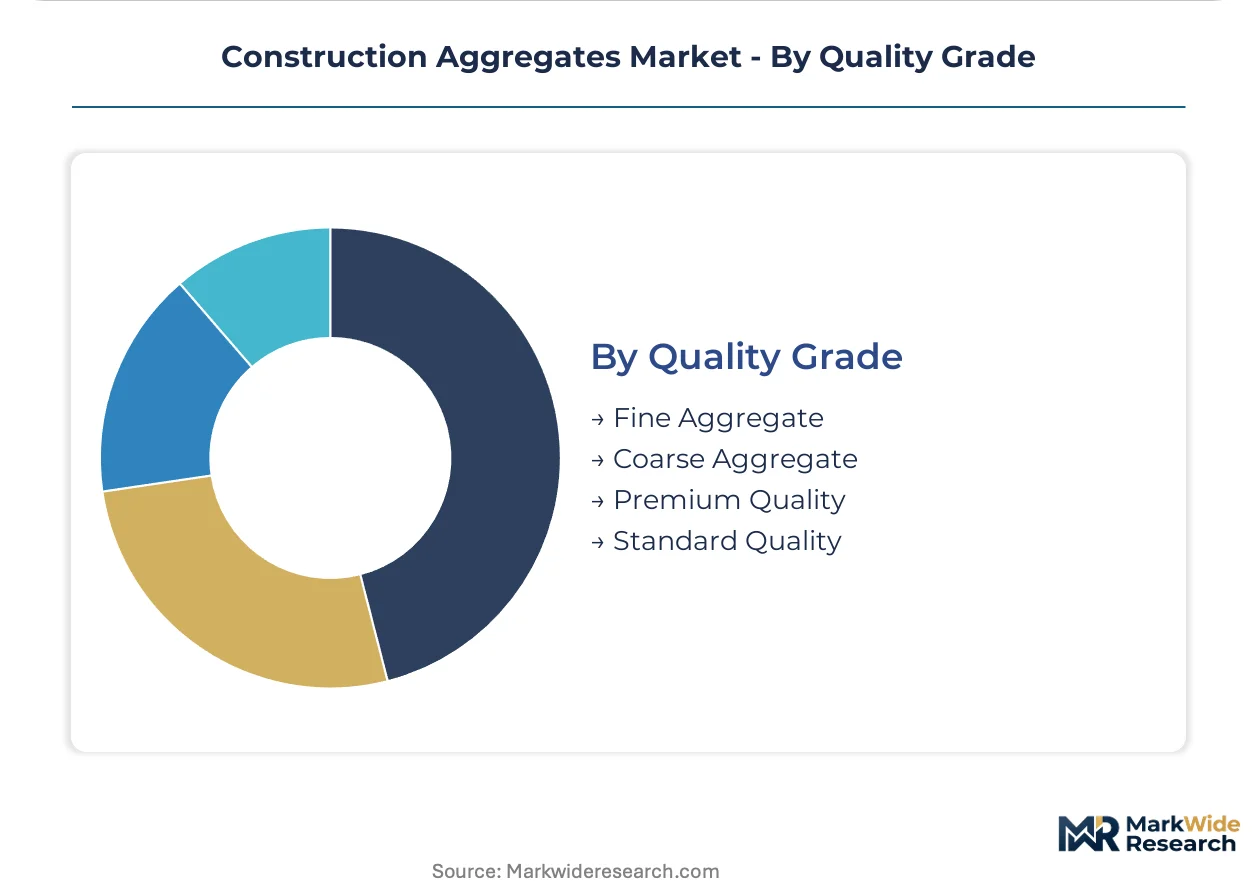
Quality Grade:
Certification tiering is fragmenting procurement pools as building-level environmental product declarations and carbon thresholds proliferate.
- Premium Quality:Aggregates meeting stringent particle shape, cleanliness, and carbon intensity specifications for high-performance infrastructure concrete. Ready-mix producers in Germany and France now require environmental product declarations for all structural-grade inputs. Carbon capture integration at limestone calcination facilities is creating compliant supply channels.
- Coarse Aggregate:Retained material above 4.75 mm serving as concrete skeleton and asphalt structural layer, with specification tightening around flakiness index and crushing value.
- Fine Aggregate:Material passing 4.75 mm sieve controlling concrete workability and surface finish quality.
- Standard Quality:General construction grades facing margin compression as procurement consolidates around certified tiers.
Premium quality commands specification premiums. Coarse aggregate is rotating up the share rankings as infrastructure concrete volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands pricing power through MEE enforcement compression of informal supply, while India absorbs volume expansion at thinner margins. This asymmetry shapes procurement patterns across Asia-Pacific infrastructure corridors.
China
MEE enforcement actions shuttered thousands of unlicensed quarries in 2023-2024, redirecting procurement toward certified producers with verified emission controls. GB standards for recycled concrete content now mandate minimum demolition waste recovery ratios in municipal construction. The Yangtze River Delta cluster around Shanghai operates the country's densest urban mining infrastructure, processing construction debris into specification-grade aggregate for metro expansion projects.
India
National Infrastructure Pipeline allocations for transport corridors pull premium crushed stone into high-performance concrete specifications. BIS quality certification requirements are tightening material traceability for government-procured projects. The Mumbai-Pune industrial corridor concentrates mobile crushing and screening deployment for linear highway construction, eliminating haulage costs through pit-side processing.
United States
OSHA respirable crystalline silica limits elevate dust suppression capital requirements at limestone facilities serving infrastructure markets. EPA stormwater regulations compress permitting timelines for greenfield quarry development in the Southeast. The I-85 corridor through Georgia and the Carolinas anchors regional pricing power for reserve-rich operators with rail-linked distribution networks.
Germany
EU Green Deal embodied carbon thresholds redirect ready-mix procurement toward verified low-carbon aggregate sources with third-party environmental product declarations. REACH substance restrictions limit certain additive chemistries in asphalt base applications. The Rhine-Ruhr industrial cluster integrates carbon capture pilot installations at select limestone calcination facilities, accessing premium procurement pools for infrastructure concrete.
Australia
Mining contractors deploy mobile crushing and screening plants with integrated sensor-based sorting to eliminate haulage from remote pit to processing. State-level quarry licensing requirements vary across Queensland and Western Australia, creating regulatory arbitrage opportunities for multi-state operators. The Pilbara iron ore corridor drives demand for specification-grade road base materials in haul road maintenance and expansion.
Construction Aggregates Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with carbon-capture integrators commanding premium positioning while reserve-scale operators defend volume share. The market structures around three tiers: multinational building materials conglomerates with backward integration into cement production, regional specialists with captive reserve bases and rail-linked distribution, and emerging urban mining operators exploiting demolition waste feedstock proximity. Dominant competitive moves include M&A consolidation of fragmented regional quarry assets and strategic partnerships between aggregate producers and ready-mix concrete operators for integrated material-carbon-logistics offerings.
Among North American reserve-scale operators, Vulcan Materials Company and Martin Marietta Materials exemplify the regional specialist archetype with extensive southeastern United States footprints. CRH plc occupies a position within the multinational conglomerate tier, representing integrated construction materials chains spanning multiple continents. Heidelberg Materials anchors the decarbonization-focused vector through carbon capture pilot installations at limestone facilities.
| Leading Market Players |
|---|
| Vulcan Materials Company |
| Martin Marietta Materials |
| CRH plc |
| Heidelberg Materials |
| CEMEX SAB de CV |
| Holcim Ltd. |
| Summit Materials |
| China Resources Cement Holdings Limited |
| EUROCEMENT Group |
| Others |
Supply Flow & Price Mechanics
Recycled aggregate substitution for virgin crushed stone is compressing price spreads between compliant and non-certified supply channels while redrawing logistics economics around urban demolition waste proximity. China's GB standards for recycled concrete content and EU Green Deal embodied carbon thresholds simultaneously elevate certification premiums and penalize long-haul virgin material movements.
Pricing Analysis
Price spreads between coastal quarry operators and inland competitors widen sharply when diesel volatility spikes, compressing delivered-cost competitiveness for rail-unlinked producers. Contract-based long-term offtake agreements dominate infrastructure procurement, with price differentiation driven by certification tier and carbon intensity verification. Pricing pressure stems from MEE enforcement compression of informal Chinese supply, which elevates certified producer margins while squeezing uncertified competitors. Residential construction buyers exhibit highest price sensitivity, while infrastructure developers absorb compliance premiums for verified low-carbon grades.
Supply Chain Analysis
Inventory cycles at limestone calcination facilities stretch during monsoon seasons in India and typhoon windows in China's Yangtze River Delta, forcing just-in-time adjustments at ready-mix plants. Supply concentrates in China, India, and the United States, with extraction anchored in limestone belts, alluvial deposits, and hard-rock formations respectively. Raw material flows draw from quarry reserves, demolition waste streams, and manufactured sand processing. Single-source vulnerability concentrates around specialized abrasion-resistant crushing wear parts sourced from limited foundry capacity. Distribution runs through rail-linked bulk shipment to urban demand centers, supplemented by barge movements on navigable waterways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks infrastructure investment cycles, with Asia-Pacific transport corridor allocations providing the current demand pulse. Recovery durability hinges on sustained government procurement commitment through multi-year offtake structures.
For Market Incumbents: Consolidate fragmented regional quarry assets around rail-linked reserve bases to defend pricing power against diesel volatility erosion. Acquire urban mining operators in Shanghai and Mumbai to capture demolition waste feedstock proximity advantages. Carbon capture integration at limestone facilities represents the critical certification lever for EU Green Deal compliance premiums. For New Entrants and Emerging Players: Lead with mobile crushing and screening deployment for remote linear infrastructure projects in Australia and Canada, where haulage elimination commands procurement preference. Target recycled aggregate production in dense demolition waste corridors lacking compliant processing capacity. Position around environmental product declaration certification as the differentiated entry credential for German and French ready-mix supply chains. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists holding southeastern United States reserve positions but lacking carbon-capture integration or backward cement linkages. Five-to-ten-year viability favors operators with verified low-carbon sourcing and multi-year infrastructure offtake visibility. Monitor carbon border adjustment mechanism implementation timelines as the inflection signal for certified supply channel premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Limestone facilities with pilot installations access EU Green Deal premium procurement pools in Germany. |
| Urban Mining Infrastructure | Shanghai and Mumbai demolition waste processing compresses feedstock costs against virgin material haulage. |
| Mobile Processing Deployment | Australian and Canadian mining contractors eliminate pit-to-plant haulage for remote linear projects. |
| Rail-Linked Distribution Expansion | Southeastern United States reserve-rich operators sustain delivered-cost competitiveness against diesel volatility. |
| Environmental Product Declaration Certification | Third-party verification opens German and French structural-grade aggregate procurement to compliant suppliers. |
Methodological Framework
The analysis maps crushed stone, recycled aggregates, sand, and gravel sub-sectors, each validated through quarry operations managers, ready-mix procurement directors, infrastructure project developers, and environmental compliance officers. Primary interview findings triangulate against customs trade data, EPA and MEE enforcement records, SEC 10-K filings for listed materials companies, and EU EPD database entries. Bottom-up reserve-base modeling and top-down infrastructure spend allocation provide cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product type, quality grade, delivery mode, and end-use industry, with CAGRs derived from reserve depletion rates and infrastructure pipeline absorption capacity. Forecast inputs incorporate diesel price elasticity coefficients and carbon intensity verification adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained public infrastructure commitment or accelerated carbon border adjustment implementation would require recalibration. Forecasts reflect documented assumptions around regulatory enforcement intensity and demolition waste recovery protocol maturation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
North America Industrial Flooring Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
US Glass Curtain Wall Market