
 Roofing Shingles Market | 2026-2036
Roofing Shingles Market Size, Share, and Industry Trends Forecast 2026-2036
Roofing Shingles Market Outlook
Impact-resistant product style upgrades is redrawing competitive positioning across the Roofing Shingles Market. Owens Corning leverages proprietary laminate technology to sustain premium positioning in wind-prone regions. GAF Materials Corporation anchors its volume leadership through backward integration into asphalt supply and extensive contractor certification networks. CertainTeed Corporation differentiates via multi-brand architecture spanning architectural and designer tiers.
Roofing shingles are overlapping, flat or curved elements installed in courses from the roof's lower edge upward, typically manufactured from fiberglass-reinforced asphalt saturated with mineral granules for UV protection and fire resistance, designed to shed water and protect structural decking. The primary purpose is to provide weatherproof, durable roof covering for residential and commercial buildings at manageable installed cost. Asphalt material type commands the dominant volume share due to cost efficiency and established contractor familiarity, while metal material type captures expanding share in commercial end-user segments seeking extended service life. Architectural product style generates the thickest margin pools as homeowners trade up from three-tab equivalents, and impact-resistant variants within the product style dimension are gaining fastest in coastal residential applications where insurance discounts offset premium pricing.
ASTM International sets wind-resistance and impact-testing protocols that manufacturers must meet for product certification and building code acceptance, while the EPA administers stormwater regulations affecting cool-roof granule formulations and runoff characteristics. State-level building codes in Florida and Texas incorporate enhanced wind-speed requirements that effectively filter lower-tier products from those markets. Stakeholders must monitor evolving insurance industry loss-mitigation incentives, as these increasingly dictate homeowner product selection ahead of raw material cost movements.
Market Dynamics
Insurance loss-mitigation incentives are restructuring demand patterns across the Roofing Shingles Market, compelling manufacturers to prioritize impact-resistant certifications over raw material cost advantages. Florida and Texas building codes now function as de facto product filters, excluding conventional three-tab shingles from coastal installation eligibility.
Growth Catalysts
- ASTM D7158 wind-resistance standards:Enhanced certification requirements in hurricane-prone zones are accelerating replacement cycles as homeowners seek insurance premium reductions through compliant installations.
- Cool-roof granule formulations:EPA stormwater management guidelines are driving specification upgrades that favor reflective mineral coatings with documented runoff reduction performance.
- Sun Belt residential retrofit concentration:Aging housing stock across Arizona, Florida, and Texas is generating sustained reroofing volume as insurance carriers mandate impact-resistant upgrades for policy renewal.
Market Restraints
- Asphalt binder cost volatility:Refinery output fluctuations and competing road-paving demand create margin compression for manufacturers without captive bitumen supply.
- Single-region production concentration:Fiberglass mat supply chains cluster in southeastern US manufacturing corridors, exposing distributors to weather-related logistics disruptions.
- Metal roofing substitution:Extended service life claims in commercial segments are diverting specification share from asphalt systems in institutional and light industrial projects.
Strategic Opportunities
- Underpenetrated Midwest impact-resistant conversion:Oklahoma and Kansas represent adjacent hail-prone territories where insurance incentive programs remain less developed than coastal counterparts.
- Solar-integrated shingle convergence:Building-integrated photovoltaic laminates are creating specification overlap with traditional roofing as Tesla Energy and GAF Timberline Solar establish contractor training networks.
- Direct-to-contractor digital platforms:Bypassing traditional two-step distribution through proprietary ordering applications is capturing specification data and loyalty from independent roofing crews.
Industry Challenges
- Certified installer capacity constraints:Manufacturer warranty programs require trained contractor networks, creating bottlenecks in high-demand storm recovery periods.
- Granule supply reconfiguration:Ceramic-coated mineral sourcing shifts are forcing reformulation timelines that delay new product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roofing Shingles Market |
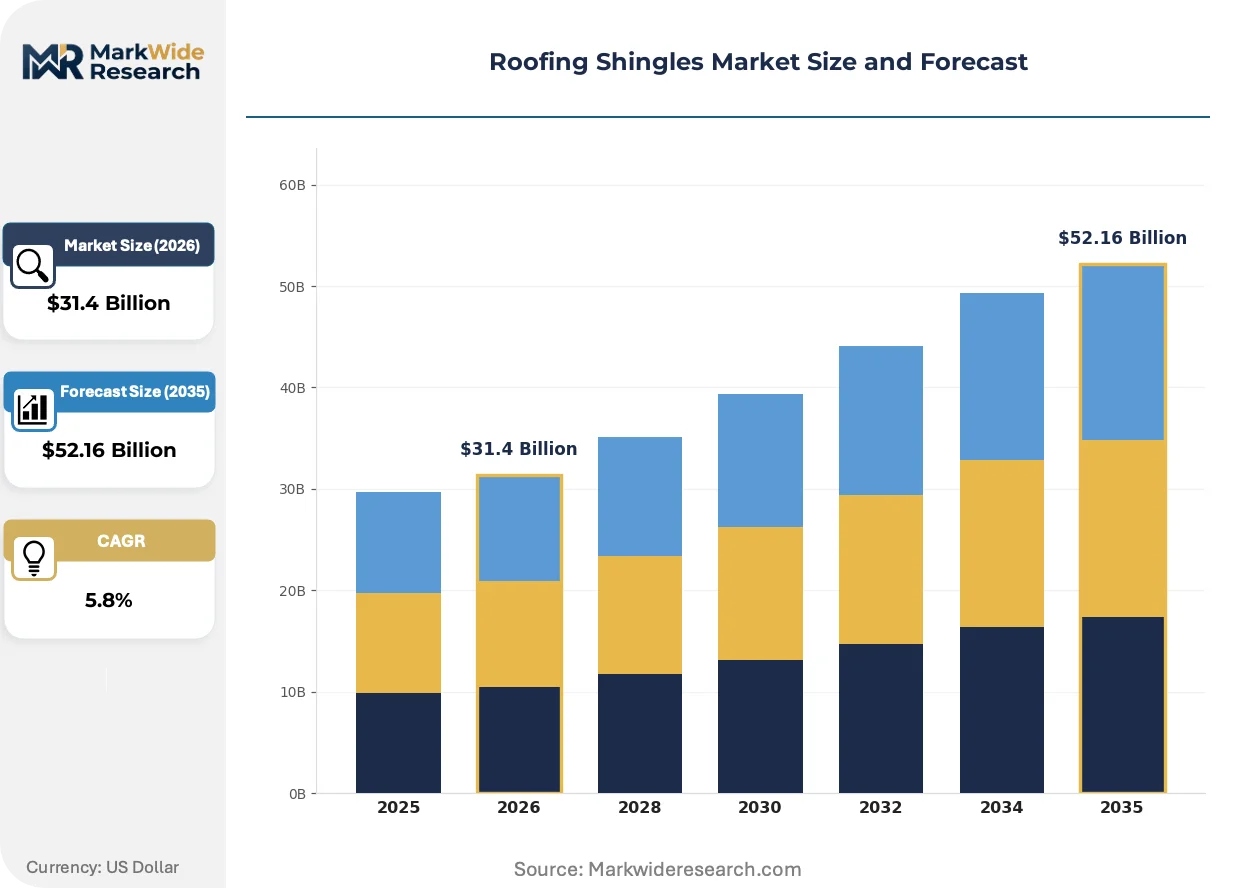
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $52.16 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Asphalt, Wood, Metal, Slate Product Style: Architectural, Three-Tab, Designer, Impact-Resistant Installation Method: Self-Adhered, Mechanically Attached, Hot-Mopped, Cold Applied End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | GAF Materials Corporation, Owens Corning, CertainTeed Corporation, IKO Industries Ltd., TAMKO Building Products, Atlas Roofing Corporation, Malarkey Roofing Products, Interlock Roofing Ltd., BP Building Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roofing Shingles Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine product performance expectations. Manufacturers now compete on certification depth rather than price alone.
Polymer-modified asphalt formulations are fragmenting the traditional performance hierarchy. These elastomer-enhanced binders deliver Class 4 impact ratings without sacrificing installation familiarity. High-end residential buyers in hail corridors are specifying these systems despite 40-60% cost premiums. The technology is fragmenting contractor expertise into certified and non-certified installation tiers.
ASTM D3462 quality standards are tightening granule adhesion requirements. Revised testing protocols now simulate accelerated UV degradation and thermal cycling. Architectural product lines face disproportionate compliance costs as mineral coating weights increase. Manufacturers with in-house granule processing capabilities are absorbing specification share from outsourced competitors.
Insurance-driven specification behavior is compressing traditional decision timelines. Homeowners in catastrophe-exposed counties now prioritize carrier-approved product lists over aesthetic preferences. Independent roofing contractors are ceding specification influence to insurance adjusters and mortgage servicers. This shift is most pronounced in Florida's wind-borne debris regions and Texas hail alleys.
Roofing Shingles Market Segmentation
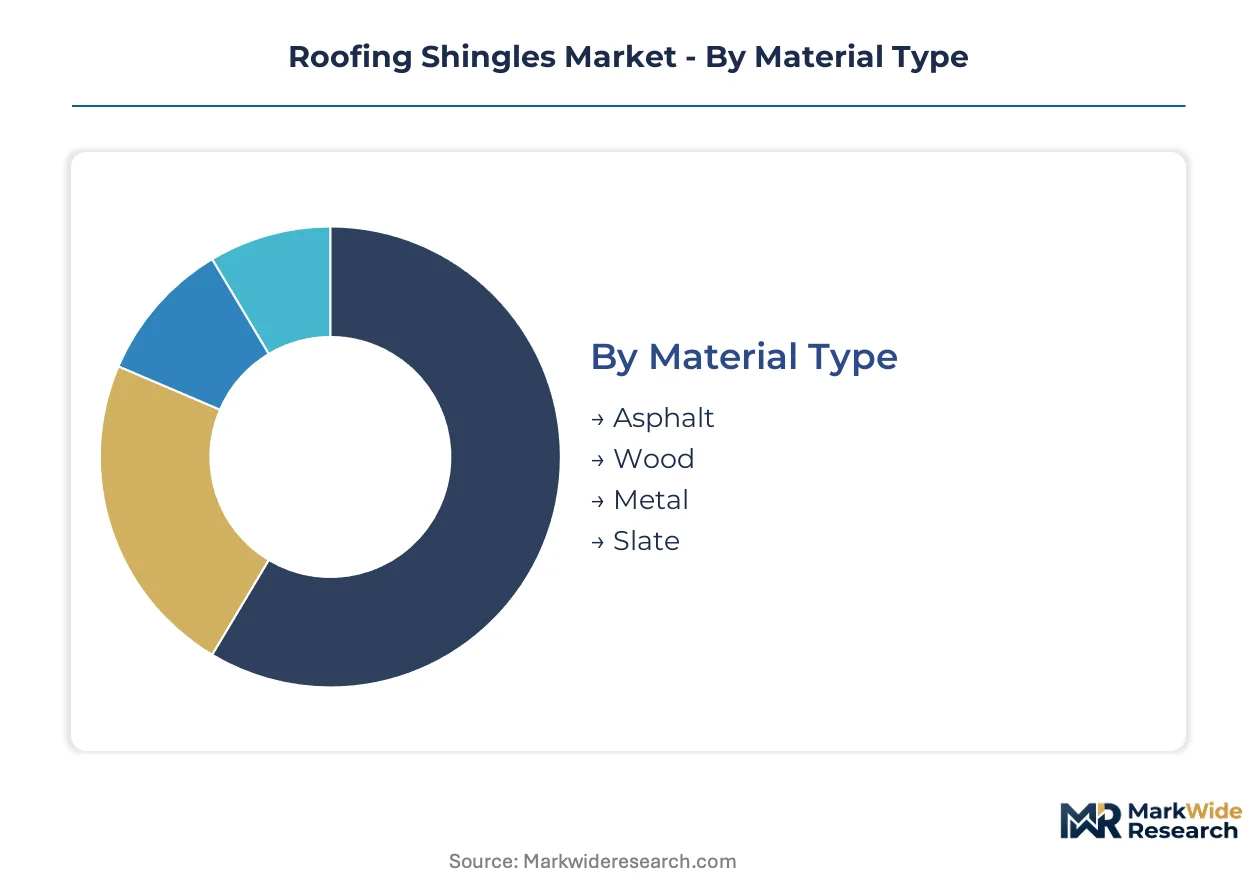
Segmentation in roofing shingles reveals how specification authority migrates across stakeholders. Insurance carriers, building code officials, and contractor networks each dominate different purchase moments depending on material and end-use context.
Material Type:
Metal systems pose the sharpest substitution threat to conventional asphalt in commercial applications where lifecycle cost calculations override installed price sensitivity.
- Asphalt:Fiberglass-reinforced mats saturated with oxidized or polymer-modified bitumen and surfaced with ceramic-coated mineral granules deliver Class A fire ratings at the lowest installed cost per square. Demand concentrates in United States Sun Belt residential retrofit as Florida and Texas building codes mandate wind-resistant formulations for coastal zones, though asphalt binder cost volatility compresses margins for manufacturers without captive refinery supply.
- Metal:Standing seam and modular panel systems fabricated from steel, aluminum, or copper alloys achieve 50-70 year service life with reflective coatings that reduce cooling loads. Commercial end-users in institutional and light industrial segments specify these systems where extended ownership horizons justify premium first costs, diverting specification share from asphalt in projects with 20-year-plus capital planning cycles.
- Wood:Cedar shakes and shingles deliver natural aesthetic differentiation in high-end residential markets with strict fire-code exemptions, requiring pressure-treated fire-retardant formulations for code compliance in wildland-urban interface zones.
- Slate:Natural stone quarried in Vermont, Virginia, and Pennsylvania provides century-scale durability for historic preservation and luxury residential applications where authentic material specification outweighs weight and structural load considerations.
Asphalt anchors the volume base while metal gains share at the steepest rate in commercial specification channels.
Product Style:
Margin stratification across product tiers reflects how certification depth separates premium positioning from commodity competition.
- Architectural:Multi-layer laminate construction with dimensional thickness and shadow lines mimics cedar shake or slate appearance at asphalt cost structures. Sun Belt homeowners trade up from three-tab equivalents as insurance discounts for wind-resistant installations offset 25-40% price premiums, concentrating demand in Florida, Texas, and Arizona replacement cycles.
- Impact-Resistant:Polymer-modified asphalt formulations achieve UL 2218 Class 4 hail ratings through rubberized binder flexibility and reinforced mat structures. Oklahoma and Kansas hail corridors drive adoption as carriers expand premium reduction programs inland from coastal origins, creating the steepest expansion trajectory among all product styles.
- Three-Tab:Single-layer strip shingles with uniform rectangular profiles and exposed fastener lines serve economy residential segments where first cost dominates specification and code minimums permit installation.
- Designer:Premium laminate profiles with proprietary color blending and enhanced shadow lines target luxury residential markets where aesthetic differentiation commands 60-80% premiums over architectural equivalents.
Architectural styles dominate current revenue pools while impact-resistant variants climb the fastest as insurance incentives restructure coastal and hail-belt demand.
Installation Method:
Application technique segmentation tracks labor availability constraints and code-driven performance requirements across climate zones.
- Self-Adhered:Pressure-sensitive adhesive membranes eliminate torch or hot asphalt requirements, accelerating installation in wind-belt regions where mechanical fastening alone fails enhanced uplift testing.
- Mechanically Attached:Fastener-driven systems using corrosion-resistant nails or screws dominate steep-slope residential applications where substrate penetration provides primary wind resistance.
- Hot-Mopped:Molten asphalt application for built-up roofing systems persists in commercial low-slope segments despite labor intensity and safety code restrictions.
- Cold Applied:Solvent or water-based adhesive systems reduce VOC exposure and fire risk in occupied building retrofits where hot work permits are impractical.
Mechanically attached methods retain the largest installer base while self-adhered systems expand most quickly in high-wind code jurisdictions.
End User:
Customer-type segmentation exposes divergent purchase authority structures between homeowner-driven and specification-driven channels.
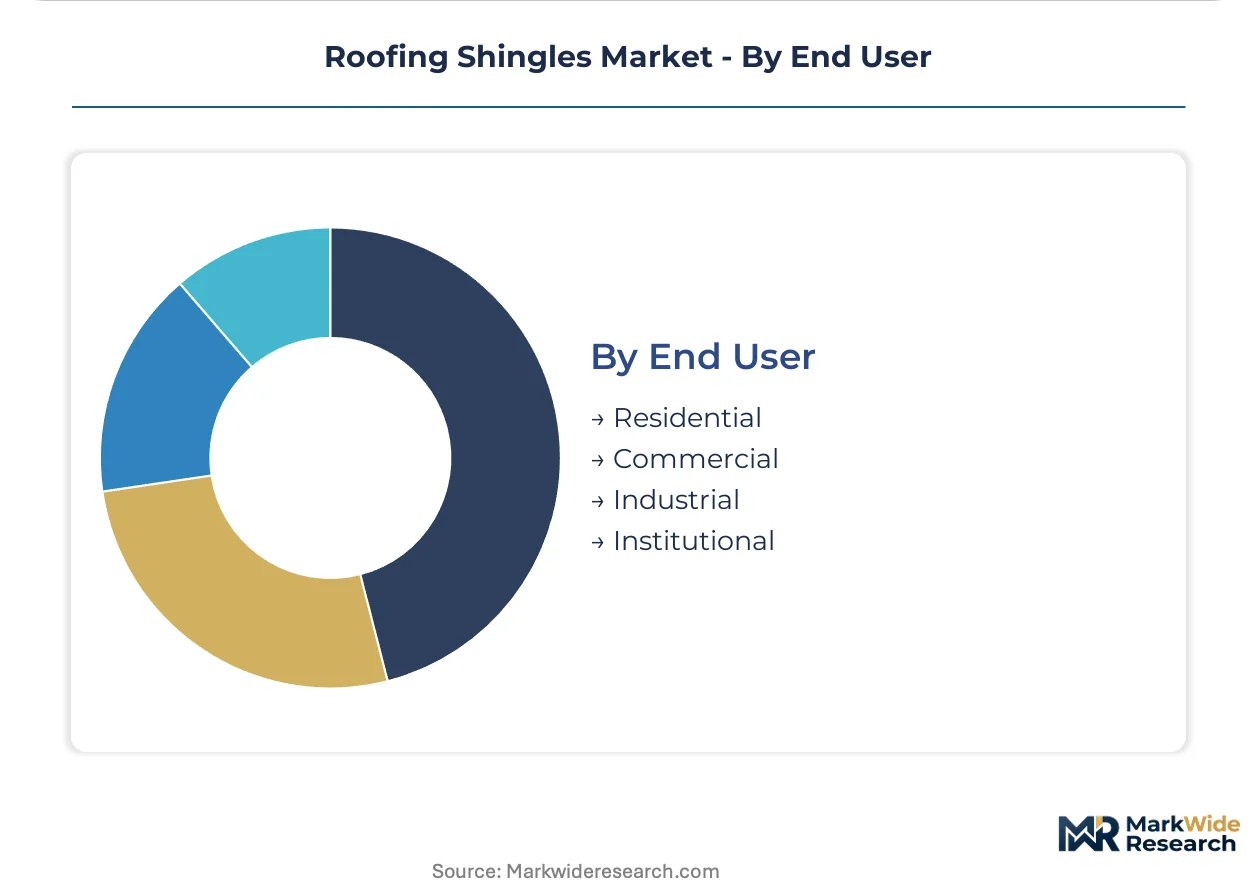
- Residential:Single-family and multifamily buildings where insurance adjusters and mortgage servicers increasingly override homeowner aesthetic preferences in catastrophe-exposed counties, compressing decision timelines and filtering product eligibility.
- Commercial:Office, retail, and hospitality properties where facility managers prioritize lifecycle cost and warranty transferability, creating specification openings for metal and modified bitumen alternatives to asphalt.
- Industrial:Manufacturing and warehouse facilities with large roof areas where structural load capacity and chemical resistance drive material selection toward metal or single-ply membrane systems.
- Institutional:Schools, hospitals, and government buildings with extended ownership horizons and public procurement protocols that favor documented performance history and competitive bidding compliance.
Residential channels generate the highest unit volume while commercial segments show the fastest specification migration toward extended-service-life alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bitumen refinery capacity and fiberglass mat manufacturing cluster disproportionately in the southeastern United States, creating supply dependencies that amplify regional demand swings. This concentration pattern shapes how coastal building codes propagate through distribution networks.
United States
Florida and Texas drive retrofit volume as insurance carriers mandate impact-resistant installations for policy renewal in wind-borne debris zones. The EPA administers stormwater guidelines that favor cool-roof granule formulations with documented runoff reduction. Manufacturing corridors in Georgia and Alabama supply fiberglass mat substrate to contractors across the Sun Belt.
Canada
Alberta and Saskatchewan hail corridors generate demand for Class 4 impact-rated systems as property insurers expand premium discount programs. Health Canada oversees building material safety standards that align with provincial energy efficiency codes. Calgary and Edmonton distribution hubs serve prairie reroofing cycles tied to agricultural and resource-sector housing.
Mexico
Northern border states experience specification migration toward ASTM-compliant products for maquiladora facility roofing and cross-border residential development. The country's national construction regulator enforces seismic and wind-load standards that filter product eligibility in Baja California and Chihuahua. Monterrey manufacturing clusters produce asphalt compounds for regional distribution.
Germany
Bavaria and Baden-Württemberg commercial construction favors extended-service-life metal systems over asphalt in institutional projects with 30-year capital planning horizons. The KBA and federal building codes enforce energy performance standards that privilege reflective roofing membranes. Stuttgart and Munich engineering consultancies specify lifecycle cost analyses that disadvantage first-cost-optimized materials.
China
Yangtze River Delta and Pearl River Delta urban renewal projects specify polymer-modified bitumen systems for high-density residential mid-rise construction. The Ministry of Ecology and Environment administers dual carbon goals that pressure manufacturers toward lower-emission production processes. Shanghai and Guangzhou municipal procurement protocols favor domestic certification over imported ASTM equivalency.
Roofing Shingles Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium positioning depends on certification depth rather than scale alone. The market consolidates around manufacturers with captive asphalt supply and in-house granule processing capabilities. Two archetypes dominate: vertically integrated volume leaders controlling upstream bitumen production, and specialty laminate innovators competing on impact-resistance ratings. Competitive moves concentrate on backward integration into refinery operations and contractor certification network expansion.
Among North American building materials specialists, GAF Materials Corporation, Owens Corning, and CertainTeed Corporation occupy positions that exemplify the integrated-volume archetype. These entities represent the convergence of asphalt supply control, fiberglass mat manufacturing, and extensive contractor training infrastructure that defines competitive viability in code-stringent coastal markets. Their positioning reflects how insurance-driven specification behavior rewards certification depth over price competition in catastrophe-exposed regions.
| Leading Market Players |
|---|
| GAF Materials Corporation |
| Owens Corning |
| CertainTeed Corporation |
| IKO Industries Ltd. |
| TAMKO Building Products |
| Atlas Roofing Corporation |
| Malarkey Roofing Products |
| Interlock Roofing Ltd. |
| BP Building Products |
| Others |
Value Chain & Pricing Dynamics
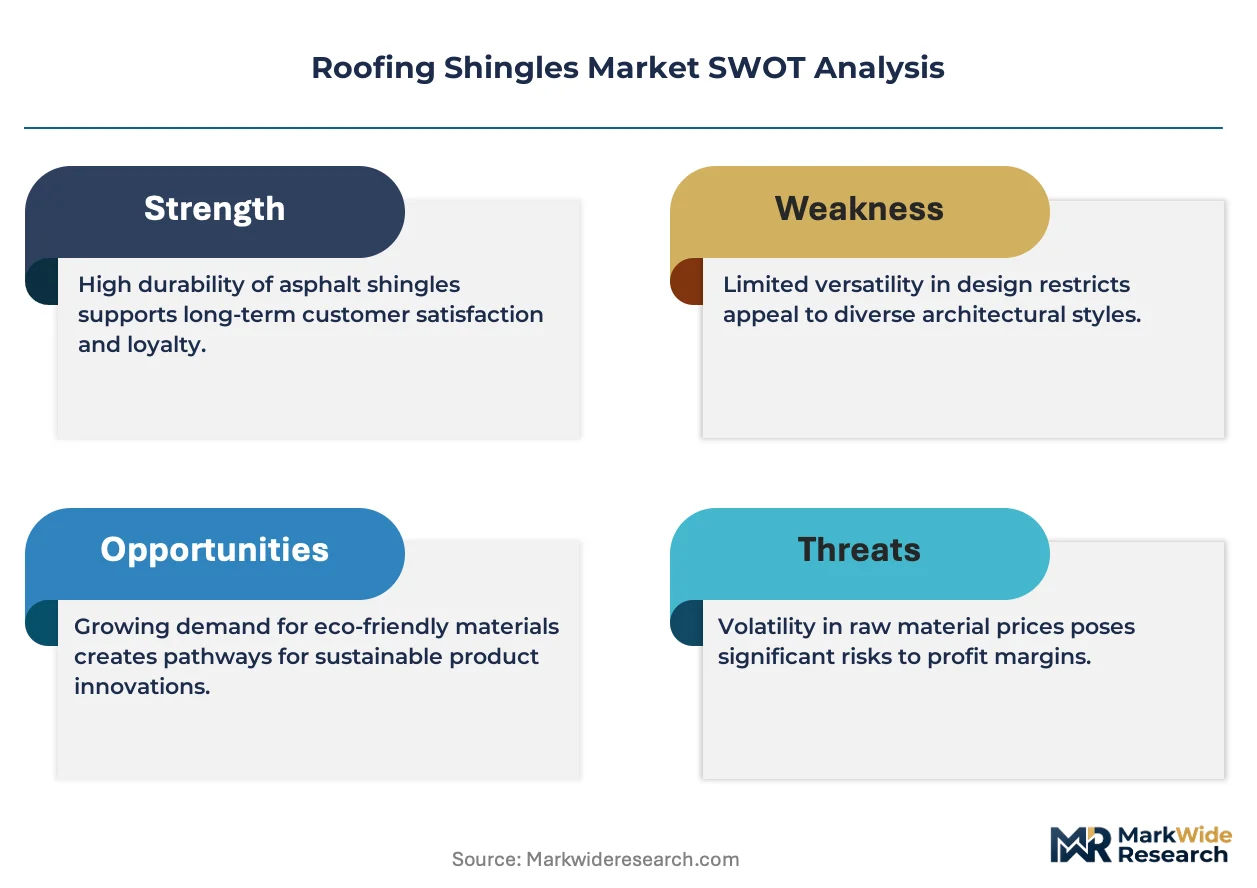
Polymer-modified asphalt displacing conventional oxidized bitumen in impact-resistant formulations is redrawing supply geography toward Gulf Coast refineries while compressing margin structures for manufacturers without captive binder production. This substitution dynamic simultaneously elevates raw material costs and concentrates pricing power among integrated producers.
Pricing Analysis
ASTM D7158 wind-resistance certification dictates the pricing tier structure across residential replacement channels, separating Class 4 impact-rated laminates from three-tab economy products. Three-tier pricing structure across premium impact-resistant, standard architectural, and economy three-tab levels reflects certification depth and insurance discount eligibility. Pricing pressure stems from asphalt binder cost volatility as refinery output competes with road-paving demand. First-cost-sensitive homeowners in inland markets exhibit highest price sensitivity, while coastal policyholders facing renewal mandates show lowest sensitivity due to premium offset calculations.
Supply Chain Analysis
Inbound logistics costs from ceramic-coated mineral granule suppliers concentrate vulnerability at Gulf and Atlantic ports serving southeastern manufacturing corridors. Fiberglass mat production clusters in Georgia, Alabama, and Texas, while asphalt binder supply draws from Texas and Louisiana refinery complexes. Ceramic mineral sourcing rests on Georgia and Tennessee mining operations with limited alternative supply. Single-region production concentration creates weather-related logistics disruption risk. Distribution runs through two-step building materials wholesalers to independent contractor networks, though direct-to-crew digital platforms are fragmenting traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal roofing substitution in commercial segments threatens asphalt volume leadership, compelling incumbents to defend residential retrofit positioning through certification depth and installer network captivity.
For Market Incumbents: Secure captive asphalt supply through refinery partnerships or backward integration into bitumen production to insulate margins from road-paving demand competition. Deepen Class 4 impact-resistant certification coverage across product portfolios to maintain eligibility in Florida and Texas building code jurisdictions. Expand proprietary contractor training networks to lock in specification influence as insurance adjusters override homeowner preferences.
For New Entrants and Emerging Players: Differentiate on solar-integrated shingle convergence by establishing building-integrated photovoltaic laminates with established roofing compatibility. Target Oklahoma and Kansas hail corridors where insurance incentive programs remain underdeveloped relative to coastal markets. Pursue direct-to-contractor digital platform routes to bypass entrenched two-step distribution and capture specification data.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional manufacturers lacking in-house granule processing capabilities. Long-term viability hinges on certification infrastructure and coastal market access rather than scale alone. Watch for EPA stormwater guideline enforcement intensity as signal for cool-roof granule formulation investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Asphalt Supply | Captive bitumen production insulates margins from refinery output competition and road-paving demand spikes. |
| Class 4 Impact-Resistant Certification Expansion | UL 2218 compliance unlocks insurance premium discount eligibility in Florida, Texas, and inland hail corridors. |
| Contractor Training Network Scaling | Proprietary certification programs capture specification loyalty as insurance adjusters dominate purchase decisions. |
| Solar-Integrated Product Development | Building-integrated photovoltaic convergence with traditional roofing creates specification overlap in residential new construction. |
| Direct-to-Contractor Digital Platform Launch | Bypassing traditional distribution captures real-time specification data and reduces channel cost structures. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with roofing contractors, insurance claims adjusters, building code officials, and asphalt refinery procurement managers. Secondary validation drew from EPA stormwater guideline documentation, ASTM International standard publications, state-level building code filings in Florida and Texas, and customs data on ceramic mineral imports. Bottom-up volume estimates from regional reroofing permits triangulated against top-down asphalt consumption figures from refinery output reports.
Across the analysis window, forecasts incorporated material type segmentation by asphalt, metal, wood, and slate; product style tiers spanning three-tab, architectural, impact-resistant, and designer categories; and end-user channels separating residential retrofit from commercial new construction. CAGRs were derived from replacement cycle modeling tied to housing stock age distributions and insurance policy renewal patterns. Inputs included storm frequency databases, building code amendment timelines, and carrier premium discount program expansions.
The analysis sits within stated boundaries; outcomes outside current ASTM certification trajectories and EPA enforcement intensity would require recalibration. Forecasts reflect assumptions on insurance incentive program geographic expansion and asphalt binder supply stability. Practitioners should keep alternative scenarios live as metal roofing substitution rates and solar-integrated product adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
Building Insulation Materials Market
Building & Construction Materials
Brick Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Plastic Decking Market