
 Asphalt Mixing Plants Market | 2026-2036
Asphalt Mixing Plants Market Size, Share, and Industry Trends Forecast 2026-2036
Asphalt Mixing Plants Market Analysis
Recycled asphalt pavement integration with warm mix technology is tilting engineering specifications toward lower-temperature production cycles. MARINI leverages European R&D networks to sustain leadership in modular plant configurations. Ammann Group anchors its position through backward integration into burner and control systems. ASTEC Industries competes aggressively on North American service density and aftermarket parts availability.
An asphalt mixing plant is an industrial facility that combines dried aggregates with bitumen binders at controlled temperatures—typically between 150°C and 180°C for hot mix—to produce paving material for road surfaces and infrastructure layers. The primary purpose is continuous or batch production of homogeneous asphalt concrete meeting precise gradation and viscosity specifications for load-bearing applications. Batch mix systems still command the largest installed base due to formulation flexibility for specialized highway overlays, while drum mix configurations capture preference in high-volume corridor projects where uninterrupted output outweighs recipe-switching needs. Warm mix asphalt technology represents the fastest-expanding segment as road agencies mandate reduced emissions during production and placement.
The EPA enforces National Emission Standards for Hazardous Air Pollutants at stationary asphalt sources, pushing operators toward thermal oxidizers and baghouse upgrades that favor newer plant investments over legacy retrofits. State DOTs including Caltrans and TxDOT embed recycled content minimums into pavement specifications, directly shaping technology selection across supplier portfolios. Stakeholders must monitor how evolving carbon accounting rules for infrastructure procurement reshape the total cost of ownership calculation between conventional and low-temperature mixing systems.
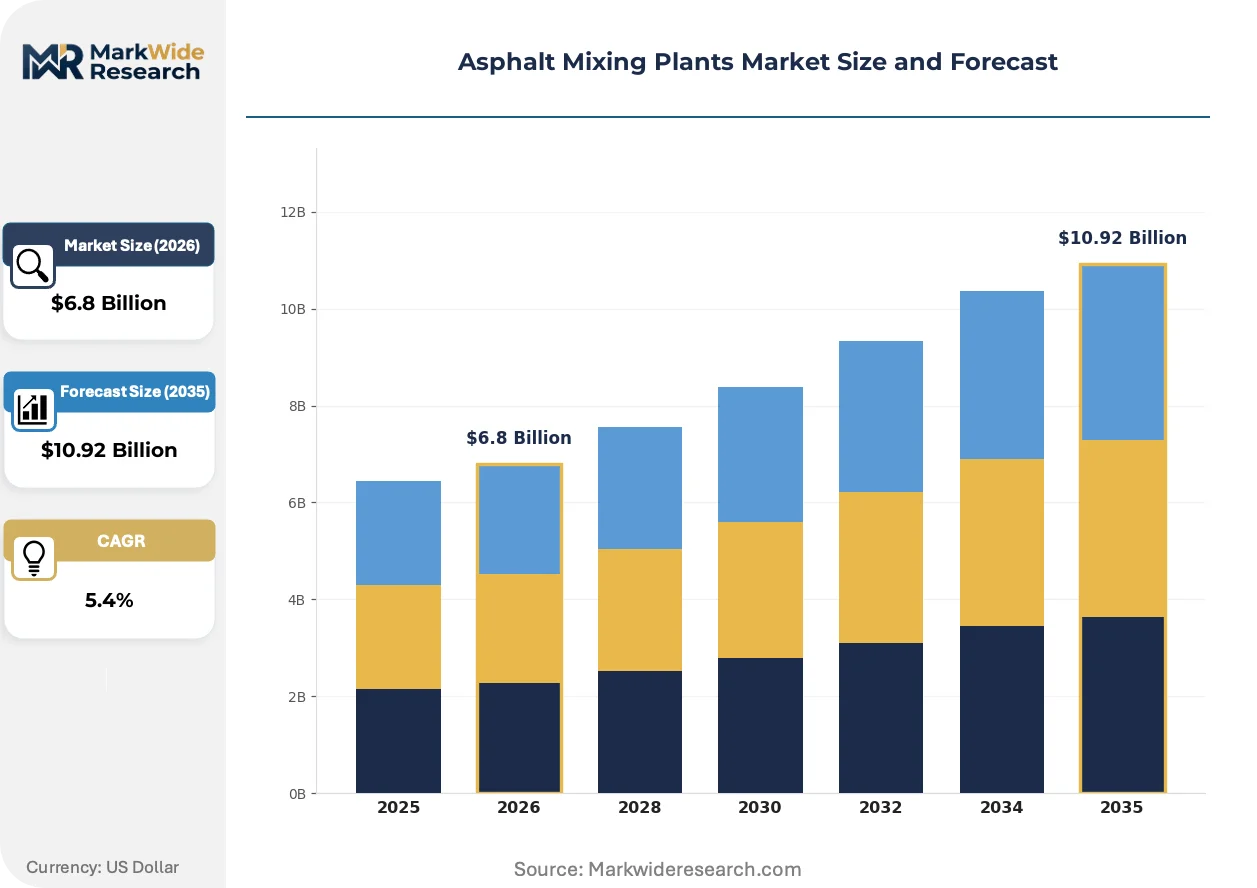
Market Dynamics
Warm mix asphalt technology is compressing the temperature differential between conventional hot mix and emerging low-carbon production methods, forcing capital allocation decisions across installed plant bases.
Growth Catalysts
- India National Highway Development:The Bharatmala Pariyojana program mandates continuous-feed drum mix capacity for corridor widening projects, pulling equipment orders toward higher-output configurations.
- EPA NESHAP Standards:Tightened hazardous air pollutant limits for stationary asphalt sources are accelerating thermal oxidizer retrofits and greenfield plant investments over marginal equipment upgrades.
- Recycled Asphalt Pavement Mandates:State DOT specifications embedding minimum RAP content directly expand demand for parallel drum systems capable of processing higher reclaimed fractions.
Market Restraints
- Bitumen Price Volatility:Crude-linked binder costs create margin compression for operators without long-term supply contracts or vertical integration into refining.
- Steel Input Concentration:Plant fabrication depends on concentrated Chinese and Turkish steel supply, exposing procurement timelines to tariff and shipping disruptions.
- Legacy Batch Plant Lock-In:Existing installed base flexibility for specialized overlays constrains drum mix conversion economics in mature highway markets.
Strategic Opportunities
- Southeast Asia Greenfield Corridors:Vietnam and Indonesia highway buildouts lack established supplier relationships, creating first-mover positioning for modular plant configurations.
- Carbon Accounting Integration:EU Green Deal procurement rules are embedding embodied carbon thresholds, advantaging warm mix and electric heating retrofits in European tenders.
- Remote Diagnostics Convergence:IoT sensor networks married to predictive maintenance algorithms are enabling service revenue unbundling from hardware sales.
Industry Challenges
- Combustion Engineering Talent Gap:Specialized burner system optimization requires skills scarce in emerging market operator workforces, constraining plant commissioning timelines.
- Multi-Jurisdictional Certification Burden:CE marking, EPA compliance, and country-specific pressure vessel codes create parallel approval tracks that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asphalt Mixing Plants Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Mix, Drum Mix, Continuous Mix, Mobile Mix Technology: Warm Mix Asphalt, Hot Mix Asphalt, Recycle Asphalt, Electric Mix End User: Highway Construction, Residential Development, Commercial Projects, Repair Works Installation: Permanent, Semi-Permanent, Modular, Portable |
| Companies Covered | MARINI, SANY Heavy Industry, Ammann Group, D&G Machinery, Nikko, ASTEC Industries, Lintec & Linnhoff, Parker Plant, WIRTGEN Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asphalt Mixing Plants Market Emerging Trajectories
Digital twin architectures are penetrating asphalt plant control systems, compressing the feedback loop between production parameters and quality assurance. This shift is redrawing competitive advantage around software integration rather than mechanical reliability alone.
Plant control software is virtualizing the traditional split between batch and drum operation modes. Large corridor contractors in India and Brazil are deploying these systems to switch recipes without production stoppage. The technology is virtualizing the historical trade-off between formulation flexibility and throughput volume.
EPA enforcement of Maximum Achievable Control Technology standards for hazardous air pollutants is mandating thermal oxidizer integration in new plant designs. Equipment suppliers are bundling oxidation systems with baghouse retrofits to preempt enforcement actions. Drum mix configurations in the US market bear the highest compliance cost burden, accelerating consolidation toward integrated system providers.
Service contract unbundling is fragmenting the traditional bundled sale model. State highway agencies in Texas and California are procuring maintenance and parts availability as standalone line items, forcing equipment makers to build regional parts depot networks. This pattern is most visible in North American markets where fleet age and utilization rates support aftermarket revenue pools.
Asphalt Mixing Plants Market Segmentation
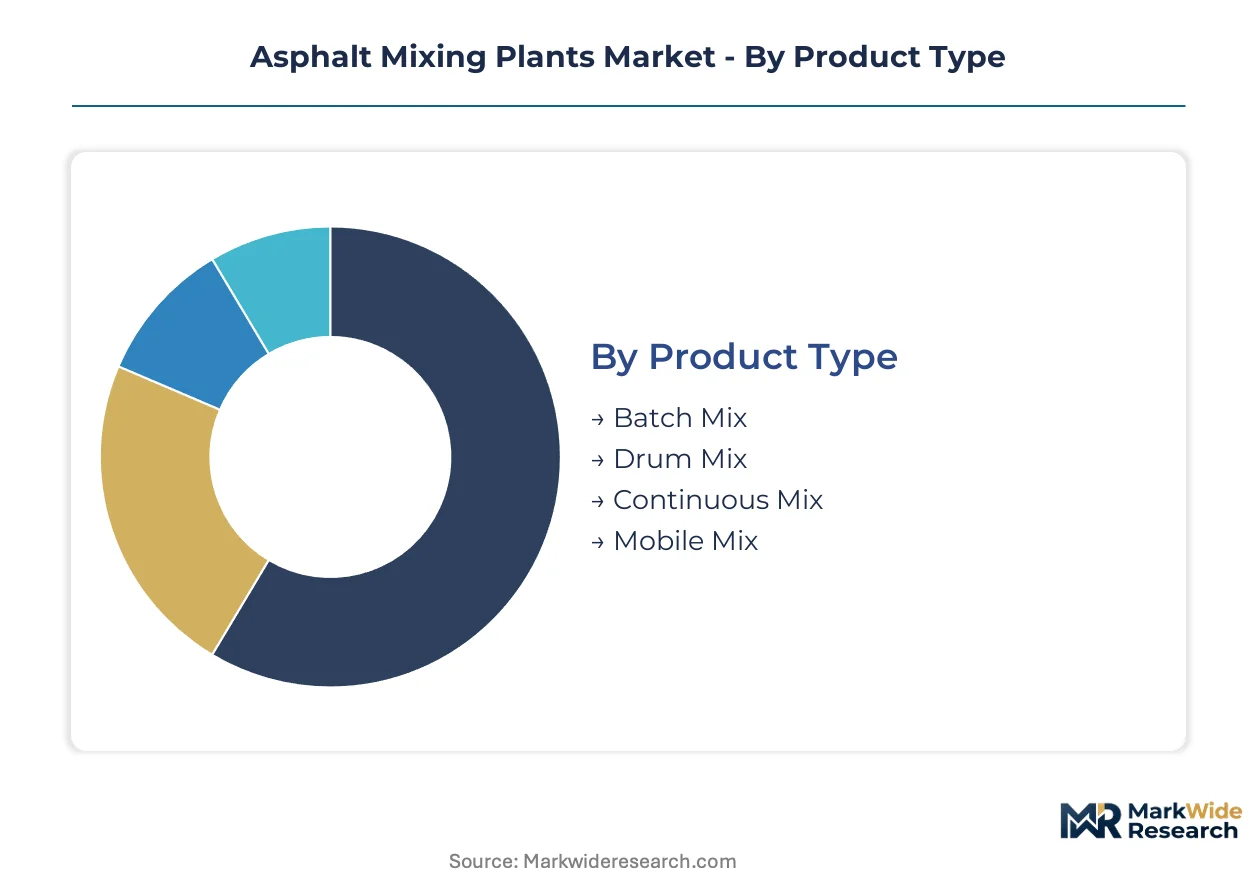
Equipment configuration choices in asphalt mixing plants directly determine capital recovery timelines, operating cost structures, and regulatory compliance pathways. Segmentation reveals how technology selection locks operators into specific production economies and aftermarket service dependencies.
Product Type:
Cost tier differentiation separates batch flexibility from drum throughput economics across project portfolios.
- Batch Mix:Discrete weighing and mixing cycles enable precise gradation control for specialized polymer-modified binders and high-RAP formulations. State DOTs in Texas and California specify batch systems for premium highway overlays where recipe integrity outweighs speed.
- Drum Mix:Continuous drying and mixing in a rotating drum delivers uninterrupted output for high-volume corridor widening. India's Bharatmala Pariyojana program pulls procurement toward 200+ ton per hour drum configurations for national highway expansion.
- Continuous Mix:Parallel-flow or counter-flow designs optimize thermal efficiency for steady-state production. Demand concentrates in emerging markets with limited grid reliability.
- Mobile Mix:Trailer-mounted or skid-based units relocate between remote quarry sites and project locations. Deployment accelerates in Southeast Asian greenfield corridors lacking fixed infrastructure.
Batch Mix commands the established base. The steepest expansion runs through Drum Mix.
Technology:
Application requirements around emissions compliance and recycled content are reconfiguring the technology hierarchy.
- Warm Mix Asphalt:Chemical or water-based foaming reduces production temperatures by 20-40°C, cutting fuel consumption and stack emissions. EU Green Deal procurement thresholds embed embodied carbon limits that favor warm mix in European tenders.
- Hot Mix Asphalt:Conventional 150-180°C production remains specified for heavy-duty pavement layers and high-stress airfield surfaces. Legacy installed base and contractor familiarity sustain dominance in mature North American markets.
- Recycle Asphalt:Parallel drum systems process reclaimed pavement at 50%+ RAP fractions. Caltrans and TxDOT minimum recycled content mandates directly shape equipment selection.
- Electric Mix:Grid-powered heating eliminates on-site combustion for zero-direct-emission production. Pilot deployments concentrate in European markets with renewable electricity access and carbon accounting integration.
Hot Mix Asphalt retains volume leadership. Warm Mix Asphalt is climbing the fastest as regulatory pressure intensifies.
End User:
Customer type determines equipment scale, financing structure, and service contract bundling preferences.
- Highway Construction:National and state road agencies specify continuous-feed capacity with 20+ year service life requirements. Procurement runs through competitive bidding with stringent availability clauses.
- Residential Development:Subdivision and local road builders favor smaller batch or mobile units for intermittent, specification-diverse production. Fleet utilization rates typically run below highway contractors.
- Commercial Projects:Airport runways, port terminals, and industrial yards demand specialized high-performance mixes with extended warranty terms. Premium pricing supports customized plant configurations.
- Repair Works:Pothole patching, surface treatments, and maintenance overlays drive demand for compact, rapid-deployment equipment. Seasonal revenue patterns favor rental and lease structures over ownership.
Highway Construction anchors equipment revenue. Repair Works is gaining share fastest as infrastructure age accumulates across OECD markets.
Installation:
Volume and mobility requirements split procurement between fixed foundations and redeployable configurations.
- Permanent:Concrete-founded plants with dedicated aggregate storage and liquid asphalt tank farms. Long-term quarry leases and stable demand forecasts justify capital intensity.
- Semi-Permanent:Elevated steel structures with limited foundation work enable relocation within 6-12 month horizons. Contractors with multi-year project pipelines favor this hybrid approach.
- Modular:Containerized or skid-mounted subsystems assemble on-site without heavy civil works. MARINI and Ammann Group compete on module interchangeability and commissioning speed.
- Portable:Highway-legal or trailered configurations relocate weekly between project segments. Demand clusters in dispersed rural networks and emergency reconstruction scenarios.
Permanent installations hold the majority position. Modular configurations are expanding most quickly as project mobility and capital efficiency priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German plant fabricators export modular configurations to Southeast Asian highway contractors, while Indian drum mix specialists supply Bharatmala corridor developers with continuous-feed systems. Equipment flows track infrastructure investment cycles and emissions compliance timelines across buyer geographies.
United States
State DOTs in Texas and California drive batch plant procurement for premium highway overlays. EPA NESHAP enforcement mandates thermal oxidizer integration, accelerating greenfield investments over retrofits. Equipment clusters concentrate in Tennessee and Georgia, where ASTEC Industries anchors North American service networks.
Germany
EU Green Deal procurement thresholds embed embodied carbon limits that favor warm mix asphalt systems. CE marking requirements and pressure vessel codes create multi-track certification burdens for plant exporters. Industrial concentration centers in Bavaria and North Rhine-Westphalia, where MARINI leverages European R&D networks for modular configurations.
India
The Bharatmala Pariyojana program mandates 200+ ton per hour drum mix capacity for national highway widening. BIS standards and state-level environmental clearances shape equipment selection timelines. Manufacturing and deployment activity concentrates in Maharashtra and Gujarat, where domestic fabricators scale production for continuous-feed corridor projects.
China
Steel input concentration in Chinese fabrication exposes procurement timelines to tariff and shipping disruptions. MIIT industrial equipment standards and provincial emissions enforcement shape plant design requirements. Production gravity sits in Zhengzhou and Xuzhou, where SANY Heavy Industry and D&G Machinery supply domestic and export markets.
Indonesia
Trans-Java toll road expansion and Sumatra corridor development create greenfield demand without established supplier relationships. The country's national infrastructure regulator evaluates equipment imports against local content requirements. Project activity clusters in Java and Sumatra, where modular plant configurations gain preference for dispersed quarry access.
Asphalt Mixing Plants Market Vendor Landscape
On the supply side, the industry is consolidating around integrated system providers capable of bundling combustion, control, and emissions hardware. Tiered competition separates premium modular specialists from scale-driven drum mix fabricators and regional service-focused operators. Dominant competitive moves include backward integration into burner and control systems, plus geographic expansion through regional parts depot networks.
Among European-based specialists, MARINI and Ammann Group occupy positions at the premium end of modular plant configurations, with the former exemplifying R&D-led product development and the latter representing backward-integrated component control. ASTEC Industries anchors the North American service density archetype, competing through aftermarket parts availability rather than hardware differentiation alone. These three represent distinct strategic postures: technology leadership, vertical integration, and service infrastructure scale.
| Leading Market Players |
|---|
| MARINI |
| SANY Heavy Industry |
| Ammann Group |
| D&G Machinery |
| Nikko |
| ASTEC Industries |
| Lintec & Linnhoff |
| Parker Plant |
| WIRTGEN Group |
| Others |
Supply Flow & Price Mechanics
Chinese and Turkish steel fabrication concentration feeds directly into margin pools at the burner system and control module tiers, where backward-integrated suppliers capture value that modular assemblers cannot access.
Pricing Analysis
Hot mix asphalt systems, warm mix retrofits, and emerging electric heating configurations occupy distinct pricing strata. Three-tier pricing structure across premium modular, standard drum mix, and economy mobile units separates MARINI's CE-marked configurations from Indian fabricators' continuous-feed corridor systems. Cost compression in standard drum configurations is intensifying because Bharatmala procurement mandates prioritize throughput over customization. Highway construction agencies show lowest price sensitivity due to 20-year service life requirements, while residential developers negotiate aggressively on mobile unit leases.
Supply Chain Analysis
Bitumen feedstock draws from Middle Eastern, Russian, and North American refining complexes, with crude-linked volatility transmitting rapidly into operator margins. Steel plate, burner assemblies, and baghouse filtration media constitute critical component dependencies. Single-source vulnerability concentrates in Chinese pressure vessel fabrication certified to ASME codes. Distribution runs through EPC contractors and direct state procurement channels rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warm mix asphalt technology is disrupting capital allocation across installed plant bases, with EPA NESHAP enforcement and EU Green Deal procurement rules creating simultaneous regulatory inflections in the two largest equipment markets.
For Market Incumbents: Entrench service revenue through predictive maintenance IoT deployments and regional parts depot density. Thermal oxidizer bundling with new plant sales defends against greenfield competitors. Capacity addition in Maharashtra and Gujarat secures proximity to India's Bharatmala corridor developers.
For New Entrants and Emerging Players: Build out modular plant configurations for Indonesia's Trans-Java toll road and Vietnam's expressway buildouts where supplier relationships remain unformed. Southeast Asian greenfield corridors offer the most penetrable geography. Target state highway agencies with availability-based service contracts rather than equipment-only positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional service operators in Texas and California holding aging batch plant fleets. The 5-10 year viability window hinges on RAP processing retrofit capability and emissions compliance upgrade paths. Monitor EPA enforcement actions against legacy drum mix configurations as inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Burner Systems | Ammann Group's captive combustion engineering locks in margin pools unavailable to modular assemblers. |
| IoT-Enabled Predictive Maintenance | Digital twin architectures at ASTEC Industries compress commissioning timelines and unbundle service revenue. |
| Warm Mix Retrofit Certification | CE marking for low-temperature systems opens EU Green Deal procurement thresholds to non-European suppliers. |
| Regional Parts Depot Expansion | Texas and California depot density determines aftermarket capture rates in North American highway markets. |
| Parallel Drum RAP System Development | Caltrans and TxDOT minimum recycled content mandates directly expand addressable equipment demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with plant engineers, state DOT procurement officers, EPC contractors, and aftermarket service heads. Secondary validation drew from EPA NESHAP enforcement records, BIS equipment standards filings, EU Green Deal procurement documentation, and customs trade data on steel plate imports. Bottom-up equipment shipment tallies were triangulated against top-down infrastructure investment forecasts.
Calibration against historical capacity additions and emissions retrofit cycles anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, technology generation, end-user type, and installation mobility class. CAGRs were derived from regression analysis on correlated infrastructure spending variables, with specific inputs for bitumen price volatility bands and steel input tariff scenarios.
Stress conditions across crude-linked binder costs, Chinese steel supply disruptions, and EPA enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against state DOT capital improvement plans and national highway authority procurement schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Austria Prefabricated Housing Market
Construction and Engineering
Road & Highway Infrastructure Market
Construction and Engineering
Derinding Machines Market
Construction and Engineering
Europe Gypsum Board Market
Construction and Engineering
Woodworking CNC Tools Market
Construction and Engineering
Asia-Pacific Cement Market
Construction and Engineering
Wire Mesh Welding Machines Market
Construction and Engineering
France Architectural Coatings Market
Construction and Engineering
Black Bricks Market
Construction and Engineering
Agitator Drive Units Market
Construction and Engineering
Cable Laying Vessel Market
Construction and Engineering
United States Gutter Guards Market
Construction and Engineering
Magnesium Oxide Boards Market
Construction and Engineering
Dust Suppression Fog Cannon Market
Construction and Engineering
DIY Ball Mill Market
Construction and Engineering
HVAC Actuators Market