
 North America Industrial Flooring Market | 2026-2036
North America Industrial Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Flooring Market Analytics
The widening performance gap between premium resin systems and commodity concrete overlays is repositioning procurement strategies across North American industrial facilities. Sika AG leverages its vertically integrated polymer supply to sustain specification-grade epoxy formulations for food processing environments. Sherwin-Williams Company anchors its position through extensive distributor control across Midwest manufacturing corridors. RPM International Inc. differentiates via specialized urethane mortar systems that compete aggressively in thermal shock applications.
North America industrial flooring encompasses engineered surface systems—typically 2-8 mm thick resinous membranes or polished/treated concrete slabs—designed to withstand mechanical abrasion, chemical exposure, and static loads in commercial and industrial environments. These installations require specified compressive strength exceeding 35 MPa and slip resistance coefficients mandated by workplace safety codes. Epoxy formulations dominate current specification volumes due to their chemical resistance and established installer base, while polyurethane systems capture faster growth in cold-storage and thermal-cycling applications where flexibility and impact recovery matter. Food processing and pharmaceutical end users concentrate margin pools around antimicrobial and USDA-compliant systems that command premium pricing over standard warehouse durability grades.
OSHA walking-working surface standards, EPA VOC content regulations under 40 CFR Part 59, and FDA food facility sanitation requirements collectively shape product formulation decisions and contractor certification demands across the region. State-level building codes in California and New York impose additional emission and performance testing that filters market access for imported material suppliers. Stakeholders must monitor evolving PFAS restrictions and biobased content mandates that will redefine acceptable polymer chemies and installation practices.
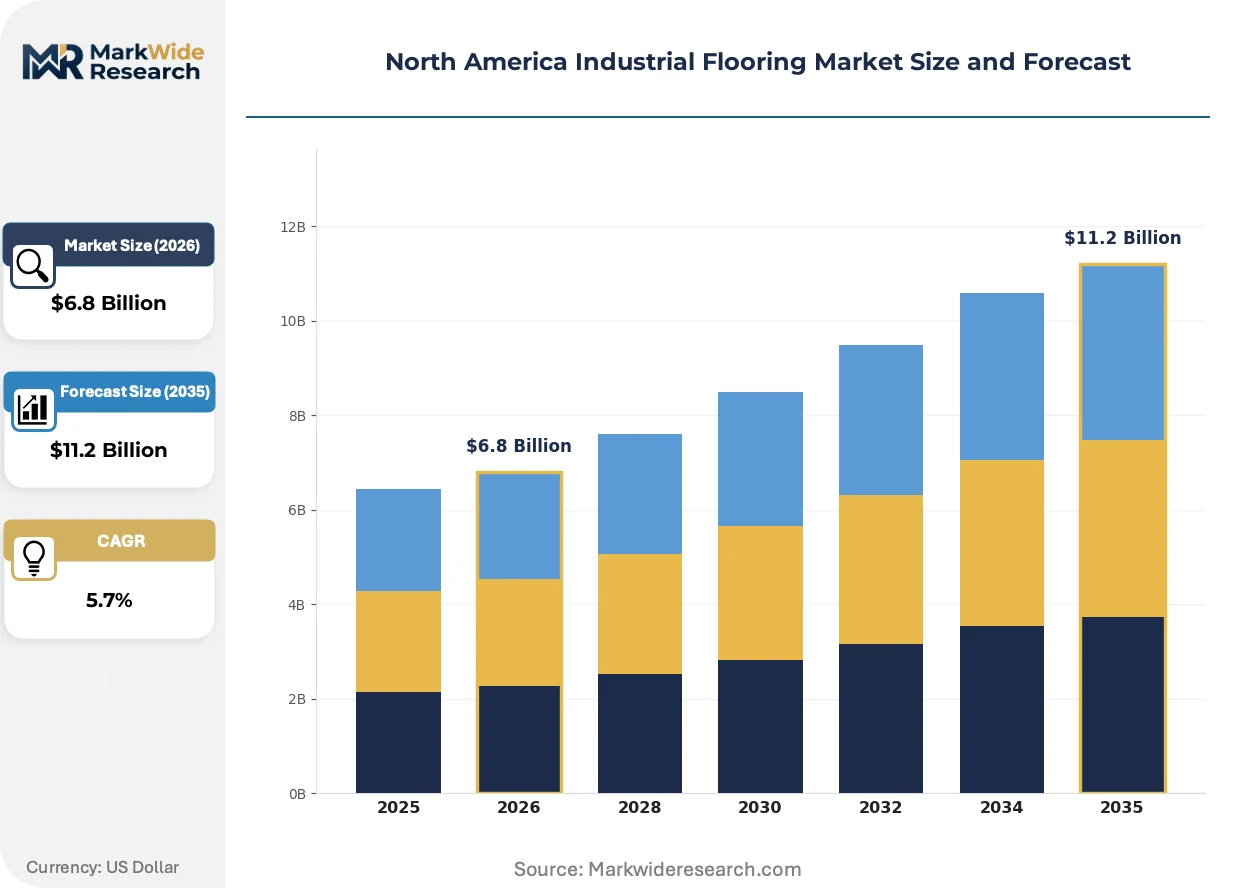
Market Dynamics
The North America industrial flooring market is compressing around specification-grade resin systems as EPA VOC emission standards under 40 CFR Part 59 and OSHA slip-resistance mandates force out commodity formulations that dominated warehouse installations through 2020.
Growth Catalysts
- Pharmaceutical cleanroom expansion:Biologics manufacturing facilities across Massachusetts and North Carolina are specifying antimicrobial epoxy systems with USDA-compliant surface treatments.
- Texas Gulf Coast petrochemical corridor:Chemical-resistant urethane mortar installations are accelerating along the Houston Ship Channel to withstand sulfuric acid exposure and thermal cycling.
- 40 CFR Part 59 compliance deadlines:The EPA's architectural coatings rule is pulling forward replacement cycles for high-VOC concrete sealers in California and New York industrial facilities.
Market Restraints
- Epoxy resin supply concentration:Bisphenol A feedstock bottlenecks in Texas and Louisiana create pricing volatility for specification-grade formulations.
- Skilled installer scarcity:The certified applicator base for thermal-shock urethane systems remains concentrated in Midwest manufacturing corridors.
- Polished concrete substitution:Dry-shake hardener treatments are capturing warehouse durability applications where chemical resistance requirements are minimal.
Strategic Opportunities
- USDA-compliant food processing:Poultry and dairy facilities in the Midwest are retrofitting with antimicrobial resin systems ahead of FDA sanitation inspections.
- Cold-storage thermal cycling:Polyurethane concrete hybrids are penetrating frozen food distribution centers where epoxy brittleness causes failure.
- Biobased polymer mandates:California's Buy Clean procurement rules are creating specification pathways for soy-epoxy and lignin-based formulations.
Industry Challenges
- Moisture vapor transmission remediation:Existing slab conditions in older Midwest manufacturing plants require calcium chloride testing and mitigation before resin installation.
- Installer certification fragmentation:Manufacturer-specific training programs for urethane mortar application create labor pool segmentation that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Flooring Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Vinyl, Concrete End User: Manufacturing Facilities, Warehouses, Food Processing, Pharmaceuticals Installation Type: On-site, Pre-cast, Modular, Roll-out Functionality: Durability, Aesthetics, Safety, Maintenance |
| Companies Covered | Sika AG, Sherwin-Williams Company, RPM International Inc., Akzo Nobel N.V., MBCC Group, Stonhard, Tremco Incorporated, 3M, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Flooring Market Evolving Landscape
Resin chemistry convergence and specification tightening are compressing the viable product set while opening premium positioning for performance-validated systems. Formulation transparency and embodied carbon documentation are becoming gatekeepers to institutional procurement.
Hybrid epoxy-urethane systems are unifying chemical resistance and thermal shock recovery in single-coat applications that reduce installation downtime. Food processing facilities in Wisconsin and Pennsylvania are specifying these formulations for blast-freezer transitions where temperature swings exceed 50°C daily. The technology is unifying what previously required separate epoxy base coats and urethane topcoats, compressing material cost structures and installer labor hours.
The EPA's 40 CFR Part 59 architectural coatings rule is eliminating solvent-based epoxy formulations from specification sheets across California and New York industrial projects. Facility managers in these states are accelerating conversion to waterborne and high-solids systems ahead of 2025 compliance deadlines. Pharmaceutical cleanroom contractors are most affected, as VOC limits intersect with FDA sanitation requirements to narrow acceptable product lists.
Life-cycle cost modeling is displacing first-cost bidding in institutional procurement across the Great Lakes manufacturing belt. Facility engineering teams at automotive and aerospace plants are contracting directly with resin manufacturers for 15-year performance guarantees that bundle installation, maintenance, and recoating. This shift is most visible in Michigan and Ohio, where capital project finance teams now require total cost of ownership documentation alongside unit pricing.
North America Industrial Flooring Market Segmentation
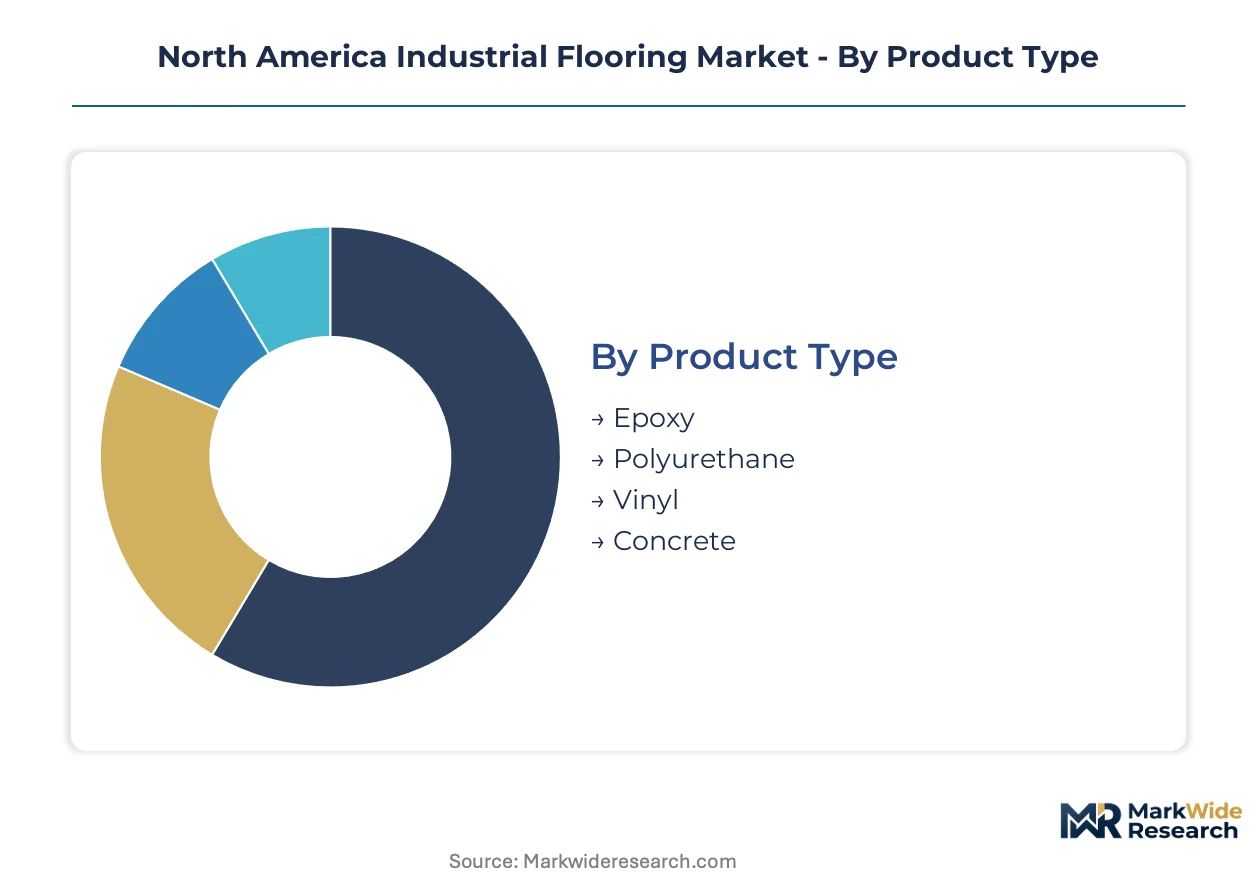
Specification-grade resin systems dominate procurement decisions as EPA VOC standards and OSHA mandates compress the viable product set. End-use requirements from pharmaceutical cleanrooms to petrochemical corridors fragment demand across performance tiers and installation methodologies.
Product Type:
Material selection hinges on chemical resistance, thermal cycling tolerance, and compliance with federal emission standards.
- Epoxy:Bisphenol-A-based formulations deliver compressive strength exceeding 35 MPa and chemical resistance for manufacturing environments. Massachusetts and North Carolina biologics facilities specify antimicrobial variants with USDA-compliant surface treatments to satisfy FDA sanitation requirements.
- Polyurethane:Flexible aliphatic systems recover from impact and thermal shock in cold-storage applications where temperature swings exceed 50°C. Frozen food distribution centers across Wisconsin and Pennsylvania favor these formulations over brittle epoxy alternatives.
- Vinyl:Sheet and tile systems serve light industrial maintenance areas with lower chemical exposure profiles.
- Concrete:Polished and densified slabs capture warehouse durability applications where dry-shake hardeners substitute for resin membranes.
Epoxy leads on scale; polyurethane leads on momentum.
End User:
Facility type determines specification stringency, from commodity warehouse grades to validated cleanroom systems.
- Manufacturing Facilities:Automotive and aerospace plants in Michigan and Ohio contract directly with resin manufacturers for 15-year performance guarantees bundling installation and maintenance. Life-cycle cost modeling now displaces first-cost bidding in capital project procurement.
- Food Processing:Poultry and dairy facilities across the Midwest retrofit with antimicrobial resin systems ahead of FDA sanitation inspections. USDA-compliant surface treatments command premium pricing over standard durability grades.
- Warehouses:Dry-shake hardener treatments and polished concrete satisfy minimal chemical resistance requirements in distribution centers.
- Pharmaceuticals:Cleanroom installations require validated epoxy systems meeting both EPA VOC limits and FDA contamination controls.
Manufacturing facilities anchor volume; food processing shows the steepest expansion trajectory.
Installation Type:
Project timelines and slab conditions dictate methodology selection across new construction and retrofit environments.
- On-site:Trowel-applied resin systems dominate specification-grade installations where moisture vapor transmission testing and calcium chloride remediation precede application. Certified applicator scarcity in thermal-shock urethane systems extends project timelines in non-Midwest corridors.
- Pre-cast:Factory-cured panels reduce field installation hours for standardized industrial layouts.
- Modular:Interlocking tile systems enable rapid deployment in temporary or reconfigurable production spaces.
- Roll-out:Vinyl sheet applications serve light-duty maintenance zones with minimal surface preparation.
On-site installation commands specification premiums; modular approaches gain share in flexible manufacturing footprints.
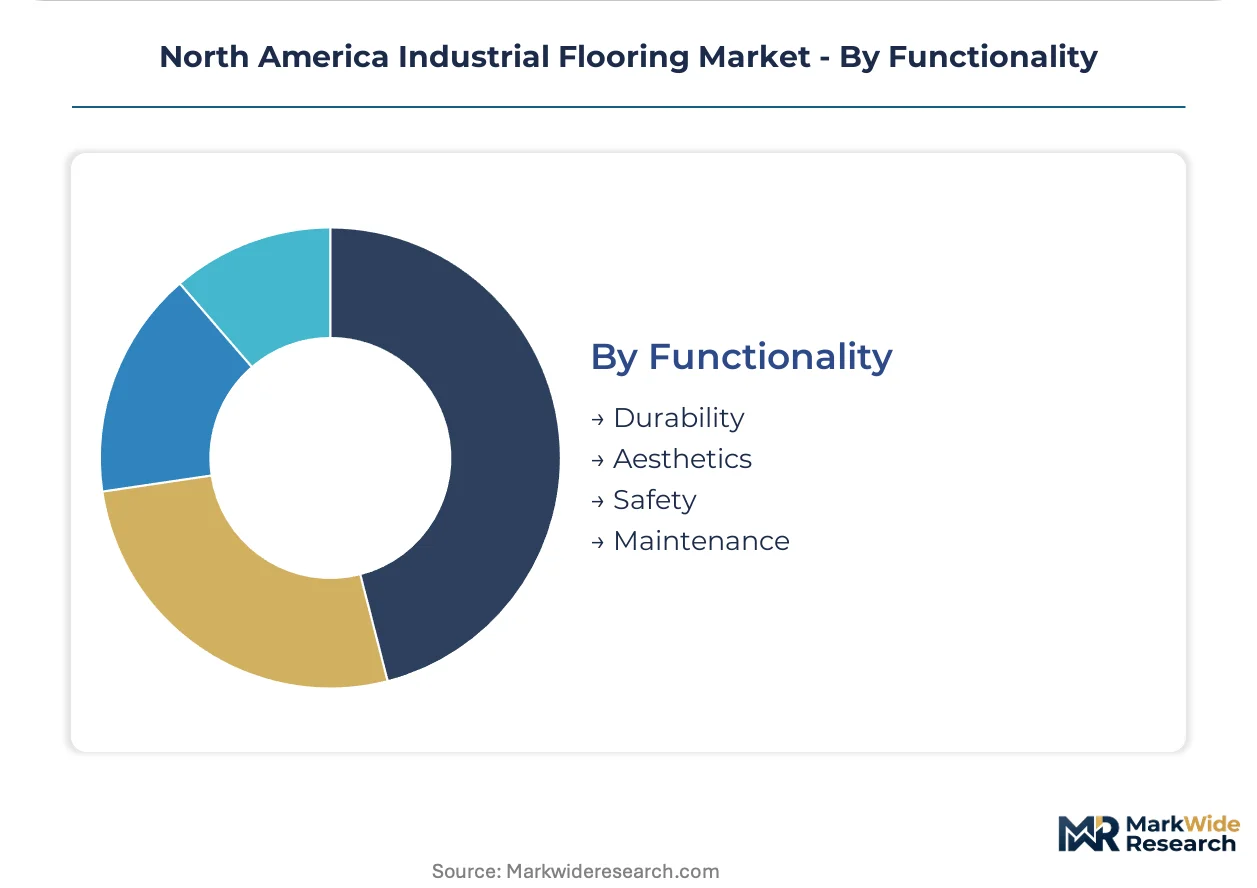
Functionality:
Performance priorities stratify procurement between capital-intensive durability specifications and operational maintenance regimes.
- Durability:Abrasion resistance and compressive strength specifications exceed 35 MPa for heavy manufacturing and petrochemical applications. Texas Gulf Coast facilities along the Houston Ship Channel specify chemical-resistant urethane mortars to withstand sulfuric acid exposure.
- Safety:Slip-resistance coefficients mandated by OSHA walking-working surface standards drive textured topcoat specifications in wet-process environments.
- Aesthetics:Color-stable aliphatic polyurethane topcoats maintain appearance in pharmaceutical and food processing visibility zones.
- Maintenance:Ease of repair and recoating intervals influence total cost of ownership calculations in institutional procurement.
Durability specifications capture the largest margin pools; safety compliance is becoming non-negotiable across all end-use categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified resin applicator concentrations in the Great Lakes and Texas Gulf Coast anchor North American installation capacity. These workforce clusters concentrate specification-grade expertise around petrochemical corridors and automotive manufacturing belts.
United States
Biologics manufacturing expansion across Massachusetts and North Carolina drives antimicrobial epoxy specifications for FDA-compliant cleanrooms. EPA's 40 CFR Part 59 VOC limits intersect with OSHA walking-working surface standards to compress acceptable product lists. The Houston Ship Channel corridor specifies chemical-resistant urethane mortars for sulfuric acid exposure and thermal cycling.
Canada
Cold-storage distribution center construction in Ontario and Quebec accelerates polyurethane concrete hybrid adoption for frozen food logistics. Health Canada's environmental assessment requirements for industrial coatings align with provincial emission standards in British Columbia and Ontario. The Calgary-Edmonton corridor concentrates oil sands maintenance flooring for abrasion-resistant epoxy systems.
Mexico
Automotive assembly plant expansion across Nuevo León and Bajío Region generates demand for compressive-strength resin systems exceeding 35 MPa. Mexico's federal environmental regulations under SEMARNAT tighten solvent-based coating formulations in border manufacturing zones. The Tijuana-Mexicali corridor specifies rapid-cure epoxy systems to minimize production downtime in electronics assembly.
North America Industrial Flooring Market Competitive Landscape
Top-tier vendors anchor specification-grade resin formulations, while regional applicator networks and commodity concrete treatment providers occupy lower-margin tiers. Market structure compresses around vertically integrated polymer suppliers with captive feedstock positions and certified installer ecosystems. Two strategic archetypes dominate: integrated chemical conglomerates controlling bisphenol-A supply chains, and specialized flooring contractors with manufacturer-exclusive certification. Competitive moves concentrate on backward integration into epoxy resin production and geographic expansion of certified applicator training programs.
Within the integrated chemical tier, Sika AG and BASF SE exemplify upstream control over polymer feedstocks that sustains specification-grade formulation consistency. Sherwin-Williams Company occupies a position anchored in distributor network density across Midwest manufacturing corridors. RPM International Inc. represents the specialized contractor archetype through urethane mortar expertise in thermal-shock applications. These three entities collectively illustrate how supply chain configuration and installation certification stratify competitive positioning.
| Leading Market Players |
|---|
| Sika AG |
| Sherwin-Williams Company |
| RPM International Inc. |
| Akzo Nobel N.V. |
| MBCC Group |
| Stonhard |
| Tremco Incorporated |
| 3M |
| BASF SE |
| Others |
Value Network & Pricing Analysis
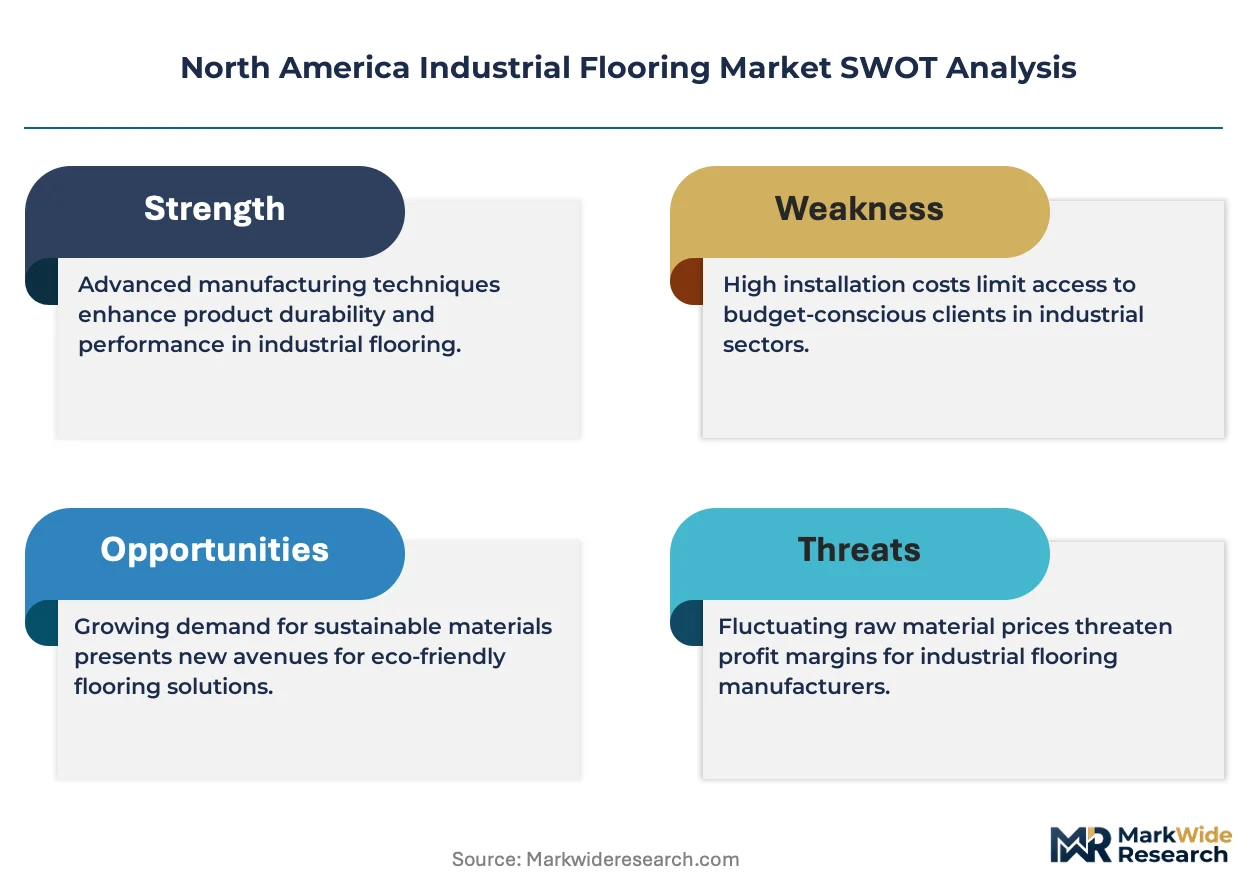
Bisphenol-A spot pricing volatility in the Texas-Louisiana corridor cascades through epoxy resin formulations into three distinct procurement tiers across North American industrial flooring. Specification-grade systems command premiums tied to polymer feedstock security, while commodity concrete treatments compete on installation labor arbitrage alone.
Pricing Analysis
Bundled 15-year performance guarantees separate from unbundled material-only supply contracts across Michigan and Ohio automotive corridors. Price differentiation rests on USDA-compliant antimicrobial certification and thermal-shock urethane applicator scarcity. Cost compression in standard warehouse epoxy reflects polished concrete substitution. Food processing facilities show least price sensitivity due to FDA sanitation compliance deadlines; distribution centers exhibit maximum sensitivity to first-cost bidding.
Supply Chain Analysis
California's Buy Clean procurement rules and New York's emission standards reshape sourcing toward domestic resin production and certified applicator networks. Bisphenol-A feedstock concentrates in Texas and Louisiana; certified urethane mortar applicators cluster in Midwest manufacturing belts. Single-source vulnerability runs through Gulf Coast petrochemical infrastructure. Distribution runs through manufacturer-authorized contractor networks rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American industrial flooring represents a late-cycle quality story as EPA VOC mandates and OSHA slip-resistance standards force replacement of commodity formulations with specification-grade resin systems.
For Market Incumbents: Hedge bisphenol-A feedstock exposure through backward integration into epoxy resin production or long-term offtake agreements with Gulf Coast petrochemical producers. Expand certified applicator training programs beyond Midwest manufacturing corridors to capture Texas Gulf Coast petrochemical corridor demand. Counter polished concrete substitution by bundling moisture vapor transmission remediation into project scope. For New Entrants and Emerging Players: Digital specification platforms offer route-to-market access for biobased polymer formulations qualifying under California Buy Clean rules. Target cold-storage thermal cycling applications in Wisconsin and Pennsylvania frozen food distribution centers where epoxy brittleness creates performance gaps. Lead with polyurethane concrete hybrid systems requiring lower capital intensity than full epoxy resin production. For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturer-specific installer certification programs fragment labor pools and extend project timelines. Five-to-ten year viability favors vertically integrated polymer suppliers with captive feedstock positions over pure-play installation contractors. Watch for PFAS restriction announcements as inflection indicators that would disqualify incumbent formulation portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Captive bisphenol-A supply secures margin stability against Gulf Coast feedstock volatility. |
| Certified Applicator Training Program Expansion | Geographic extension beyond Midwest clusters captures Texas petrochemical corridor specifications. |
| Biobased Polymer Formulation Development | Soy-epoxy and lignin-based systems unlock California Buy Clean procurement pathways. |
| Hybrid Epoxy-Urethane System Launch | Single-coat thermal shock recovery reduces installation downtime for food processing blast-freezer transitions. |
| 15-Year Performance Guarantee Bundling | Life-cycle cost contracts displace first-cost bidding in Michigan and Ohio automotive procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window across North American industrial flooring stakeholders. Primary engagement captured resin manufacturer technical directors, certified flooring applicators, facility engineering managers at automotive and food processing plants, and procurement leads at pharmaceutical cleanroom contractors. Secondary validation drew from EPA 40 CFR Part 59 regulatory filings, OSHA walking-working surface standard updates, USDA facility sanitation guidelines, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up project pipeline analysis triangulated against top-down resin consumption estimates.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation modeling captured product type tier, end-use industry vertical, installation methodology, and regional regulatory cluster. CAGRs derived from polynomial trend fitting against disclosed capital expenditure patterns and facility construction permit data. Forecast inputs incorporated biologics manufacturing expansion timelines along Massachusetts and North Carolina corridors and Texas Gulf Coast petrochemical capacity additions.
The model assumes a particular technology adoption path; alternative pathways for waterborne epoxy formulations or rapid-cure polyurethane systems would alter the outlook. Forecasts reflect assumptions around EPA enforcement consistency and skilled installer training program expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
US Metal Stadium Seating Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Global Formwork Market