
 North America Plywood Market | 2026-2036
North America Plywood Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plywood Market Intelligence
Aftermarket service revenue is fragmenting across the North America plywood value chain as mills diversify beyond commodity panel sales. Roseburg Forest Products leverages its integrated Oregon timber base to control fiber costs through captive supply. Georgia-Pacific sustains scale advantages across multiple southern states with coordinated mill networks. West Fraser Timber Co. anchors Canadian supply into US distribution channels through rail-linked production.
North America plywood comprises engineered wood panels built from thin veneer layers cross-laminated under heat and pressure, typically bonded with phenol-formaldehyde or urea-formaldehyde resins rated for interior or exterior exposure grades. Structural plywood dominates construction applications through PS 1-19 performance standards governing span ratings and bond durability. Softwood plywood occupies mature volume positions in subflooring and wall sheathing where building codes mandate structural grades, while hardwood plywood segments into premium cabinetry and furniture facing where Columbia Forest Products competes on formaldehyde-free PureBond technology.
US EPA enforcement of TSCA Title VI formaldehyde emission limits shapes product certification and market access for domestic and imported panels alike. APA – The Engineered Wood Association maintains quality auditing protocols that California Air Resources Board standards reference through AB 705 compliance pathways. Canadian producers navigate dual oversight from Health Canada/PMRA chemical regulations and CSA O121 structural certification. Stakeholders must monitor evolving state-level amendments to green building codes that specify low-emitting materials for public procurement.
Market Dynamics
EPA enforcement of TSCA Title VI formaldehyde emission limits is compressing certification timelines and reshaping competitive access for domestic mills and importers alike. The regulatory pressure cascades through supply chains as buyers demand documented compliance for project eligibility.
Growth Catalysts
- Multi-family residential construction:Five-over-one wood-frame building codes in Texas and Florida are absorbing structural sheathing volumes at accelerated clip rates.
- TSCA Title VI certification harmonization:Federal preemption of patchwork state standards is reducing compliance duplication costs for cross-border Canadian suppliers.
- Mass timber building codes:ICC adoption of tall wood construction standards is extending plywood demand into mid-rise commercial structural applications.
Market Restraints
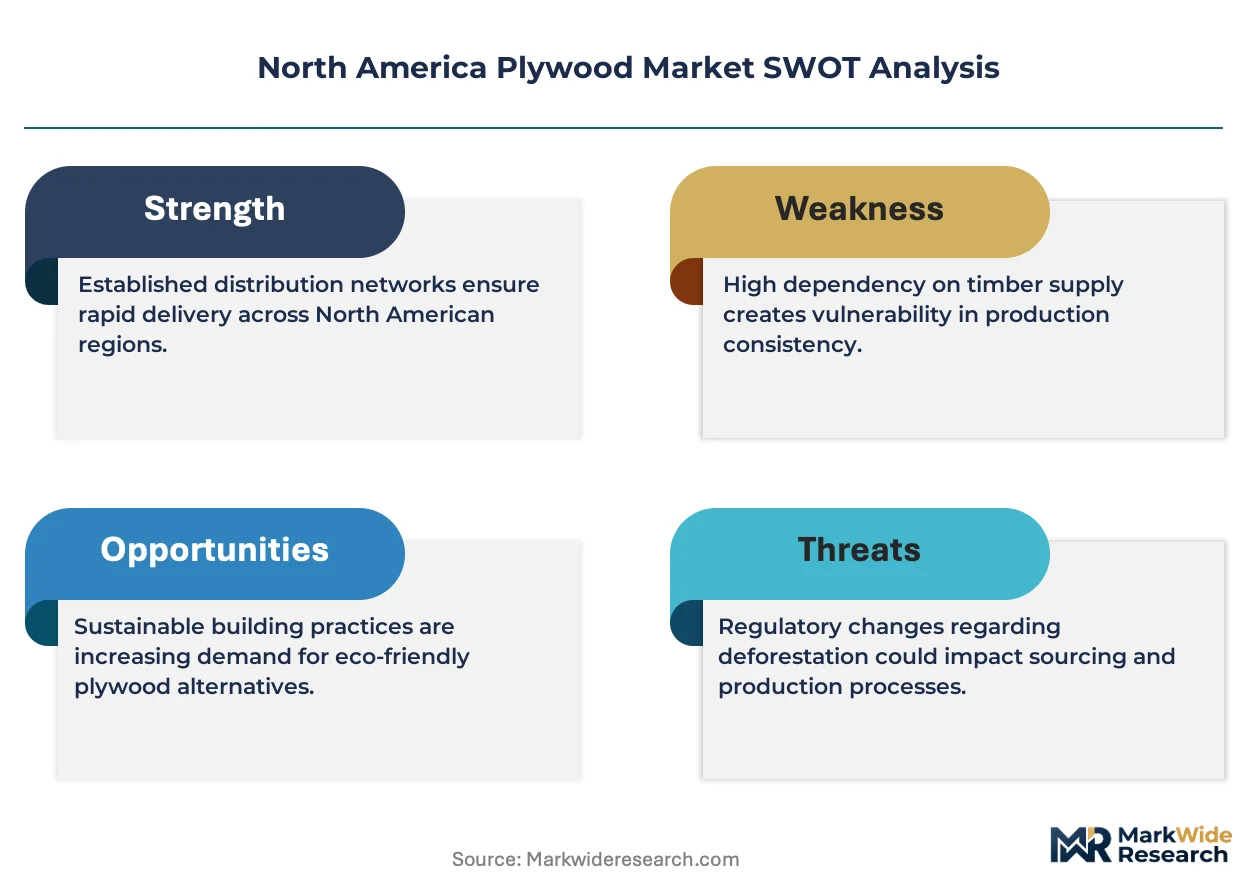
- Softwood timber input volatility:Mountain pine beetle damage in British Columbia has constrained fiber availability for veneer peeling operations.
- OSB substitution elasticity:Oriented strand board pricing discounts during demand troughs capture wall sheathing specifications from plywood in tract housing.
- Import certification friction:EPA third-party certifier bottlenecks delay container clearance at US ports for Southeast Asian panel shipments.
Strategic Opportunities
- Cross-laminated timber integration:CLT plant investments in Arkansas and Alabama create captive plywood demand for protective facing layers.
- Low-emitting materials procurement mandates:California Department of General Services specifications for public buildings specify CARB Phase 2 or TSCA Title VI panels exclusively.
- Prefabricated wall panel manufacturing:Offsite construction factories in the US Southeast are consolidating sheathing purchases through direct mill relationships.
Industry Challenges
- Certified panel grader workforce scarcity:APA auditor training programs face enrollment gaps as experienced graders retire from quality assurance roles.
- Mill capital intensity for continuous press upgrades:Single-opening press replacements require extended downtime that strains order fulfillment during demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plywood Market |
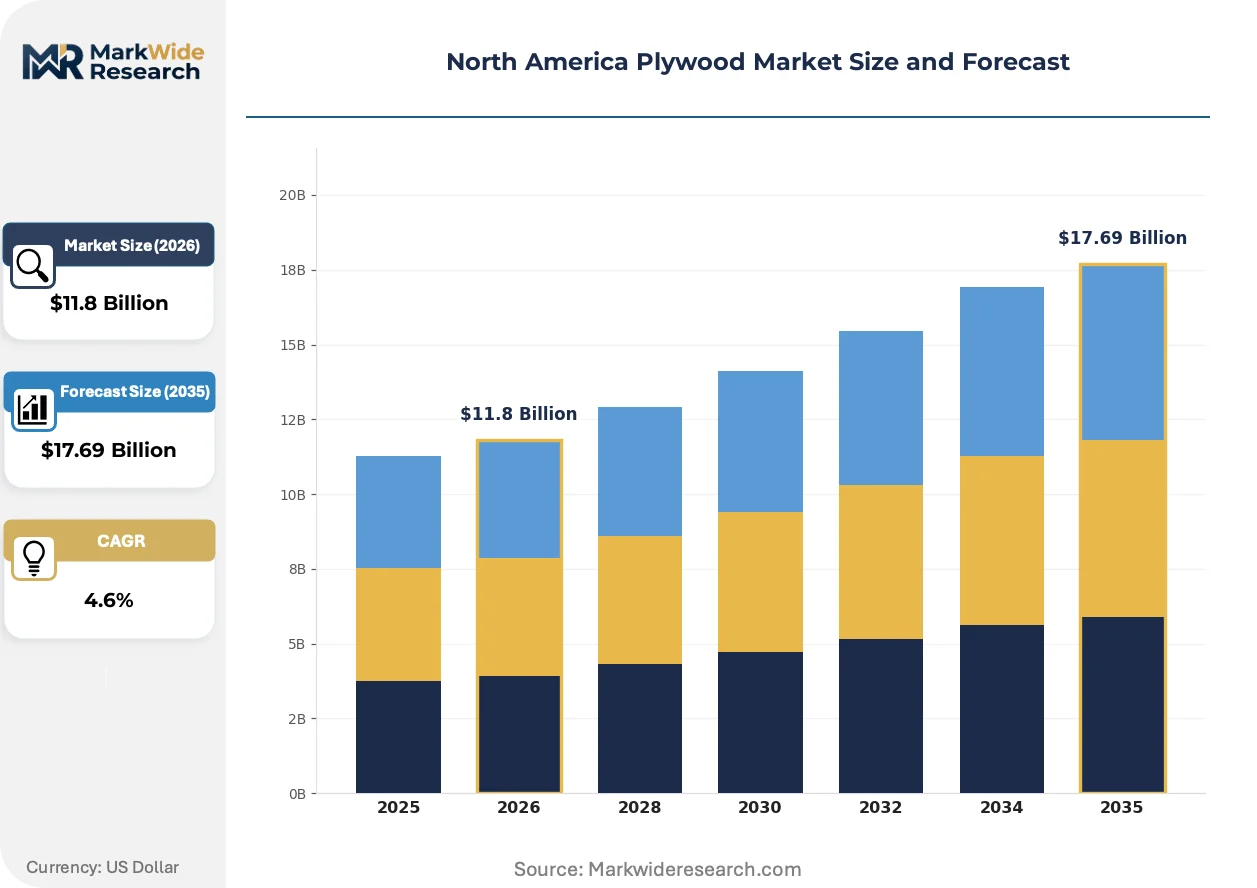
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softwood Plywood, Hardwood Plywood, Marine Plywood, Structural Plywood Application: Furniture, Flooring, Construction, Cabinetry End User: Residential, Commercial, Industrial, Institutional Thickness: 4mm, 6mm, 12mm, 18mm |
| Companies Covered | Roseburg Forest Products, Columbia Forest Products, Georgia-Pacific, Canfor Corporation, PotlatchDeltic, Boise Cascade, West Fraser Timber Co., Tolko Industries, Weyerhaeuser Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plywood Market Strategic Shifts & Innovations
Digital veneer grading and resin formulation advances are compressing quality variance and enabling real-time process adjustment. These capabilities intersect with tightening emission standards to redefine product differentiation.
Automated optical scanning systems with machine-learning defect detection are virtualizing manual veneer grading labor. Southern yellow pine mills in Georgia and Alabama deploy these systems to maintain PS 1-19 grade recovery rates amid skilled labor attrition. The technology is virtualizing traditional quality assurance staffing models while accelerating throughput per shift.
EPA's phased implementation of TSCA Title VI third-party certification is consolidating accredited testing laboratory relationships. Mills now maintain continuous monitoring protocols rather than batch testing, embedding compliance into production rhythm. Canadian producers with Health Canada/PMRA dual oversight experience navigate this transition faster than new market entrants.
Builder procurement consolidation through national distribution cooperatives is compressing regional price variance. Large production homebuilders in Texas and Florida negotiate direct mill contracts that bypass traditional two-step distribution. This channel concentration is most visible in the US Southeast where mill density supports competitive sourcing within 300-mile haul zones.
North America Plywood Market Segmentation
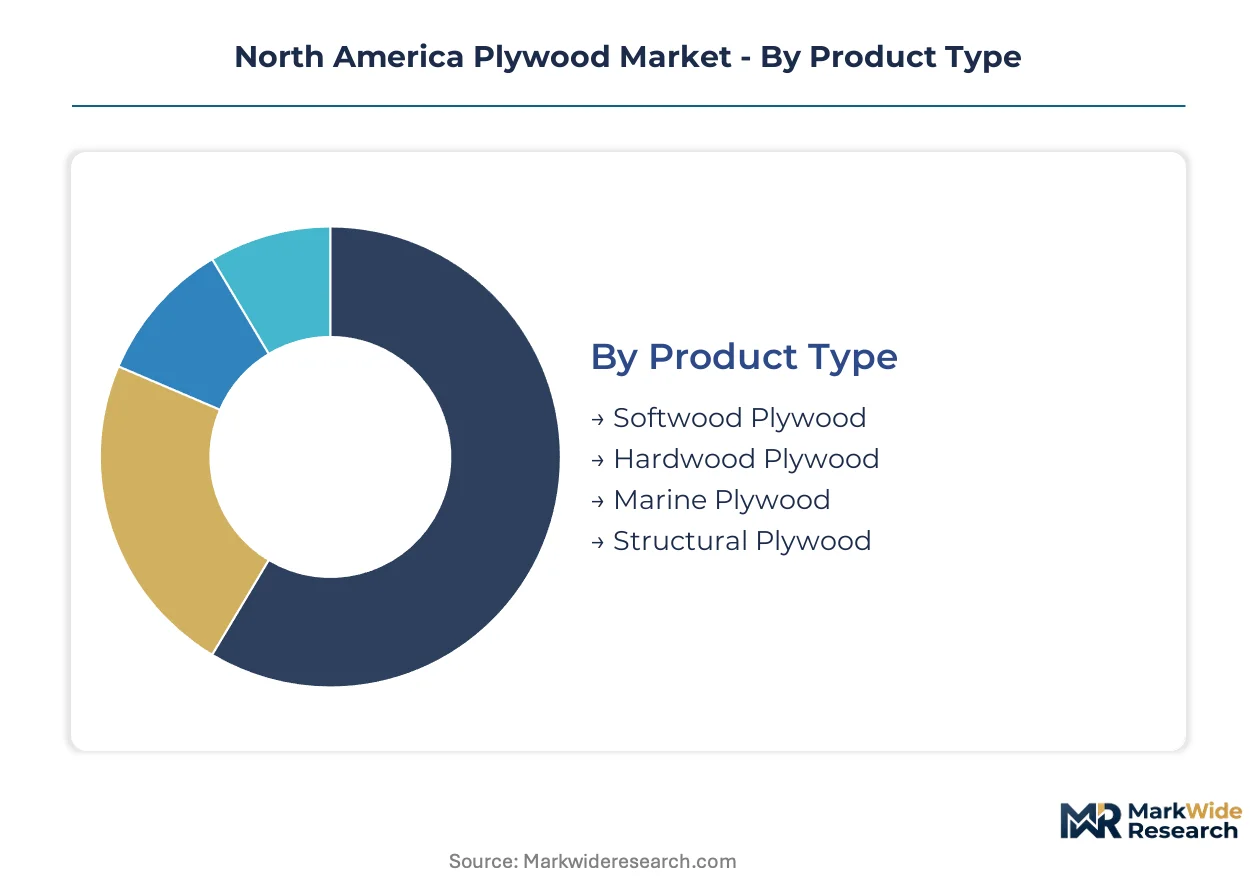
Segmentation in the North America plywood market reveals how product specifications, end-use requirements, and buyer categories create distinct competitive arenas. Each dimension governs different purchasing criteria, from structural code compliance in construction to aesthetic grading in furniture applications.
Product Type:
Cost tier separates commodity structural panels from premium specialty grades, with resin chemistry and veneer quality driving the price architecture.
- Softwood Plywood:Southern yellow pine and Douglas fir veneers bonded with phenol-formaldehyde resin dominate subflooring and wall sheathing applications. Five-over-one multi-family construction in Texas and Florida absorbs volume at accelerated rates as building codes mandate PS 1-19 structural ratings.
- Hardwood Plywood:Decorative face veneers from maple, oak, and birch overlay poplar or hardwood cores for cabinetry and furniture facing. California public procurement specifications for low-emitting materials are concentrating demand toward TSCA Title VI certified hardwood panels.
- Marine Plywood:Waterproof adhesive systems and void-free cores satisfy ABYC and NMMA standards for boatbuilding applications.
- Structural Plywood:Engineered span ratings and bond durability specifications govern load-bearing applications per APA performance standards.
Softwood plywood holds installed capacity. Hardwood plywood is rotating up the share rankings.
Application:
End-use specifications determine grade requirements, with structural codes governing construction while aesthetic standards drive furniture and cabinetry selection.
- Construction:Wall sheathing, roof decking, and subflooring consume structural grades governed by IRC and IBC code adoption. Mass timber building code expansion into mid-rise commercial is extending plywood demand beyond traditional single-family residential.
- Furniture:Decorative hardwood plywood with premium face veneers serves casegoods and upholstery frames. CARB Phase 2 and TSCA Title VI emission certifications are becoming baseline requirements for retail channel access.
- Flooring:Underlayment grades provide dimensional stability for finished floor systems in residential and light commercial.
- Cabinetry:Hardwood plywood with hardwood or thermally fused laminate faces supplies kitchen and bath manufacturers.
Construction maintains volume leadership. Furniture is climbing the fastest on emission compliance differentiation.
End User:
Customer type governs procurement scale and specification complexity, from fragmented residential builders to consolidated national accounts.
- Residential:Single-family and multi-family builders purchase structural sheathing through distribution or direct mill relationships. Prefabricated wall panel factories in the US Southeast are consolidating sheathing purchases through direct mill contracts.
- Commercial:Office, retail, and hospitality developers specify architectural grades with documented emission compliance for LEED and WELL certification.
- Industrial:Packaging, crating, and material handling applications consume lower-grade structural panels.
- Institutional:Schools, healthcare, and government buildings mandate low-emitting materials per California DGS and similar state procurement codes.
Residential anchors volume throughput. Institutional is gaining share fastest on green building procurement mandates.
Thickness:
Panel dimension correlates with structural span capacity and end-use durability requirements, with thicker grades commanding premium positioning.
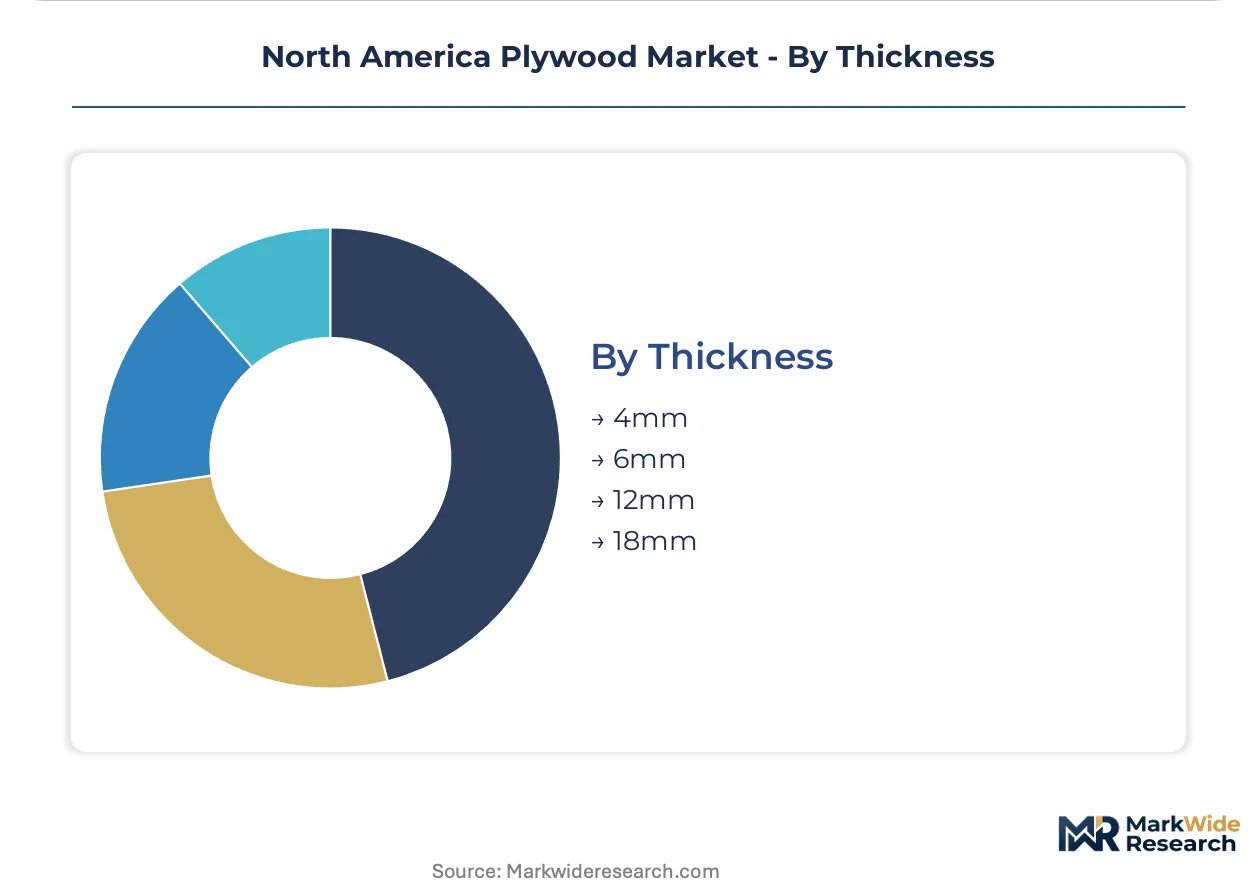
- 18mm:Standard subflooring and roof decking thickness for residential platform framing, typically specified as 23/32" in US markets.
- 12mm:Wall sheathing and cabinet box construction grade balancing stiffness and weight.
- 6mm:Underlayment, drawer bottoms, and furniture backing applications.
- 4mm:Specialty facing and bent lamination applications requiring conformability.
18mm holds the production base. 12mm is rotating up the share rankings on multi-family construction density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Southeast consumes structural plywood at intensities unmatched elsewhere in North America, driven by multi-family wood-frame construction codes, while Canadian demand concentrates in cross-laminated timber feedstock and Pacific Coast architectural grades.
United States
Texas and Florida absorb structural sheathing volumes through five-over-one multi-family construction booms. EPA TSCA Title VI enforcement compresses certification timelines for domestic mills and importers alike. Mill capacity clusters within 300-mile haul zones of Atlanta, Georgia and Charlotte, North Carolina.
Canada
British Columbia veneer peeling operations face fiber constraints from mountain pine beetle damage, redirecting supply focus to Alberta and Quebec timber bases. Health Canada/PMRA dual oversight experience accelerates compliance navigation for cross-border panel shipments. Rail-linked production in Vancouver anchors Canadian supply into US distribution channels.
Mexico
Northern border states consume structural grades for maquiladora-adjacent warehouse and light industrial construction. Mexican federal environmental standards reference CARB Phase 2 benchmarks for emission-labeled import eligibility. Monterrey-based fabricators serve regional cabinetry demand through hardwood plywood distribution networks.
North America Plywood Market Key Industry Players
Capability concentration sits with integrated timber holders; scale advantage sits with coordinated multi-state mill networks. The market structure reflects a tiered competitive field where fiber security separates sustainable performers from volume-dependent operators. Three archetypes dominate: captive-supply integrated producers, scale-coordinated regional networks, and specialty-grade technology differentiators. Capacity expansion and emission-certification portfolio diversification represent the dominant competitive moves reshaping positioning.
Among North American integrated producers, Roseburg Forest Products exemplifies the captive-supply archetype through Oregon timber base control, while Georgia-Pacific occupies a position within the scale-coordinated tier across multiple southern states. West Fraser Timber Co. represents the cross-border supply anchor archetype, with Canadian production linked to US distribution infrastructure. Columbia Forest Products sits within the specialty-grade tier, differentiated by formaldehyde-free technology positioning.
| Leading Market Players |
|---|
| Roseburg Forest Products |
| Columbia Forest Products |
| Georgia-Pacific |
| Canfor Corporation |
| PotlatchDeltic |
| Boise Cascade |
| West Fraser Timber Co. |
| Tolko Industries |
| Weyerhaeuser Company |
| Others |
Cost & Logistics Intelligence
Mill undercapacity in the US Southeast during peak construction seasons compresses lead times and emboldens suppliers to enforce price premiums on structural sheathing contracts. This utilization dynamic tightens buyer leverage while rewarding integrated producers with captive fiber supplies.
Pricing Analysis
Long-term offtake agreements dominate procurement between national homebuilders and southern mill networks, though spot purchases spike during weather-driven demand surges. Price differentiation separates TSCA Title VI certified panels from uncertified imports, with volume scale and haul-zone proximity as secondary tiering factors. Cost compression in commodity structural grades is intensifying as OSB substitution elasticity captures tract housing specifications. National production homebuilders exhibit lowest price sensitivity due to direct mill relationships, while regional contractors face margin pressure from distribution markups.
Supply Chain Analysis
Southern yellow pine timber bases in Georgia, Alabama, and Mississippi anchor North American veneer peeling capacity, with Douglas fir from Oregon and Washington as secondary feedstock. Resin chemistry, peeler log quality, and energy inputs constitute the critical cost stack. Single-source vulnerability concentrates in British Columbia fiber supply damaged by mountain pine beetle infestations. Distribution runs through rail-linked mill networks serving 300-mile haul zones, with national distribution cooperatives consolidating regional price discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through prefabricated wall panel factories and national distribution cooperatives that bypass traditional two-step channels. This procurement consolidation fragments legacy supplier relationships.
For Market Incumbents: Insulate fiber security through backward integration into timberland holdings or long-term stumpage agreements, as mountain pine beetle damage in British Columbia threatens cross-border supply stability. Prioritize TSCA Title VI certification portfolio breadth to defend specification access against low-cost Southeast Asian imports facing EPA third-party certifier bottlenecks. For New Entrants and Emerging Players: Establish a beachhead in low-emitting hardwood plywood for California institutional procurement, where CARB Phase 2 and TSCA Title VI mandates create compliance barriers for commodity importers. Target direct relationships with offsite construction factories in Texas and Florida that consolidate sheathing purchases outside traditional distribution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous press upgrade cycles, favoring scaled operators with maintenance capital discipline over fragmented regional mills. Focus acquisition screening on integrated producers with rail-served mill networks and APA-audited quality systems. Monitor EPA third-party certifier capacity expansion as an inflection signal for import competition intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Press Upgrade | Reduces energy intensity and quality variance for PS 1-19 structural grades. |
| Captive Timberland Acquisition | Secures stumpage supply against beetle-damaged British Columbia fiber constraints. |
| TSCA Title VI Certification Expansion | Unlocks California public procurement and LEED-specified commercial projects. |
| Rail Infrastructure Investment | Extends competitive haul zones from 150 to 300 miles for Southeast mill networks. |
| Prefabricated Panel Partnership | Captures consolidated sheathing demand from offsite construction factories. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mill operations managers, national homebuilder procurement directors, APA quality auditors, distribution cooperative buyers, and resin formulation chemists. Secondary validation drew from EPA enforcement bulletins, APA production statistics, FERC rail rate filings, and customs trade data. Bottom-up volume estimates triangulated against top-down construction spending models.
Calibration against historical capacity utilization and price realization data anchored projections across the analysis window. Segmentation modeling incorporated product type, application, end user, and thickness dimensions alongside regional mill capacity clusters. CAGRs were derived from elasticity-adjusted demand curves and supply-side constraint scenarios, with multi-family construction permit velocity and mass timber code adoption as key forecast inputs.
Stress conditions across timber input volatility, import certification friction, and OSB substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EPA enforcement continuity and building code adoption timelines. Quarterly review of construction permit data, mill operating rates, and third-party certifier queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Building and Construction Sealants Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Precast Concrete Manufacturing Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
North America Steel Rebar Market