
 United Kingdom Timber Cladding Market | 2026-2036
United Kingdom Timber Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Timber Cladding Market Analytics
Merchant distribution networks for timber cladding is tilting toward specialist cladding distributors and direct-to-contractor channels. Vastern Timber Limited leverages its Bristol manufacturing base to control regional supply chains across southern England. BSW Timber Ltd anchors bulk volume through integrated sawmilling and treatment facilities in Scotland. Accsys differentiates via modified timber technologies that extend service life in harsh coastal exposures.
United Kingdom timber cladding comprises profiled timber boards and shingles applied as external weather-resistant facades, typically specified in thicknesses from 18 mm to 25 mm with moisture content below 20 percent at installation. These assemblies protect structural walls from precipitation while providing breathable vapor control and aesthetic warmth for building envelopes. Western Red Cedar commands premium positioning in residential applications where natural durability reduces lifecycle maintenance. Horizontal installation methods dominate commercial projects seeking cost efficiency through familiar detailing and faster on-site assembly. Treated finish types are gaining specification share as architects balance appearance requirements with extended warranty periods.
Building Regulations Part L and British Standards BS 8417 govern preservative treatment classes and durability categories for external timber use across England, Wales, Scotland, and Northern Ireland. The Timber Research and Development Association publishes best-practice guidance that influences insurance-backed warranty schemes and mortgage lender acceptance criteria. Stakeholders must monitor evolving carbon accounting rules for biogenic materials in whole-life assessments as these frameworks reshape specification priorities across public procurement pathways.
Market Dynamics
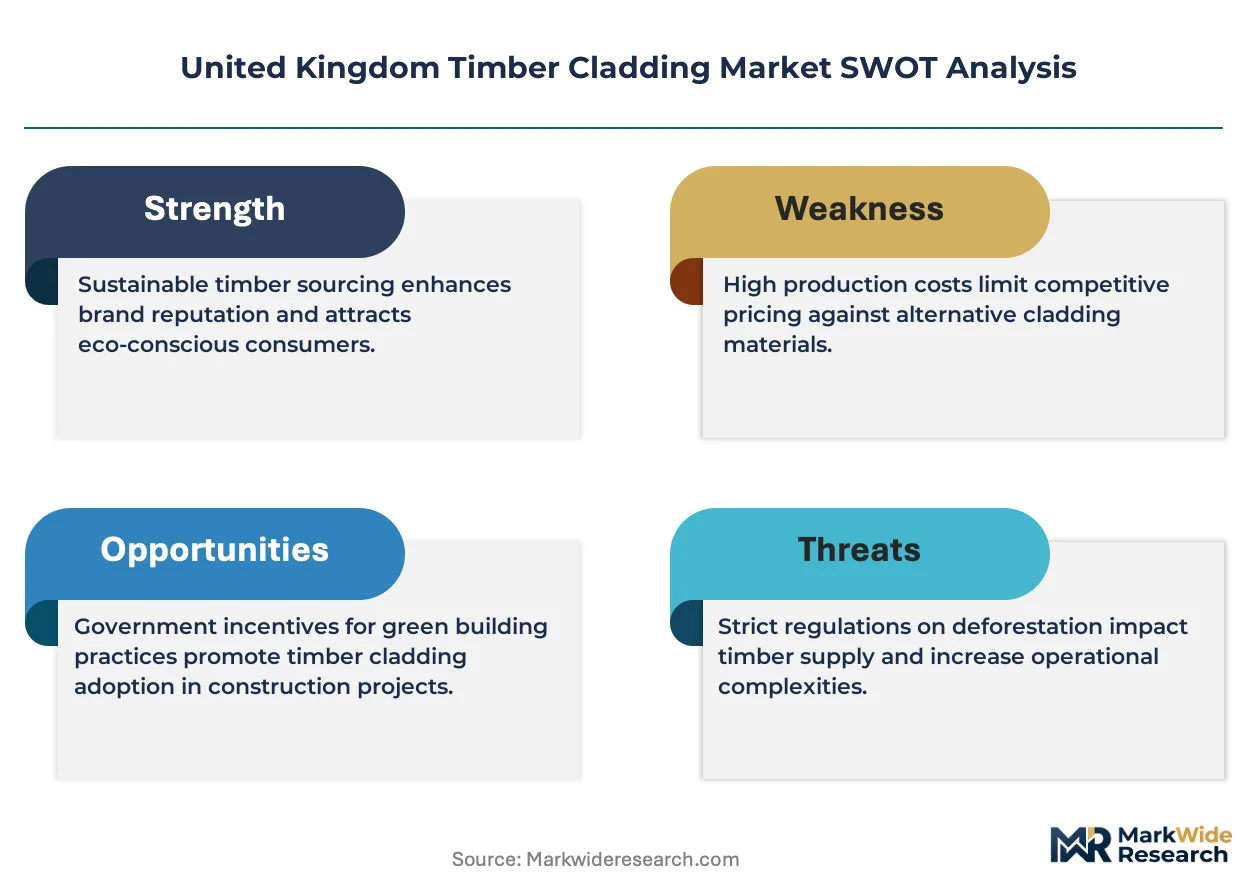
Building Regulations Part L conservation of fuel and power is tightening thermal performance requirements for external walls across England, Wales, Scotland, and Northern Ireland. This regulatory compression is forcing residential housing developers to expand specification of certified timber facades with enhanced insulation integration.
Growth Catalysts
- Part L thermal upgrades:The UK's Building Regulations mandate improved U-values for external walls, accelerating specification of timber cladding systems with integrated breathable membranes and insulation cavities.
- Biogenic carbon accounting:Whole-life carbon assessment frameworks are elevating timber's specification priority in public procurement pathways as architects document embodied carbon reductions.
- South East England residential pipeline:Housing development corridors spanning Oxfordshire, Surrey, and Greater London concentrate demand for Western Red Cedar and modified timber facades in premium residential schemes.
Market Restraints
- Western Red Cedar import dependency:Premium durable species rely on North American supply chains exposed to currency volatility, shipping capacity constraints, and trade policy friction.
- Treatment chemical availability:Preservative formulations meeting BS 8417 durability categories face input cost pressure from biocide regulation under EU REACH and UK REACH divergence scenarios.
- Modified timber capacity limits:Accoya and thermally modified wood production scales constrain volume availability for large-scale commercial projects seeking extended service life warranties.
Strategic Opportunities
- Scottish sawmilling integration:Bulk volume producers with captive timber supply and treatment facilities can anchor specification share in social housing and commercial segments.
- Direct-to-contractor digital channels:Specialist cladding distributors are building specification tools and BIM object libraries that bypass traditional merchant intermediaries.
- Coastal exposure applications:Modified timber technologies with proven performance in harsh marine environments can displace composite and fibre cement alternatives in Cornish, Welsh, and Scottish coastal developments.
Industry Challenges
- Installer competency gaps:Moisture content control, secret fixing methods, and vapour-open assembly detailing require skilled carpentry labour in short supply across southern England construction markets.
- Warranty alignment complexity:Insurance-backed guarantee schemes, mortgage lender acceptance criteria, and British Standards compliance timelines create specification friction for innovative timber systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Timber Cladding Market |
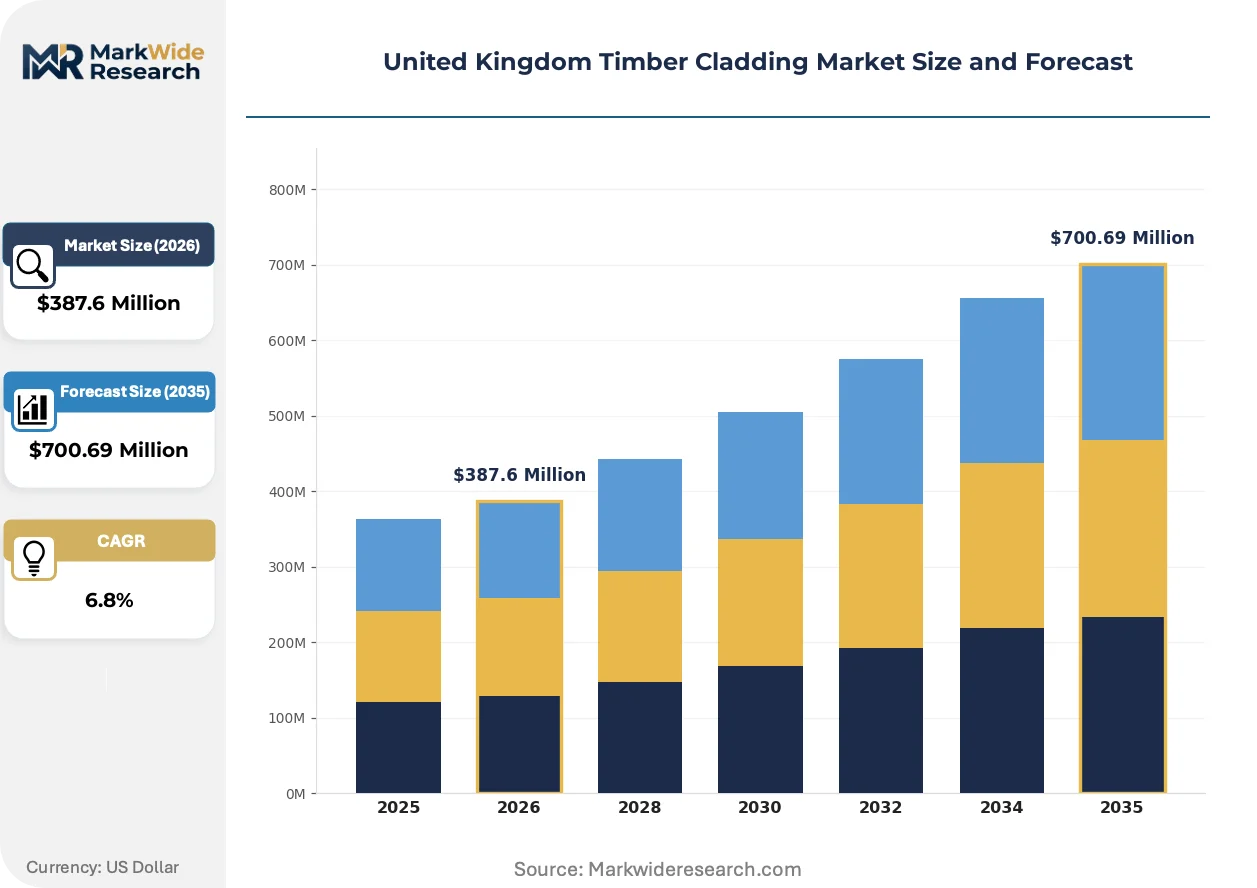
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Western Red Cedar, Larch, Oak, Pine Application: Residential, Commercial, Industrial, Recreational Finish Type: Natural, Stained, Painted, Treated Installation Method: Vertical, Horizontal, Overlapping, Lap |
| Companies Covered | Vastern Timber Limited, BSW Timber Ltd, Timbmet, NORclad Ltd., The Brookridge Group, Accsys, Glenalmond Timber Company Ltd, Howarth Timber Group, Russwood Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Timber Cladding Market Evolving Landscape
Specification workflows for timber cladding are digitising rapidly as architects and contractors seek to compress design-to-installation cycles. Three interconnected shifts are restructuring how materials are selected, procured, and assembled on site.
Building information modelling is virtualizing the specification process for timber cladding systems. Architects in commercial and residential practices are embedding manufacturer-supplied BIM objects directly into envelope designs. This compression is eliminating traditional sample-based selection cycles and accelerating design intent translation into procurement schedules.
The UK's divergence from EU REACH is creating regulatory complexity for preservative treatment formulations. Biocide approval timelines and dual-compliance obligations are increasing formulation costs for treatment facilities serving both UK and Irish markets. Scottish and Irish sawmillers with integrated treatment capacity are responding by segregating production lines and stockholding positions.
Merchant distribution networks for timber cladding are fragmenting as specialist cladding distributors capture specification influence. These specialists combine technical advisory services with direct contractor fulfilment, compressing traditional two-step merchant channels. The South East England corridor shows this pattern most visibly, where housing developers specify through distributor-led design-and-build packages rather than merchant procurement desks.
United Kingdom Timber Cladding Market Segmentation
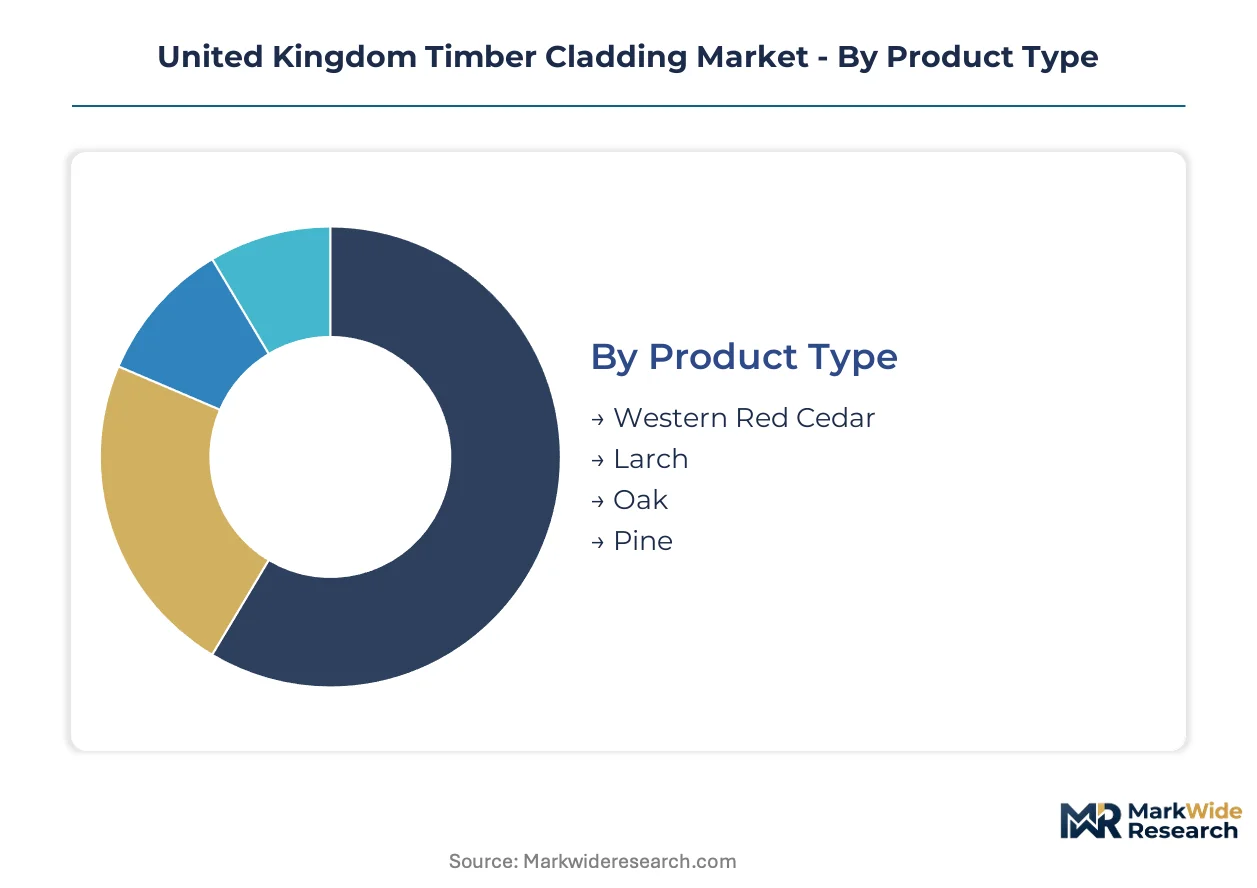
Timber cladding specification in the United Kingdom fragments across species selection, building typology, surface treatment, and assembly orientation. Each dimension carries distinct warranty implications, installer competency requirements, and supply chain lead times that reshape procurement decisions across housing developers and commercial contractors.
Product Type:
After-sales service intensity varies sharply across species grades, with premium durable hardwoods demanding specialist maintenance protocols while treated softwoods integrate into standard builder warranty schemes.
- Western Red Cedar:This lightweight, dimensionally stable species offers natural resistance to decay without chemical treatment. Demand concentrates in Surrey and Oxfordshire premium residential schemes where architects specify clear grades for visible facades and extended service life justifies import premiums.
- Larch:A domestic softwood with moderate natural durability, larch develops a distinctive silver-grey weathering patina. Scottish sawmillers anchor volume supply for social housing and commercial projects across Greater London where cost efficiency outweighs premium aesthetics.
- Oak:Dense hardwood valued for structural cladding applications and heritage restoration matching. Specification tracks conservation-area projects requiring traditional material continuity.
- Pine:Treated plantation softwood serving budget-conscious residential extensions and agricultural buildings. Pressure-treated formulations extend service life for cost-sensitive segments.
By volume, pine leads through mass housing and agricultural applications. By growth pace, Western Red Cedar is ahead as premium residential developers chase biogenic carbon credentials and reduced lifecycle maintenance.
Application:
Cost tier stratification separates specification workflows, with luxury residential commanding bespoke design services while industrial procurement prioritizes bulk volume discounts and rapid fulfillment.
- Residential:Single-family homes and multi-unit housing drive specification diversity across species and finishes. South East England corridors concentrate demand for certified timber with integrated breathable membranes meeting Part L thermal upgrades.
- Commercial:Offices, retail, and hospitality projects favor horizontal installation methods for faster envelope completion. Standardized detailing reduces site labor costs and accelerates programme delivery.
- Industrial:Warehousing and manufacturing facilities specify treated pine and larch for cost efficiency. Durability requirements focus on weather resistance rather than aesthetic grading.
- Recreational:Visitor centers, sports facilities, and educational buildings balance visual warmth with high-traffic durability. Modified timber technologies gain traction for extended warranty periods.
Residential commands absolute volume through housing pipeline density. Commercial is expanding most quickly as post-occupancy evaluation data validates timber's biophilic productivity benefits.
Finish Type:
Customer type divides the market, with architect-specified natural finishes commanding premium positioning while contractor-procured treated options dominate volume housing.
- Natural:Unfinished timber left to weather organically, prized by sustainability-focused clients for eliminating coating maintenance and VOC emissions. Coastal Cornish developments favor modified timbers with proven marine exposure performance.
- Stained:Semi-transparent coatings preserving grain visibility while moderating color shift. Specification tracks mid-market residential seeking controlled aesthetic evolution.
- Painted:Opaque finishes enabling color matching to branding or planning requirements. Commercial applications use factory-applied systems for quality control.
- Treated:Preservative formulations meeting BS 8417 durability categories for hazardous use classes. Social housing and industrial segments prioritize warranty alignment over appearance.
Treated finishes lead by volume through housing association and local authority procurement. Natural finishes are climbing the fastest as whole-life carbon assessments elevate maintenance-free specifications.
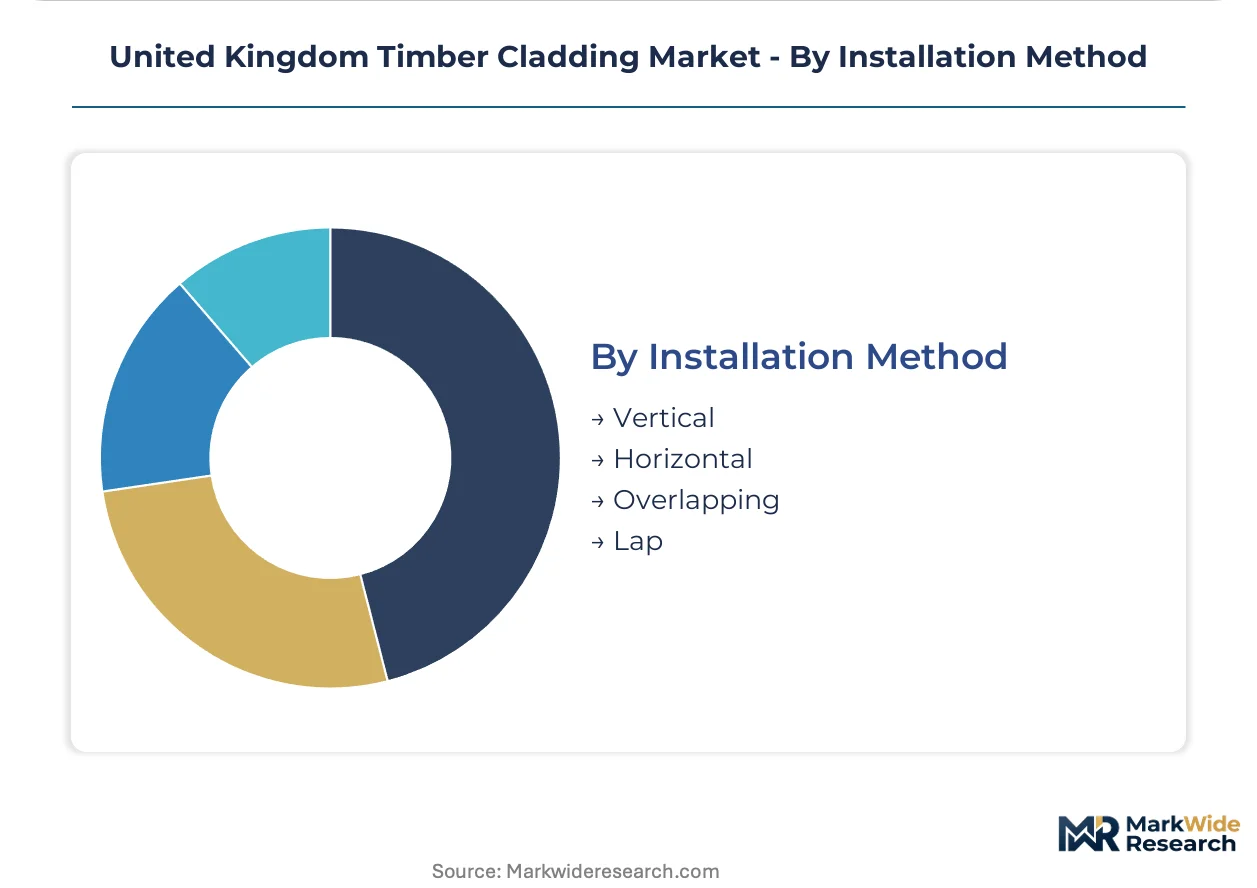
Installation Method:
Supply concentration shapes availability, with horizontal systems dominating merchant stockholding while vertical and specialist fixings flow through distributor-led design-and-build packages.
- Vertical:Board-on-board or channel-gap arrangements creating contemporary aesthetic with enhanced water-shedding. Specification concentrates in architect-designed one-off homes across Oxfordshire and Bristol corridors.
- Horizontal:Traditional clapboard or shiplap profiles familiar to site carpenters across southern England. Faster installation speeds dominate commercial programmes seeking programme certainty.
- Overlapping:Rustic featheredge profiles for agricultural and rural outbuilding applications. Cost minimization drives specification through direct sawmill procurement.
- Lap:Rabbeted edge profiles creating weather-tight joints without additional flashings. Heritage restoration and conservation area projects require traditional detailing compliance.
Horizontal installation leads by volume through commercial familiarity and labour availability. Vertical systems are gaining share fastest as contemporary residential aesthetics displace traditional styling preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium timber cladding commands higher margins in South East England than in Scottish bulk markets, creating a pricing-power asymmetry that shapes manufacturer location decisions and distribution network investments across the United Kingdom.
London and South East England
Housing developers in Oxfordshire, Surrey, and Greater London specify Western Red Cedar and modified timber facades for premium residential schemes. Building Regulations Part L mandates improved U-values for external walls, accelerating demand for certified timber with integrated breathable membranes. Merchant distribution networks fragment here as specialist cladding distributors capture specification influence through design-and-build packages.
Scotland
Scottish sawmillers anchor bulk volume supply for social housing and commercial projects through integrated sawmilling and treatment facilities. The UK's divergence from EU REACH creates regulatory complexity for preservative formulations, prompting Scottish producers to segregate production lines for UK and Irish markets. Edinburgh and Glasgow corridors concentrate demand for treated larch in cost-sensitive segments.
Wales
Coastal developments in Pembrokeshire and Gwynedd favor modified timber technologies with proven performance in harsh marine exposures. Welsh housing associations prioritize warranty-aligned treated finishes over natural weathering options. Cardiff and Newport construction markets source cladding through distributor channels that bypass traditional merchant intermediaries.
Midlands
Birmingham and Nottingham housing developers balance cost efficiency with Part L compliance, driving specification of treated pine and larch for volume residential schemes. The region's central location supports distribution hub strategies for national merchant networks. Installer competency gaps in moisture content control and secret fixing methods create specification friction for innovative timber systems.
Northern England
Manchester and Leeds commercial projects favor horizontal installation methods for faster envelope completion and programme certainty. Industrial warehousing and manufacturing facilities in Yorkshire specify treated softwoods for weather resistance rather than aesthetic grading. Regional distributors build specification tools and BIM object libraries to compress design-to-installation cycles.
United Kingdom Timber Cladding Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying raw material and treatment services. The United Kingdom timber cladding market structures around three tiers: bulk volume producers with captive timber supply, specialist cladding distributors with technical advisory capabilities, and modified timber technology licensors. Competitive moves concentrate on Scottish sawmilling integration for supply security and direct-to-contractor digital channel development for specification capture.
Among Bristol-based manufacturers, Vastern Timber Limited occupies a position within the regional supply chain control archetype, leveraging proximity to southern England demand corridors. BSW Timber Ltd represents the integrated sawmilling archetype with facilities in Scotland. Accsys exemplifies the modified timber technology tier, differentiating through extended service life warranties in harsh coastal exposures.
| Leading Market Players |
|---|
| Vastern Timber Limited |
| BSW Timber Ltd |
| Timbmet |
| NORclad Ltd. |
| The Brookridge Group |
| Accsys |
| Glenalmond Timber Company Ltd |
| Howarth Timber Group |
| Russwood Ltd |
| Others |
Value Network & Pricing Analysis
North American Western Red Cedar supply concentration in British Columbia and Washington State feeds premium margin pools to specialist cladding distributors serving Oxfordshire and Surrey residential developers. This upstream geography locks in import dependency that amplifies currency-driven cost volatility across the South East England corridor.
Pricing Analysis
Configured-to-order pricing for certified clear-grade Western Red Cedar commands substantial premiums over standard treated pine stockholding. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade, with FSC Chain of Custody and PEFC endorsements driving architect-specified premiums. Cost compression in treated softwood tiers is intensifying because biocide formulation costs under UK REACH divergence are squeezing treatment facility margins. Social housing developers exhibit highest price sensitivity, while conservation-area heritage projects demonstrate lowest elasticity.
Supply Chain Analysis
Extended payment terms from housing developers are forcing distributor-led finance facilities and supply-chain finance structures upon Scottish sawmillers with captive timber supply. Production gravity centers on Scotland for treated larch, North America for Western Red Cedar, and the Netherlands for Accoya modified timber feedstock. Raw material dependencies encompass British Columbia coastal old-growth cedar, Scottish plantation spruce and larch, and acetylation-grade radiata pine. Single-source vulnerability to transatlantic shipping capacity constraints threatens just-in-time delivery commitments. Distribution runs through specialist cladding distributors capturing specification influence in the South East England corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building Regulations Part L thermal upgrade mandates are disrupting specification workflows as biogenic carbon accounting elevates timber priority in public procurement pathways.
For Market Incumbents: Build treatment technology moats through backward integration into preservative formulation facilities that segregate UK REACH and EU REACH compliance streams. Scottish sawmillers should anchor bulk volume share by adding acetylation capacity for modified timber production. This defends against composite cladding substitution in coastal exposure applications. Certification investment in FSC and PEFC Chain of Custody systems preserves architect specification access. For New Entrants and Emerging Players: Build out direct-to-contractor digital channels with BIM object libraries and vapor-open assembly detailing tools that bypass traditional merchant intermediaries. The Midlands installer competency gap presents the most penetrable white-space for technical advisory services targeting moisture content control and secret fixing methods. Go-to-market execution should lead with Part L compliance documentation and warranty alignment packages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialist cladding distributors holding South East England specification relationships and design-and-build contract flows. Long-term viability hinges on regulatory durability of biogenic carbon accounting frameworks and treatment chemical approval pathways under UK REACH divergence. Acquisition targets should demonstrate captive Scottish timber supply or proprietary modified timber licensing. Watch for Part L enforcement intensity and housing association procurement centralization as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Scottish Sawmilling Integration | Captive timber supply and treatment capacity anchors specification share in social housing procurement. |
| Direct-to-Contractor Digital Channel | BIM object libraries and specification tools compress design-to-installation cycles for architect practices. |
| Modified Timber Capacity Expansion | Acetylation and thermal modification facilities extend service life warranties for harsh coastal exposures. |
| UK REACH Compliance Segregation | Dual production lines preserve cross-border market access amid biocide regulatory divergence. |
| Installer Competency Programs | Moisture content control training addresses labor scarcity friction in southern England construction markets. |
Research Methodology
Initial hypotheses were tested against primary input from timber cladding specification architects, housing development procurement directors, Scottish sawmill operations managers, and specialist distributor technical advisors and refined through secondary validation. Primary fieldwork combined structured interviews with envelope design consultants and merchant category buyers. Secondary sources encompassed TRADA technical guidance documents, Building Regulations Part L compliance bulletins, British Standards BS 8417 durability classifications, and timber trade association import statistics. Bottom-up volume modeling triangulated against top-down construction output forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed species grade tier, building typology, surface treatment category, and installation orientation. CAGRs were derived from housing pipeline density projections and Part L compliance penetration curves. Industry-specific forecast inputs incorporated treated timber capacity utilization rates and modified timber production scale constraints.
Practitioners should monitor UK REACH biocide approval timelines, transatlantic shipping rate volatility, and housing association procurement centralization for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
PVC Window Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Europe Industrial Flooring Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Balustrade Market
Building & Construction Materials
SBS Waterproofing Membrane Market
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Europe Building Materials Market