
 Building Insulation Market | 2026-2036
Building Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Building Insulation Market Analysis
A shift from single-source mineral wool procurement to multi-material sourcing strategies is recalibrating how contractors and developers manage project risk. ROCKWOOL A/S anchors its position through captive basalt sourcing and European manufacturing density. Owens Corning competes via fiberglass technology leadership and channel control across North American distribution networks. BASF SE differentiates through polyurethane chemistry depth and spray-applied system integration.
Building insulation comprises engineered materials—fiberglass batts, rigid foam boards, loose-fill cellulose, and reflective membranes—designed to reduce conductive and convective heat transfer through building envelopes, typically measured by R-value per inch of thickness. The primary commercial purpose is to minimize heating and cooling energy loads while managing moisture migration and occupant comfort. Foam board dominates new commercial construction where continuous insulation requirements create premium margin pools, while blow-in cellulose sustains growth in residential retrofit channels where dense-pack applications address air sealing mandates. Mineral wool leads industrial and institutional segments due to fire resistance ratings and acoustic dampening properties that fiberglass struggles to match.
The EU Green Deal and REACH frameworks in Europe, alongside the EPA's ENERGY STAR certification requirements and state-level stretch codes in the United States, are tightening thermal performance thresholds and restricting certain flame retardant chemistries. These regulations are forcing manufacturers to reformulate core products and expand third-party certification coverage to maintain market access. Stakeholders must monitor evolving embodied carbon accounting rules and prepare for material passport requirements that will reshape competitive positioning in specification-driven segments.
Market Dynamics
EU Green Deal enforcement is compressing retrofit timelines and forcing contractors to source higher-performance materials at scale, while mineral wool supply bottlenecks in basalt fiber are creating procurement urgency across cold-climate housing markets.
Growth Catalysts
- EU Green Deal retrofit mandates:France and Germany now require thermal bridge remediation in existing residential stock, pulling demand for dense-pack cellulose and rigid foam systems.
- REACH flame retardant restrictions:Manufacturers reformulating halogen-free chemistries are capturing specification share in institutional projects where fire ratings govern procurement.
- Cold-climate housing stock deterioration:Nordic and Baltic markets face accelerated envelope replacement cycles as energy poverty reduction programs expand subsidy pools.
Market Restraints
- Basalt fiber supply concentration:Captive mining rights in Scandinavia and Russia constrain mineral wool expansion for non-integrated producers.
- Polyurethane feedstock volatility:MDI and polyol pricing swings compress margin stability for spray-foam contractors on fixed-bid projects.
- Technical limitation in historic envelopes:Breathable insulation requirements in heritage-protected structures block standard vapor-barrier systems.
Strategic Opportunities
- Underpenetrated Polish residential retrofit:Single-family housing stock with sub-100 mm envelope insulation represents white space for blow-in contractors.
- Industrial heat recovery integration:Combined thermal-acoustic mineral wool systems are capturing data center and logistics warehouse specifications.
- Digital material passports:Early compliance with France's RE2024 embodied carbon tracking creates specification advantage in public procurement.
Industry Challenges
- Certified installer scarcity:Dense-pack cellulose and spray-foam applications require manufacturer-authorized training that outpaces workforce pipeline capacity.
- Legacy HVAC integration friction:Downsized heating loads from high-R envelopes conflict with existing boiler sizing and distribution hydronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Insulation Market |
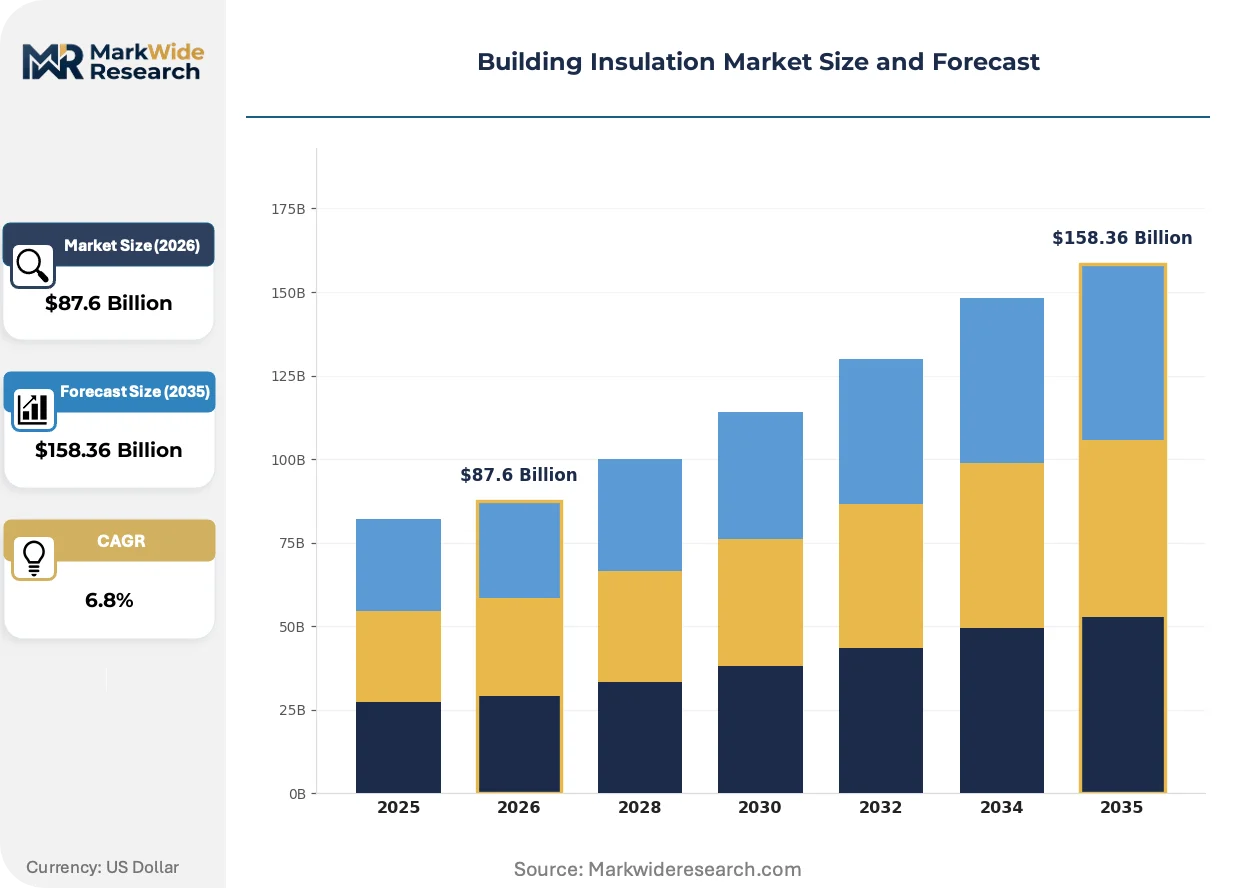
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Board, Reflective, Blow-in, Batt Material: Polyurethane, Fiberglass, Cellulose, Mineral Wool End User: Residential, Commercial, Industrial, Institutional Installation Method: Sprayed, Fitted, Loose-fill, Injected |
| Companies Covered | ROCKWOOL A/S, Johns Manville, Owens Corning, Dow Inc., BASF SE, Saint-Gobain, Knauf Group, TopBuild Corp., Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Insulation Market Emerging Trajectories
Material science convergence and digital specification tools are compressing product development cycles while fragmenting procurement authority across architects, contractors, and energy auditors.
Prefabricated insulated panel systems are modularizing cold-climate envelope construction. Scandinavian multifamily developers now specify factory-integrated mineral wool and OSB assemblies that cut site labor by half. This shift is compressing traditional batt-and-board distribution channels while opening specification access for panelized system integrators.
REACH Annex XVII restrictions on halogenated flame retardants are forcing reformulation across rigid foam and EPS categories. German and Dutch manufacturers now prioritize phosphorus-based chemistries in commercial roofing applications. The construction chemicals segment is responding with expanded third-party fire testing to maintain Building Research Establishment certification coverage.
Energy audit software is consolidating specification influence. French and Belgian contractors now source insulation through platforms that auto-generate material schedules from thermal imaging data. This channel shift is visible in residential retrofit verticals where subsidy eligibility depends on modeled performance guarantees rather than product brand preference.
Building Insulation Market Segmentation
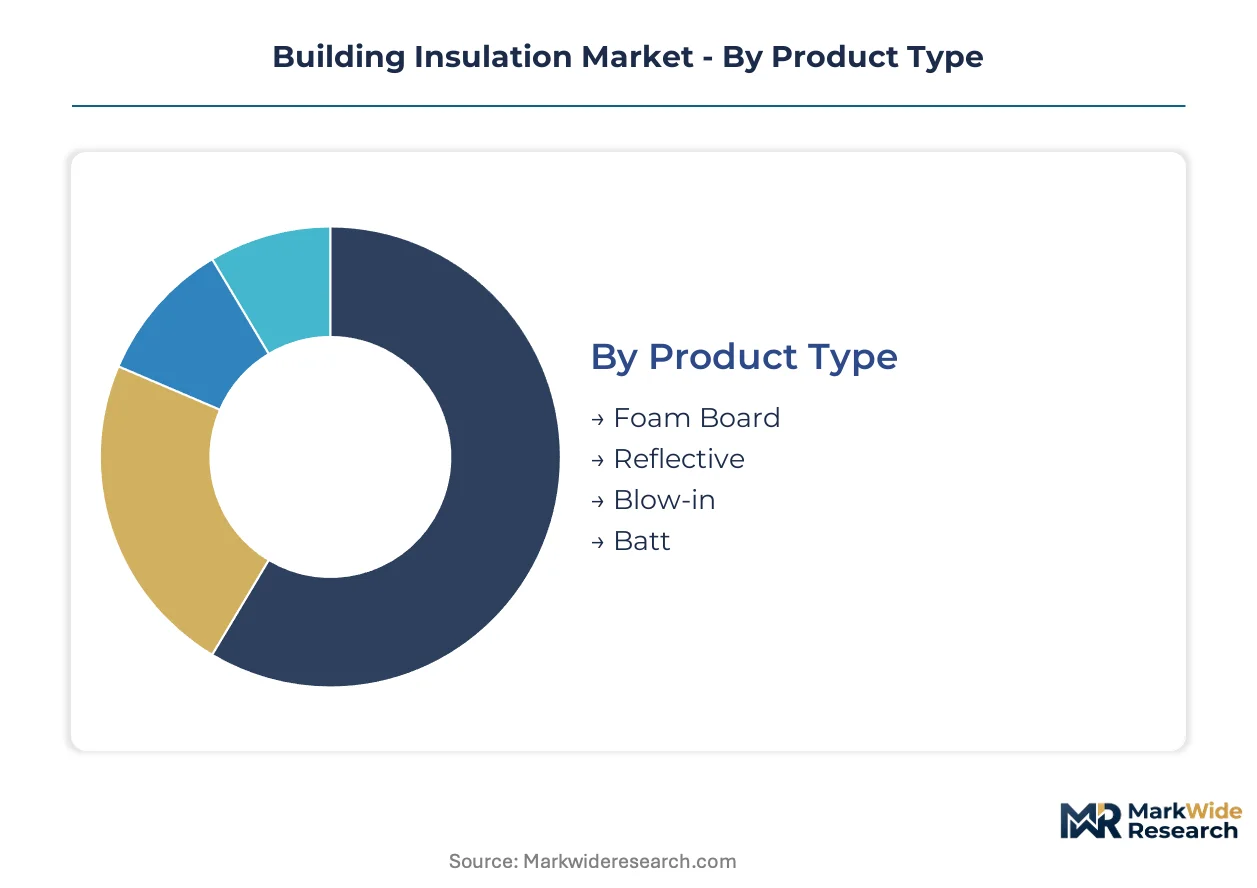
Segmentation in building insulation reveals how capital deployment, regulatory pressure, and installation economics fragment procurement authority across product categories. Manufacturers must align production footprints with the capital intensity and margin structures of specific material systems.
Product Type:
Capital intensity peaks in foam board manufacturing where continuous extrusion lines and blowing agent containment systems demand heavy upfront investment. Reflective systems require minimal fixed capital but depend on metallized film supply chains.
- Foam Board:Rigid polyisocyanurate and XPS boards deliver the highest R-values per inch for continuous insulation applications. Demand concentrates in North American commercial construction where ASHRAE 90.1 thermal bridging mandates have tightened. Premium margin pools attract integrated chemical producers with captive MDI supply.
- Blow-in:Cellulose and fiberglass loose-fill systems require specialized blowing equipment and dense-pack training infrastructure. Retrofit contractors in Germany and France source blow-in cellulose for EU Green Deal–compliant residential envelope upgrades where air sealing guarantees determine subsidy eligibility.
- Reflective:Radiant barrier films and foil-faced bubble wraps address convective heat transfer in hot-climate attics.
- Batt:Pre-cut fiberglass and mineral wool batts serve standard stud-bay applications with lowest installed cost per square meter.
Most installed capacity flows through Batt. Expansion is steepest in Blow-in.
Material:
Raw material sourcing geography and feedstock volatility divide competitive positions across chemistry families. Polyurethane producers face MDI concentration risk while mineral wool operators compete on basalt fiber security.
- Polyurethane:Spray-applied and rigid foam systems derive from isocyanate and polyol chemistries with formulation flexibility for varying density and fire performance. Cold-climate housing markets in the Nordic region specify high-density spray foam for thermal bridge remediation where continuous insulation is mandatory.
- Mineral Wool:Basalt and slag fiber melts produce non-combustible insulation with acoustic dampening properties. Industrial and institutional specifications in France favor mineral wool for fire resistance ratings that fiberglass cannot match under RE2024 safety codes.
- Fiberglass:Molten glass fiber spinning yields cost-competitive thermal insulation for residential volume markets.
- Cellulose:Recycled paper fiber with borate fire retardant serves dense-pack retrofit applications.
Volume leadership sits with Fiberglass. Value capture is climbing fastest in Polyurethane.
End User:
Project scale and specification authority vary dramatically across building types, with institutional procurement governed by fire rating requirements and residential retrofit driven by subsidy program design.
- Residential:Single-family and multifamily housing stock drives batt and blow-in demand through new construction and energy retrofit channels. German KfW subsidy programs and French MaPrimeRénov schemes pull dense-pack cellulose and rigid foam board into existing building envelopes.
- Commercial:Office, retail, and hospitality construction specifies continuous insulation systems for curtain wall and roofing assemblies. US state stretch codes in California and New York mandate higher R-values that favor foam board and spray-applied polyurethane.
- Industrial:Manufacturing facilities and process plants require high-temperature mineral wool for equipment insulation.
- Institutional:Schools, hospitals, and government buildings prioritize fire safety and acoustic performance in specification.
Residential commands the largest addressable base. Commercial is gaining share fastest on continuous insulation mandates.
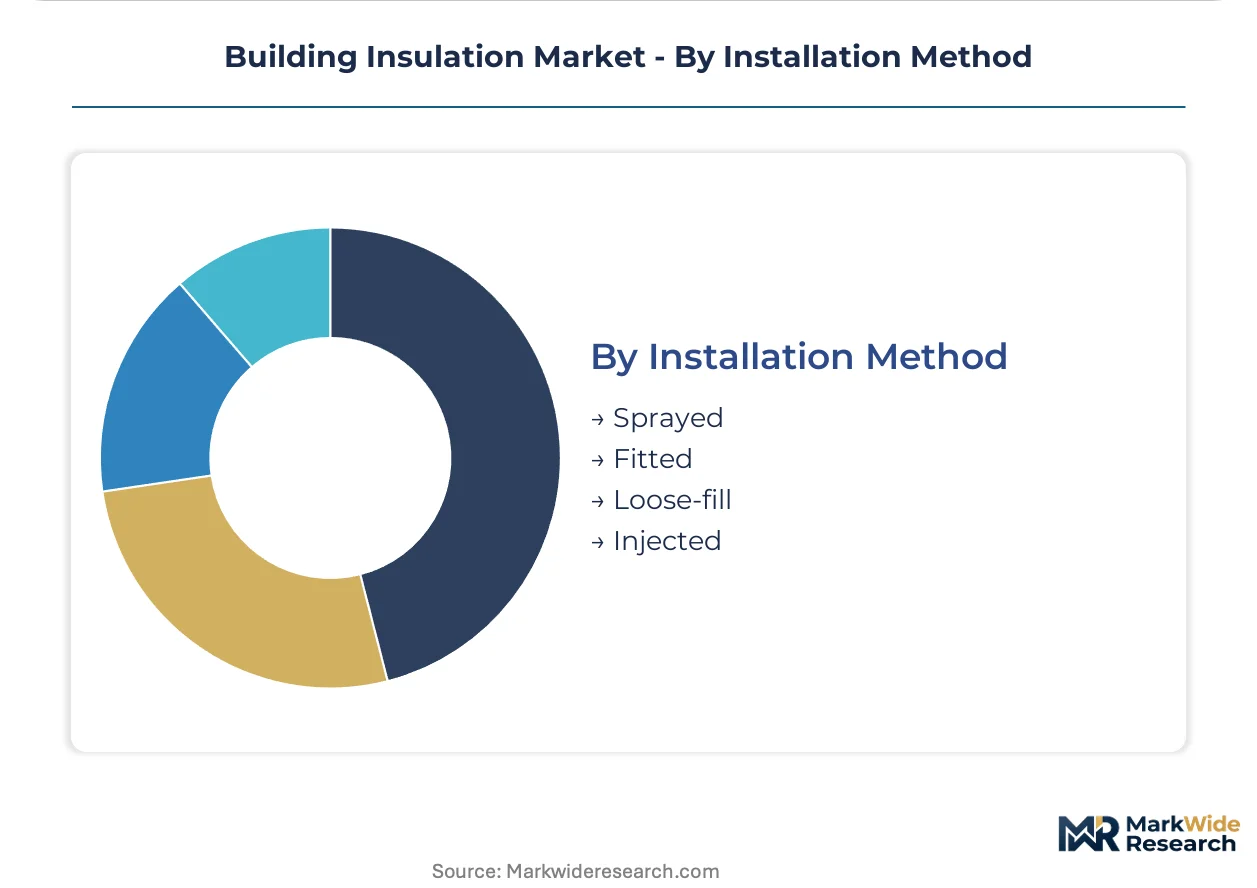
Installation Method:
Labor skill requirements and equipment economics determine contractor specialization, with sprayed systems creating the highest barriers to entry through manufacturer-authorized certification programs.
- Sprayed:Polyurethane foam and cementitious coatings require proportioning equipment and applicator certification for consistent thickness and adhesion. US contractors serving ENERGY STAR–certified new home programs rely on sprayed foam for air barrier continuity that batt systems cannot achieve.
- Fitted:Precut batts and rigid boards install with basic carpentry skills and staple guns. Volume residential builders in Poland and Romania deploy fitted mineral wool and fiberglass for cost-sensitive new construction where labor rates compress total installed cost.
- Loose-fill:Blown fiberglass and cellulose fill irregular cavities and attic floors.
- Injected:Slow-rise foam and dense-pack cellulose fill enclosed wall cavities through small access holes.
Fitted methods dominate by project count. Sprayed applications are climbing fastest on performance-based code adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting mineral wool capacity toward jurisdictions with basalt fiber security and streamlined REACH compliance pathways. Producers are relocating extrusion assets to capture EU Green Deal subsidy flows while sidestepping feedstock concentration risks in Scandinavia and Russia.
Germany
KfW subsidy programs are pulling dense-pack cellulose and rigid foam into single-family retrofits across Bavaria and North Rhine-Westphalia. The national building energy code (GEG) mandates thermal bridge remediation in existing stock. The Stuttgart industrial corridor hosts prefabricated panel integrators supplying factory-integrated mineral wool assemblies to multifamily developers.
France
MaPrimeRénov schemes are accelerating blow-in contractor deployment in Île-de-France and Auvergne-Rhône-Alpes. RE2024 embodied carbon tracking requirements are reshaping public procurement specifications. Lyon-based building research centers are certifying halogen-free foam formulations for commercial roofing applications.
United States
State stretch codes in California and New York are tightening ASHRAE 90.1 thermal bridging mandates for commercial construction. ENERGY STAR certification requirements govern residential new home program eligibility. The Pacific Northwest cluster hosts spray-foam applicator training networks serving high-performance envelope specifications.
Poland
Single-family housing stock with sub-100 mm envelope insulation represents underpenetrated retrofit opportunity in Masovian and Silesian Voivodeships. EU cohesion funds are channeling energy poverty reduction subsidies into dense-pack cellulose programs. Warsaw-based contractors are scaling blown-in installation capacity to meet compressed EU Green Deal timelines.
Sweden
Nordic energy poverty reduction programs are accelerating envelope replacement cycles in Stockholm and Gothenburg metropolitan areas. Captive basalt mining rights anchor mineral wool production for industrial and data center specifications. The Skåne region hosts acoustic dampening system integrators targeting logistics warehouse projects.
Building Insulation Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue prefabricated panel integration and digital specification platforms. The market structures around three tiers: integrated chemical producers with captive feedstock, mineral wool operators with basalt security, and regional batt distributors with channel density. Strategic archetypes include backward-integrated specialty chemical players, Scandinavian mining-rights holders, and North American fiberglass spinners with distribution control. Competitive moves concentrate on M&A for installer network capture and capacity expansion in cold-climate manufacturing clusters.
Among Denmark-based mineral wool specialists, ROCKWOOL A/S exemplifies the mining-rights-anchored archetype through its captive basalt sourcing position. Owens Corning occupies a position within the fiberglass technology leadership tier, leveraging North American channel infrastructure. BASF SE represents the integrated chemical producer archetype with polyurethane chemistry depth and spray-applied system capabilities.
| Leading Market Players |
|---|
| ROCKWOOL A/S |
| Johns Manville |
| Owens Corning |
| Dow Inc. |
| BASF SE |
| Saint-Gobain |
| Knauf Group |
| TopBuild Corp. |
| Kingspan Group |
| Others |
Supply Flow & Price Mechanics
Captive basalt sourcing in Scandinavia and Russia anchors mineral wool producers' supply positions while insulating them from spot-market volatility that compresses pricing power for non-integrated competitors. This backward integration into raw material security allows ROCKWOOL A/S and similar operators to maintain premium positioning against fiberglass distributors dependent on external glass fiber supply.
Pricing Analysis
Distributor margin layers in European retrofit channels absorb 15-25 points before contractor markup, compressing manufacturer netbacks on standard batt products. Three-tier pricing structure across premium, standard, and economy levels separates certified spray-foam systems from commodity fiberglass batts, with RE2024 compliance premiums widening spreads in French public procurement. Cost compression in blow-in cellulose is intensifying because dense-pack installer certification scarcity limits contractor pool expansion. Residential retrofit contractors in Poland and Romania exhibit highest price sensitivity, while data center developers in Sweden prioritize fire-rated mineral wool with minimal bid-shopping.
Supply Chain Analysis
Single-source vulnerability sits with Scandinavian and Russian basalt mining concessions that constrain mineral wool expansion for non-integrated producers. Geographic supply concentration centers on Germany, Sweden, and the United States for fiberglass spinning; China, Germany, and Belgium for MDI/polyol polyurethane feedstocks; and Scandinavia for basalt fiber. Raw material dependencies include molten glass batch chemicals, isocyanate monomers, and metallized films for radiant barriers. Tariff exposure on Chinese glass fiber imports threatens North American batt pricing stability. Distribution runs through regional building-material distributors with contractor loyalty programs, though direct specification relationships with multifamily developers are gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in spray-applied polyurethane and prefabricated panel systems where technical certification barriers sustain pricing power against commodity batt alternatives. Cost-down drivers include automated blowing equipment deployment and captive basalt integration that flattens raw material volatility.
For Market Incumbents: Hedge against MDI feedstock volatility through long-term polyol supply agreements with BASF SE or Covestro AG, and secure installer network capacity through acquisition of regional spray-foam training centers. Mineral wool leaders should defend specification share by accelerating RE2024 embodied carbon certification coverage before France mandates digital material passports in public procurement.
For New Entrants and Emerging Players: Energy audit software platforms represent the most penetrable channel entry point, as French and Belgian contractors increasingly source insulation through auto-scheduling tools that bypass traditional distributor relationships. Target Polish single-family retrofit contractors with dense-pack cellulose equipment leasing programs tied to EU cohesion fund subsidy workflows. A go-to-market angle of guaranteed air-sealing performance modeled from thermal imaging data differentiates against product-brand-centric incumbents.
For Investors and Strategic Acquirers: Consolidation pressure builds where certified installer scarcity constrains spray-foam and dense-pack contractor pool expansion. Long-term viability favors integrated producers with captive raw material positions and specification-grade certification portfolios. Acquisition target archetypes include regional blow-in contractors with established KfW and MaPrimeRénov subsidy program relationships, and prefabricated panel integrators with Scandinavian multifamily developer track records. The signal to watch is France's RE2024 digital material passport enforcement timeline, which will reshuffle competitive positioning in public procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Mining | Captive raw material security insulates ROCKWOOL A/S from Scandinavian supply bottlenecks. |
| Installer Certification Network Expansion | Manufacturer-authorized training capacity outpaces dense-pack and spray-foam workforce pipeline. |
| Prefabricated Panel System Integration | Factory-integrated mineral wool assemblies cut site labor by half for Scandinavian multifamily developers. |
| Digital Material Passport Compliance | Early RE2024 embodied carbon tracking creates specification advantage in French public procurement. |
| REACH Halogen-Free Reformulation | Phosphorus-based chemistries capture institutional share as ECHA restrictions tighten. |
Methodological Framework
Multiple input streams — primary interviews with insulation contractors and energy auditors, secondary validation through customs and trade data, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Stakeholder roles engaged include dense-pack cellulose contractors, spray-foam applicator trainers, building envelope consultants, and procurement officers at multifamily developers. Secondary sources span ECHA REACH substance registrations, KfW and MaPrimeRénov subsidy disbursement records, SEC 10-K filings from listed building-material producers, and national building energy code enforcement data. Bottom-up project pipeline analysis and top-down construction spend allocation were triangulated against manufacturer shipment disclosures.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type (foam board, blow-in, batt, reflective), material chemistry (polyurethane, mineral wool, fiberglass, cellulose), end-use sector (residential, commercial, industrial, institutional), and installation method (sprayed, fitted, loose-fill, injected). CAGRs were derived from slope analysis of retrofit subsidy program budgets and new construction thermal code stringency indices. Industry-specific forecast inputs include EU Green Deal enforcement timelines and cold-climate housing stock deterioration rates in Nordic markets.
Revisions become necessary when REACH flame retardant restrictions accelerate, basalt fiber supply disruptions materialize, or embodied carbon accounting rules shift procurement specifications. Forecasts reflect documented assumptions about subsidy program continuity and installer certification pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Mexican Insulated Panels Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Sectional Door Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
North America Laminated Veneer Lumber Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Japan Concrete Conditioner Market