
 US Parking Deck Coatings Market | 2026-2036
US Parking Deck Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
US Parking Deck Coatings Market Intelligence
Distributor networks serving the US parking deck coatings sector is narrowing as national accounts consolidate procurement through direct manufacturer relationships. PPG Industries, Inc. leverages its architectural coatings infrastructure to secure specification-driven projects across Sun Belt metros. The Sherwin-Williams Company anchors volume through its contractor loyalty programs and same-day distribution from over 4,000 US stores. Sika AG competes by specializing in methyl methacrylate systems for rapid-turnover parking restorations.
US parking deck coatings comprise resin-based protective layers—typically 10–60 mils dry film thickness—engineered to resist carbonation, chloride ingress, and vehicular abrasion on reinforced concrete parking structures. Epoxy formulations dominate refurbishment work due to cost efficiency and established contractor familiarity, while polyaspartic systems capture premium new-build specifications where return-to-service speed commands priority. Application patterns reveal commercial parking structures generating the deepest volume pools, with institutional parking representing a margin-rich segment driven by extended warranty requirements and federal procurement standards.
EPA VOC regulations under 40 CFR Part 59 reshape product formulation thresholds, compelling manufacturers to shift from solvent-borne to waterborne and high-solids chemistries. State-level adoption of LEED v4.1 and Buy America provisions for federally funded infrastructure further filter eligible coating systems and contractor qualifications. Stakeholders must monitor evolving MUTCD reflectivity standards and state DOT maintenance cycles to align R&D investment with specification windows.
Market Dynamics
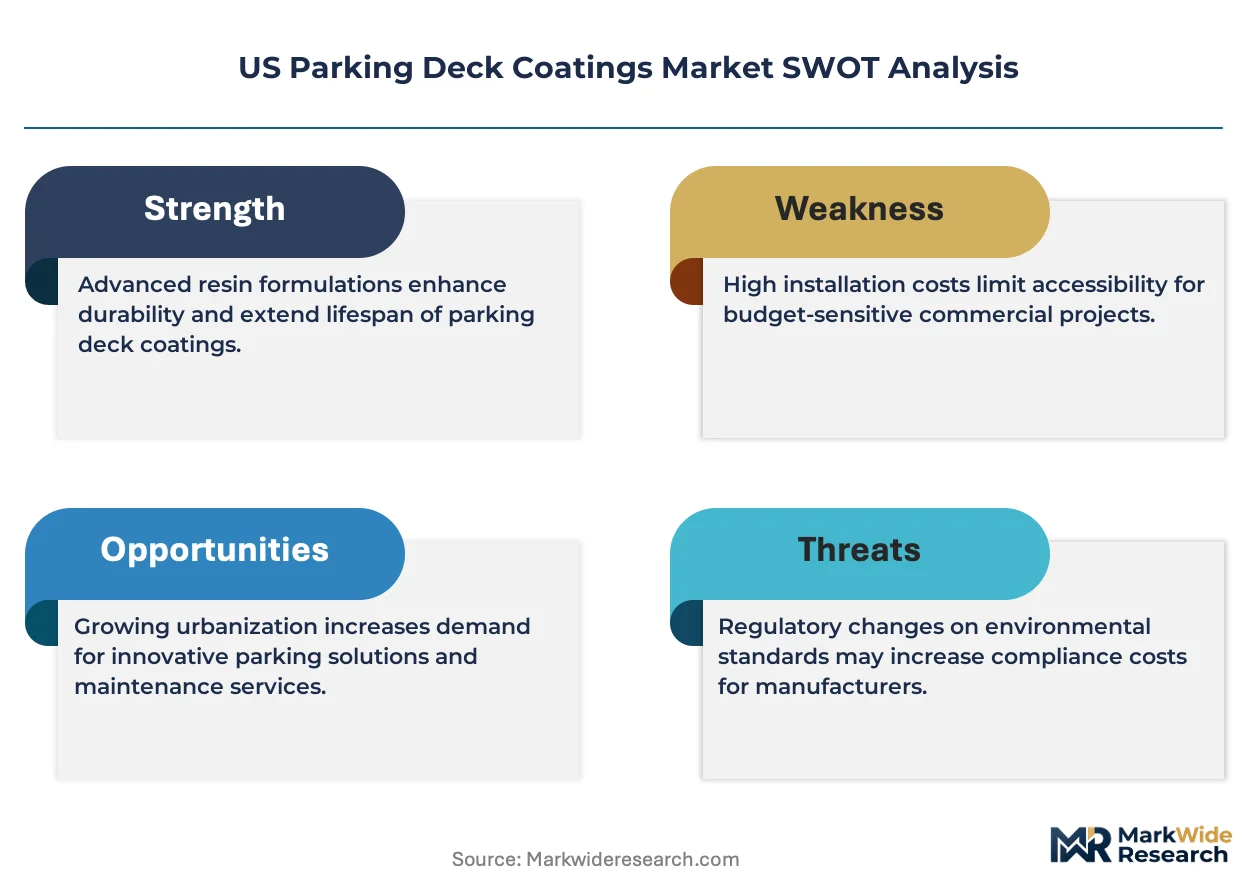
Stricter EPA VOC limits under 40 CFR Part 59 are forcing solvent-borne coating manufacturers to reformulate product lines toward waterborne and high-solids alternatives, compressing margins while accelerating R&D cycles across the supply base.
Growth Catalysts
- Coastal corrosion cycles:Florida, California, and Texas parking structures face accelerated concrete degradation from chloride ingress, shortening recoating intervals and expanding refurbishment demand pools.
- LEED v4.1 adoption:State-level green building standards in California and New York mandate low-emitting materials, steering specification toward qualifying coating systems in commercial new-build projects.
- Methyl methacrylate (MMA) systems:Rapid-cure technology enables parking deck return-to-service within hours, capturing premium segments where downtime costs exceed material premiums.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations compress coating manufacturer margins and destabilize project bidding accuracy.
- Contractor consolidation:Regional applicator networks in the Midwest and Northeast concentrate among fewer certified installers, creating capacity bottlenecks during peak refurbishment seasons.
- Solvent-borne phase-out friction:EPA 40 CFR Part 59 compliance timelines force inventory write-downs and reformulation costs that smaller manufacturers cannot absorb.
Strategic Opportunities
- Institutional parking expansion:Federal Buy America provisions for infrastructure projects create specification windows for domestic coating manufacturers serving university and hospital systems.
- Polyaspartic-epoxy hybrid systems:Converging chemistries balance rapid cure with cost efficiency, opening mid-market commercial segments previously locked into pure epoxy specifications.
- Direct manufacturer procurement:National account consolidation bypasses distributor markups, enabling coating suppliers to capture margin and specification control simultaneously.
Industry Challenges
- Skilled applicator shortage:Surface preparation and coating installation certification programs lag demand growth, extending project timelines in Sun Belt metros.
- Multi-layer system compatibility:Integrating new high-solids primers with legacy concrete substrates requires substrate testing protocols that delay project starts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Parking Deck Coatings Market |
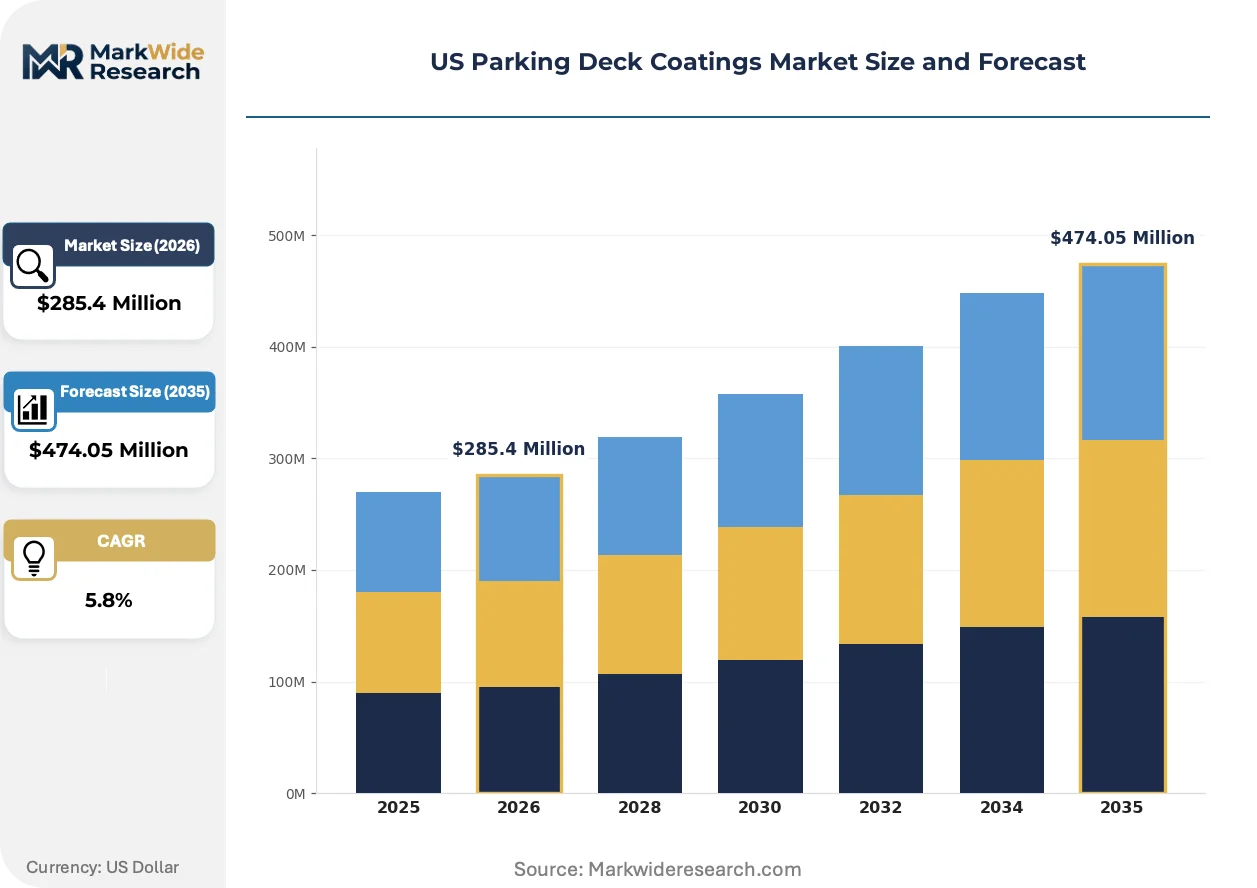
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyaspartic Application: Residential Garages, Commercial Parking Structures, Institutional Parking, Industrial Facilities Installation Method: Roll-On, Spray, Trowel, Injection End User: Property Owners, Contractors, Facility Managers, Architects |
| Companies Covered | Dur-A-Flex, Inc., PPG Industries, Inc., Tennant Coatings, The Sherwin-Williams Company, Stonhard, Inc., LATICRETE International, Inc., Tremco Incorporated, MAPEI S.p.A., Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Parking Deck Coatings Market Strategic Shifts & Innovations
Formulation chemistry and procurement architecture are undergoing parallel transformation as regulatory pressure and buyer consolidation reshape competitive advantage in protective coatings for concrete infrastructure.
Polyaspartic aliphatic polyurethane technology delivers UV stability and rapid cure profiles that epoxy systems cannot match. Commercial parking operators in high-traffic urban cores are specifying these systems for topcoat layers despite 40-60% material cost premiums. This performance tier is rendering obsolete the two-coat epoxy specifications that dominated 2010s refurbishment protocols.
EPA enforcement of 40 CFR Part 59 Subpart D is tightening VOC content thresholds for architectural coatings used in federal and state-funded parking structures. Manufacturers must submit reformulated product lines for requalification under amended test methods. Waterborne epoxy and high-solids polyurethane categories face accelerated specification adoption in California Air Resources Board jurisdictions and Northeast state implementation plans.
Facility managers at healthcare and university campuses are consolidating coating procurement through single-source national agreements rather than project-by-project bidding. This buyer concentration shifts volume toward manufacturers with specification engineering staff and warranty underwriting capacity. The procurement model is most visible in Texas and Florida institutional markets where multi-campus systems coordinate capital maintenance schedules.
US Parking Deck Coatings Market Segmentation
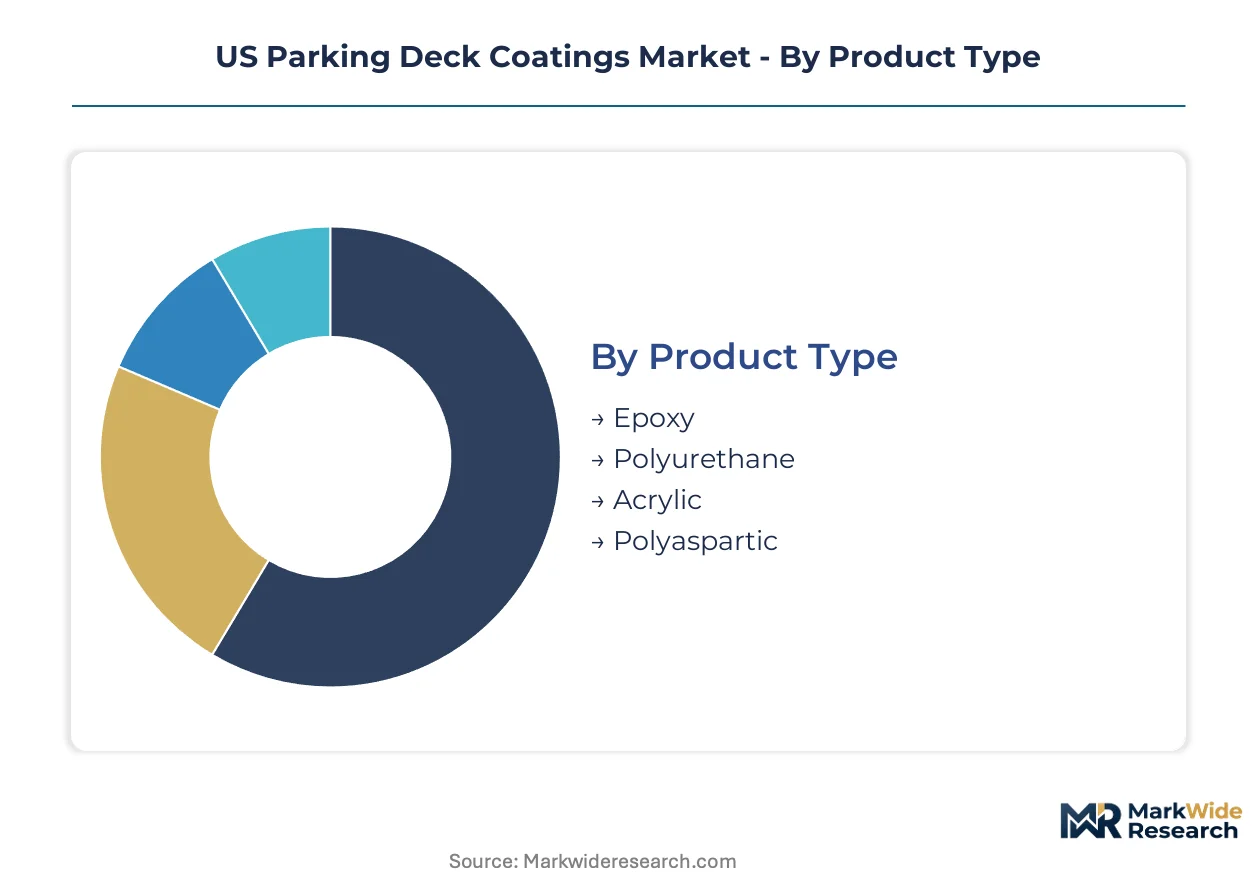
Parking deck coatings segment across resin chemistry, installation scale, application technique, and procurement authority. Each dimension shapes specification pathways, margin structures, and contractor certification requirements in distinct ways.
Product Type:
Mature epoxy formulations dominate refurbishment economics while emerging polyaspartic systems capture premium new-build specifications.
- Epoxy:Two-part thermosetting systems deliver 10-60 mils dry film thickness with established contractor familiarity and lowest installed cost per square foot. Demand concentrates in Sun Belt commercial refurbishment where California, Texas, and Florida building owners prioritize budget adherence over rapid return-to-service.
- Polyaspartic:Aliphatic polyurethane technology cures within hours versus epoxy's multi-day downtime, commanding 40-60% material premiums. Specifications cluster in high-traffic urban cores where parking revenue loss during closure exceeds coating cost differentials.
- Polyurethane:UV-stable aromatic and aliphatic variants serve exposed topcoat layers on multi-level structures facing direct weathering.
- Acrylic:Waterborne formulations address low-VOC compliance thresholds in EPA 40 CFR Part 59 jurisdictions with limited durability requirements.
Epoxy handles the majority of throughput; polyaspartic is the fastest mover on share.
Application:
Volume concentrates in commercial structures while margin accrues to institutional segments with extended warranty demands.
- Commercial Parking Structures:Multi-level garages in urban cores generate the deepest refurbishment pools as deferred maintenance from the 2000s construction boom comes due. Texas and Florida coastal markets face accelerated chloride-induced degradation, shortening recoating cycles.
- Institutional Parking:University and hospital systems under federal Buy America provisions specify domestic-manufactured systems with 10-year performance warranties. Procurement runs through national accounts rather than project bidding.
- Residential Garages:Single-family and multi-family private parking represents a price-sensitive segment with minimal specification engineering.
- Industrial Facilities:Manufacturing and warehouse loading docks require chemical-resistant formulations beyond standard parking deck specifications.
Commercial structures absorb the greatest volume; institutional parking climbs the fastest as federal infrastructure spending expands.
Installation Method:
Contractor capability and project scale determine technique selection across the application spectrum.
- Roll-On:Squeegee and roller application dominates small-to-mid commercial projects with straightforward access and minimal surface complexity.
- Spray:Airless and plural-component spray systems accelerate coverage on large horizontal decks, requiring certified applicator networks that concentrate in Sun Belt metros.
- Trowel:High-build mortar systems address spalled concrete substrates with 1/4-inch to 1/2-inch repair thickness before membrane installation.
- Injection:Crack injection methods precede coating application on structures with active concrete deterioration requiring structural stabilization.
Roll-on methods carry the bulk of project count; spray application is expanding most quickly as contractor fleets upgrade equipment.
End User:
Procurement authority has shifted from decentralized project bidding toward consolidated national agreements.
- Facility Managers:Healthcare and university campus operators now coordinate multi-site coating schedules through single-source manufacturer contracts, capturing volume discounts and warranty alignment.
- Contractors:Certified applicator networks in California and Florida influence specification through established relationships with coating distributors.
- Property Owners:Commercial real estate investment trusts retain direct procurement authority on major refurbishment decisions.
- Architects:Specification engineers on new-build projects increasingly mandate polyaspartic topcoats in LEED v4.1-registered developments.
Facility managers control the largest consolidated spend; contractor influence is gaining share fastest as skilled applicator scarcity tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 10 corridor from Houston to Jacksonville anchors North American parking deck refurbishment demand, with coastal chloride exposure accelerating coating replacement cycles across the Sun Belt's aging concrete infrastructure.
California
Los Angeles and San Francisco Bay Area multi-level garages drive specification volume for low-VOC systems under CARB SCM 2007 standards. EPA 40 CFR Part 59 enforcement compels manufacturers to reformulate waterborne epoxies for state-funded transit-oriented development projects. San Diego's institutional campus clusters coordinate coating procurement through consolidated facility management contracts.
Texas
Houston's petrochemical corridor and Dallas-Fort Worth's healthcare campus expansions generate institutional parking demand with extended warranty requirements. State implementation plans under the Clean Air Act filter eligible coating systems for federally funded infrastructure. Austin's university system multi-site maintenance schedules concentrate procurement authority through national manufacturer agreements.
Florida
Miami and Tampa coastal parking structures face compressed recoating intervals from salt-laden air and storm surge exposure. Florida Department of Environmental Protection air quality rules align with EPA VOC thresholds for commercial refurbishment projects. Orlando's hospitality and convention center parking complexes prioritize rapid-cure systems to minimize revenue disruption during peak tourist seasons.
New York Metro
Manhattan and Brooklyn high-density commercial garages drive demand for durable topcoat systems resisting freeze-thaw cycling and de-icing chemical exposure. New York State Department of Environmental Conservation regulations enforce low-emitting material standards on state-funded parking structures. The Port Authority's multi-facility capital programs consolidate coating procurement across regional transportation hubs.
Illinois/Michigan/Ohio
Chicago's institutional healthcare and university parking systems specify high-performance membrane systems under extended performance warranties. Midwest state environmental agencies adopt EPA 40 CFR Part 59 compliance frameworks for commercial refurbishment. Detroit's automotive corridor industrial parking facilities require chemical-resistant formulations beyond standard commercial specifications.
US Parking Deck Coatings Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in resin and additive supply. The US parking deck coatings sector consolidates around manufacturers with specification engineering capacity and warranty underwriting infrastructure. Three archetypes dominate: multinational coating conglomerates with architectural distribution networks, specialty flooring system providers with certified applicator programs, and construction chemical specialists with methyl methacrylate rapid-cure expertise. Competitive moves concentrate on direct national account procurement bypassing distributor markups, and polyaspartic-epoxy hybrid formulation development capturing mid-market commercial segments.
Among the multinational coating conglomerates, PPG Industries, Inc. and The Sherwin-Williams Company occupy positions defined by distribution scale and contractor loyalty infrastructure. Sika AG represents the construction chemical specialist archetype with rapid-cure system capabilities. These three exemplify the competitive tension between specification control through engineering relationships and volume capture through distribution density.
| Leading Market Players |
|---|
| Dur-A-Flex, Inc. |
| PPG Industries, Inc. |
| Tennant Coatings |
| The Sherwin-Williams Company |
| Stonhard, Inc. |
| LATICRETE International, Inc. |
| Tremco Incorporated |
| MAPEI S.p.A. |
| Sika AG |
| Others |
Cost & Logistics Intelligence
Overcapacity in epoxy resin production across Gulf Coast petrochemical corridors compresses coating manufacturer margins while accelerating price competition for standard refurbishment contracts. This utilization dynamic forces suppliers to differentiate through rapid-cure methyl methacrylate systems and high-solids formulations that command material premiums in specification-driven segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates rapid-cure polyaspartic systems from commodity epoxy refurbishments and basic acrylic sealers. Price differentiation hinges on certification grade under EPA 40 CFR Part 59 compliance tiers and volume scale through national account consolidation. Cost compression in standard epoxy tiers is intensifying because petrochemical feedstock volatility destabilizes project bidding accuracy. Commercial real estate investment trusts exhibit highest price sensitivity, while institutional facility managers under federal Buy America provisions prioritize warranty underwriting over material cost.
Supply Chain Analysis
Extended payment terms from national account facility managers are reshaping working capital requirements for coating manufacturers serving multi-campus healthcare and university systems. Raw material sourcing draws from Texas and Louisiana petrochemical corridors for epoxy resins, Ohio and Pennsylvania for specialty amine hardeners, and Germany and Switzerland for methyl methacrylate monomers. Single-source vulnerability concentrates in rapid-cure additive supply from European construction chemical specialists. Distribution runs through manufacturer-direct procurement channels that bypass traditional distributor markups in consolidated institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment through EPA 40 CFR Part 59 requalification requirements creates durable barriers against unqualified competitors.
For Market Incumbents: Entrench specification control by embedding certified applicator training programs within contractor loyalty infrastructure, particularly in Sun Belt metros facing skilled labor shortages. Deepen backward integration into high-solids resin production to defend margin position against petrochemical price volatility. Prioritize polyaspartic-epoxy hybrid R&D to capture mid-market commercial segments previously locked into pure epoxy specifications.
For New Entrants and Emerging Players: The Northeast institutional corridor from Boston to Philadelphia offers underpenetrated white-space for rapid-cure system specialists with LEED v4.1-compliant waterborne formulations. Target healthcare campus facility managers through specification engineering partnerships that bypass established distributor relationships. Enter via regional certified applicator networks that concentrate procurement influence in markets with limited incumbent warranty underwriting capacity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across waterborne formulation sub-segments as equipment standardization reduces batch processing costs. Acquisition targets should display domestic manufacturing footprints aligned with Buy America provisions and established specification engineering staff serving federal infrastructure channels. Monitor methyl methacrylate monomer supply agreements as inflection indicators for rapid-cure system expansion capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captures margin from volatile petrochemical feedstock cycles while securing supply for high-solids formulations. |
| Certified Applicator Network Expansion | Addresses skilled labor scarcity in Sun Belt metros while embedding specification influence through training relationships. |
| Polyaspartic-Epoxy Hybrid Development | Opens mid-market commercial segments previously locked into pure epoxy refurbishment protocols. |
| National Account Direct Procurement | Bypasses distributor markups while capturing consolidated facility management spend in healthcare and university systems. |
| EPA 40 CFR Part 59 Requalification Investment | Entrenches regulatory moat against unqualified competitors while enabling specification in federally funded infrastructure. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, state air quality implementation plans, and construction chemical trade data. Primary interviews engaged coating manufacturer product managers, certified applicator network operators, facility management procurement directors, and architectural specification engineers. Secondary validation drew from SEC 10-K disclosures, California Air Resources Board SCM 2007 compliance databases, and federal Buy America procurement records. Bottom-up project pipeline analysis triangulated against top-down resin consumption estimates.
Forecast inputs considered resin chemistry segmentation, installation scale tiers, application technique adoption curves, and procurement authority concentration patterns across the analysis window. Modeled dimensions spanned product type, application vertical, installation method, and end-user procurement structure. CAGRs derived from regression analysis against historical refurbishment cycle data and regulatory compliance timeline acceleration. Industry-specific inputs included coastal chloride exposure severity indices and LEED v4.1 adoption trajectories in state implementation plans.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by methyl methacrylate specialists or accelerated solvent-borne phase-out timelines would shift outcomes. Macroeconomic deviation in commercial real estate investment, regulatory amendment to VOC thresholds, or breakthrough in rapid-cure alternative chemistries would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
North America Gypsum Board Market
Building & Construction Materials
North America Concrete Conditioner Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Insulating Glass Window Market